
 Europe Wood Activated Carbon Market | 2026-2036
Europe Wood Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wood Activated Carbon Market Intelligence
France is tilting toward expanded steam-activation capacity to serve pharmaceutical and food-grade buyers. Jacobi Carbons Group leverages its vertical integration into coconut-shell precursor networks to secure feedstock stability. Donau Carbon GmbH anchors Central European supply through specialized regeneration services for industrial water clients. Chemviron competes on mercury-removal specifications for coal-fired utility scrubbers.
Europe wood activated carbon denotes a porous carbonaceous material produced by controlled pyrolysis and steam activation of hardwood feedstocks, typically exhibiting surface areas between 800 and 1500 square meters per gram and iodine numbers exceeding 800 milligrams per gram for premium grades. Its primary commercial purpose centers on adsorptive purification across liquid and gas-phase industrial processes. Granular formats dominate municipal water treatment infrastructure due to lower pressure-drop characteristics and regeneration compatibility. Powdered grades command premium positioning in food and beverage decolorization where rapid kinetics outweigh handling complexity. Extruded pellets sustain growth in air purification applications across commercial HVAC systems.
The EU REACH framework and ECHA substance evaluation protocols govern chemical safety documentation for activated carbon imports, while the EU Green Deal's carbon border adjustment mechanism shapes cost structures for non-European suppliers. Germany's Federal Environment Agency enforces drinking-water purity standards that specify maximum total organic carbon leakage thresholds, directly influencing product certification requirements. France's ANSM mandates pharmacopeial-grade activated carbon specifications for pharmaceutical processing applications. Stakeholders must monitor regulatory divergence between national implementation of EU-wide frameworks and sector-specific purity demands across water, food, and pharmaceutical end uses.
Market Dynamics
The EU Green Deal's tightening chemical footprint targets are forcing activated carbon buyers to requalify suppliers against stricter purity benchmarks, compressing procurement cycles and elevating certification costs across European water utilities and pharmaceutical processors.
Growth Catalysts
- REACH substance evaluation protocols:ECHA's expanding candidate list for SVHCs is compelling industrial users to replace synthetic adsorbents with certified wood-based alternatives in solvent recovery systems.
- Steam-activation capacity expansion:French processors around Lyon are installing continuous rotary kilns to serve ANSM-mandated pharmacopeial-grade demand from regional drug manufacturers.
- Mercury removal specifications:Germany's Federal Environment Agency is enforcing stricter scrubber discharge limits for coal-fired utilities, sustaining specification-grade carbon consumption despite plant retirements.
Market Restraints
- Hardwood feedstock scarcity:Baltic birch and beech supply chains face competing demand from engineered wood products, elevating precursor costs for Central European activation facilities.
- Regeneration infrastructure concentration:Thermal reactivation services cluster in Germany's industrial corridor, forcing French and Benelux buyers to absorb cross-border logistics premiums or accept single-use economics.
- Coconut-shell substitution:Jacobi Carbons Group's captive coconut-shell networks in Southeast Asia are displacing wood grades in gold recovery and food decolorization where iodine number premiums justify the switch.
Strategic Opportunities
- Poland's water infrastructure modernization:EU Cohesion Fund allocations for municipal treatment upgrades in Kraków and Wrocław are creating first-mover advantages for suppliers offering bundled carbon-and-regeneration contracts.
- Biogas upgrading applications:Siloxane and H₂S removal from agricultural anaerobic digesters represents an emerging volume channel as France and Italy expand farm-scale methane capture subsidies.
- CE marking convergence with ISO 14021:Environmental product declarations are becoming gatekeeping documents for public procurement, rewarding processors with verified lifecycle data.
Industry Challenges
- Pharmacopeial certification timelines:ANSM and EMA documentation requirements for new carbon sources extend qualification cycles to 18-24 months, freezing supplier rotations.
- Pyrolysis kiln retrofit capex:Continuous activation systems require €4-8 million per line, straining mid-cap processors facing margin compression from energy cost volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wood Activated Carbon Market |
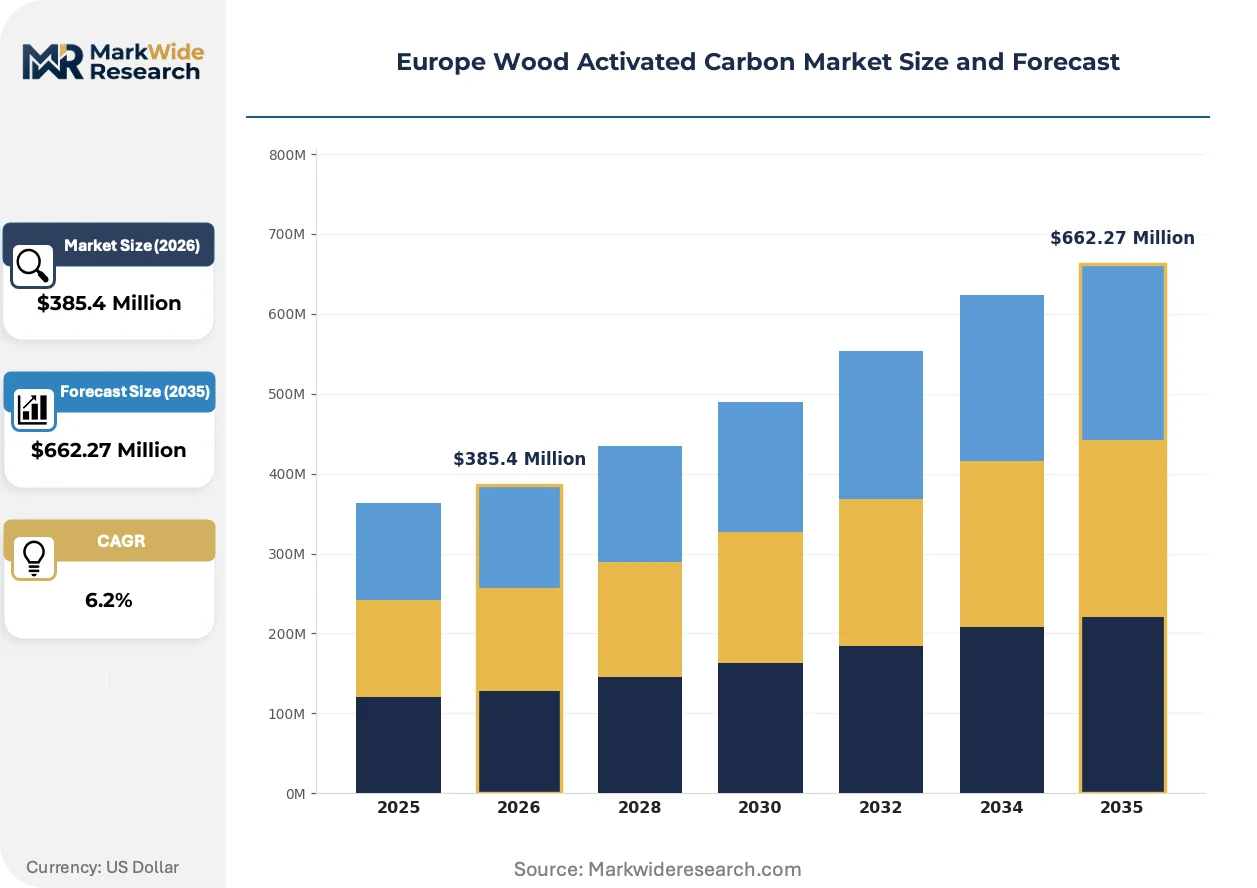
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powdered, Extruded, Pellets Application: Water Treatment, Air Purification, Food and Beverage Processing, Pharmaceuticals End User: Industrial, Residential, Commercial, Environmental Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Jacobi Carbons Group, Donau Carbon GmbH, Calgon Carbon Corporation, Eurocarb Products Limited, Carbon Activated Corporation, Chemviron, Kuraray Europe GmbH, Desotec, Ingevity, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wood Activated Carbon Market Strategic Shifts & Innovations
Activation technology and buyer qualification protocols are converging to favor precision-controlled production with full supply chain traceability, displacing commodity spot-market trading.
Continuous rotary kiln systems with real-time temperature and steam-ratio control are migrating from batch-dominated pharmaceutical-grade production into municipal water treatment supply. German utilities in the Rhine-Ruhr corridor are specifying these systems for replacement carbon to minimize lot-to-lot performance variance. The technology is migrating from premium niche applications into volume infrastructure contracts, compressing margins for batch-activated commodity suppliers.
REACH authorization requirements for polycyclic aromatic hydrocarbon content are tightening maximum permissible limits in food-contact and potable-water grades. EFSA's 2023 updated guidance on carbonaceous materials in food processing is forcing importers to submit extended migration testing data. French and Italian beverage processors are responding by consolidating supplier bases to three qualified partners with in-house analytical capabilities.
Specification-driven procurement is consolidating buyer decision authority from plant-level engineers to centralized technical procurement functions with sustainability mandates. Industrial water treatment contracts in Belgium and the Netherlands now bundle carbon supply with guaranteed regeneration cycles and spent-carbon liability transfer. This pattern is most visible in Benelux chemical manufacturing clusters where ETS compliance costs have elevated total-cost-of-ownership analytics over unit pricing.
Europe Wood Activated Carbon Market Segmentation
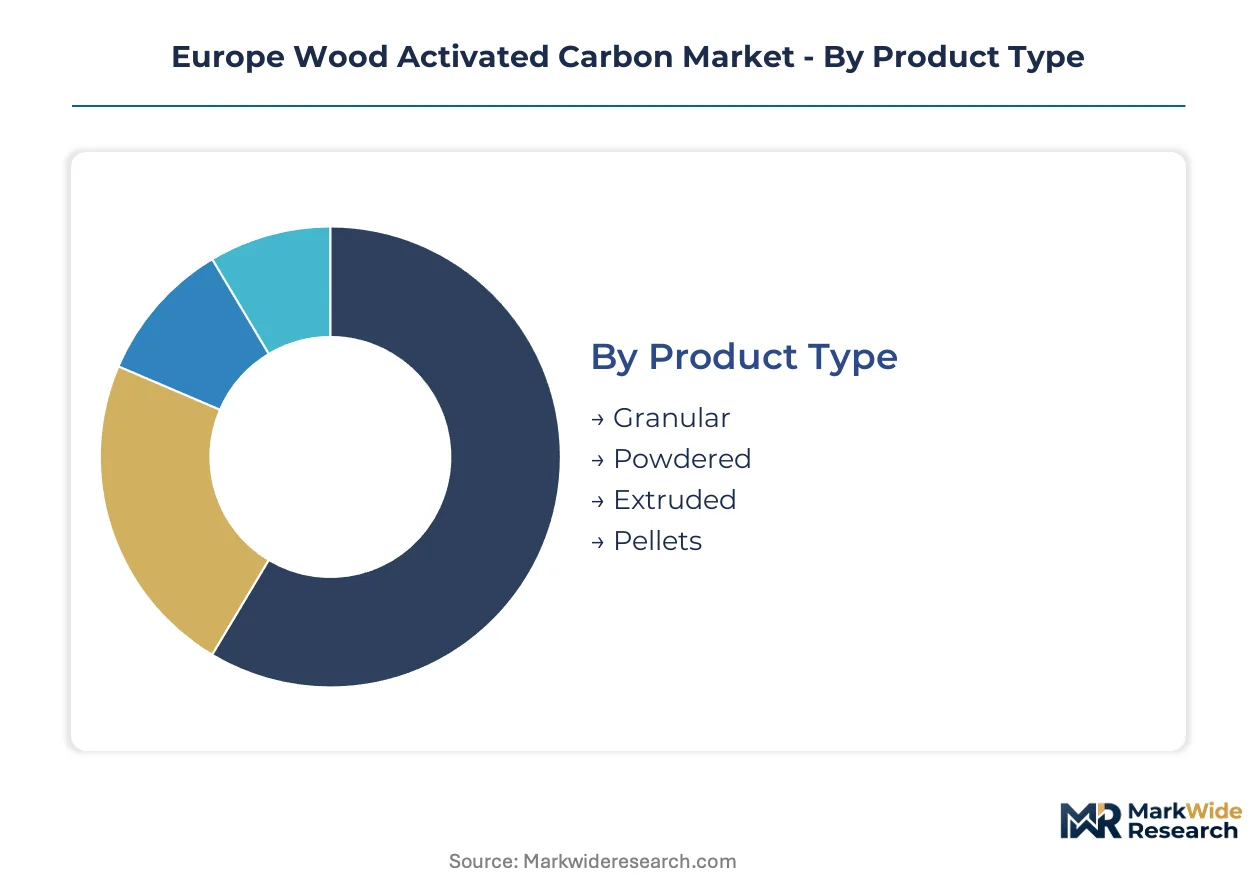
Wood activated carbon segments diverge sharply by technical specification and buyer procurement economics. Product format dictates regeneration feasibility and pressure-drop performance, while application segments map directly onto regulatory compliance burdens.
Product Type:
Mature formats dominate infrastructure replacement cycles; emerging formats target precision air treatment specifications.
- Granular:Irregular particles sized 0.2-5mm with macropore structures optimized for liquid-phase adsorption and thermal reactivation. German municipal utilities in the Rhine-Ruhr corridor specify granular grades for carbon contactors due to established regeneration protocols under Federal Environment Agency drinking-water standards.
- Powdered:Finely milled particles below 0.18mm delivering rapid adsorption kinetics for batch processing. French sugar refineries around Lyon and pharmaceutical processors in Strasbourg drive specification-grade demand where ANSM pharmacopeial purity mandates require rapid decolorization with minimal residence time.
- Extruded:Cylindrical pellets with controlled diameter and crush strength for fixed-bed gas-phase applications. Belgian HVAC contractors specify extruded formats for commercial building air handling units.
- Pellets:Spherical or cylindrical forms with uniform sizing for low-pressure-drop systems. Italian biogas upgrading facilities use pelletized carbon for siloxane removal from agricultural digesters.
Granular handles the majority of throughput; extruded is gaining share fastest on air purification specifications.
Application:
Regulatory intensity varies dramatically across end-uses, with potable water and pharmaceuticals imposing the steepest certification barriers.
- Water Treatment:Municipal and industrial liquid-phase purification requiring compliance with EU Drinking Water Directive and national TOC leakage thresholds. Poland's Cohesion Fund infrastructure modernization in Kraków and Wrocław is expanding granular carbon procurement for surface water treatment plants.
- Air Purification:Gas-phase contaminant removal across commercial HVAC, industrial scrubbers, and biogas upgrading. Germany's tightened mercury discharge limits for coal-fired utilities sustain specification-grade consumption despite plant retirement schedules.
- Food and Beverage Processing:Decolorization, deodorization, and contaminant removal in sugar refining, edible oil purification, and alcoholic beverage filtration. EFSA's updated migration testing requirements are consolidating French and Italian processor supplier bases to qualified partners with in-house analytical capabilities.
- Pharmaceuticals:Pharmacopeial-grade adsorption for active pharmaceutical ingredient purification and toxin removal. ANSM documentation timelines extending 18-24 months freeze supplier rotations and protect incumbent positions.
Water treatment absorbs the largest volume commitments; pharmaceuticals commands the steepest premium tier on certification scarcity.
End User:
Procurement scale and technical sophistication separate industrial buyers from fragmented residential and commercial segments.
- Industrial:Large-scale manufacturing, chemical processing, and utility operations with centralized technical procurement functions. Benelux chemical clusters now bundle carbon supply with guaranteed regeneration cycles and spent-carbon liability transfer under ETS compliance cost pressure.
- Environmental:Remediation contractors and waste management operators handling soil vapor extraction and groundwater treatment. German brownfield redevelopment projects in former industrial zones drive periodic demand spikes.
- Commercial:Office buildings, hospitality, and retail requiring HVAC-integrated air quality management. French commercial real estate ESG mandates are accelerating specification-grade adoption.
- Residential:Point-of-use water filters and air purifiers sold through retail channels. Online retail penetration is expanding access but compressing margin structures.
Industrial accounts for the dominant procurement volume; environmental is expanding most quickly on remediation liability transfers.
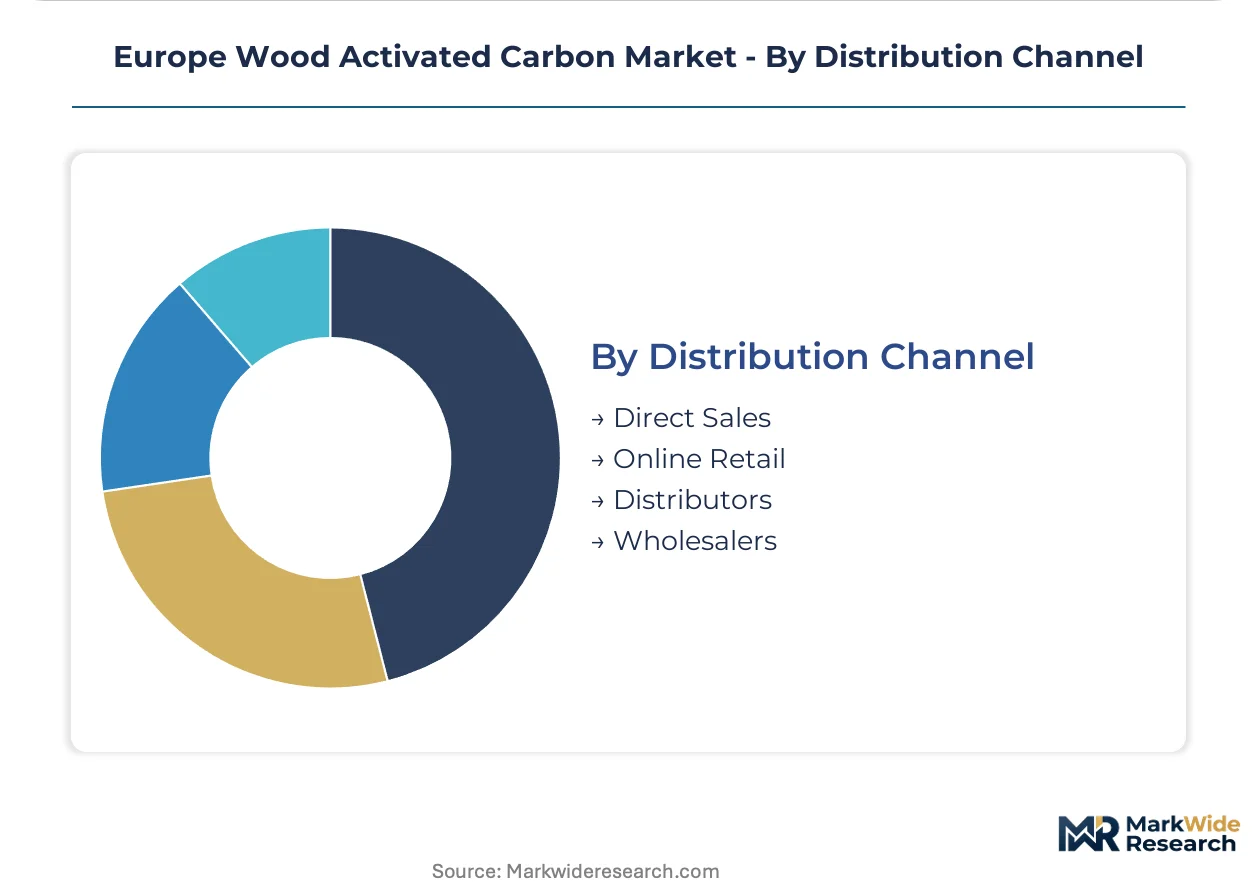
Distribution Channel:
Channel selection tracks buyer scale, technical service requirements, and geographic proximity to regeneration infrastructure.
- Direct Sales:Manufacturer-to-buyer relationships for large-volume industrial accounts requiring technical specification support. German utilities negotiate direct contracts with activation facilities for carbon-and-regeneration bundles.
- Distributors:Regional stocking intermediaries providing logistics and credit terms to mid-scale processors. French pharmaceutical manufacturers rely on specialized chemical distributors for ANSM-compliant documentation chains.
- Wholesalers:Bulk handlers serving smaller industrial accounts and regional water utilities with standardized grades. Baltic states access Central European supply through Polish wholesale networks.
- Online Retail:E-commerce platforms for residential and small commercial point-of-use systems. Channel growth is concentrated in standardized replacement filter cartridges.
Direct sales capture the highest-value contracts; distributors maintain the broadest geographic coverage footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central European activated carbon logistics, connecting Bavarian activation facilities to North Sea ports and Danube industrial zones.
Germany
Rhine-Ruhr municipal utilities drive granular carbon replacement cycles for surface water treatment plants. The Federal Environment Agency enforces drinking-water TOC leakage thresholds that demand certified regeneration protocols. Industrial water clusters around Leverkusen and Ludwigshafen bundle carbon supply with spent-carbon liability transfer under ETS compliance pressure.
France
Pharmaceutical manufacturing corridors around Lyon and Strasbourg concentrate ANSM-mandated pharmacopeial-grade demand. The EU Green Deal's chemical footprint targets tighten purity requirements for activated carbon imports serving food and drug processors. Steam-activation capacity expansion in the Auvergne-Rhône-Alpes region targets regional drug manufacturer procurement.
Poland
EU Cohesion Fund allocations for municipal treatment upgrades in Kraków and Wrocław expand granular carbon procurement for surface water infrastructure. National drinking-water standards align with EU Drinking Water Directive implementation timelines. Silesian industrial zones create bundled carbon-and-regeneration contract opportunities for first-mover suppliers.
Belgium
Benelux chemical manufacturing clusters centralize technical procurement functions with sustainability mandates. ETS compliance costs elevate total-cost-of-ownership analytics over unit pricing in carbon procurement decisions. Antwerp port logistics anchor cross-border supply to French and Dutch industrial water treatment facilities.
Italy
Farm-scale biogas upgrading subsidies expand pelletized carbon demand for siloxane removal from agricultural anaerobic digesters. EFSA migration testing requirements consolidate beverage processor supplier bases to qualified partners. Northern industrial zones around Milan maintain pharmaceutical-grade consumption alongside emerging environmental remediation applications.
Europe Wood Activated Carbon Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The Europe wood activated carbon market structures around three activation technology tiers: batch-activated commodity suppliers, continuous kiln specialists, and integrated regeneration service providers. Competitive moves concentrate on captive feedstock securing through precursor network control and thermal reactivation capacity expansion near industrial demand clusters.
Among vertically integrated specialists, Jacobi Carbons Group exemplifies upstream precursor control through coconut-shell network positioning. Donau Carbon GmbH anchors Central European supply architecture through specialized regeneration services. Chemviron occupies a position on mercury-removal specification competition for utility scrubber applications. These three represent distinct strategic archetypes: feedstock-integrated global supplier, regional regeneration-anchored service provider, and specification-grade application specialist.
| Leading Market Players |
|---|
| Jacobi Carbons Group |
| Donau Carbon GmbH |
| Calgon Carbon Corporation |
| Eurocarb Products Limited |
| Carbon Activated Corporation |
| Chemviron |
| Kuraray Europe GmbH |
| Desotec |
| Ingevity |
| Others |
Cost & Logistics Intelligence
Bavarian activation facilities along the Rhine-Main corridor translate kiln capacity scarcity into pricing leverage over Benelux chemical processors seeking bundled carbon-and-regeneration contracts. Their proximity to industrial demand clusters allows premium capture on ANSM-mandated pharmacopeial grades while batch-activated commodity suppliers absorb margin compression.
Pricing Analysis
EU REACH substance evaluation protocols dictate the pricing tier structure across the European wood activated carbon market, separating certified wood-based alternatives for solvent recovery from uncertified commodity grades. Three-tier pricing structure across premium pharmacopeial, standard municipal water, and economy industrial grades reflects ANSM documentation timelines and Federal Environment Agency TOC leakage thresholds. Cost compression in standard municipal tiers is intensifying because continuous rotary kiln operators migrate technology from pharmaceutical niches into volume infrastructure contracts. Small French pharmaceutical processors exhibit the least price sensitivity due to 18-24 month supplier qualification freezes, while Polish municipal utilities negotiating Cohesion Fund projects show acute sensitivity to unit pricing.
Supply Chain Analysis
Tariff exposure between Baltic states and Central European activation facilities dominates supply chain risk calculations for hardwood feedstock procurement. Manufacturing gravity centers on Germany, France, and Poland, with Bavarian kiln networks and Lyon-region steam-activation capacity anchoring regional supply. Feedstock supply draws from Baltic birch and beech precursor networks facing competing demand from engineered wood products. Single-source vulnerability concentrates in thermal reactivation services clustering along Germany's industrial corridor, forcing cross-border logistics premiums on French and Benelux buyers. Distribution runs through direct manufacturer relationships for large-volume German utilities, specialized chemical distributors for French pharmaceutical documentation chains, and Polish wholesale networks serving Baltic state access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
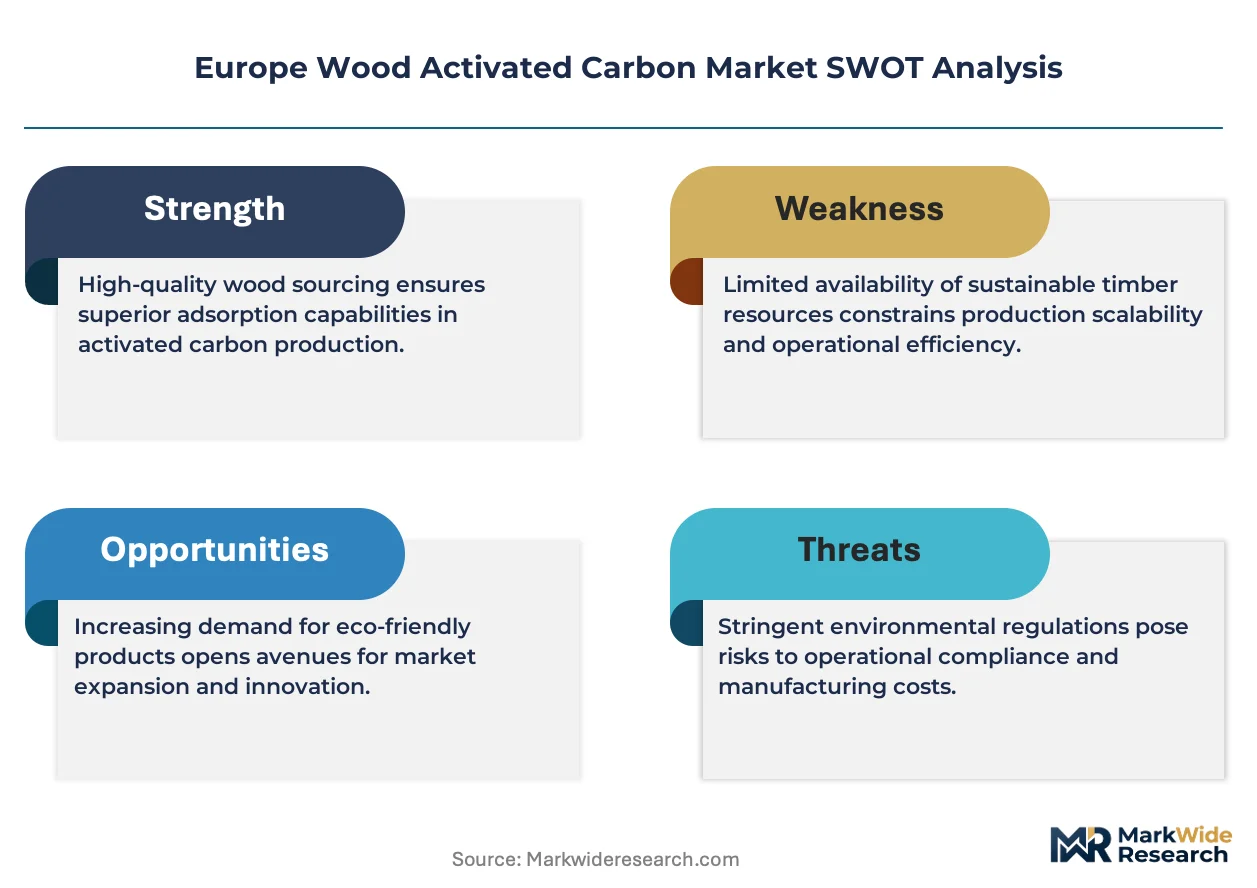
Fragmentation opportunities emerge as EU Green Deal chemical footprint targets force buyer requalification cycles, creating niches for certified suppliers capable of navigating divergent national implementations of REACH and ECHA protocols.
For Market Incumbents: Pre-empt coconut-shell substitution threats by securing captive hardwood precursor networks through long-term Baltic birch supply agreements. Expand continuous rotary kiln capacity in the Auvergne-Rhône-Alpes region to capture ANSM-mandated pharmacopeial demand from Lyon and Strasbourg drug manufacturers. Consolidate regeneration infrastructure advantages through cross-border service partnerships that neutralize logistics premiums currently burdening French buyers. For New Entrants and Emerging Players: Poland's Cohesion Fund municipal treatment upgrades in Kraków and Wrocław represent the most penetrable entry point for first-mover suppliers offering bundled carbon-and-regeneration contracts. Italian farm-scale biogas upgrading subsidies for siloxane removal create a secondary white-space channel with lower certification barriers than pharmaceutical or potable water segments. Lead with CE marking convergence and ISO 14021 environmental product declarations as gatekeeping credentials for public procurement eligibility. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EU Drinking Water Directive implementation timelines and ETS compliance cost pressure institutionalize carbon-and-regeneration bundling economics. Acquisition targets should display vertical integration into precursor networks or captive thermal reactivation capacity near industrial demand clusters. Monitor ECHA SVHC candidate list expansion velocity as the signal indicating substitution-driven volume inflection for certified wood-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Networks | Captive Baltic birch and beech supply secures feedstock stability against engineered wood product competition. |
| Continuous Rotary Kiln Capacity Expansion | Real-time temperature and steam-ratio control captures ANSM pharmacopeial-grade premiums from Lyon drug manufacturers. |
| Regeneration Infrastructure Proximity Investment | Thermal reactivation capacity near Benelux chemical clusters eliminates cross-border logistics premiums and locks in bundling economics. |
| CE Marking and ISO 14021 Certification Program | Environmental product declarations become mandatory gatekeeping documents for EU Cohesion Fund public procurement. |
| Long-term Supply Agreement with Municipal Utilities | Carbon-and-regeneration contracts with Rhine-Ruhr utilities institutionalize replacement cycle revenue under Federal Environment Agency standards. |
Research Approach
A standing panel of plant managers at Bavarian activation facilities, procurement leads at Benelux chemical manufacturers, technical R&D directors at French pharmaceutical processors, and channel partners in Polish wholesale networks provided ongoing calibration throughout the research process. Primary interview insights combined with secondary validation from ECHA substance evaluation databases, EU customs and trade data, Cefic chemical industry reports, and SEC filings from publicly traded carbon processors. Bottom-up volume modeling across kiln capacity installations and top-down demand triangulation from end-use industry consumption patterns ensured analytical consistency.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product format, application regulatory intensity, end-user procurement scale, and geographic proximity to regeneration infrastructure. CAGRs derived from capacity expansion announcements, Cohesion Fund allocation timelines, and EU Drinking Water Directive implementation schedules. Industry-specific forecast inputs incorporated ETS compliance cost trajectories and ANSM documentation cycle durations for new carbon source qualification.
Macroeconomic conditions sit as an overlay; deviation in energy cost volatility, hardwood feedstock availability, or EU carbon border adjustment mechanism implementation would shift the trajectory. Forecasts reflect documented assumptions regarding continuous kiln technology migration and REACH authorization timeline adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Welding Consumables Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Steel Cord Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Cork Material Market