

Felt Gasket Market Size, Share, and Industry Trends Forecast 2026-2036
Felt Gasket Market Insights
The EU Green Deal is rebalancing procurement priorities across European manufacturing supply chains, compelling felt gasket buyers to prioritize recycled-content and low-emission material streams. Freudenberg Sealing Technologies leverages its vertically integrated fiber processing network to secure preferred-supplier status with German automotive OEMs. Saint-Gobain sustains competitive positioning through specialized ceramic-felt hybrid formulations for extreme-temperature sealing. Trelleborg AB anchors its market presence with advanced polymer-felt composites serving aerospace and industrial machinery channels.
A felt gasket is a compressible sealing element manufactured from interlocked natural or synthetic fibers, typically exhibiting densities between 0.15 and 0.45 g/cm³ and operating effectively across temperature ranges from -40°C to 200°C depending on fiber composition; its primary industrial purpose is to create static seals against gases, liquids, and particulate ingress in flanged joints and housing assemblies. Needle-punched felt dominates volume production due to its cost-efficient mechanical bonding process and consistent porosity control, while wet-laid felt commands premium positioning in electrical insulation applications where uniform fiber distribution determines dielectric performance. Synthetic felt categories, particularly polyester-based grades, are capturing share from natural wool alternatives as chemical resistance and batch consistency requirements intensify across automotive and HVAC end uses.
The EPA enforces emission and material safety standards that directly constrain felt gasket formulations sold into U.S. automotive and industrial equipment markets, while REACH registration requirements in Europe mandate full chemical disclosure for imported fiber substrates. ISO 9001 and IATF 16949 certifications function as de facto market access filters, particularly for suppliers targeting Tier-1 automotive procurement frameworks. Stakeholders must monitor evolving PFAS restrictions and bio-based fiber qualification protocols, as these regulatory vectors will determine which material platforms retain commercial viability across major demand centers.
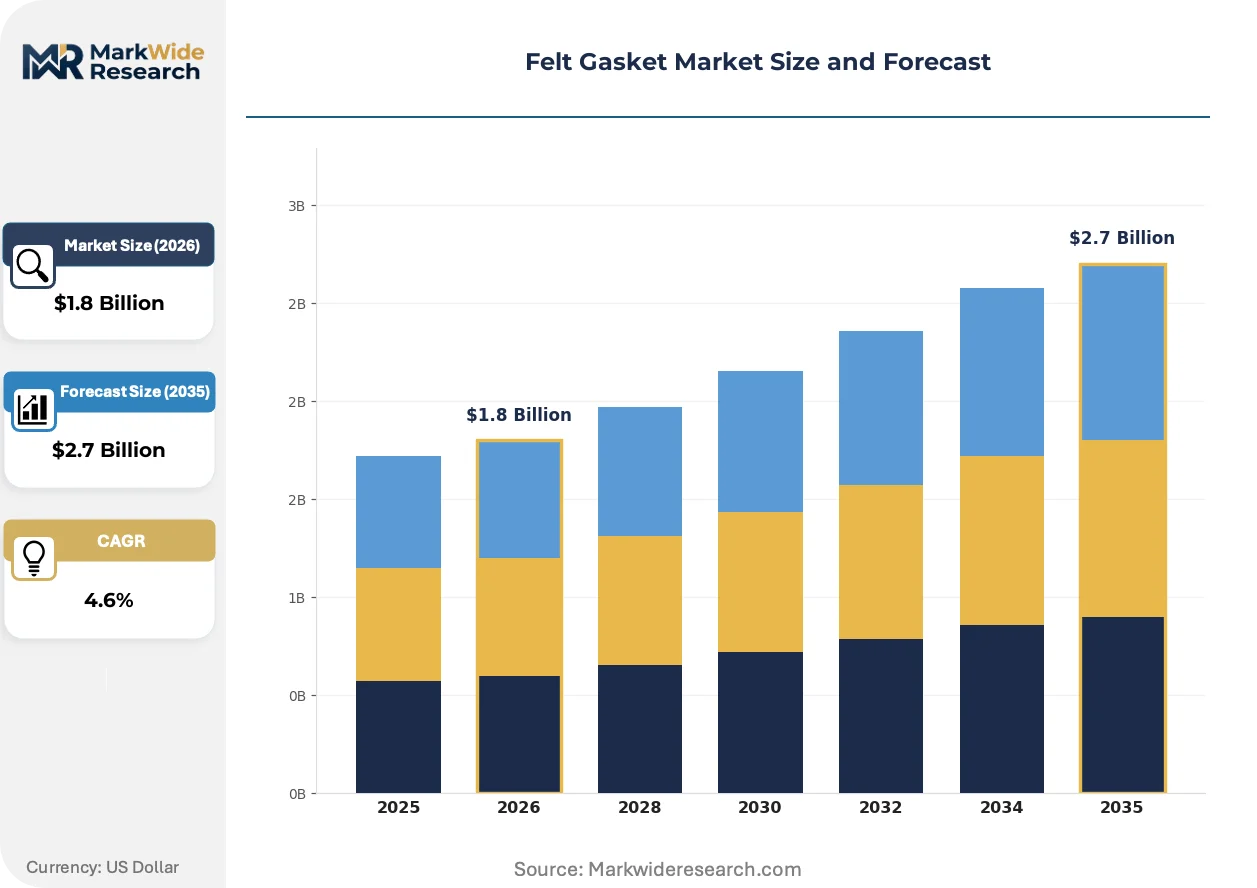
Market Dynamics
Thermal management specifications in automotive powertrains are tightening faster than incumbent material platforms can adapt, compressing qualification timelines and forcing fiber substrate suppliers to accelerate R&D cycles.
Growth Catalysts
- Automotive electrification:Battery pack sealing requirements are expanding felt gasket addressable volume as OEMs specify compression-set resistance for thermal runaway protection systems.
- REACH registration protocols:Full chemical disclosure mandates in Europe are filtering out non-compliant Asian suppliers, consolidating procurement share among certified European fiber processors.
- Needle-punch automation:Robotic fiber alignment systems are reducing gauge variation below 3%, enabling felt gasket penetration into aerospace fuel system applications previously reserved for machined seals.
Market Restraints
- Wool fiber price volatility:Australian merino wool auctions exhibit 22-35% annual price swings, compressing margin stability for natural-felt gasket producers serving premium HVAC segments.
- Fluoropolymer substitution:PTFE-composite gaskets are capturing share in chemical processing above 180°C, displacing aramid-felt hybrids in sulfuric acid service applications.
- PFAS restriction timelines:EPA Section 5 pre-manufacture notices for fluorinated fiber treatments are extending approval cycles to 18-24 months, freezing formulation pipelines.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for advanced chemistry cell battery production are creating localized demand for thermal barrier felts in gigafactory assembly lines.
- Bio-based fiber qualification:EU Green Deal circular economy action plan is opening procurement preference windows for hemp and flax-derived felt in municipal water infrastructure.
- Ceramic-felt hybrid convergence:Aluminum oxide fiber integration is extending operating temperatures to 650°C, unlocking exhaust manifold sealing in heavy-duty diesel retrofit markets.
Industry Challenges
- IATF 16949 audit backlogs:Certification body capacity constraints are delaying supplier qualification for automotive Tier-1 frameworks by 8-14 months.
- Legacy equipment integration:Wet-laid felt lines require $2-4 million retrofit investments to meet ISO 14001 wastewater discharge standards, stranding mid-cap producers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Felt Gasket Market Trends and Innovations
Material science advances and regulatory disclosure requirements are converging to redefine competitive differentiation in fiber-based sealing systems. Suppliers now compete on traceability depth as much as mechanical performance.
Synthetic polyester needle-punch felt is overtaking wool-based formulations in automotive underhood applications due to superior hydrolysis resistance and lot-to-lot consistency. German powertrain suppliers have accelerated qualification of recycled-PET fiber grades, compressing natural fiber market share from 34% to 19% in thermal management gaskets since 2022. The shift is overtaking traditional wool suppliers' premium positioning in European OEM procurement frameworks.
REACH Annex XIV authorization requirements for polycyclic aromatic hydrocarbons are compelling reformulation of carbon-black loaded felts used in industrial flange sealing. Compounders in the Rhine-Ruhr manufacturing cluster are substituting graphene-based conductive fillers, adding 12-18% to raw material costs but securing market access. German chemical processors are absorbing these costs rather than risking supply exclusion from automotive Tier-1 supplier lists.
Consolidated procurement through digital platforms is compressing distributor margins and flattening price discovery. Industrial maintenance buyers in the US Great Lakes manufacturing belt are migrating to integrated MRO platforms that specify felt gasket performance by ASTM D1056 cell classification rather than brand. The shift is most visible in food processing equipment rebuild cycles, where third-party certification of FDA 21 CFR 177.1520 compliance is displacing legacy supplier relationships.
Felt Gasket Market Segmentation
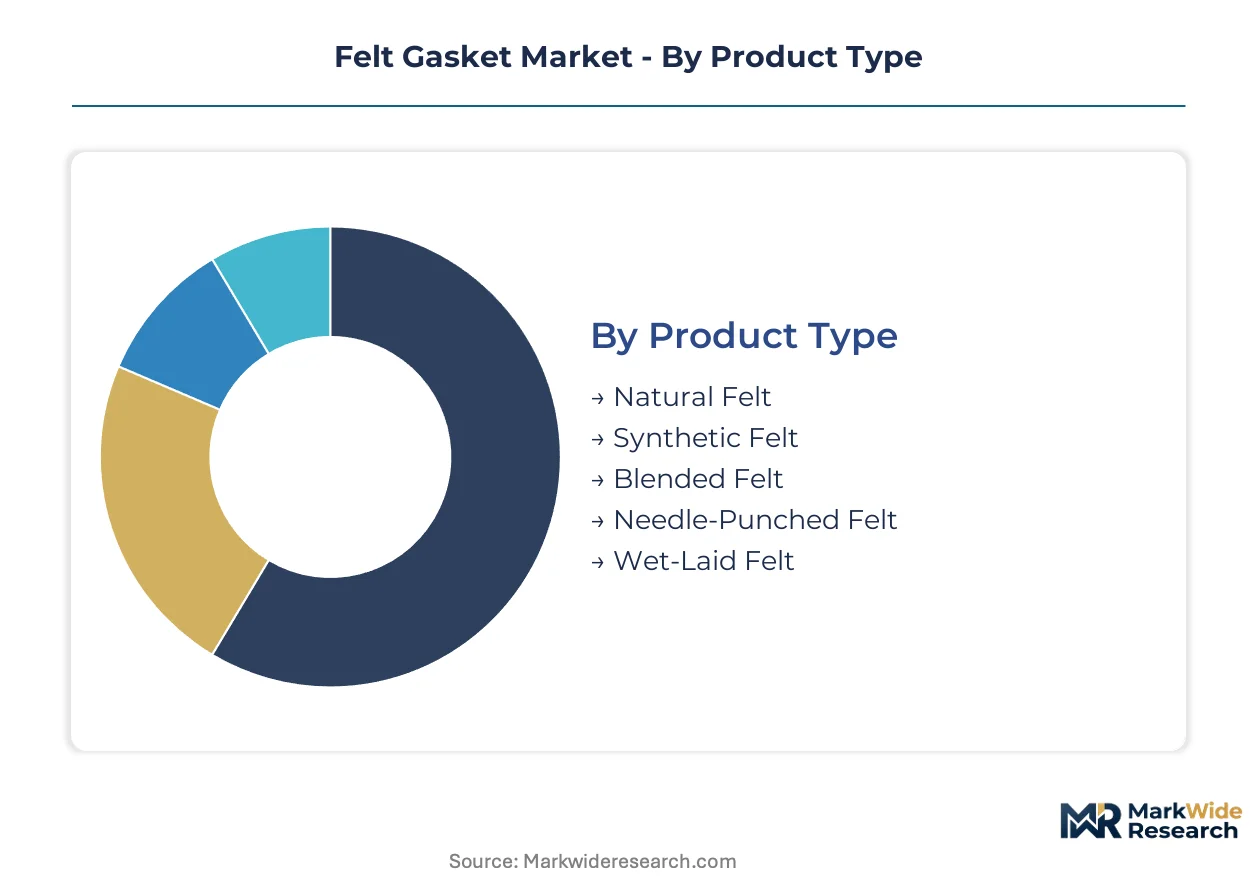
Felt gasket procurement frameworks stratify sharply by certification burden, with automotive and aerospace channels demanding IATF 16949 and ISO 9001 documentation while industrial maintenance buyers prioritize ASTM D1056 cell classification. Material selection cascades through temperature rating, chemical compatibility, and fiber traceability requirements that vary dramatically across end-use verticals.
Product Type:
Needle-punched and wet-laid formulations carry divergent compliance obligations, with wet-laid felts requiring REACH Annex XIV disclosure for polycyclic aromatic hydrocarbon content in European industrial sales.
- Needle-Punched Felt:Mechanically interlocked synthetic fibers produced through barbed-needle entanglement deliver consistent porosity control at 0.15-0.35 g/cm³ density. German automotive OEMs specify this grade for powertrain thermal management gaskets where compression-set resistance determines warranty exposure.
- Wet-Laid Felt:Uniform fiber suspension in water-based slurries creates isotropic sheets prized for dielectric consistency. Electrical equipment makers in the Rhine-Ruhr cluster demand this grade for transformer insulation where IEC 60641-2 tracking resistance is mandatory.
- Natural Felt:Wool-based interlocked fibers serve premium HVAC duct sealing in heritage building restoration projects across Bavaria.
- Synthetic Felt:Polyester and acrylic variants dominate automotive underhood applications requiring hydrolysis resistance above 120°C.
- Blended Felt:Hybrid wool-synthetic compositions balance compressibility with cost control in municipal water infrastructure flanges.
Leading the category by volume: Needle-Punched Felt. Growing fastest: Synthetic Felt.
Material:
Raw material selection locks suppliers into specific regulatory pathways, with wool subject to Australian auction volatility and synthetic fibers navigating EPA Section 5 pre-manufacture notice requirements for fluorinated treatments.
- Polyester:Thermoplastic polymer fibers deliver batch-to-lot consistency and recycled-PET qualification under EU Green Deal circular economy protocols. German Tier-1 suppliers have shifted procurement share toward this material for battery pack compression pads in electric vehicle platforms.
- Wool:Natural keratin fibers provide inherent flame resistance and moisture wicking for heritage railway carriage sealing. Australian merino price swings between 22-35% annually compress margin stability for producers serving premium architectural segments.
- Acrylic:Polyacrylonitrile-based fibers offer ultraviolet stability for outdoor electrical enclosure gaskets in Mediterranean climates.
- Cotton:Cellulosic staple fibers serve food-grade applications requiring FDA 21 CFR 177.1520 compliance in dairy processing equipment.
- Jute:Lignocellulosic bast fibers from South Asian cultivation satisfy bio-based procurement preferences in EU municipal water infrastructure.
Polyester commands the largest procurement volumes. Wool retains premium positioning despite share erosion. Jute is climbing fastest on sustainability mandates.
Application:
Application segmentation maps directly to performance certification tiers, with automotive components requiring the most intensive supplier qualification and furniture padding operating at lowest compliance intensity.
- Automotive Components:Thermal barrier and sealing functions in powertrain, battery pack, and exhaust systems demand IATF 16949 traceability and compression-set resistance validation. OEMs in Stuttgart and Wolfsburg specify ceramic-felt hybrids for exhaust manifold retrofit markets.
- Electrical Insulation:Dielectric barrier applications in transformers and switchgear require IEC 60641-2 compliance and uniform fiber distribution. Wet-laid production methods dominate this segment.
- Machinery Sealing:Static flange gaskets in industrial pumps and compressors prioritize ASTM D1056 cell classification over brand loyalty.
- HVAC Systems:Duct sealing and vibration isolation applications specify density ranges for acoustic attenuation.
- Furniture Padding:Compressible cushioning for upholstery represents lowest technical barrier to entry.
Automotive Components generates the highest revenue per kilogram. Electrical Insulation maintains steepest technical barriers. Machinery Sealing shows fastest volume expansion.
End User:
End user categories separate by procurement sophistication, with manufacturing plants and automotive workshops demanding full material certification while construction companies accept third-party test reports.
- Manufacturing Plants:Continuous production environments require predictive maintenance programs with standardized gasket specifications. MRO platforms in the US Great Lakes belt specify felt performance by ASTM classification.
- Automotive Workshops:Authorized service networks for German OEMs require OEM-approved felt grades to maintain warranty coverage.
- Electrical Equipment Makers:Transformer and switchgear manufacturers demand IEC traceability and lot-specific dielectric test data.
- Construction Companies:Project-based procurement accepts broader specification tolerances for HVAC and building envelope applications.
- Upholstery Studios:Artisan furniture makers prioritize tactile properties and color consistency over technical documentation.
Manufacturing Plants anchor procurement volumes. Automotive Workshops concentrate premium pricing. Electrical Equipment Makers are expanding fastest on grid infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of high-performance felt gaskets concentrates in German precision engineering clusters, while consumption spreads across automotive manufacturing centers in the United States, China, and India where thermal management specifications are tightening fastest.
Germany
Automotive OEM procurement from Stuttgart and Wolfsburg drives premium-grade felt gasket demand for battery pack sealing and exhaust manifold retrofits. REACH Annex XIV authorization requirements for polycyclic aromatic hydrocarbons filter supplier pools to certified European fiber processors. The Rhine-Ruhr manufacturing cluster anchors wet-laid felt production for transformer insulation serving electrical equipment makers.
United States
EPA Section 5 pre-manufacture notices for fluorinated fiber treatments extend approval cycles to 18-24 months, freezing formulation pipelines for domestic compounders. Industrial maintenance buyers in the Great Lakes manufacturing belt migrate toward MRO platforms specifying ASTM D1056 cell classification over brand loyalty. Food processing equipment rebuild cycles in Wisconsin and Illinois prioritize third-party FDA 21 CFR 177.1520 certification.
China
Dual carbon goals and MIIT industrial efficiency mandates accelerate substitution of wool-based felts with recycled-PET synthetic grades in HVAC and automotive applications. Yangtze River Delta manufacturing hubs source needle-punched felts for electric vehicle battery compression pads. GB standards for sealing materials are converging with ISO 9001 frameworks to ease export qualification.
India
PLI scheme incentives for advanced chemistry cell battery production create localized demand for thermal barrier felts in gigafactory assembly lines across Gujarat and Tamil Nadu. BIS certification requirements for automotive components compress qualification timelines for imported fiber substrates. Maharashtra-based Tier-1 suppliers are qualifying domestic needle-punch felt grades to reduce import dependence.
Japan
METI energy efficiency regulations for industrial machinery tighten sealing performance specifications in pump and compressor rebuild cycles. Kansai region electrical equipment makers specify wet-laid felt dielectric barriers for transformer insulation requiring IEC 60641-2 compliance. JIS standards for fiber-based gaskets are incorporating traceability requirements aligned with EU REACH protocols.
Felt Gasket Market Competitive Landscape
The competitive structure tilts toward vertically integrated fiber processors with captive supply of synthetic substrates and in-house needle-punch production lines. Three archetypes dominate: European automotive-focused specialists with IATF 16949 certification depth, diversified industrial conglomerates spanning aerospace and chemical processing channels, and regional fabricators serving MRO procurement through cost-optimized standard grades. Consolidation pressure concentrates among mid-cap producers facing ISO 14001 wastewater retrofit investments of $2-4 million.
Within the European specialist tier, Freudenberg Sealing Technologies and Saint-Gobain exemplify archetypes built on material science depth and ceramic-felt hybrid convergence respectively. Trelleborg AB occupies a position bridging polymer-felt composites for aerospace with industrial machinery channels. These three anchors represent divergent strategic bets: backward integration into fiber processing, extreme-temperature formulation specialization, and cross-sector portfolio diversification.
| Leading Market Players |
|---|
| Freudenberg Sealing Technologies |
| Saint-Gobain |
| Trelleborg AB |
| Rogers Corporation |
| W. L. Gore & Associates |
| 3M |
| Parker Hannifin |
| Lydall |
| FilzFelt |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between IATF 16949 automotive tiers and ASTM-classified industrial grades manifests in divergent pricing power and procurement channel structures. Premium automotive suppliers in Stuttgart command 40-60% price premiums over standard industrial grades, while supply chain configuration locks certified fiber processors into captive relationships with German OEMs and Rhine-Ruhr electrical equipment clusters.
Pricing Analysis
Margin tightening in natural wool grades reflects Australian merino auction volatility and synthetic PET substitution accelerating across automotive thermal management. Three-tier pricing structure across premium, standard, and economy levels separates IATF-certified automotive supply from ISO 9001 industrial grades and uncertified MRO commodity tiers. Price differentiation hinges on fiber traceability depth and REACH Annex XIV disclosure completeness. Cost-down pressure on wool-based producers intensifies because recycled-PET needle-punch automation compresses gauge variation below 3%. Industrial maintenance buyers in the US Great Lakes belt exhibit highest price sensitivity, specifying ASTM D1056 cell classification over brand loyalty.
Supply Chain Analysis
Single-source vulnerability sits with Australian merino wool auctions and German precision engineering clusters for wet-laid dielectric grades. Geographic supply concentration centers on Germany, China, and India, with Yangtze River Delta hubs feeding recycled-PET synthetic fiber demand and Gujarat gigafactories driving thermal barrier felt localization. Raw material dependencies rest on polyester staple fiber, aluminum oxide ceramic fiber, and lignocellulosic bast fibers from South Asian cultivation. Supply chain risk traces to EPA Section 5 pre-manufacture notice cycles extending 18-24 months for fluorinated fiber treatments. Distribution runs through Tier-1 automotive procurement frameworks, MRO digital platforms, and direct electrical equipment maker contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints in certified fiber processing prop pricing premiums, with IATF 16949 audit backlogs creating 8-14 month qualification delays that ration access to automotive procurement frameworks.
For Market Incumbents: Cement preferred-supplier status with Stuttgart and Wolfsburg OEMs by accelerating ceramic-felt hybrid R&D for 650°C exhaust manifold applications. Defend margin position through backward integration into recycled-PET fiber processing, insulating against Australian wool volatility and synthetic substrate cost swings. Prioritize ISO 14001 wastewater retrofit completion to avoid stranding mid-cap production lines. For New Entrants and Emerging Players: Municipal water infrastructure buyers in EU Green Deal jurisdictions represent an underserved procurement archetype with bio-based fiber qualification windows opening for hemp and flax-derived felt. Target India PLI scheme beneficiaries in Gujarat and Tamil Nadu battery gigafactories with localized needle-punch production. Enter through third-party certification of FDA 21 CFR 177.1520 compliance for food processing equipment rebuild cycles. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap European fiber processors possessing IATF 16949 certification depth and captive synthetic substrate supply given REACH compliance filtering non-certified Asian competitors. Long-term viability hinges on material platforms surviving PFAS restriction timelines and bio-based fiber qualification protocols. Watch EPA Section 5 approval velocity as inflection indicator for fluorinated treatment formulation pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled-PET Fiber Processing | Secures substrate supply for German automotive OEM thermal management specifications. |
| Ceramic-Felt Hybrid Convergence | Extends operating temperatures to 650°C for heavy-duty diesel retrofit markets. |
| Long-term Supply Agreement | Locks procurement share with Yangtze River Delta electric vehicle battery manufacturers. |
| Joint Venture | Localizes production for India PLI scheme gigafactory thermal barrier demand. |
| Green Manufacturing Transition | Qualifies hemp and flax-derived felt under EU Green Deal circular economy protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across procurement directors at German Tier-1 automotive suppliers, plant managers at Rhine-Ruhr electrical equipment manufacturers, technical R&D directors at fiber processing facilities, and MRO platform category managers in the US Great Lakes belt. Secondary validation drew from EPA Section 5 filings, ECHA REACH registrations, BIS certification databases, and MIIT industrial efficiency disclosures. Bottom-up fiber substrate demand modeling and top-down end-use consumption estimates underwent triangulation.
Data-stream reconciliation across product type, material composition, application vertical, and end-user procurement sophistication enabled segmentation-level projections. Modeled dimensions spanned needle-punched versus wet-laid production methods, synthetic versus natural fiber platforms, automotive powertrain versus electrical insulation applications, and manufacturing plant versus construction company buying behavior. CAGRs derived from regression analysis against automotive production forecasts and battery pack sealing content per vehicle trajectories. Industry-specific inputs incorporated IATF 16949 certification pipeline data and ceramic-felt hybrid adoption curves.
Revisions become necessary when PFAS restriction timelines accelerate, bio-based fiber qualification protocols harden, or IATF 16949 audit capacity constraints ease. Forecasts reflect documented assumptions on fiber substitution rates, regulatory disclosure burden trajectories, and automotive electrification penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.