
 United States Ceramic Roller Bearings Market | 2026-2036
United States Ceramic Roller Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ceramic Roller Bearings Market Intelligence
Preventive maintenance contracts and performance-based service agreements is shifting how ceramic roller bearings are monetized beyond unit sales. SKF Corporation leverages its North American service network to anchor long-term industrial contracts. The Timken Company sustains R&D intensity in silicon nitride formulations for high-temperature applications. Schaeffler Group USA Inc. competes through geographic dominance in the Midwest automotive supplier ecosystem.
Ceramic roller bearings are precision-engineered antifriction components fabricated from silicon nitride, zirconia, or alumina ceramics, typically operating at temperatures exceeding 500°F with corrosion resistance superior to conventional steel alloys. Their primary purpose centers on extending service life in hostile environments where lubrication degradation and thermal expansion compromise metallic bearing performance. Angular contact configurations command premium positioning in aerospace spindle applications where combined radial and thrust loads predominate. Industrial Machinery represents the deepest installed base, though Medical Devices emerges as the fastest-growing application as surgical robotics and imaging equipment demand non-magnetic, sterilization-compatible rotation interfaces. OEMs capture the largest volume channel, while Aftermarket Providers concentrate margin pools through emergency replacement and retrofit services.
FAA airworthiness directives and NHTSA safety standards shape material certification requirements and product qualification timelines for ceramic bearing suppliers serving regulated transportation sectors. EPA emissions frameworks indirectly stimulate demand by pressuring automotive and industrial customers toward lighter, more efficient rotating machinery. OSHA workplace safety regulations influence maintenance protocol design, extending replacement intervals where ceramic bearings reduce hazardous access frequency. Stakeholders must monitor evolving FAA certification pathways for ceramic components in next-generation electric propulsion systems and weigh capital allocation between in-house ceramic processing capabilities and qualified supplier partnerships.
Market Dynamics
FAA certification pathways for ceramic components in electric propulsion systems are compressing supplier qualification timelines while NHTSA fuel-economy mandates accelerate lightweight drivetrain adoption across Michigan's automotive belt.
Growth Catalysts
- NHTSA Fuel-Economy Mandates:Automakers in Detroit's manufacturing corridor substitute steel bearings with silicon nitride variants to reduce rotating mass and meet Corporate Average Fuel Economy standards.
- Aerospace Thermal Cycling Requirements:Turbine manufacturers specify ceramic roller bearings for engine spindles operating above 500°F where lubricant degradation destroys conventional alloys.
- Silicon Nitride Material Advances:Improved fracture toughness formulations extend bearing life in hostile chemical environments, opening substitution opportunities in chemical processing equipment.
Market Restraints
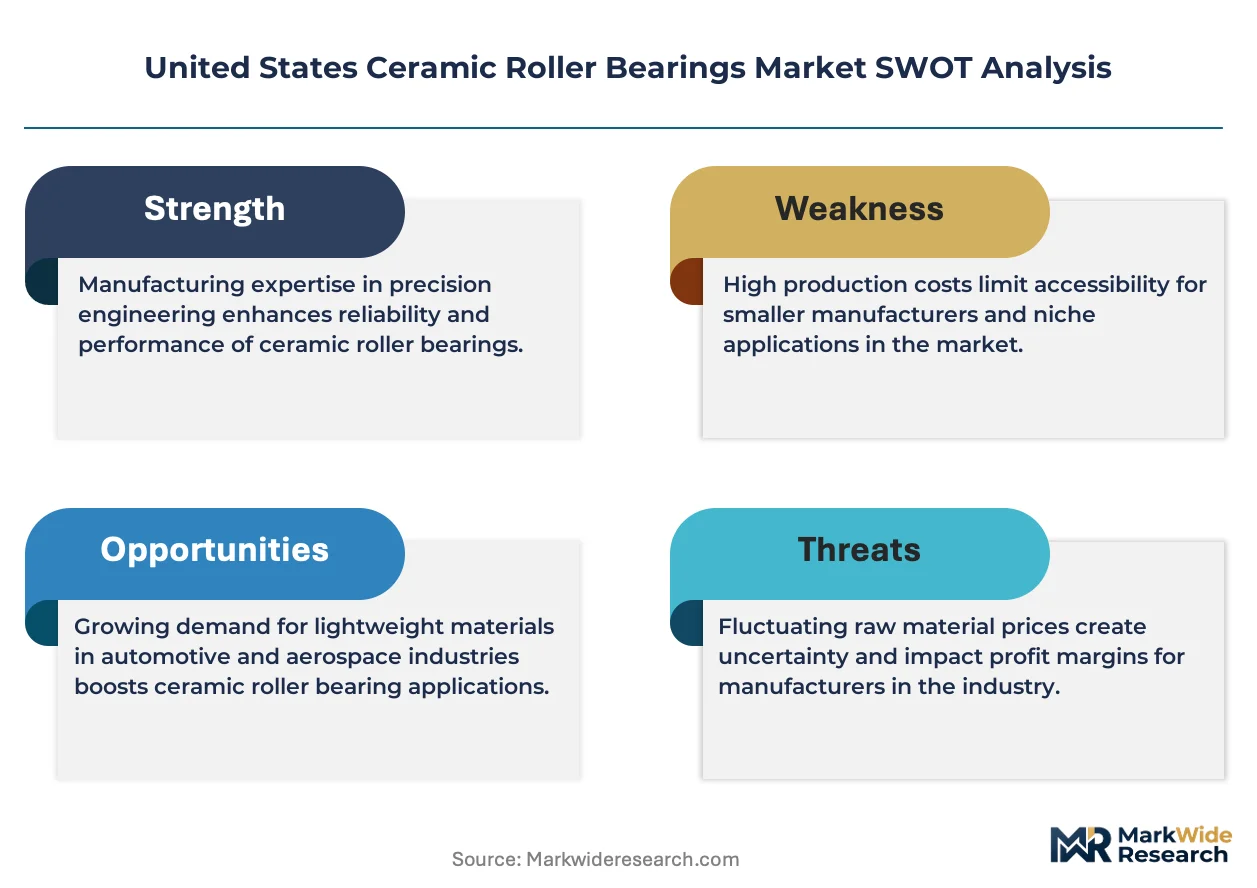
- Raw Material Concentration Risk:High-purity silicon nitride powder production concentrates among a limited supplier base, creating input cost volatility and supply security concerns for domestic fabricators.
- FAA Certification Friction:Extended qualification timelines for ceramic bearing assemblies in commercial aviation applications delay revenue recognition and lock working capital in pre-production inventory.
- Steel Bearing Performance Improvements:Advanced vacuum-degassed steel alloys with ceramic coatings deliver partial ceramic benefits at substantially lower unit costs in moderate-temperature industrial applications.
Strategic Opportunities
- Surgical Robotics Expansion:Non-magnetic ceramic bearings enable MRI-compatible surgical instruments and imaging equipment rotation systems, penetrating medical device OEM supply chains.
- California Precision Manufacturing Corridor:Semiconductor fabrication equipment builders in Silicon Valley demand contamination-free ceramic bearings for vacuum chamber applications.
- Preventive Maintenance Contracting:Performance-based service agreements shift revenue from unit sales to lifetime value capture, embedding suppliers in customer operations through California and Texas industrial clusters.
Industry Challenges
- Ceramic Processing Specialist Shortage:Domestic labor pools lack sufficient expertise in hot isostatic pressing and precision grinding of advanced ceramics, constraining capacity expansion.
- Legacy System Integration Complexity:Retrofitting ceramic bearings into existing steel-bearing housings requires custom adapter designs and tolerance matching, extending sales cycles in aftermarket channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ceramic Roller Bearings Market |
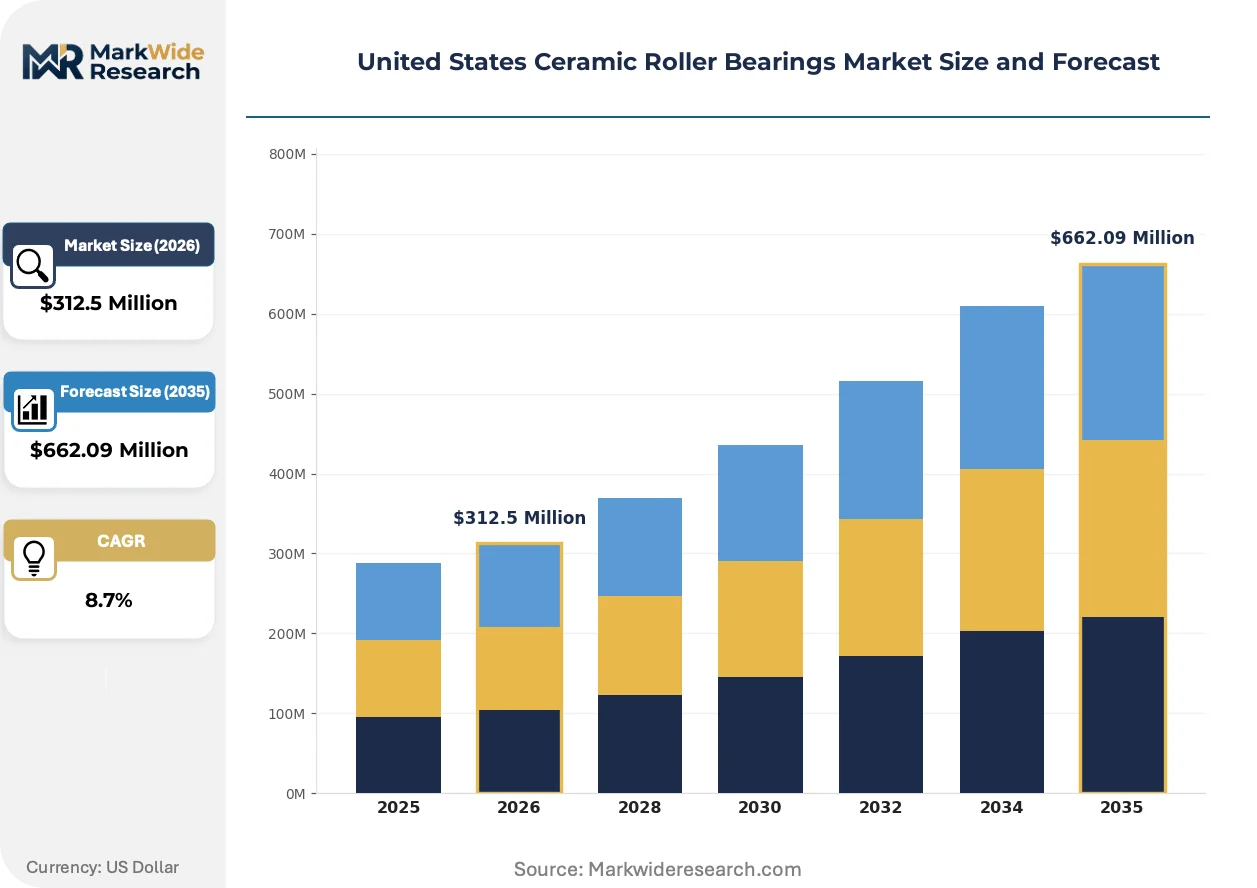
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deep Groove, Angular Contact, Self-Aligning, Thrust Application: Aerospace, Automotive, Industrial Machinery, Medical Devices End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Maintenance Services Technology: CNC Machining, 3D Printing, Automated Assembly, Manual Assembly |
| Companies Covered | SKF Corporation, The Timken Company, Schaeffler Group USA Inc., NSK Global, JTEKT Corporation, RBC Bearings Incorporated, NTN Corporation, CeramicSpeed, Emerson Bearing Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ceramic Roller Bearings Market Strategic Shifts & Innovations
Hybrid ceramic-steel bearing architectures are displacing full-ceramic designs in cost-sensitive industrial applications while regulatory pressure on emissions intensifies material substitution across transportation sectors.
Additive manufacturing of silicon nitride bearing cages is unifying complex geometries previously requiring multi-part assemblies into single printed components. Medical device OEMs in Minnesota and Massachusetts adopt these consolidated cage designs for surgical robotics applications. This unification reduces part count, assembly labor, and tolerance stack-up errors while enabling conformal cooling channels for high-speed spindle thermal management.
EPA emissions frameworks indirectly stimulate ceramic bearing demand by pressuring automotive and industrial customers toward lighter, more efficient rotating machinery. The regulatory consequence cascades through supply chains as Tier-1 suppliers specify ceramic alternatives to achieve weight reduction targets. California's precision manufacturing corridor experiences the most acute compliance pressure, driving fastest substitution rates in semiconductor and aerospace equipment.
Aftermarket service unbundling separates bearing replacement from comprehensive maintenance contracts, creating standalone procurement channels for emergency ceramic bearing retrofits. Industrial machinery operators in Texas and Ohio now source ceramic replacements directly from distributors rather than through captive OEM service networks. This channel shift concentrates margin capture among specialized distributors with metallurgical diagnostic capabilities and rapid ceramic inventory positioning.
United States Ceramic Roller Bearings Market Segmentation
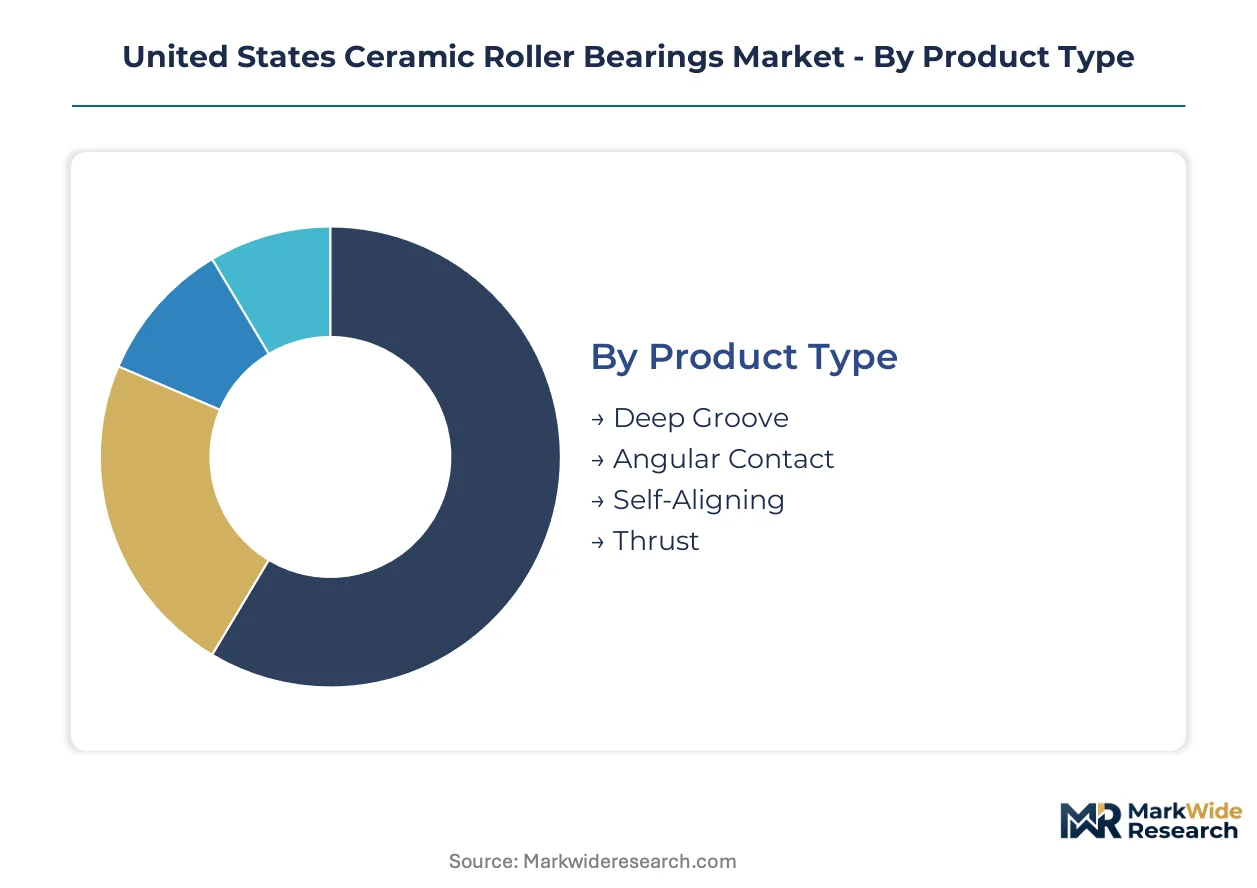
Ceramic roller bearing procurement patterns diverge sharply between integrated system builds and standalone replacement cycles. Understanding where each segment sits on this integration spectrum clarifies margin capture mechanics and channel strategy requirements for suppliers operating across Michigan's automotive belt and California's precision manufacturing corridor.
Product Type:
Integration depth varies dramatically across bearing geometries, with some configurations engineered for embedded turbine assemblies while others serve as drop-in aftermarket replacements.
- Deep Groove:Full ceramic and hybrid variants handle combined radial and axial loads in moderate-speed applications. Demand concentrates in Ohio and Texas industrial machinery retrofits where operators seek extended service intervals without housing modifications.
- Angular Contact:Precision-matched duplex pairs maintain rigidity under combined loading in high-speed spindles. Aerospace turbine manufacturers in Connecticut and Arizona specify these for engine main shaft applications where thermal expansion tolerance exceeds steel capabilities.
- Self-Aligning:Accommodates shaft deflection and mounting misalignment through spherical outer ring geometry. Paper mills in Wisconsin and chemical processors in Louisiana deploy these in contaminated environments where seal degradation is inevitable.
- Thrust:Handles pure axial loads in vertical spindle and screw drive applications. Machine tool builders in Illinois integrate these into precision grinding equipment where rigidity directly determines surface finish quality.
Deep Groove leads volumes today; Angular Contact is gaining share fastest.
Application:
Cost tier stratification separates premium-certified aerospace and medical applications from price-sensitive industrial machinery deployments.
- Aerospace:FAA-certified silicon nitride bearings withstand thermal cycling from ambient to 1200°F in turbine engine spindles. Qualification timelines extend 18-24 months, locking working capital in pre-production inventory for suppliers serving Pratt & Whitney and GE Aviation operations.
- Automotive:NHTSA fuel-economy mandates accelerate lightweight drivetrain adoption across Detroit's manufacturing corridor. Silicon nitride variants reduce rotating mass in electric vehicle reduction gearboxes where efficiency targets tighten annually.
- Industrial Machinery:Represents the deepest installed base across paper processing, chemical handling, and food equipment. Texas and Pennsylvania machinery operators prioritize total cost of ownership over unit price, favoring ceramics where lubrication access is hazardous.
- Medical Devices:Non-magnetic zirconia bearings enable MRI-compatible surgical robotics and imaging equipment rotation systems. Minnesota and Massachusetts OEMs specify these for sterilization-compatible interfaces in minimally invasive surgical platforms.
Industrial Machinery dominates current procurement; Medical Devices shows the steepest expansion trajectory.
End User:
Customer type determines contract structure, with OEMs demanding volume commitments and aftermarket channels capturing emergency replacement premiums.
- OEMs:Original equipment manufacturers specify ceramic bearings during initial system design, embedding suppliers in multi-year platform contracts. Boeing and Tesla procurement teams negotiate qualification exclusivity in exchange for volume guarantees.
- Aftermarket Providers:Emergency replacement and retrofit services command 40-60% unit price premiums over OEM channels. Distributors with metallurgical diagnostic capabilities and rapid ceramic inventory positioning capture concentrated margins in Ohio and California industrial clusters.
- Tier-1 Suppliers:Intermediate integrators like BorgWarner and Dana source ceramic bearings for subassembly incorporation into larger automotive and aerospace systems. These suppliers buffer OEMs from direct ceramic qualification complexity.
- Maintenance Services:Performance-based service agreements shift revenue from unit sales to lifetime value capture. SKF and Timken service networks in Texas and Michigan embed technicians directly in customer facilities.
OEMs anchor current volume; Maintenance Services is expanding most quickly.
Technology:
Manufacturing process maturity separates scalable automated production from craft-dependent manual methods still required for aerospace certification.
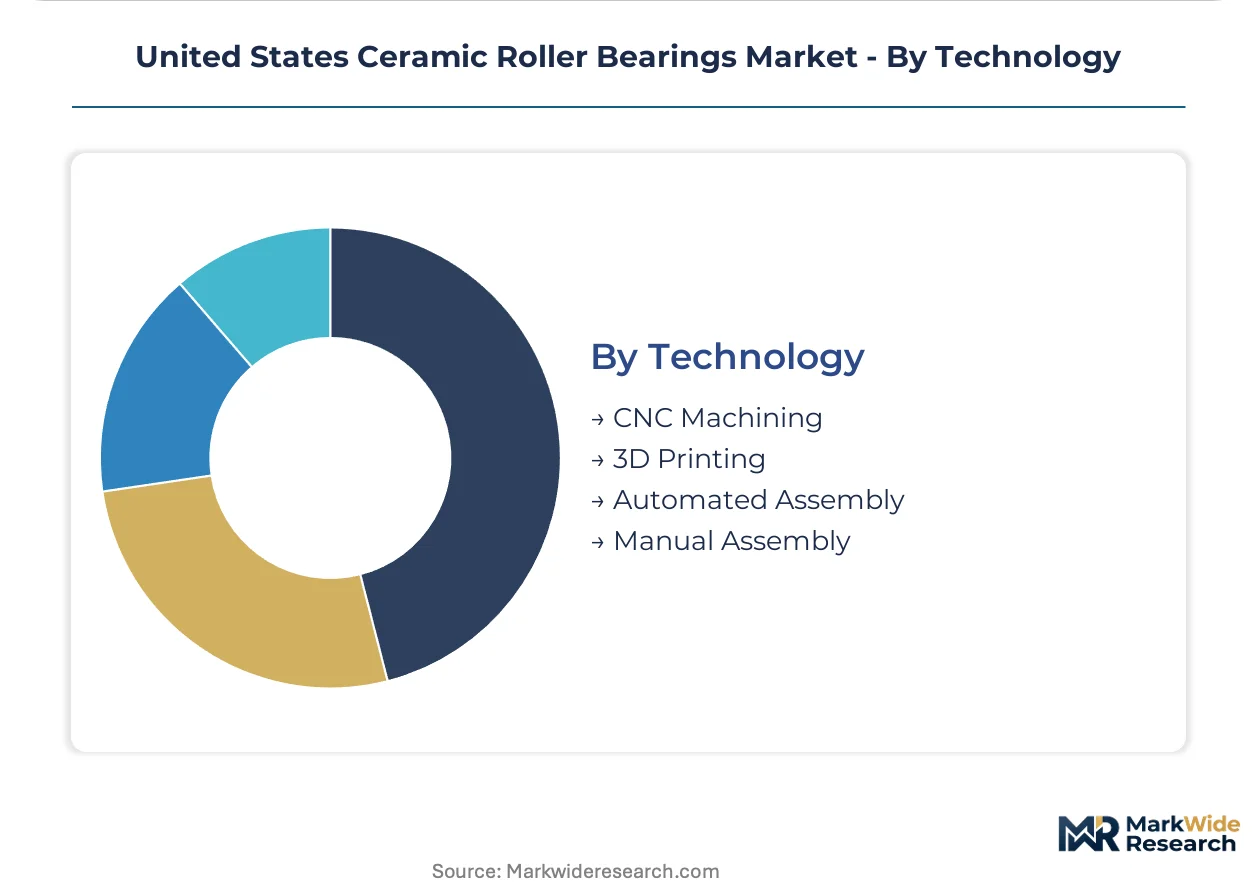
- CNC Machining:Computer-controlled grinding achieves sub-micron tolerance in silicon nitride raceways. California and New York precision shops dominate high-volume production for industrial and automotive applications.
- 3D Printing:Additive manufacturing of bearing cages consolidates multi-part assemblies into single printed components. Minnesota medical device OEMs adopt these designs for surgical robotics where part count reduction matters.
- Automated Assembly:Robotic handling reduces contamination and damage during precision component mating. High-volume lines in Ohio and Illinois serve automotive Tier-1 suppliers with six-sigma quality requirements.
- Manual Assembly:Craft technicians perform final fitting and inspection for FAA-certified aerospace bearings. Connecticut and Arizona facilities maintain this capability despite labor cost premiums for qualification-critical applications.
CNC Machining generates the highest output volumes; 3D Printing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification friction and NHTSA fuel-economy mandates create divergent cost-of-compliance pressures across U.S. manufacturing belts. Production gravitates toward states where regulatory alignment with federal transportation standards reduces qualification overhead.
Michigan
Detroit's automotive belt drives silicon nitride adoption in electric vehicle reduction gearboxes. NHTSA Corporate Average Fuel Economy standards tighten annually, pressuring Tier-1 suppliers toward lightweight rotating components. Grand Rapids and Ann Arbor machining clusters specialize in automated ceramic bearing assembly for BorgWarner and Dana subsystems.
California
Silicon Valley semiconductor fabrication equipment builders demand contamination-free ceramic bearings for vacuum chamber applications. EPA emissions frameworks cascade through supply chains, accelerating material substitution in precision manufacturing. San Jose and Fremont equipment OEMs specify angular contact configurations for high-speed spindle thermal management.
Texas
Gulf Coast chemical processors deploy ceramic bearings in hostile environments where lubrication degradation destroys conventional alloys. OSHA workplace safety regulations extend replacement intervals where hazardous access frequency drops. Houston and Beaumont industrial clusters prioritize total cost of ownership over unit price in maintenance contracting decisions.
Connecticut
Aerospace turbine manufacturers in Hartford's manufacturing corridor specify FAA-certified ceramic bearings for engine spindles operating above 500°F. Extended qualification timelines lock working capital in pre-production inventory for Pratt & Whitney suppliers. Manual assembly craft technicians perform final fitting for certification-critical applications despite labor cost premiums.
Ohio
Cleveland and Cincinnati industrial machinery operators source ceramic replacements directly from distributors rather than captive OEM service networks. Aftermarket service unbundling creates standalone procurement channels for emergency retrofits. Metallurgical diagnostic capabilities concentrate margin capture among specialized distributors with rapid ceramic inventory positioning.
United States Ceramic Roller Bearings Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with aerospace certification requirements favoring established players and industrial applications permitting broader participation. The vendor base organizes around three archetypes: integrated bearing conglomerates with captive ceramic processing, precision ceramics specialists supplying into bearing assemblies, and regional distributors with metallurgical service capabilities. Dominant competitive moves include qualification exclusivity negotiations with OEM platform teams and preventive maintenance contract expansion into customer facilities.
Within the integrated conglomerate tier, SKF Corporation and The Timken Company represent archetypes of service-network-anchored market presence. Schaeffler Group USA Inc. exemplifies geographic dominance strategies in Midwest automotive supplier ecosystems. These three entities occupy positions spanning OEM specification, Tier-1 supply, and aftermarket service channels without exclusive segment concentration.
| Leading Market Players |
|---|
| SKF Corporation |
| The Timken Company |
| Schaeffler Group USA Inc. |
| NSK Global |
| JTEKT Corporation |
| RBC Bearings Incorporated |
| NTN Corporation |
| CeramicSpeed |
| Emerson Bearing Company |
| Others |
Cost & Logistics Intelligence
Captive silicon nitride powder processing within integrated bearing conglomerates anchors both supply security and pricing power for domestic fabricators serving FAA-certified aerospace and NHTSA-regulated automotive channels. This vertical control over high-purity feedstock insulates qualified suppliers from raw material volatility while enabling premium positioning against import-dependent competitors.
Pricing Analysis
Distributor margin layers separate emergency aftermarket procurement from direct OEM contract pricing, with Ohio and California industrial clusters capturing 40-60% premiums on rapid ceramic inventory positioning. Three-tier pricing structure across FAA-certified aerospace, NHTSA-compliant automotive, and standard industrial grades reflects qualification burden and volume scale. Cost compression in moderate-temperature industrial tiers intensifies as hybrid ceramic-steel architectures displace full-ceramic designs. Tier-1 automotive suppliers exhibit highest price sensitivity; aerospace turbine manufacturers accept premium positioning for thermal cycling performance.
Supply Chain Analysis
Domestic-content mandates under NHTSA and FAA procurement guidelines reshape sourcing toward qualified U.S. fabricators with captive hot isostatic pressing capabilities. High-purity silicon nitride powder production concentrates in Germany, Japan, and domestic specialty ceramics facilities; zirconia feedstock draws from Australian and Chinese mineral processing. Single-source vulnerability in aerospace-grade powder qualification creates supply security concerns for Pratt & Whitney and GE Aviation suppliers. Distribution runs through authorized distributor networks with metallurgical diagnostic capabilities in Texas, Ohio, and California industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in U.S. ceramic roller bearings rests on silicon nitride formulation cost-down curves and medical device premium-tier penetration where MRI compatibility commands pricing power.
For Market Incumbents: Hedge against hybrid ceramic-steel displacement in industrial machinery by deepening captive powder processing capabilities and securing FAA qualification exclusivity on next-generation electric propulsion bearing architectures. Anchor service-network presence in Michigan automotive and California precision manufacturing corridors through performance-based maintenance contracting. For New Entrants and Emerging Players: Launch via specialized distributor partnerships targeting Ohio and Texas aftermarket channels where emergency retrofit demand concentrates among industrial machinery operators unbundled from captive OEM service networks. Prioritize surgical robotics OEM supply chains in Minnesota and Massachusetts where 3D-printed bearing cage consolidation reduces incumbent assembly cost advantages. For Investors and Strategic Acquirers: Roll-up economics work for precision ceramics specialists with FAA certification track records because aerospace qualification timelines create sustainable moats against commodity import competition. Target mid-cap fabricators with hot isostatic pressing capacity and existing NHTSA automotive supplier relationships. Monitor FDA breakthrough device designations for surgical robotics platforms as inflection indicators for medical device bearing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Nitride Powder | Captive feedstock supply secures margin against Japanese and German import dependency for domestic fabricators. |
| FAA Electric Propulsion Qualification Pathway | Early certification locks in platform exclusivity with Pratt & Whitney and GE Aviation next-generation programs. |
| 3D-Printed Bearing Cage Manufacturing Scale-Up | Additive consolidation reduces part count for Minnesota surgical robotics OEMs competing on instrument miniaturization. |
| Performance-Based Maintenance Contract Expansion | SKF and Timken service networks embed technicians directly in Michigan automotive and Texas chemical processing facilities. |
| Medical Device OEM Supply Chain Penetration | MRI-compatible zirconia bearings penetrate Massachusetts minimally invasive surgical platform specifications. |
Research Approach
Coverage spans Michigan automotive belt, California precision manufacturing corridor, Texas Gulf Coast chemical processing cluster, and Connecticut aerospace manufacturing corridor, with primary inputs from each. Ceramic bearing procurement directors at BorgWarner and Dana, FAA certification engineers at Pratt & Whitney suppliers, maintenance directors at Ohio industrial machinery operators, and biomedical engineers at Minnesota surgical robotics OEMs provided demand-side intelligence. Secondary validation drew from FAA airworthiness directive filings, NHTSA CAFE standard rulemakings, EPA emissions framework documents, and SEC 10-K disclosures from SKF, Timken, and Schaeffler. Bottom-up volume builds across product type, application, and end-user segments triangulated against top-down market sizing from trade flow analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include bearing geometry configuration, thermal performance tier, certification grade, and regional manufacturing cluster concentration. CAGRs derive from installed base replacement cycle analysis and new platform penetration curves. Industry-specific forecast inputs incorporate NHTSA fuel-economy mandate compliance trajectories and FAA electric propulsion certification timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended FAA qualification delays or breakthrough advances in coated steel alloy performance. Forecasts reflect documented assumptions regarding silicon nitride fracture toughness improvement curves and medical device OEM adoption rates for MRI-compatible rotation interfaces. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Self Locking Nuts Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Mineral Wool Market
Industrial Materials
Global Jet Mill Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Wire Hoods Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Industrial Drum Market
Industrial Materials
Global Friction Products and Materials Market
Industrial Materials
Industrial Films Market
Industrial Materials
Steel Processing Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Couplings Market