
 Heavy Gauge and Thin Gauge Thermoformed Plastics Market | 2026-2036
Heavy Gauge and Thin Gauge Thermoformed Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Gauge and Thin Gauge Thermoformed Plastics Market Foresight
Multi-source procurement among food packaging buyers is hardening as resin volatility pressures contract structures. Greiner Packaging International GmbH leverages captive sheet extrusion across Central European plants to buffer feedstock swings. Placon Corporation anchors its position through recycled PET specialization in thermoformed clamshells for produce chains. Pactiv Evergreen competes via integrated fiber and plastics packaging portfolios serving QSR and grocery channels.
Heavy gauge and thin gauge thermoformed plastics are polymer sheets heated above glass transition temperature then vacuum-formed, pressure-formed, or twin-sheet molded into dimensional parts with wall thicknesses spanning 0.005 to 0.250 inches, serving protective, structural, and barrier functions across packaging and industrial applications. Vacuum forming dominates commodity production of trays and lids where cycle speed governs unit economics, while pressure forming captures premium margin pools in medical device enclosures requiring tight dimensional tolerances. Twin sheet forming sustains growth in automotive HVAC ducting and pallet applications where hollow-core stiffness-to-weight ratios outperform injection molded alternatives.
FDA food-contact notification requirements and EPA resin emissions standards shape material selection and plant siting decisions for domestic producers. ISO 13485 quality system mandates govern sterile barrier validation pathways for healthcare thermoformers supplying surgical kits. Stakeholders must monitor state-level extended producer responsibility legislation as California and Oregon advance post-consumer content minimums that recalibrate recycled feedstock access and pricing.
Market Dynamics
Resin price volatility and FDA food-contact notification tightening are compressing margins for commodity thermoformers while rewarding integrated producers with captive sheet extrusion and recycled feedstock pipelines.
Growth Catalysts
- Sterile barrier validation:ISO 13485 quality system mandates are accelerating healthcare thermoformer qualification for surgical kit trays, locking in multi-year supply agreements with hospital purchasing coalitions.
- Extended producer responsibility laws:California and Oregon post-consumer content minimums are redirecting recycled PET flows toward thermoformed clamshells, creating feedstock security for early compliance adopters.
- Pressure forming precision:Medical device enclosures demanding tight dimensional tolerances are migrating from injection molding, opening premium margin pools for thermoformers with validated cleanroom operations.
Market Restraints
- Propylene and styrene volatility:Crude-linked resin contracts expose thin-gauge producers to margin compression when feedstock swings exceed hedging coverage.
- Tooling lead times:Multi-cavity aluminum mold fabrication for heavy-gauge twin-sheet pallets stretches 14-20 weeks, constraining capacity responsiveness to automotive HVAC ducting demand spikes.
- Fiber-based substitution:Molded fiber trays for QSR clamshells are capturing share in jurisdictions with single-use plastics bans, pressuring polypropylene thermoformer volumes.
Strategic Opportunities
- Pharmaceutical cold chain:Insulated shipper panels for temperature-sensitive biologics represent underpenetrated white space where twin-sheet hollow-core construction outperforms expanded polystyrene.
- Digital print integration:Direct-to-sheet inkjet decoration is collapsing label application steps, enabling versioning for regional produce chains without separate SKU tooling.
- EU Green Deal alignment:CSRD disclosure requirements are creating first-mover advantage for thermoformers with verified recycled content mass-balance accounting.
Industry Challenges
- Cleanroom technician scarcity:ISO Class 8 validation expertise for medical thermoforming remains concentrated among a narrow labor pool in Minnesota and Massachusetts manufacturing clusters.
- Legacy ERP integration:Batch-level traceability for FDA food-contact notifications demands MES upgrades that mid-cap thermoformers struggle to prioritize against tooling capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Gauge and Thin Gauge Thermoformed Plastics Market |
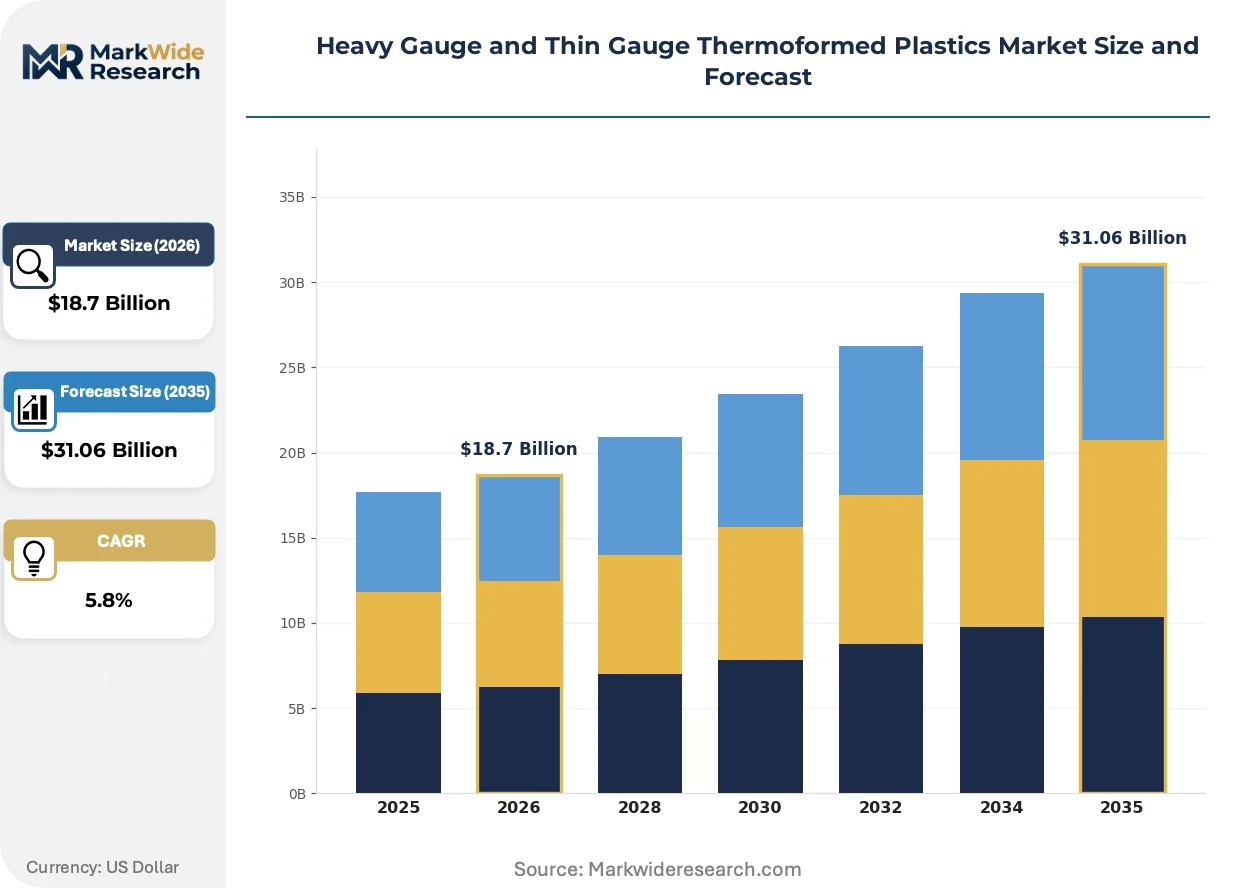
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Containers, Trays, Clamshells Technology: Vacuum Forming, Pressure Forming, Twin Sheet Forming, Plug Assist Application: Food Packaging, Medical Devices, Automotive Components, Retail Displays End User: Food & Beverage, Healthcare, Consumer Goods, Electronics |
| Companies Covered | Greiner Packaging International GmbH, Placon Corporation, Pactiv Evergreen, Amcor plc, Genpak LLC, Berry Global Inc., Anchor Packaging LLC, Dart Container Corporation, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Gauge and Thin Gauge Thermoformed Plastics Market Shifts & Advancements
Active developments across materials science, regulatory compliance architecture, and buyer procurement protocols are restructuring competitive position in thermoformed plastics.
Barrier-coated recycled PET is unifying oxygen and moisture protection with circular feedstock claims. Produce chains and prepared meal packagers are specifying this material for case-ready meat and berry clamshells. The technology is unifying shelf-life extension with EPR compliance, compressing the premium that virgin PET previously commanded.
REACH restrictions on intentionally added microplastics are forcing reformulation of slip agents and anti-static coatings used in thin-gauge thermoformed lids. Compounders serving European food packaging thermoformers are accelerating bio-based additive qualification. Medical device sterile barrier applications face parallel scrutiny under MDR substance disclosure requirements, redirecting R&D spend toward compliant masterbatch development.
Hospital purchasing coalitions are consolidating surgical kit sourcing through designated sterile barrier thermoformers with validated ISO 13485 quality systems. Group Purchasing Organizations are displacing fragmented distributor networks, compressing supplier bases to three-to-five approved thermoformers per geography. This concentration is most visible in the United States Southeast, where health system mergers have consolidated procurement authority across multi-state networks.
Heavy Gauge and Thin Gauge Thermoformed Plastics Market Segmentation
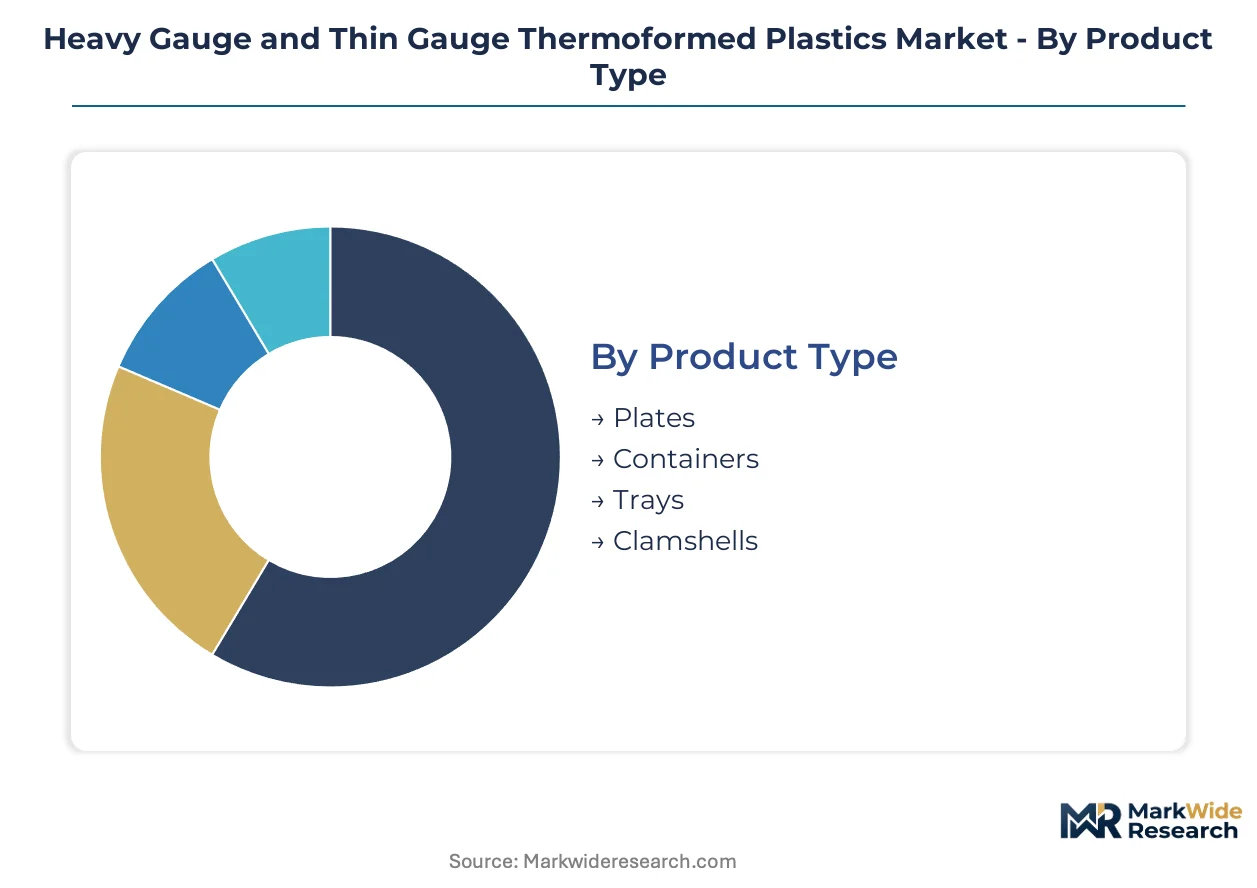
Segmentation in thermoformed plastics reveals how buyer priorities diverge across end-use specifications, with food packaging demanding cycle speed and medical applications requiring validated cleanroom precision. Understanding these dimensional splits exposes where margin pools concentrate and where tooling investments generate durable returns.
Product Type:
Buyer procurement decisions pivot on shelf-life extension requirements and handling durability, with premium specifications commanding dedicated tooling investments.
- Plates:Single-use disposable designs in polypropylene and polystyrene dominate QSR and institutional feeding channels. Demand concentrates in the United States Southeast where healthcare cafeteria contracts specify microwave-safe specifications.
- Containers:Deep-drawn rectangular and round formats with snap-fit lids serve prepared meal and deli applications. European buyers under EPR mandates are redirecting volumes toward recycled PET variants with barrier coatings.
- Trays:Medical-grade sterile barrier formats for surgical kits absorb capacity in Minnesota and Massachusetts manufacturing clusters where ISO 13485 validation concentrates.
- Clamshells:Hinged-lid produce packaging in clear PET and recycled content grades faces fiber substitution pressure in jurisdictions with single-use plastics restrictions.
Trays lead on scale through healthcare procurement consolidation; containers lead on momentum through EPR-driven material switching.
Technology:
Capital intensity and cycle economics separate commodity producers from premium-positioned specialists serving tolerance-critical applications.
- Vacuum Forming:Atmospheric pressure-driven shaping of heated sheet dominates high-volume tray and lid production. United States food packaging buyers source from this tier for cost-sensitive produce and bakery applications.
- Pressure Forming:Positive air pressure against matched molds achieves tight dimensional tolerances for medical device enclosures. Cleanroom-validated operations in California and Massachusetts capture surgical kit and diagnostic housing demand.
- Twin Sheet Forming:Simultaneous heating and bonding of two sheets creates hollow-core structural parts. Automotive HVAC ducting and reusable pallet applications in Germany and the United States Midwest exploit stiffness-to-weight advantages over injection molding.
- Plug Assist:Mechanical pre-stretching with auxiliary plugs improves material distribution in deep-draw parts. Complex industrial housings and display fixtures requiring uniform wall thickness specify this method.
Vacuum forming leads on scale through commodity food packaging volumes; pressure forming leads on momentum through medical device migration from injection molding.
Application:
Regulatory compliance burdens and substitution threats fragment competitive dynamics across end-use verticals.
- Food Packaging:Oxygen and moisture barrier specifications dominate material selection for case-ready meat and berry applications. FDA food-contact notification requirements constrain resin and additive choices for domestic producers.
- Medical Devices:Sterile barrier trays and diagnostic enclosures demand ISO 13485 quality systems and validated cleanroom operations. United States hospital purchasing coalitions are consolidating supplier bases to three-to-five approved thermoformers per geography.
- Automotive Components:HVAC ducting and interior trim panels exploit thermoforming's lower tooling costs versus injection molding for medium-volume production runs.
- Retail Displays:Point-of-sale fixtures and signage leverage thermoforming's rapid prototyping and short-run economics for seasonal merchandising campaigns.
Food packaging leads on scale through QSR and grocery channel absorption; medical devices lead on momentum through sterile barrier validation requirements locking in supply agreements.
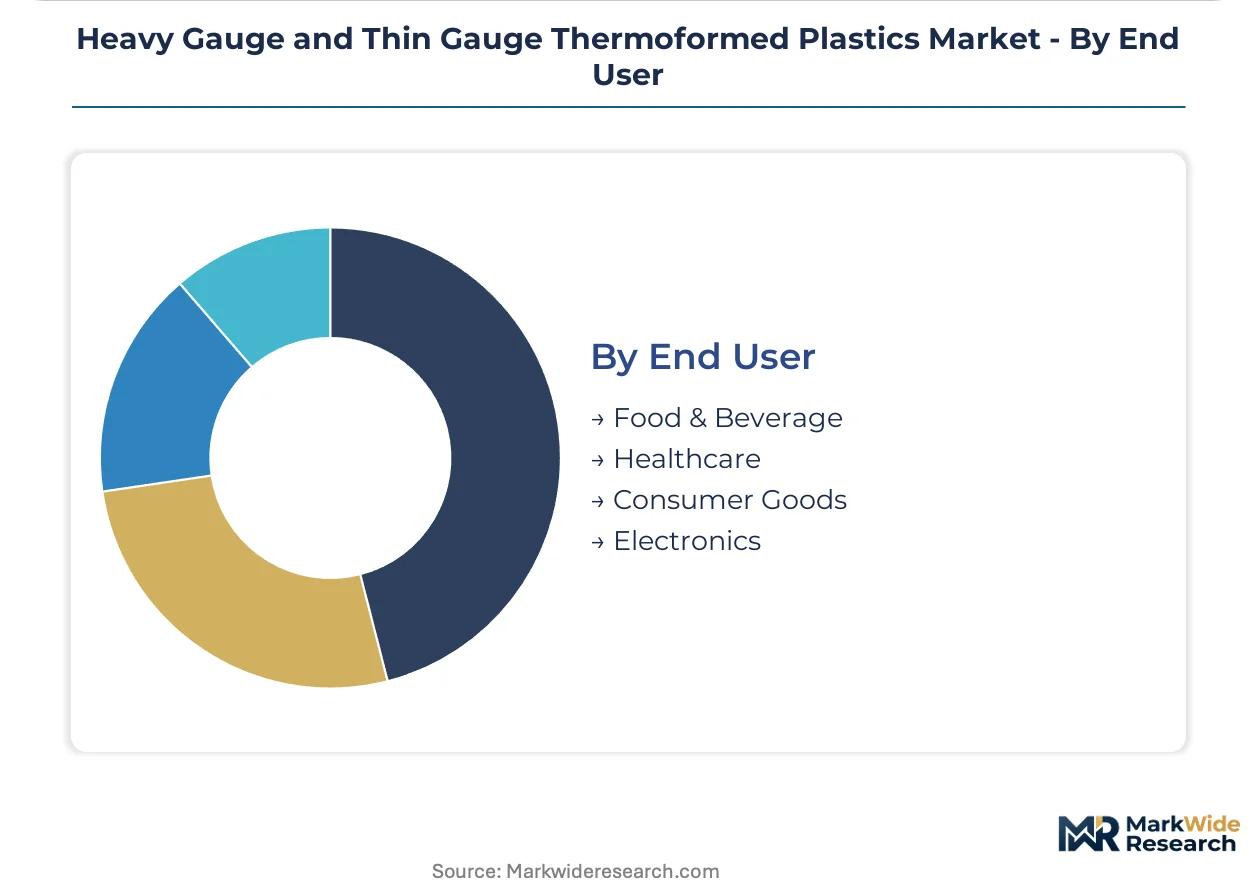
End User:
Procurement sophistication and specification stringency separate price-driven commodity buyers from partnership-oriented strategic accounts.
- Food & Beverage:Multi-source procurement strategies dominate as resin volatility pressures contract structures. Extended producer responsibility laws in California and Oregon are recalibrating recycled feedstock access and pricing.
- Healthcare:Group Purchasing Organizations displace fragmented distributor networks, compressing supplier bases and demanding validated quality systems. Surgical kit tray specifications require multi-year supply commitments.
- Consumer Goods:Electronics packaging and personal care applications prioritize visual clarity and tactile surface finishes for shelf differentiation.
- Electronics:ESD-dissipative trays and shipping containers protect sensitive components through controlled static discharge properties.
Food and beverage leads on scale through produce chain and QSR volume absorption; healthcare leads on momentum through purchasing coalition consolidation and sterile barrier validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minnesota and Massachusetts manufacturing clusters anchor sterile barrier tray production for surgical kit suppliers. FDA food-contact notification requirements shape material selection across domestic thermoforming operations. Extended producer responsibility laws in California and Oregon redirect recycled PET flows toward compliant packaging producers.
United States
Healthcare procurement consolidation drives sterile barrier tray demand from hospital purchasing coalitions. FDA food-contact notification tightening constrains resin and additive choices for food packaging thermoformers. Minnesota and Massachusetts manufacturing clusters concentrate ISO 13485 validated operations serving surgical kit assemblers.
Germany
Automotive HVAC ducting applications exploit twin-sheet forming's stiffness-to-weight advantages over injection molding. REACH restrictions on intentionally added microplastics force reformulation of slip agents in thin-gauge thermoformed lids. Bavaria and Baden-Württemberg industrial zones host precision pressure-forming operations for medical device enclosures.
China
Domestic electronics packaging demand absorbs ESD-dissipative thermoformed tray volumes for semiconductor component shipping. GB standards for food-contact plastics govern material compliance for export-oriented thermoformers. Yangtze River Delta manufacturing corridors concentrate vacuum-forming capacity for commodity produce and bakery applications.
India
Prepared meal and QSR channel expansion drives polypropylene tray and container absorption. FSSAI food-contact regulations shape material selection for domestic packaging producers. Maharashtra and Gujarat industrial corridors concentrate thin-gauge thermoforming operations serving retail food chains.
Brazil
Produce chain modernization drives clear PET clamshell demand for berry and case-ready meat packaging. ANVISA pharmaceutical packaging regulations govern sterile barrier requirements for imported medical device kits. São Paulo state manufacturing clusters anchor thermoformed industrial packaging for automotive component suppliers.
Heavy Gauge and Thin Gauge Thermoformed Plastics Market Competitive Landscape
Global majors compete with regional champions across material specialization and cleanroom validation capabilities. The vendor base stratifies into three tiers: integrated resin-to-package producers with captive sheet extrusion, mid-cap specialists with recycled feedstock pipelines, and commodity thermoformers exposed to resin volatility. Strategic archetypes include healthcare-validated sterile barrier suppliers, EPR-compliant recycled content specialists, and automotive structural parts fabricators. Dominant competitive moves encompass backward integration into sheet extrusion and geographic expansion through distribution partnerships.
Within the integrated producer tier, Greiner Packaging International GmbH exemplifies captive sheet extrusion across Central European manufacturing footprints. Placon Corporation occupies a position within recycled PET specialization for thermoformed clamshell applications. Pactiv Evergreen anchors the diversified packaging portfolio segment through integrated fiber and plastics operations serving QSR and grocery channels.
| Leading Market Players |
|---|
| Greiner Packaging International GmbH |
| Placon Corporation |
| Pactiv Evergreen |
| Amcor plc |
| Genpak LLC |
| Berry Global Inc. |
| Anchor Packaging LLC |
| Dart Container Corporation |
| Sonoco Products Company |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap thermoformers across the United States Midwest and Germany anchor supply discipline through generational capital allocation patience, insulating contract pricing from private-equity-driven margin extraction while concentrating feedstock procurement leverage among integrated resin-to-sheet producers.
Pricing Analysis
Resin cost pass-through clauses dominate contract structures for thin-gauge food packaging thermoformers, with polypropylene and PET price indices resetting monthly against crude-linked benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-validated sterile barrier trays from commodity produce clamshells and institutional disposables. Pricing pressure stems from fiber-based substitution in California and Oregon jurisdictions with single-use plastics restrictions. Food and beverage buyers exhibit highest price sensitivity through multi-source procurement strategies, while healthcare purchasing coalitions lock in premium pricing through multi-year sterile barrier agreements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and medical device buyer demand, while distributor networks serve fragmented QSR and produce chain accounts across North American and European markets. Supply concentrates in the United States, Germany, and China, with Minnesota and Massachusetts clusters anchoring healthcare validation capabilities and Yangtze River Delta corridors dominating commodity vacuum-forming capacity. Feedstock dependencies center on propylene, styrene, and recycled PET flake streams. Single-source vulnerability runs through specialized cleanroom technician labor pools concentrated in Minnesota and Massachusetts. Distribution runs through integrated packaging distributors and direct mill relationships for high-volume healthcare accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in sterile barrier validation tiers and EPR-compliant recycled content positioning, with feedstock cost-down drivers from captive sheet extrusion and premium-tier shifts toward barrier-coated medical formats.
For Market Incumbents: Cement sterile barrier supply relationships through ISO 13485 certification investments in Minnesota and Massachusetts manufacturing clusters, locking in multi-year agreements with hospital purchasing coalitions before fiber-based substitution pressures expand beyond California and Oregon. Backward integration into captive sheet extrusion buffers resin volatility exposure while securing recycled PET feedstock pipelines for EPR compliance. For New Entrants and Emerging Players: E-commerce-enabled direct sourcing platforms offer route to bypass entrenched distributor networks serving mid-tier produce chains, capturing share through rapid prototyping and short-run versioning capabilities. Pharmaceutical cold chain insulated shipper panels represent most penetrable white space, with twin-sheet hollow-core construction outperforming expanded polystyrene incumbents. Target regional produce chains with digital print integration for SKU versioning without separate tooling investments. For Investors and Strategic Acquirers: Valuations sit cheapest among commodity thin-gauge thermoformers exposed to resin volatility without captive extrusion or recycled feedstock pipelines. Long-term viability over the projection horizon favors healthcare-validated specialists with ISO 13485 quality systems and EPR-compliant recycled content positioning. Watch California and Oregon extended producer responsibility enforcement timelines as inflection indicator for recycled feedstock pricing and access dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sheet Extrusion | Captive resin supply buffers margin compression from propylene volatility for integrated producers. |
| ISO 13485 Quality System Certification | Validation unlocks sterile barrier supply agreements with consolidated hospital purchasing coalitions. |
| Recycled PET Feedstock Pipeline Development | EPR compliance positioning secures preferential access to post-consumer flake flows in California and Oregon. |
| Digital Print Integration Investment | Direct-to-sheet inkjet collapses label steps, enabling regional versioning for produce chains. |
| Cleanroom Capacity Expansion | Class 8 validated operations capture medical device enclosure migration from injection molding. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with thermoforming plant managers, procurement leads at food packaging OEMs, hospital GPO contracts managers, and resin compounder technical directors with secondary validation from FDA food-contact notification databases, EPA emissions filings, SEC 10-K disclosures, and trade association production statistics. Bottom-up capacity modeling triangulates against top-down demand aggregation across end-use verticals.
Granularity-level framing applies country-specific resin price indices and regulatory compliance cost structures at the national level, with technology splits modeled at vacuum forming versus pressure forming versus twin-sheet forming resolution. Segmentation dimensions include product type, application vertical, end-user procurement sophistication, and regional production hub clustering. CAGRs derive from weighted average of demand driver elasticities and supply constraint adjustments. Forecast inputs incorporate FDA notification backlog timelines and EPR implementation phase-in schedules.
The model assumes a particular technology adoption path; alternative pathways for barrier-coated recycled PET or fiber-based substitution would alter the outlook for thermoformed plastics penetration in food packaging. Forecasts reflect assumptions regarding resin price correlation stability, regulatory enforcement consistency, and healthcare procurement consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Plastic Gears Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Couplings Market
Industrial Materials
Shock Mat Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Wood Protein Market
Industrial Materials
Twin Screw Extruders Market