
 Global Melamine Faced Chipboard (MFC) Market | 2026-2036
Global Melamine Faced Chipboard (MFC) Market Size, Share, and Industry Trends Forecast 2026-2036
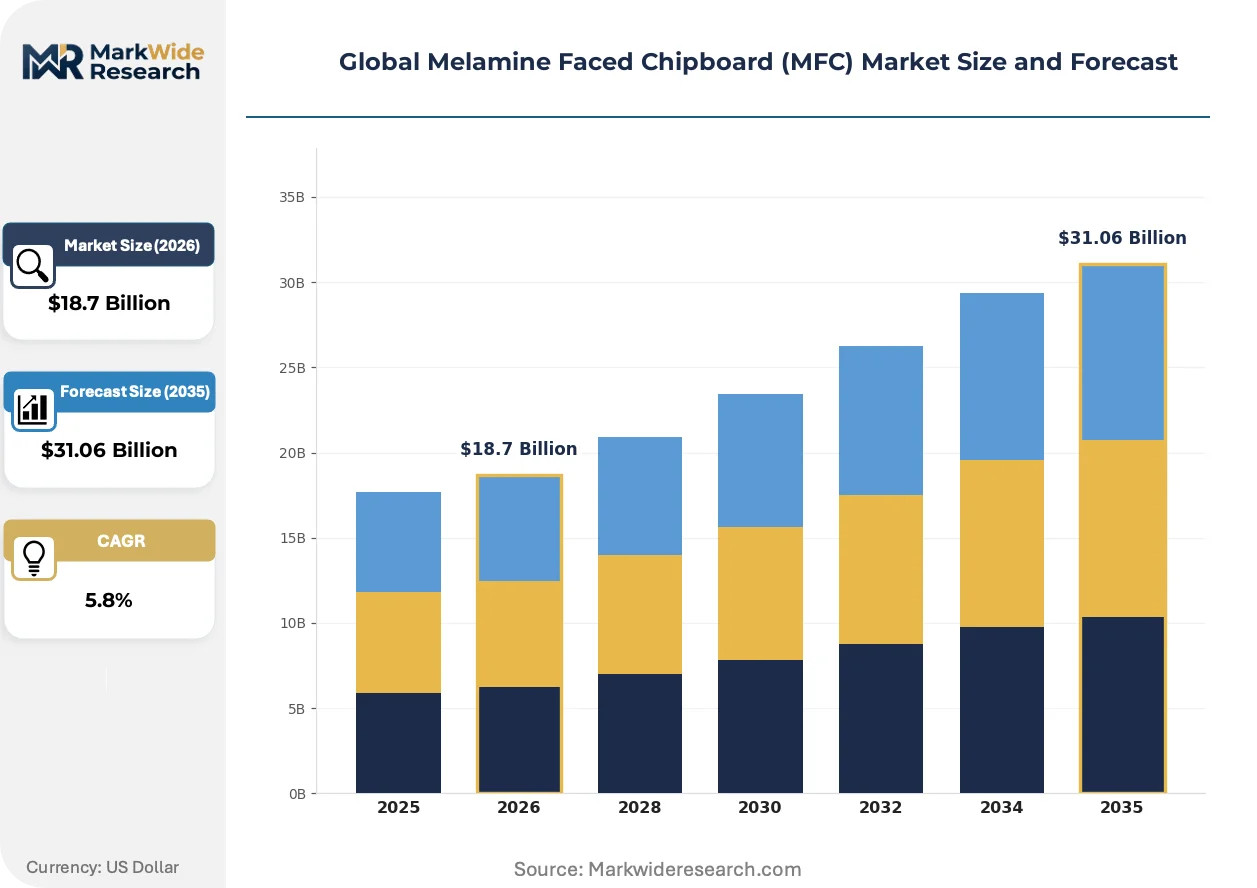
Global Melamine Faced Chipboard (MFC) Market Outlook
Aftermarket service revenue from panel replacement and refurbishment is reshaping margin pools in the MFC value chain, pulling profitability downstream from raw board production. Kronospan leverages its integrated resin and substrate operations across Central European mills to sustain cost leadership in standard-grade output. Egger anchors its competitive position through specialized decor design capabilities and direct distribution to furniture OEMs in Germany and Austria. Pfleiderer competes aggressively on high-gloss and textured surface technologies, occupying premium specification channels in commercial interiors.
Melamine faced chipboard consists of a particleboard core bonded with thermosetting melamine-formaldehyde resin-impregnated decorative paper under heat and pressure, typically achieving surface densities of 800-900 kg/m³ and scratch resistance rated to EN 438. Standard MFC dominates volume flows into mass-market furniture, while textured MFC commands widening specification in architect-driven commercial fit-outs where tactile surface quality differentiates project bids. The 18mm thickness category leads residential cabinet applications, whereas 25mm and 36mm boards concentrate in institutional and heavy-duty commercial installations where load-bearing performance justifies material premiums.
The EU Ecodesign Framework and REACH restrictions on formaldehyde emissions under EN 13986 are tightening compliance thresholds for board importers into European markets. China's GB standards for indoor decoration materials and the US EPA TSCA Title VI certification for composite wood products create divergent testing regimes that fragment market access protocols. Japan's JIS A 5908 and South Korea's KC marking add further certification layers for Asian supply chains targeting premium export segments. Stakeholders must monitor regulatory harmonization pressures between EU and Asian emission standards while building dual-certified production lines to preserve cross-border shipment flexibility.
Market Dynamics
The EU Ecodesign Framework and tightening formaldehyde emission standards under EN 13986 are forcing residential furniture manufacturers across Germany and Poland to accelerate substitution toward low-emission boards, compressing procurement timelines for certified suppliers.
Growth Catalysts
- EU Ecodesign Framework:Tightening formaldehyde emission thresholds under EN 13986 are accelerating substitution toward low-emission boards across German and Polish kitchen cabinetry production.
- China's Guangdong Province:Integrated furniture clusters consume over one-third of regional MFC output, creating concentrated demand pull for high-volume board suppliers.
- Aftermarket Panel Replacement:Service revenue from refurbishment and replacement is reshaping margin pools, pulling profitability downstream from raw board production into distribution and installation channels.
Market Restraints
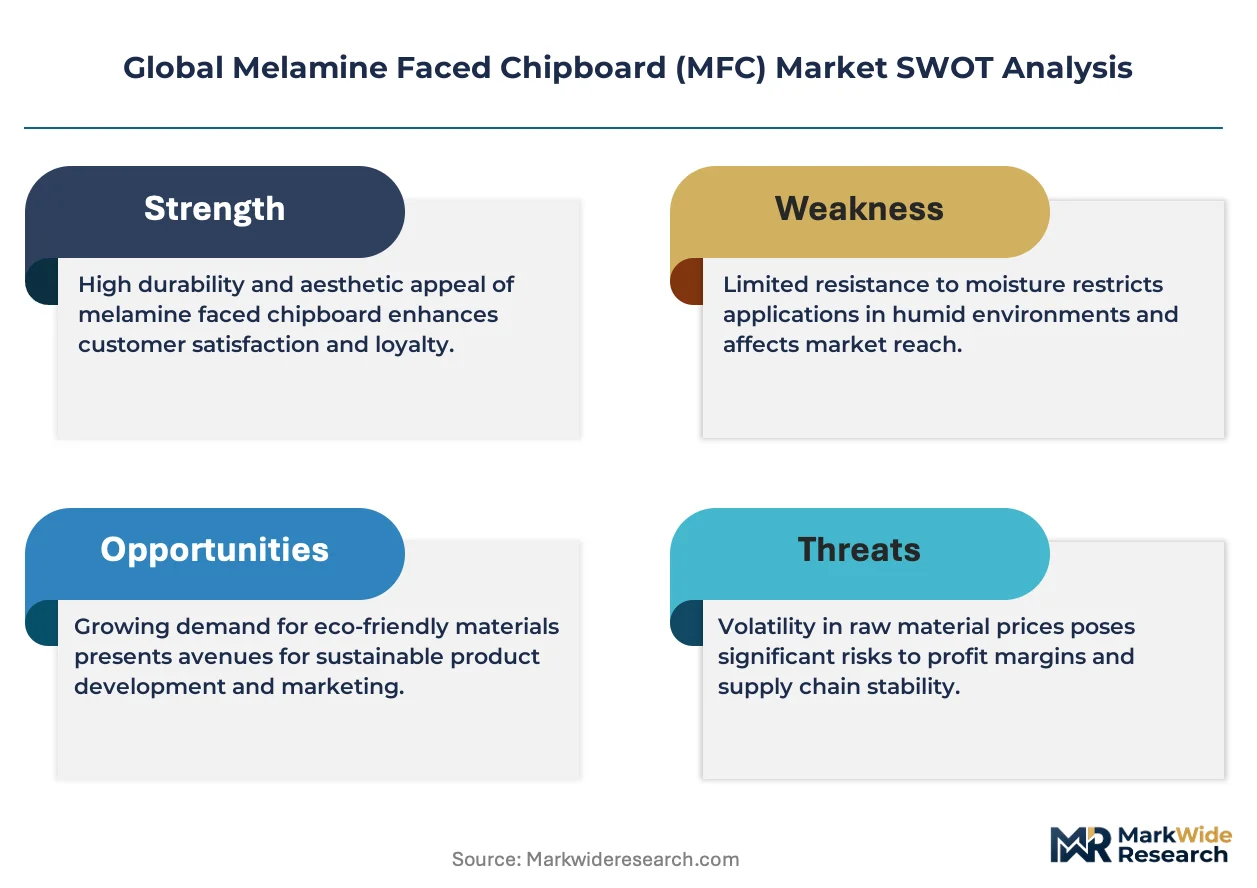
- Urea-Formaldehyde Resin Volatility:Input cost fluctuations for melamine-formaldehyde resin binders compress margins for non-integrated producers lacking captive chemical supply.
- Central European Supply Concentration:Kronospan's integrated resin and substrate operations across Central European mills create cost leadership barriers for new entrants in standard-grade output.
- Divergent Certification Regimes:Fragmented testing protocols between EU EN 13986, China GB standards, and US EPA TSCA Title VI create compliance friction for cross-border shipment flexibility.
Strategic Opportunities
- India's Underpenetrated Furniture Market:Low MFC penetration in residential cabinetry offers white space for certified suppliers as BIS standards align with international emission protocols.
- Digital Decor Design Convergence:Integration of high-resolution printing with thermosetting resin impregnation enables mass-customization of surface aesthetics for architect-driven commercial fit-outs.
- EU Green Deal Procurement Mandates:Public sector furniture tenders increasingly specify low-emission certified boards, creating regulatory tailwind for EN 13986-compliant producers.
Industry Challenges
- Dual-Certification Production Complexity:Building production lines compliant with both EU EN 13986 and China GB standards requires capital-intensive equipment reconfiguration and extended validation timelines.
- Decor Design Talent Scarcity:Specialized surface texture development capabilities concentrate with established players, constraining new entrants' access to premium specification channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Melamine Faced Chipboard (MFC) Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MFC, High-Gloss MFC, Textured MFC, Slatted MFC Application: Furniture, Cabinets, Wall Panels, Flooring End User: Residential, Commercial, Institutional, Industrial Thickness: 16mm, 18mm, 25mm, 36mm |
| Companies Covered | Kronospan, Egger, Pfleiderer, Saviola Group, Finsa, Unilin, Kastamonu Entegre, Sonae Arauco, SM 'art, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Melamine Faced Chipboard (MFC) Market Strategic Shifts
Surface technology advancement and procurement digitization are compressing traditional specification cycles while elevating tactile quality as a competitive differentiator in architect-driven commercial projects.
Digital surface design platforms are digitizing decor development workflows, enabling real-time pattern customization and accelerated sample-to-production cycles. German and Austrian furniture OEMs are adopting these tools fastest, compressing traditional six-month design cycles to eight-week turnarounds. This compression is digitizing competitive positioning around design responsiveness rather than scale economies alone.
REACH restrictions on formaldehyde emissions are tightening compliance thresholds for board importers into European markets. Industrial consequence includes accelerated phase-out of urea-formaldehyde binders in favor of phenol-formaldehyde and pure melamine alternatives. Kitchen cabinetry manufacturers in Germany face the steepest adaptation costs, driving consolidation toward integrated chemical-board producers.
Architects and interior designers are consolidating specification authority, displacing traditional distributor influence in commercial fit-out channels. Direct procurement relationships between furniture OEMs and board producers are replacing multi-tier distribution in Germany and Austria. This concentration is most visible in high-gloss and textured surface categories where tactile quality differentiates project bids.
Global Melamine Faced Chipboard (MFC) Market Segmentation
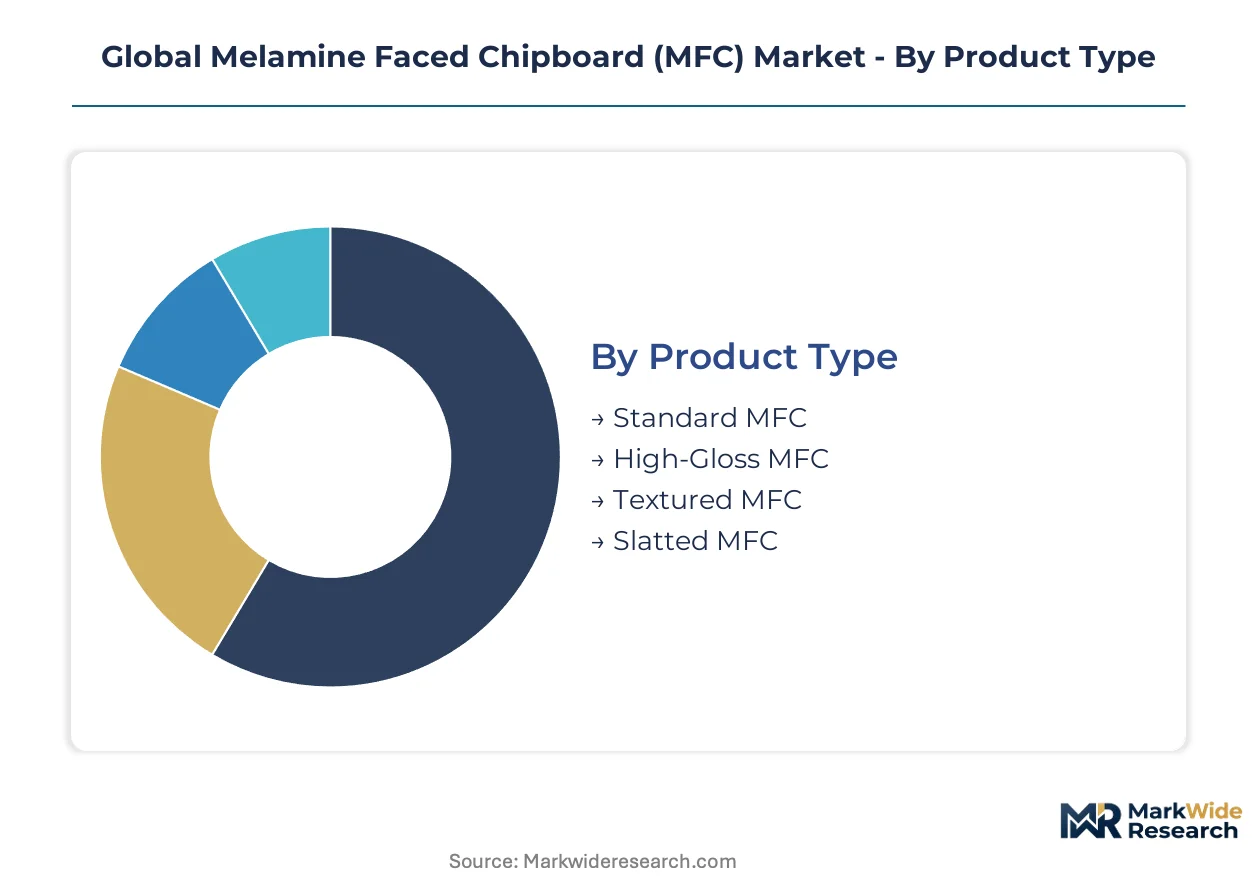
Segmentation in the MFC market tracks divergent specification requirements across residential cabinetry, commercial interiors, and institutional fit-outs. Surface finish technology and board thickness specifications vary sharply by end-use durability demands and regulatory exposure.
Product Type:
Cost tier differentiation separates commodity-grade output from premium specification surfaces where tactile quality commands material premiums.
- Standard MFC:Particleboard core bonded with melamine-formaldehyde resin-impregnated decorative paper achieves surface densities of 800-900 kg/m³. Mass-market furniture manufacturers in China and Poland consume this grade in highest volumes for kitchen cabinetry where scratch resistance to EN 438 suffices.
- High-Gloss MFC:Thermosetting resin formulation with specialized press calibration delivers mirror-finish surfaces. Commercial interior specification in Germany and Austria concentrates here, where project bids differentiate on reflective surface quality in reception areas and retail environments.
- Textured MFC:Embossed surface replication of wood grain or fabric weave serves architect-driven commercial fit-outs.
- Slatted MFC:Pre-cut linear groove patterns reduce on-site fabrication for acoustic panel applications.
Standard MFC commands the established base. The steepest expansion runs through textured MFC.
Application:
Application focus determines resin formulation, density calibration, and edge-banding requirements across furniture manufacturing channels.
- Furniture:Residential case goods and seating frames utilize 18mm boards with standard decor matching. Polish and German OEMs drive procurement volumes for flat-pack distribution across European retail channels.
- Cabinets:Kitchen and bath cabinetry demand moisture-resistant edge sealing and formaldehyde-compliant substrates under EN 13986. German manufacturers face the steepest adaptation costs as EU Ecodesign Framework thresholds tighten.
- Wall Panels:Vertical surface installations prioritize lightweight 16mm construction with fire-retardant additives.
- Flooring:High-traffic commercial installations specify 25mm and 36mm thickness categories with enhanced load-bearing cores.
Furniture applications command the established base. The steepest expansion runs through wall panel specification.
End User:
Customer type segmentation maps divergent procurement authority structures and compliance exposure across private and public sector channels.
- Residential:Individual homeowners and developers specify through retail distribution or direct contractor relationships. China's Guangdong province furniture clusters consume over one-third of regional MFC output for this segment.
- Commercial:Corporate fit-out contractors and interior design firms consolidate specification authority. Direct procurement between furniture OEMs and board producers is displacing multi-tier distribution in Germany and Austria.
- Institutional:Public sector tenders under EU Green Deal mandates increasingly specify low-emission certified boards.
- Industrial:Manufacturing facility furnishings and workstation systems prioritize durability over surface aesthetics.
Residential end users command the established base. The steepest expansion runs through institutional procurement channels.
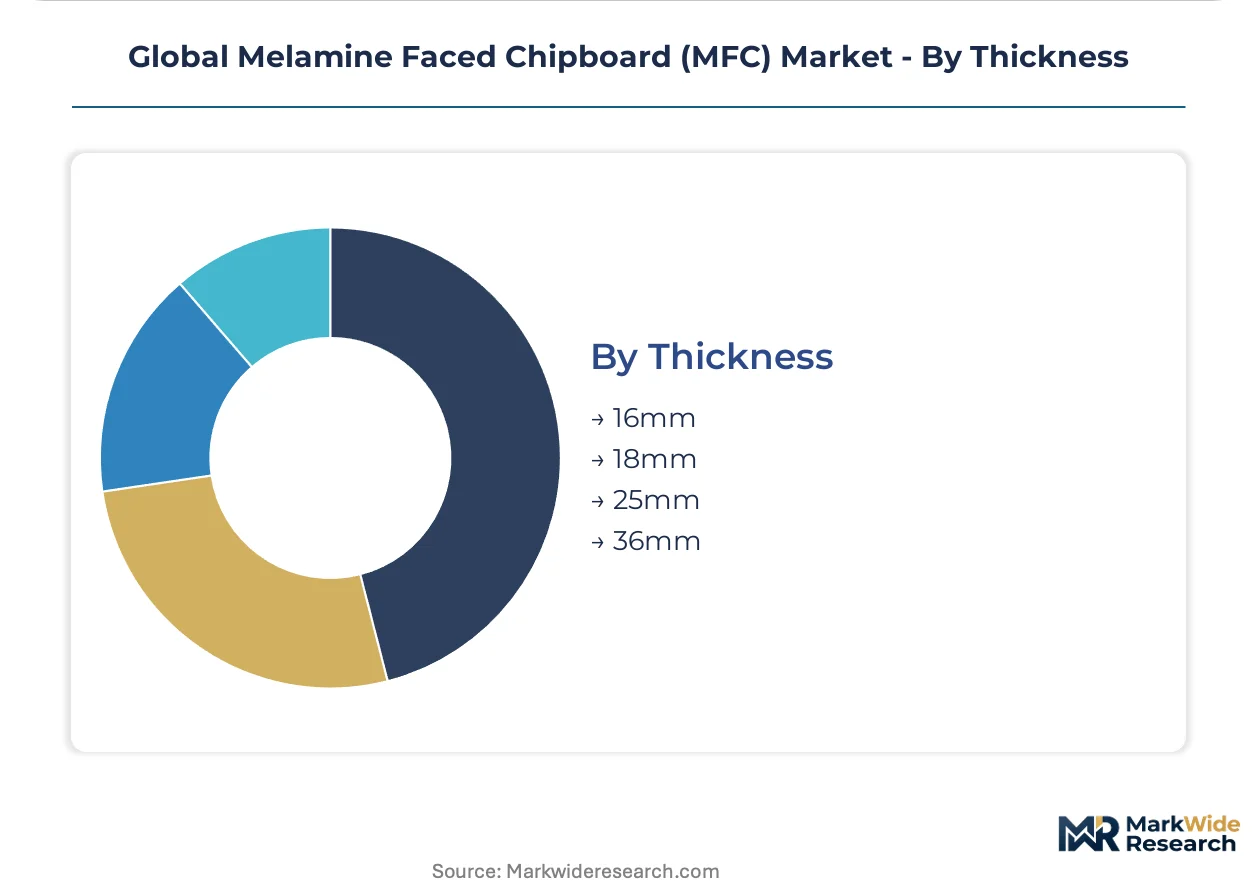
Thickness:
Volume segmentation by board thickness correlates directly with load-bearing performance requirements and material cost positioning.
- 18mm:Dominant specification for residential cabinet carcasses and drawer boxes. Polish kitchen manufacturers standardize on this thickness for flat-pack export production.
- 25mm:Heavy-duty commercial applications including reception desks and transaction counters. German contract furniture producers specify this grade for institutional installations where structural integrity justifies material premiums.
- 16mm:Lightweight vertical applications and budget furniture lines.
- 36mm:Structural worktops and laboratory surfaces requiring maximum span capability.
18mm thickness commands the established base. The steepest expansion runs through 25mm specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Poland exhibit acute price sensitivity on standard-grade MFC, while commercial specifiers in Austria and Switzerland absorb material premiums for textured and high-gloss surfaces without volume elasticity.
Germany
Kitchen cabinetry manufacturers in North Rhine-Westphalia and Bavaria dominate procurement volumes for 18mm standard boards under flat-pack export programs. The EU Ecodesign Framework and EN 13986 emission thresholds are accelerating consolidation toward integrated chemical-board producers. Direct procurement relationships between furniture OEMs and board mills are displacing traditional distributor tiers in the Baden-Württemberg furniture cluster.
Poland
Residential furniture exporters source standard MFC at scale for European retail distribution, with procurement concentrated around Poznań and Wrocław manufacturing basins. Polish producers face compressed margins from urea-formaldehyde resin volatility absent captive chemical supply. The country's national standardization body is aligning domestic certification with EU emission protocols to preserve cross-border shipment access.
China
Integrated furniture clusters in Guangdong province consume over one-third of regional MFC output for domestic residential cabinetry and export assembly. GB standards for indoor decoration materials create divergent testing regimes from EU and US certification requirements. The Pearl River Delta concentration of board mills and furniture OEMs enables compressed logistics costs for high-volume procurement.
United States
Commercial interior contractors specify textured and high-gloss surfaces for corporate fit-outs, with demand concentrated in Texas and California metropolitan construction corridors. EPA TSCA Title VI certification for composite wood products creates compliance friction for European and Asian import shipments. The Southeast furniture manufacturing belt is expanding MFC consumption for mid-market residential case goods production.
India
Residential cabinetry penetration remains underdeveloped relative to global benchmarks, creating white space for certified suppliers as BIS standards converge with international emission protocols. Mumbai and Delhi-NCR furniture manufacturers are initiating MFC procurement trials for modular kitchen programs. The country's national standards body is accelerating harmonization timelines to unlock import certification pathways.
Global Melamine Faced Chipboard (MFC) Market Competitive Environment
Capability concentration sits with decor design specialists; scale advantage sits with integrated resin-substrate operators. The vendor base separates into three functional tiers: chemical-integrated volume producers, surface technology specialists, and regional fabrication mills serving protected domestic markets. Consolidation pressure runs highest among non-integrated standard-grade producers facing input cost volatility. Dominant competitive moves include backward integration into captive resin supply and direct distribution bypass to furniture OEMs.
Among Central European integrated producers, Kronospan exemplifies scale-driven positioning through captive chemical and substrate operations. Egger and Pfleiderer occupy distinct capability tiers, with the former representing specialized decor design anchoring and the latter exemplifying premium surface technology specialization. These three entities collectively illustrate the structural divergence between volume efficiency and specification authority in board procurement channels.
| Leading Market Players |
|---|
| Kronospan |
| Egger |
| Pfleiderer |
| Saviola Group |
| Finsa |
| Unilin |
| Kastamonu Entegre |
| Sonae Arauco |
| SM 'art |
| Others |
Value Chain & Pricing Dynamics
Guangdong province's integrated furniture clusters anchor global MFC capacity, with Pearl River Delta mills leveraging co-located resin production and downstream OEM demand to extract pricing power through logistics compression. This geographic concentration enables board producers to offset urea-formaldehyde resin volatility via captive chemical supply, while procurement digitization accelerates spot-price discovery for standard-grade volumes.
Pricing Analysis
Aftermarket panel replacement and refurbishment service revenue drives lifetime value capture, with distribution and installation channels pulling profitability downstream from raw board production. Three-tier pricing structure across premium, standard, and economy levels separates high-gloss and textured surfaces from commodity-grade output, where EN 13986 certification tiers command material premiums. Cost compression in standard-grade segments is intensifying because Polish and German buyers exhibit acute price sensitivity on 18mm boards for flat-pack export programs. Commercial specifiers in Austria and Switzerland absorb surface technology premiums without volume elasticity, while residential procurement in China's Guangdong province concentrates on mass-market decor matching.
Supply Chain Analysis
Contract manufacturing concentration sits with Kronospan's integrated Central European mills, Egger's specialized decor design facilities, and Pfleiderer's premium surface technology operations. Production gravity centers on Germany, Poland, and China, with raw material dependencies spanning melamine-formaldehyde resin binders, decorative paper substrates, and particleboard cores. Single-source vulnerability runs through urea-formaldehyde resin supply for non-integrated producers lacking captive chemical operations. Distribution runs through direct procurement relationships between furniture OEMs and board mills in Germany and Austria, displacing traditional multi-tier distributor channels in architect-driven commercial fit-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MFC market represents an early-cycle expansion story, with India's underpenetrated residential cabinetry segment and institutional procurement mandates under the EU Green Deal creating structural tailwinds for certified suppliers.
For Market Incumbents: Pre-empt margin erosion from resin input volatility by deepening backward integration into captive melamine-formaldehyde production or securing long-term offtake agreements with chemical suppliers. Accelerate EN 13986 dual-certification investments to preserve cross-border shipment flexibility as EU Ecodesign Framework thresholds tighten. Channel control through direct distribution to furniture OEMs in Germany and Austria defends specification authority against emerging surface technology specialists. For New Entrants and Emerging Players: Build out white-space positioning in India's modular kitchen programs before BIS standards fully converge with international emission protocols, targeting Mumbai and Delhi-NCR furniture manufacturers initiating MFC procurement trials. Digital decor design capabilities enable mass-customization entry into architect-driven commercial fit-outs, where eight-week sample-to-production cycles compress traditional specification timelines. Go-to-market execution should anchor on specialized surface texture development, bypassing scale disadvantages against integrated Central European producers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors surface technology specialists with digital design platforms and dual-certified production assets over pure-volume commodity operators. Long-term viability across the projection horizon rests on acquisition targets combining EN 13986 compliance with direct OEM distribution relationships in Germany and Austria. The signal to watch is consolidation velocity among non-integrated standard-grade producers facing sustained input cost pressure, which indicates inflection toward integrated chemical-board structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Kronospan's captive chemical operations sustain cost leadership against resin volatility. |
| Dual-Certification Production Investment | EN 13986 and China GB compliance preserves cross-border shipment flexibility for integrated mills. |
| Digital Decor Design Platform Deployment | German furniture OEMs compress six-month design cycles to eight-week turnarounds through real-time customization. |
| Direct Distribution to Furniture OEMs | Egger's channel bypass in Austria and Austria consolidates specification authority in commercial fit-outs. |
| Surface Technology Specialization | Pfleiderer's high-gloss and textured capabilities capture premium specification in architect-driven projects. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at Central European board mills, procurement leads at German and Polish furniture OEMs, distribution channel partners, and technical R&D directors at resin suppliers, then refined through secondary validation. Trade data from Eurostat and Chinese customs authorities, SEC filings from integrated producers, industry association reports from the European Panel Federation, and certification registries under EN 13986 and EPA TSCA Title VI anchored quantitative sizing. Bottom-up volume triangulation across thickness categories and surface finish tiers was cross-checked against top-down demand aggregation from end-use applications.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling spanning product type, application, end user, and board thickness specifications. CAGRs were derived from regression analysis of historical procurement volumes and projected substitution rates toward low-emission boards. Industry-specific forecast inputs included EU Ecodesign Framework implementation timelines and BIS standard harmonization progress in India.
Sensitivities concentrate around regulatory acceleration in emission standard harmonization, resin input cost volatility, and consolidation velocity among non-integrated producers. Forecasts reflect documented assumptions on substitution elasticities and certification adoption curves. Quarterly review of EN 13986 compliance rates, BIS standard convergence milestones, and integrated producer capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Tooling Board Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market