
 Industrial Sodium Chloride Market | 2026-2036
Industrial Sodium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Sodium Chloride Market Outlook
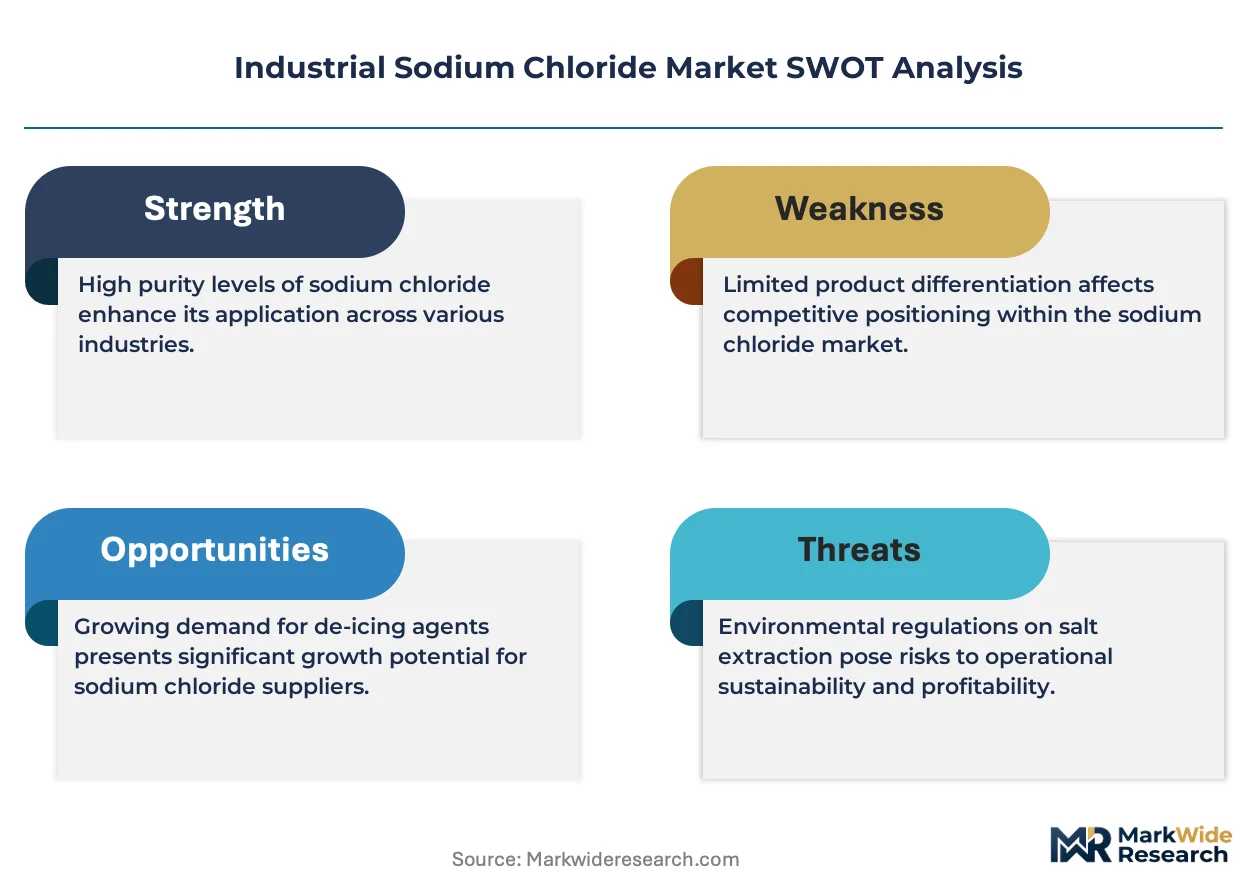
The gap between solar-evaporated premium grades and mechanically harvested commodity salt is repositioning procurement strategies across the value chain. Tata Chemicals leverages captive brine reserves in Gujarat to sustain cost leadership in bulk chemical feedstock. INEOS anchors its European chlor-alkali network with integrated salt sourcing that controls supply continuity for caustic soda and chlorine derivatives. K+S Aktiengesellschaft competes on deep vertical integration from mine to port, dominating winter de-icing contracts across Northern Europe.
Industrial sodium chloride is a crystalline inorganic compound with minimum purity thresholds of 99.1% NaCl for chemical-grade applications, produced through solar evaporation, vacuum evaporation, or rock salt mining depending on regional geology and energy costs. Its primary industrial purpose centers on serving as the essential chlorine and sodium ion source for chlor-alkali electrolysis, water softening ion exchange regeneration, and highway de-icing operations. Granular and flake product types command margin premiums in chemical production where controlled dissolution rates protect membrane cell integrity, while powder grades face commoditization in bulk water treatment. Application segmentation reveals de-icing as a mature volume pool with weather-dependent volatility, whereas pharmaceutical-grade purification for dialysis and intravenous solutions represents a concentrated margin segment.
The US EPA regulates chloride discharge limits under the Clean Water Act, pushing water treatment operators toward higher-efficiency salt formulations that reduce downstream environmental loading. EU REACH registration requirements and the F-Gas Regulation constrain fluorochemical manufacturers to certified salt purity grades that prevent catalyst poisoning in hydrofluoric acid production. China's SAMR enforces GB/T 5462 standards for industrial salt quality, creating compliance barriers for imported material in state-backed chemical park expansions. Stakeholders must monitor tightening effluent standards in coastal manufacturing zones where brine disposal restrictions threaten conventional solar evaporation economics.
Market Dynamics
Chlor-alkali membrane cell technology upgrades are forcing salt purity specifications upward across chemical manufacturing corridors, compressing margins for commodity-grade suppliers while rewarding integrated producers with captive brine processing.
Growth Catalysts
- EU F-Gas Regulation tightening:Fluorochemical manufacturers must source certified high-purity salt to prevent catalyst poisoning in hydrofluoric acid production, creating a premium-grade demand pool.
- China's chemical park expansion:State-backed capacity builds in the coastal processing belt concentrate procurement volumes and favor suppliers with GB/T 5462 compliance documentation.
- Membrane cell integrity requirements:Controlled dissolution rate salts protect electrolyzer performance, driving granular and flake product premiums over powder grades in chlor-alkali operations.
Market Restraints
- Brine disposal restrictions:Coastal manufacturing zones face tightening effluent standards that threaten conventional solar evaporation economics and raise compliance costs.
- Energy cost volatility:Vacuum evaporation production depends on natural gas and electricity inputs, exposing margins to regional power market fluctuations.
- Substitution in de-icing:Calcium magnesium acetate and potassium acetate formulations displace sodium chloride in environmentally sensitive highway corridors.
Strategic Opportunities
- Pharmaceutical-grade purification:Dialysis and intravenous solution manufacturing represents a concentrated margin segment with stringent purity thresholds and long-term supply contracts.
- Water softening efficiency mandates:US EPA Clean Water Act chloride discharge limits push treatment operators toward higher-efficiency salt formulations that reduce downstream environmental loading.
- Integrated mine-to-port logistics:Deep vertical integration from subterranean rock salt extraction through dedicated port terminals secures supply continuity for caustic soda and chlorine derivative producers.
Industry Challenges
- Geological reserve depletion:Rock salt mining operations face declining ore quality in mature deposits, requiring deeper shafts and higher extraction costs.
- REACH registration timelines:EU chemical safety documentation creates extended certification cycles for imported material, delaying market entry for non-European suppliers.
- Membrane cell retrofit compatibility:Legacy electrolyzer installations require salt specification matching that complicates supplier switching and limits sourcing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Sodium Chloride Market |
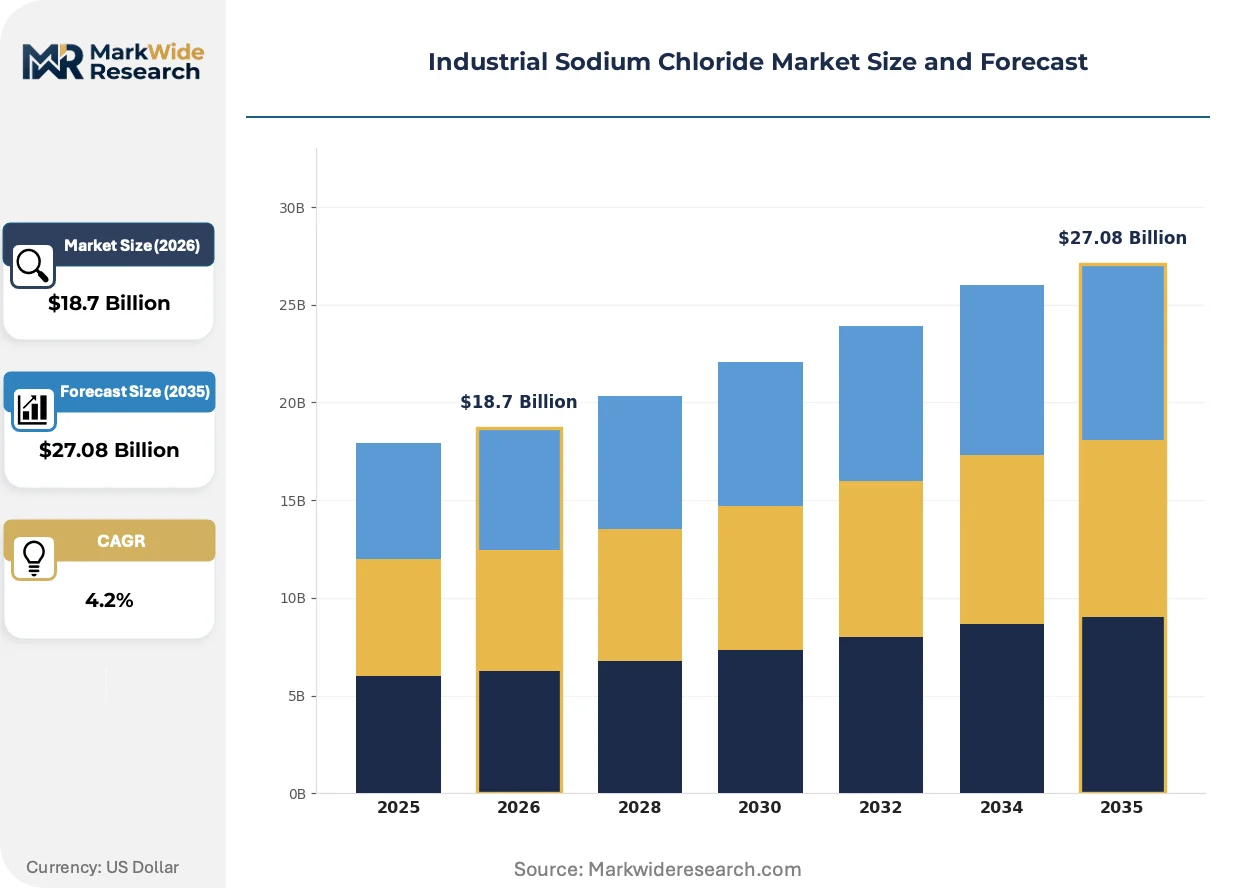
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Flake, Powder, Block Application: Chemical Production, Water Treatment, De-icing, Food Processing End User: Manufacturing, Mining, Agriculture, Pharmaceuticals Distribution Channel: Online, Direct Sales, Wholesalers, Retail |
| Companies Covered | Tata Chemicals, INEOS, Cargill Incorporated, ICL Group, Cheetham Salt, K+S Aktiengesellschaft, China National Salt Industry Corporation, Nouryon, Compass Minerals International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Sodium Chloride Market Strategic Shifts
Processing automation and purity verification technologies are compressing the gap between solar-evaporated premium grades and mechanically harvested commodity salt, reshaping procurement strategies across the value chain.
Automated optical sorting and laser-induced breakdown spectroscopy is automating real-time impurity detection in salt processing lines. Chlor-alkali producers with membrane cell assets are adopting these systems fastest to protect electrolyzer integrity. The technology is automating quality control labor out of mid-tier processing facilities, forcing consolidation among regional packagers.
REACH compliance and evolving EU F-Gas Regulation specifications constrain fluorochemical manufacturers to certified salt purity grades. Industrial salt used in hydrofluoric acid production now requires documented trace element thresholds to prevent catalyst poisoning. European chlor-alkali networks are responding with backward integration into captive brine reserves and dedicated purification investments.
Long-term offtake contracting is displacing spot market purchasing among large chemical manufacturers seeking supply security. Bulk consumers in the chlor-alkali sector are locking in multi-year agreements with integrated producers controlling mine-to-port logistics. This pattern concentrates procurement volumes with vertically integrated suppliers in Germany, China, and India.
Industrial Sodium Chloride Market Segmentation
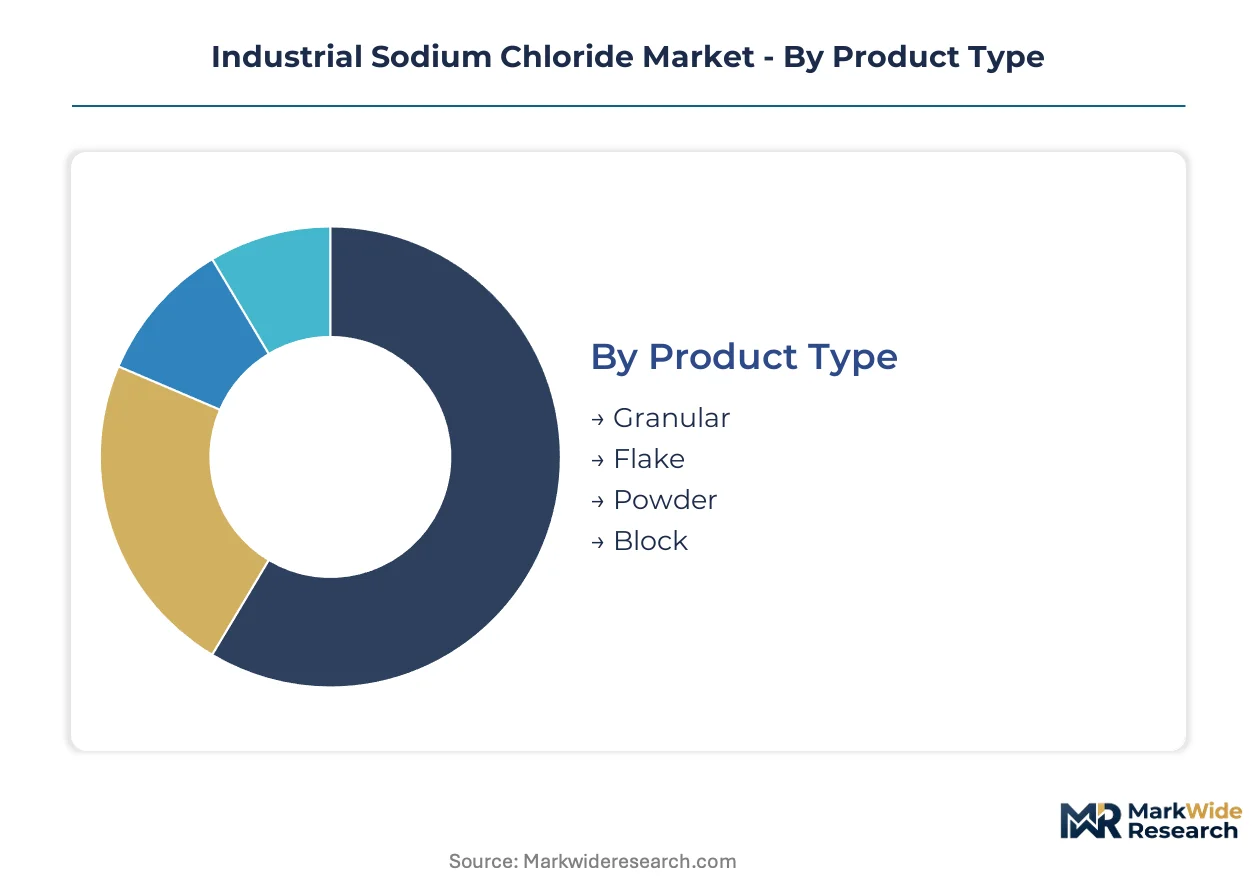
Industrial sodium chloride procurement varies sharply across buyer profiles, with chlor-alkali operators demanding membrane-compatible purity grades while highway authorities prioritize volume economics over chemical specifications. Segmentation reveals where margin pools concentrate and which supply configurations command pricing power.
Product Type:
Granular and flake formats command premium positioning where controlled dissolution protects process equipment, while powder and block grades serve bulk commodity applications with thinner margins.
- Granular:Uniform crystal structure with 99.1% minimum NaCl purity and low insoluble residue. Chlor-alkali membrane cell operators in Germany and China specify granular feedstock to prevent electrolyzer fouling, with multi-year offtake contracts locking in supply security.
- Flake:Thin, plate-like crystals produced through vacuum evaporation with rapid dissolution kinetics. Water softening regeneration applications in US municipal treatment facilities favor flake geometry for uniform brine generation, though energy-intensive production exposes margins to natural gas price swings.
- Powder:Finely milled rock salt or evaporated material for bulk chemical synthesis and general industrial use.
- Block:Compressed salt for livestock nutrition and specialized water conditioning systems.
Granular leads volumes today; flake is gaining share fastest.
Application:
Chemical manufacturing absorbs the highest-purity tonnage, while de-icing and food processing split between commodity scale and certification-driven premiums.
- Chemical Production:Chlor-alkali electrolysis consumes salt as the sole sodium and chlorine ion source, with membrane cell technology upgrades forcing purity thresholds upward. Integrated producers with captive brine reserves in Gujarat and Saskatchewan control cost structures unavailable to merchant purchasers.
- Water Treatment:Ion exchange regeneration for industrial boilers and municipal softening systems. US EPA Clean Water Act chloride discharge limits in coastal states push operators toward higher-efficiency formulations that reduce downstream environmental loading.
- De-icing:Highway and airport runway maintenance with weather-dependent demand volatility.
- Food Processing:Curing, preservation, and flavoring applications requiring food-grade certification.
Chemical production anchors revenue concentration; water treatment shows the steepest expansion trajectory.
End User:
Manufacturing and pharmaceutical buyers impose stringent purity documentation, while mining and agriculture absorb lower-specification material at volume discounts.
- Manufacturing:Chlor-alkali, fluorochemical, and synthetic rubber producers requiring consistent feedstock chemistry. EU F-Gas Regulation compliance documentation now mandates certified trace element thresholds for hydrofluoric acid catalyst protection.
- Pharmaceuticals:Dialysis solution and intravenous saline manufacturing with USP/EP-grade purity requirements. Long-term supply contracts with dedicated purification investments isolate this segment from commodity price cycles.
- Mining:Ore processing and dust suppression with tolerance for higher insoluble content.
- Agriculture:Fertilizer manufacturing and livestock feed supplementation.
Manufacturing dominates procurement volumes; pharmaceuticals delivers the highest margin per ton.
Distribution Channel:
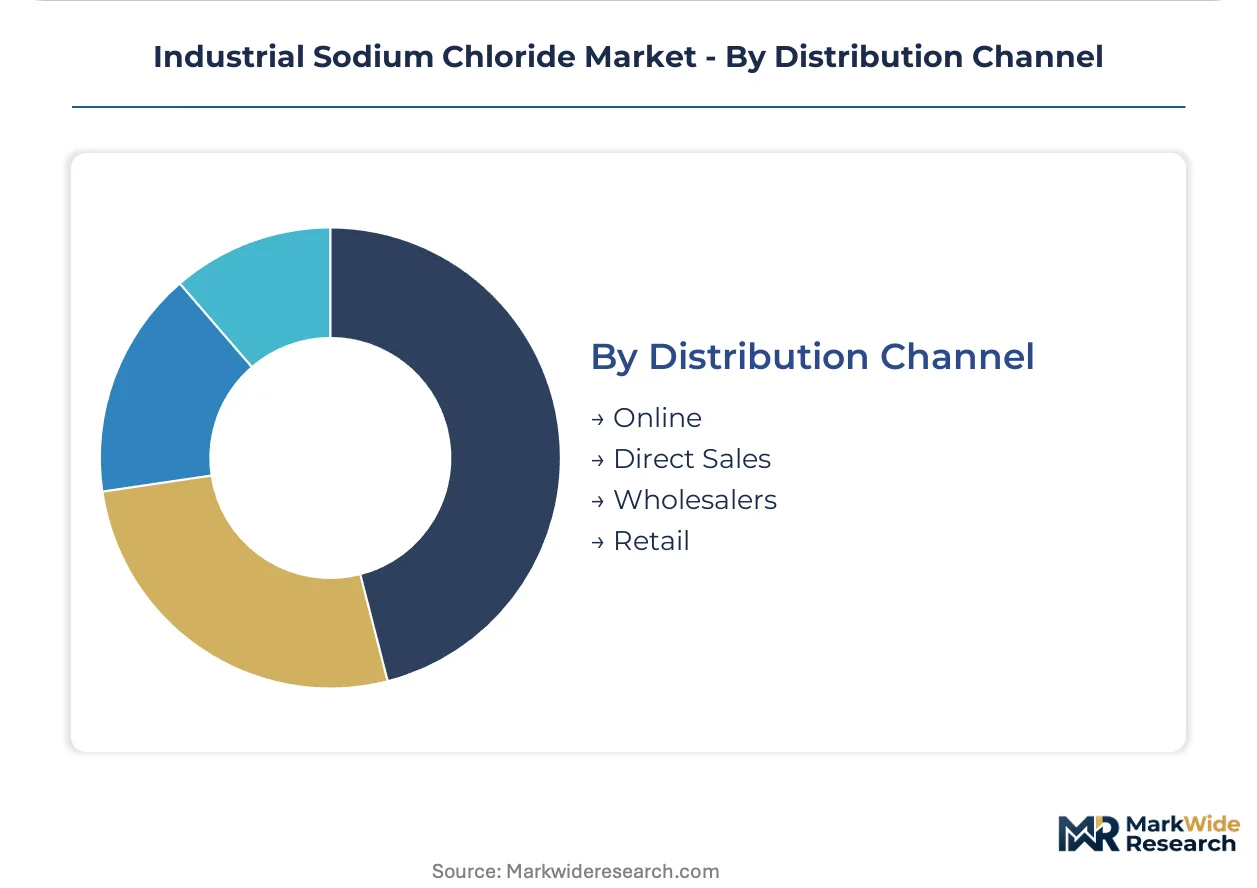
Direct sales and wholesaler networks control industrial bulk flows, while online and retail channels fragment small-lot purchasing with higher logistics overhead.
- Direct Sales:Mine-to-plant contracts for chlor-alkali and water treatment operators with dedicated logistics infrastructure. K+S and Tata Chemicals anchor European and Indian procurement through integrated port terminals and rail spurs.
- Wholesalers:Regional distributors aggregating de-icing and agricultural demand across seasonal buying patterns.
- Online:E-procurement platforms for specialty grades and spot purchasing.
- Retail:Packaged consumer and small commercial quantities through hardware and agricultural supply stores.
Direct sales channels capture the majority of industrial tonnage; online platforms are expanding most quickly in specialty grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and process technicians cluster around chlor-alkali corridors in Germany, China, and the US Gulf Coast, anchoring regional production networks.
United States
Chlor-alkali membrane cell operators along the Gulf Coast consume high-purity salt for caustic soda and chlorine derivatives. EPA Clean Water Act chloride discharge limits tighten specifications for water treatment salt formulations. The Texas-Louisiana chemical processing belt concentrates procurement volumes with integrated producers controlling dedicated logistics infrastructure.
China
State-backed capacity expansions in the coastal processing belt reshape procurement patterns for chemical-grade feedstock. SAMR enforces GB/T 5462 standards for industrial salt quality, creating compliance barriers for imported material. The Yangtze River Delta chemical parks favor suppliers with documented purity certifications and captive brine reserves.
Germany
EU F-Gas Regulation tightening drives certified high-purity salt demand from fluorochemical manufacturers preventing catalyst poisoning. REACH registration requirements constrain hydrofluoric acid producers to documented trace element thresholds. The North Rhine-Westphalia chlor-alkali network responds with backward integration into captive brine processing and dedicated purification investments.
India
Tata Chemicals leverages captive brine reserves in Gujarat to sustain cost leadership in bulk chemical feedstock supply. BIS quality standards and state-level environmental clearances regulate solar evaporation operations. The Gujarat chemical processing corridor anchors procurement concentration for domestic chlor-alkali and water treatment operators.
Canada
Rock salt mining operations in Saskatchewan and Alberta serve North American de-icing and chemical manufacturing demand. Environment Canada effluent guidelines constrain brine disposal from conventional extraction methods. The Prairie Provinces concentrate mine-to-port logistics for bulk export to US Midwest chemical processors.
Industrial Sodium Chloride Market Competitive Environment
Capital-heavy producers compete with asset-light traders across distinct supply chain positions. The vendor base organizes around three strategic archetypes: integrated miners with captive reserves, regional evaporators serving seasonal de-icing contracts, and specialty purifiers targeting pharmaceutical-grade specifications. Consolidation pressures concentrate procurement volumes with backward-integrated suppliers controlling mine-to-port logistics. Competitive moves center on multi-year offtake contracting and geographic expansion into state-backed chemical park zones.
Within the integrated mining tier, K+S Aktiengesellschaft and Tata Chemicals exemplify archetypes of deep vertical control from subterranean extraction through dedicated port terminals. INEOS occupies a position bridging European chlor-alkali networks with integrated salt sourcing for supply continuity. These three anchors represent distinct geographic concentrations: German mine-to-port dominance, Indian captive brine leverage, and European chemical network integration.
| Leading Market Players |
|---|
| Tata Chemicals |
| INEOS |
| Cargill Incorporated |
| ICL Group |
| Cheetham Salt |
| K+S Aktiengesellschaft |
| China National Salt Industry Corporation |
| Nouryon |
| Compass Minerals International |
| Others |
Value Chain & Pricing Dynamics
Natural gas futures pricing cascades through vacuum evaporation economics into three-tier pricing structure across premium, standard, and economy levels, with membrane-compatible granular grades commanding sustained premiums over commodity powder feedstock.
Pricing Analysis
Contract logistics bundling separates mine-to-port integrated suppliers from merchant traders competing on spot purity differentials. Price differentiation hinges on GB/T 5462 certification tier and captive brine reserve access, with energy cost volatility compressing margins for vacuum-evaporated flake producers. Pricing pressure stems from brine disposal compliance costs in coastal manufacturing zones. Chlor-alkali operators show lowest price sensitivity due to membrane cell protection requirements, while seasonal de-icing procurement exhibits acute spot-market reactivity.
Supply Chain Analysis
Inland freight costs from Saskatchewan and Gujarat extraction hubs to coastal chemical parks constitute 15-25% of delivered cost for bulk consumers. Supply concentrates in China, Germany, and India, with rock salt mining drawing from geological reserves and solar evaporation feeding from captive brine ponds. Single-source vulnerability runs through Yangtze River Delta chemical park dependency on certified domestic supply. Distribution runs through direct mine-to-plant contracts with dedicated rail spurs and port terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial sodium chloride market functions as a stable compounder anchored by chlor-alkali membrane cell technology upgrades that perpetually tighten purity thresholds and lock in premium-grade demand.
For Market Incumbents: Anticipate calcium magnesium acetate substitution in environmentally sensitive highway corridors by securing multi-year de-icing contracts with weather-risk sharing clauses. Backward integration into captive brine reserves in Gujarat or Saskatchewan insulates margin structures from energy cost volatility that merchant evaporators cannot absorb. For New Entrants and Emerging Players: Capture pharmaceutical-grade purification white space in dialysis and intravenous solution manufacturing where USP/EP certification barriers limit incumbent expansion. Target water treatment efficiency formulations in US coastal states facing EPA chloride discharge tightening, deploying direct sales teams with technical brine optimization expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier regional evaporators holding GB/T 5462 documentation and rail-served coastal terminal access in China's chemical processing belt. Long-term viability rests on membrane cell feedstock positioning rather than commoditized de-icing exposure. Watch for SAMR enforcement actions against uncertified imports as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Brine | Gujarat and Saskatchewan reserve control eliminates merchant salt price exposure for chlor-alkali networks. |
| Long-term Supply Agreement | Multi-year offtake contracts with membrane cell operators secure volume commitments through energy price cycles. |
| Pharmaceutical-grade Certification Investment | USP/EP purification capabilities unlock dialysis solution margins unavailable to commodity producers. |
| Joint Venture in Chemical Park Zones | Partnerships with state-backed Yangtze River Delta expansions guarantee GB/T 5462-compliant market access. |
| Green Manufacturing Transition | Solar evaporation expansion in Rajasthan reduces natural gas dependency and carbon intensity disclosures. |
Study Parameters
Direct dialogue with chlor-alkali plant managers, chemical procurement leads at fluorochemical manufacturers, solar evaporation operators, and water treatment facility engineers grounded qualitative assessment in operational reality. Secondary validation drew from SAMR GB/T 5462 enforcement records, EPA Clean Water Act discharge permit databases, EU ECHA REACH registration filings, and customs trade flow data. Bottom-up capacity modeling and top-down demand triangulation reconciled volume estimates across the analysis window.
Segment-level outputs reflect grade tier, end-use industry, and regional production hub dimensions modeled across the projection horizon. CAGRs derived from electrolyzer capacity expansion pipelines, membrane cell retrofit schedules, and chemical park investment announcements. Forecast inputs incorporated natural gas price scenarios and brine disposal regulatory trajectory assumptions.
Energy cost volatility, SAMR import certification enforcement, and membrane cell technology substitution are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EU F-Gas Regulation implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Global and US Inorganic Salt Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Solar Salt Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Europe Frac Sand Market