
 Polish Water Treatment Chemicals Market | 2026-2036
Polish Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Polish Water Treatment Chemicals Market Analytics
Membrane-compatible chemical formulations is tilting the technology stack away from legacy aluminum sulfate toward polymer-based coagulants and customized flocculant blends. BASF SE leverages its Ludwigshafen R&D pipeline to supply advanced polyacrylamide grades tailored to Polish membrane filtration installations. Kemira sustains strong positioning through backward integration into monomer production, securing feedstock cost advantages for its Gdansk-area operations. PCC Rokita anchors significant local manufacturing scale, dominating regional supply chains for chlorine-derived disinfectants and pH adjustment chemicals.
Water treatment chemicals encompass formulated substances engineered to remove suspended solids, control microbial contamination, and regulate acidity in water systems, with polyaluminum chloride typically containing 10-12% aluminum oxide by weight and cationic polyacrylamides carrying charge densities between 10-60% for targeted flocculation performance. Coagulants and flocculants command the largest share of product-type revenue due to universal deployment across both municipal and industrial treatment trains. Disinfectants represent the fastest-expanding product category as ozone and UV-chlorine hybrid systems gain traction in Polish drinking water plants upgrading to EU-mandated pathogen limits. Industrial grade chemicals generate the highest volume throughput, though food grade specifications capture superior margin pools from beverage and dairy processing applications.
Poland's water treatment sector operates under the Polish Ministry of Infrastructure's drinking water quality oversight, supplemented by EU Drinking Water Directive harmonization and REACH chemical registration requirements enforced by ECHA. These frameworks mandate stricter maximum contaminant levels for lead, microplastics, and disinfection byproducts, directly expanding demand for advanced coagulation and activated carbon pairing solutions. Stakeholders must monitor how impending EU pharmaceutical-grade water standards reshape specification requirements for boiler and cooling applications in Polish pharmaceutical manufacturing clusters.
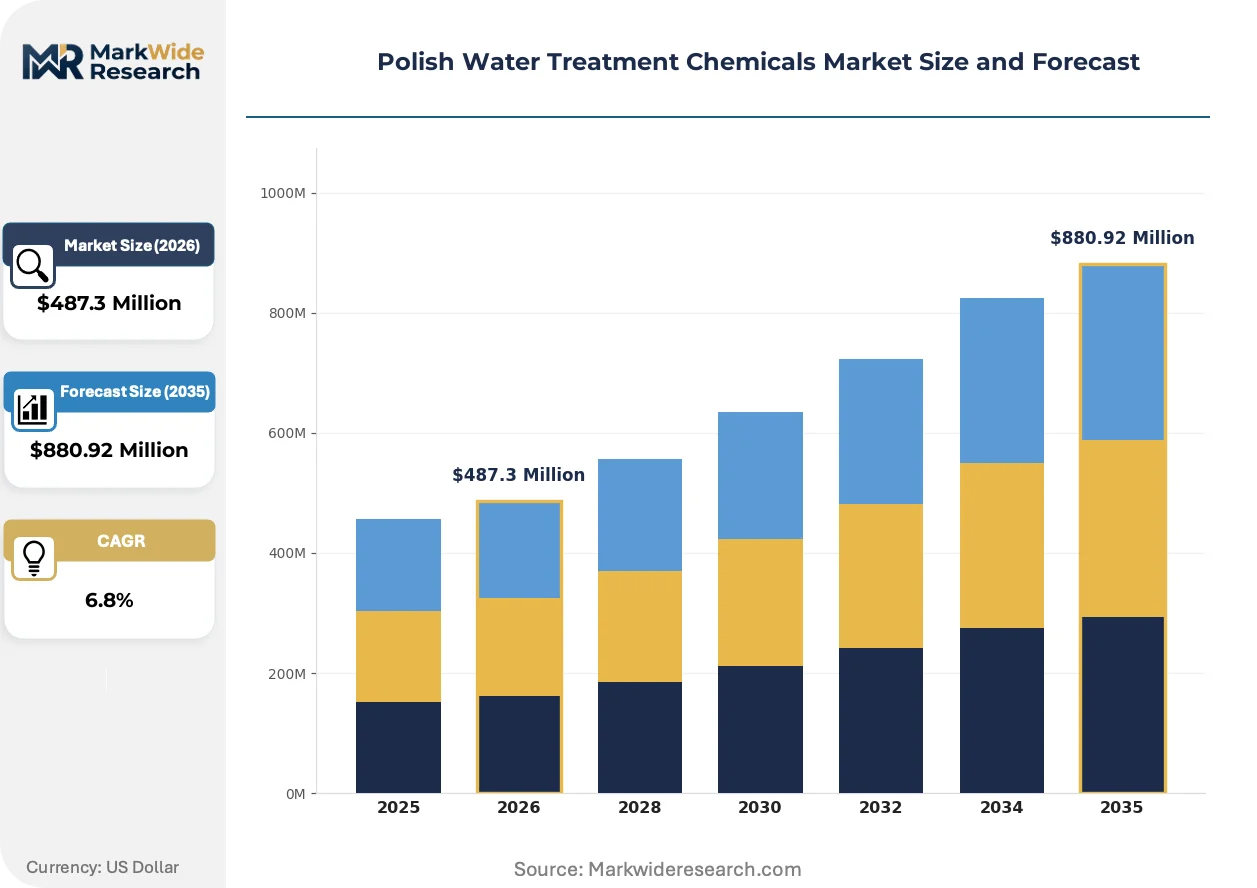
Market Dynamics
Membrane filtration retrofits across Polish municipal plants are forcing coagulant chemistry reformulation, as polyaluminum chloride and ferric salts must perform within narrow pH windows compatible with hollow-fiber and ceramic membranes.
Growth Catalysts
- EU Drinking Water Directive revisions:Tightened limits on lead, microplastics, and disinfection byproducts mandate activated carbon pairing and advanced oxidation processes in Polish utilities.
- Silesian industrial corridor expansion:Steelworks and combined-cycle power plants require heavy-metal precipitation chemicals and zero-liquid-discharge chemistries.
- Pharmaceutical-grade water specifications:Boiler and cooling water treatment in Polish drug manufacturing clusters must meet impending EU pharmaceutical water standards.
Market Restraints
- Acrylamide monomer price volatility:Polyacrylamide flocculant costs fluctuate with propylene feedstock and energy pricing, compressing margins for formulated blends.
- Chlor-alkali supply concentration:Chlorine-derived disinfectants depend on electrolysis capacity concentrated in northwestern Poland, creating geographic vulnerability.
- Membrane fouling incompatibility:Legacy aluminum sulfate chemistries trigger irreversible fouling on polyethersulfone membranes, limiting retrofit options.
Strategic Opportunities
- Lesser Poland voivodeship underpenetration:Municipal treatment infrastructure lags behind Silesia and Mazovia, creating greenfield chemical specification opportunities.
- Ozone-UV hybrid disinfection:Polish plants upgrading to pathogen limits drive demand for peracetic acid and chlorine dioxide as residual disinfectants.
- Food-grade certification premium:Dairy and beverage processors in central Poland pay margin premiums for NSF/ANSI 60 certified pH adjusters and sanitizers.
Industry Challenges
- Process analytical chemistry skill gaps:Membrane-compatible dosing requires real-time charge neutralization monitoring that existing plant operators lack training to execute.
- REACH registration timelines:Novel polymer chemistries face 18-24 month ECHA evaluation delays before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polish Water Treatment Chemicals Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Adjusters Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Technical Grade End Use Industry: Municipal, Industrial, Agricultural, Residential Application: Drinking Water Treatment, Wastewater Treatment, Cooling Water Treatment, Boiler Water Treatment |
| Companies Covered | BASF SE, SUEZ, Ecolab, Kemira, Lonza, Akzo Nobel N.V., Kurita Water Industries Ltd, PCC Rokita, Veolia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polish Water Treatment Chemicals Market Evolving Landscape
Formulation science and digital dosing control are converging to displace fixed-ratio chemical feeding, enabling real-time adjustment to raw water variability that static dosing cannot match.
Polymer-based coagulants with tailored charge density profiles are rendering obsolete aluminum sulfate in membrane-equipped Polish plants. Municipal utilities in Warsaw and Krakow are adopting these formulations within 24-month retrofit cycles. The shift compresses demand for commodity alum while expanding specification work for customized flocculant blends.
REACH chemical registration requirements enforced by ECHA mandate full substance dossiers for imported treatment actives. This regulatory burden favors local formulators with established registration portfolios over new market entrants. Polish industrial end-users increasingly specify REACH-registered chemistries to avoid supply disruption risk.
Buyers are consolidating chemical procurement through multi-year framework agreements that bundle coagulants, flocculants, and disinfectants under single-supplier contracts. Municipal water utilities in Poznan and Wroclaw have moved to five-year tender structures. The model displaces spot purchasing and forces suppliers to integrate technical service capabilities into contract value.
Polish Water Treatment Chemicals Market Segmentation
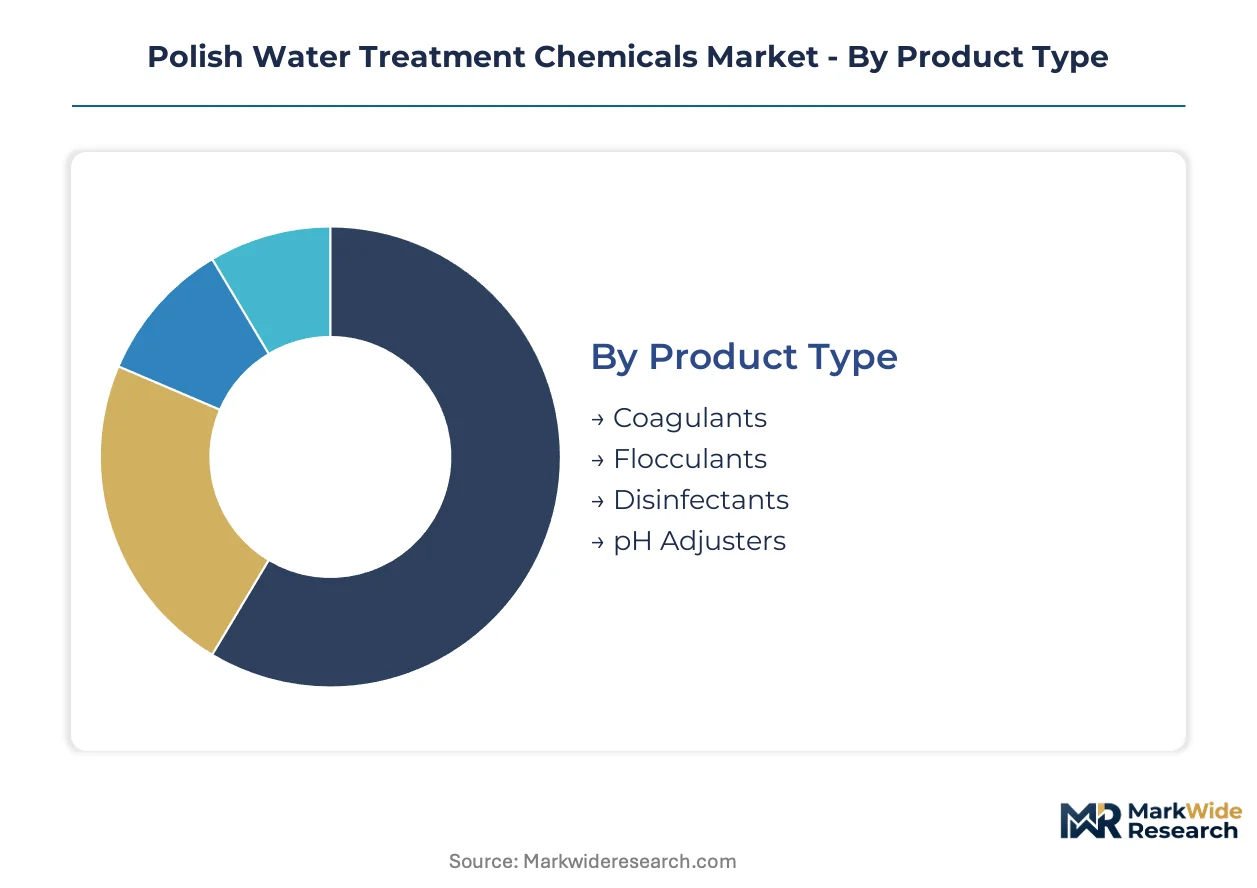
Poland's water treatment chemicals market fragments across four intersecting dimensions that determine formulation chemistry, regulatory burden, and margin capture. Product type and grade specifications dominate procurement decisions, while end-use industry and application context dictate performance thresholds and certification requirements.
Product Type:
Cost tier differentiation separates commodity chemistries from performance-engineered formulations in Polish procurement patterns.
- Coagulants:Polyaluminum chloride formulations containing 10-12% aluminum oxide by weight dominate municipal clarifier operations. Silesian steelworks and power plants drive demand for heavy-metal precipitation variants with enhanced ferric salt content.
- Flocculants:Cationic polyacrylamides carry charge densities between 10-60% for targeted particle aggregation. Membrane filtration retrofits in Warsaw and Krakow municipal plants force specification shifts toward low-fouling polymer grades compatible with hollow-fiber systems.
- Disinfectants:Chlorine-derived chemistries anchor baseline microbial control, though ozone-UV hybrid systems gain traction in EU Directive-compliant upgrades.
- pH Adjusters:Sulfuric acid and caustic soda volumes track industrial cooling tower and boiler feedwater specifications across Polish manufacturing clusters.
Coagulants and flocculants command the established base. The steepest expansion runs through disinfectants as pathogen limit tightening accelerates.
Grade:
Application context determines purity thresholds, with certification requirements fragmenting supply relationships and margin structures.
- Industrial Grade:Highest volume throughput serves steel, power, and chemical manufacturing across the Silesian corridor. REACH registration requirements enforced by ECHA mandate full substance dossiers, favoring established Polish formulators over import-dependent competitors.
- Food Grade:NSF/ANSI 60 certified pH adjusters and sanitizers capture superior margins from dairy and beverage processors in central Poland. Certification overhead creates procurement stickiness and multi-year framework contracting.
- Pharmaceutical Grade:Impending EU pharmaceutical water standards reshape boiler and cooling specifications for Polish drug manufacturing clusters.
- Technical Grade:General-purpose formulations serve non-critical industrial applications with reduced documentation burden.
Industrial grade maintains volume leadership. Food grade climbs the fastest on certification premium capture.
End Use Industry:
Customer type concentration shapes technical service intensity and contract duration across the Polish market.
- Municipal:Water utilities in Poznan and Wroclaw consolidate procurement through five-year framework agreements bundling coagulants, flocculants, and disinfectants. EU Drinking Water Directive revisions tighten lead, microplastic, and disinfection byproduct limits, expanding activated carbon pairing requirements.
- Industrial:Steelworks and combined-cycle power plants in the Silesian corridor require zero-liquid-discharge chemistries and heavy-metal precipitation systems. Process analytical chemistry skill gaps constrain membrane-compatible dosing adoption.
- Agricultural:Irrigation water treatment and livestock operation sanitization drive seasonal demand patterns with lower specification barriers.
- Residential:Point-of-use and point-of-entry systems represent fragmented, price-sensitive demand with limited formulation customization.
Municipal utilities anchor the installed base. Industrial applications gain share fastest on corridor expansion and environmental compliance tightening.
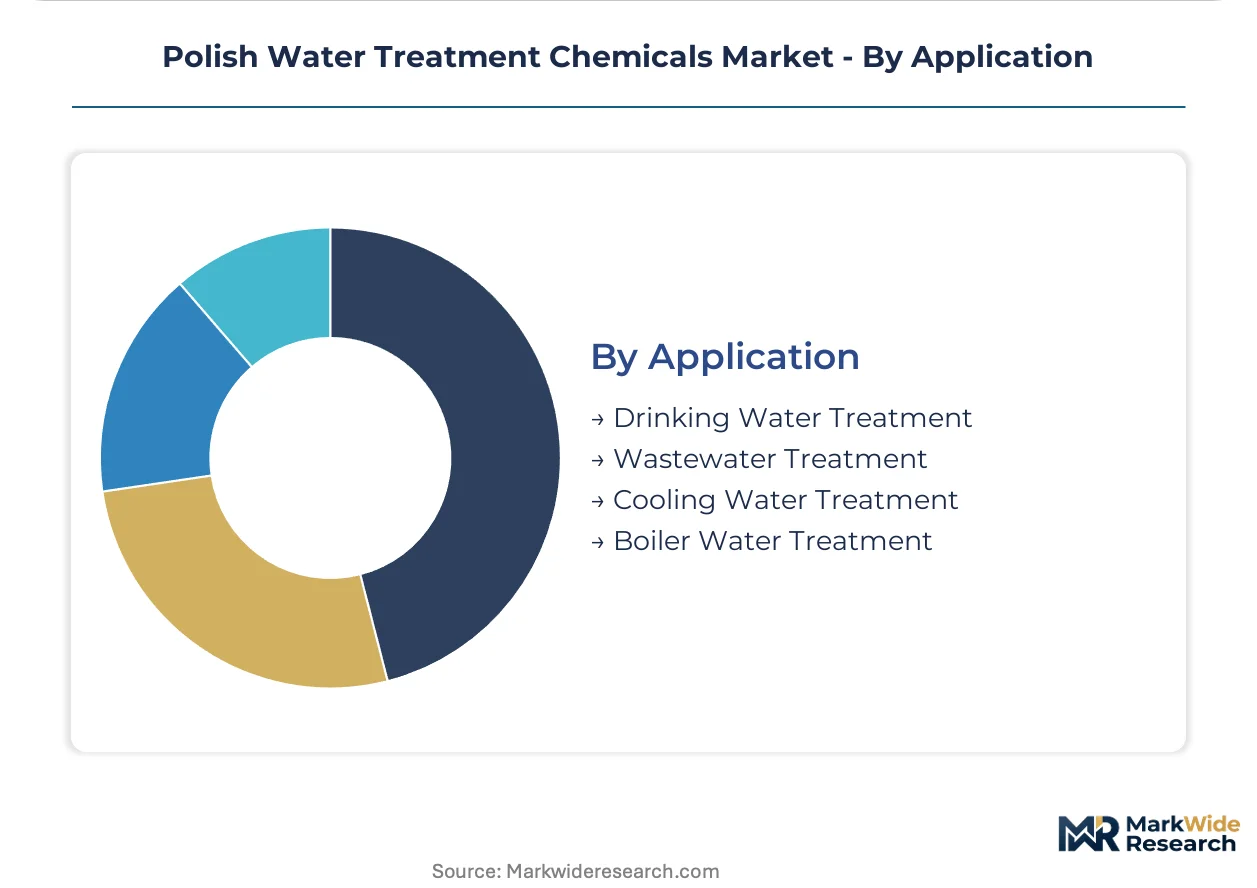
Application:
Volume scale and performance requirements diverge sharply across treatment contexts, with membrane compatibility emerging as the critical specification filter.
- Drinking Water Treatment:Polish plants upgrading to EU-mandated pathogen limits deploy advanced oxidation processes and activated carbon pairing. Membrane filtration retrofits force coagulant chemistry reformulation within narrow pH windows.
- Wastewater Treatment:Industrial effluent standards drive demand for customized flocculant blends in Silesian heavy industry clusters. Biological nutrient removal requirements expand polymer specification complexity.
- Cooling Water Treatment:Scale inhibition and corrosion control formulations serve power generation and manufacturing infrastructure across Lesser Poland and Mazovia.
- Boiler Water Treatment:Pharmaceutical manufacturing clusters face impending EU pharmaceutical-grade water specifications for steam and process applications.
Wastewater treatment holds the volume base. Drinking water applications expand most quickly on Directive compliance investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's water treatment chemicals trade flows reflect a structural deficit in specialized polymer formulations, with domestic production concentrated in chlorine derivatives and commodity coagulants while advanced flocculants and membrane-compatible grades enter through northwestern European supply corridors.
Silesian Voivodeship
Steelworks and combined-cycle power plants in Katowice and Gliwice drive heavy-metal precipitation chemical consumption. The Polish Ministry of Infrastructure enforces industrial effluent standards that mandate zero-liquid-discharge chemistries for large emitters. Municipal utilities in the Upper Silesian metropolitan area are retrofitting clarifiers with polyaluminum chloride systems to meet EU Drinking Water Directive pathogen limits.
Mazovia
Warsaw's municipal water authority consolidates five-year framework procurement contracts bundling coagulants, flocculants, and disinfectants. ECHA REACH registration requirements favor established Polish formulators with complete substance dossiers over import-dependent competitors. The Warsaw agglomeration's membrane filtration retrofits force specification shifts toward low-fouling polymer grades compatible with hollow-fiber systems.
Lesser Poland
Krakow's municipal treatment infrastructure lags Silesia and Mazovia in chemical sophistication, creating greenfield specification opportunities for advanced oxidation process chemicals. The EU Drinking Water Directive's tightened disinfection byproduct limits expand activated carbon pairing requirements. Dairy and beverage processors in the Krakow-Tarnow corridor pay margin premiums for NSF/ANSI 60 certified pH adjusters and sanitizers.
Pomerania
Gdansk-area chemical manufacturing anchors regional supply chains for chlorine-derived disinfectants and pH adjustment chemicals. Chlor-alkali electrolysis capacity concentrated in northwestern Poland creates geographic supply vulnerability for utilities in the Baltic corridor. Kemira's backward integration into monomer production secures feedstock cost advantages for its Pomeranian operations serving municipal and industrial accounts.
Polish Water Treatment Chemicals Market Competitive Landscape
On the supply side, the industry is tiered between integrated chemical majors with captive monomer production and regional formulators dependent on imported active ingredients. European-headquartered multinationals leverage R&D pipelines to supply advanced polyacrylamide grades, while Polish domestic producers dominate commodity disinfectants and pH adjusters through chlor-alkali integration. Three archetypes define competitive positioning: integrated polymer producers, regional chlorine specialists, and water services conglomerates bundling chemicals with equipment. Capacity expansion in Gdansk-area monomer production and multi-year municipal framework contracting represent the dominant competitive moves reshaping supply relationships.
Within the integrated polymer tier, BASF SE and Kemira exemplify players leveraging backward integration into upstream monomer production to secure formulation cost positions. PCC Rokita occupies a position as the dominant regional chlorine specialist, anchoring supply chains for disinfectants through captive electrolysis capacity. These three companies represent the supply-side concentration that ECHA REACH registration timelines reinforce, as established registration portfolios create barriers against new market entrants facing 18-24 month evaluation delays.
| Leading Market Players |
|---|
| BASF SE |
| SUEZ |
| Ecolab |
| Kemira |
| Lonza |
| Akzo Nobel N.V. |
| Kurita Water Industries Ltd |
| PCC Rokita |
| Veolia |
| Others |
Value Network & Pricing Analysis
The Baltic freight corridor connecting Gdansk-area chlor-alkali production to Silesian industrial consumers shapes cost dynamics across Poland's water treatment chemicals market. Concentrated electrolysis capacity in northwestern Poland generates pricing power for chlorine-derived disinfectants while forcing downstream buyers to absorb elevated logistics costs for membrane-compatible polymer formulations sourced from northwestern European supply corridors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Poland's water treatment chemicals procurement. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 60 certified food-grade formulations from technical-grade commodities. Cost compression in standard-grade polyacrylamides is intensifying because acrylamide monomer price volatility feeds directly into formulated blend margins. Municipal utilities demonstrate lowest price sensitivity due to five-year framework agreements bundling multiple chemical categories, while residential point-of-use segments exhibit highest elasticity to per-unit pricing.
Supply Chain Analysis
Tariff exposure between Germany and Poland dominates supply chain risk calculations for advanced polymer formulations crossing the Oder-Neisse logistics corridor. Geographic supply concentration centers on Germany, the Netherlands, and domestic Polish production for chlorine derivatives. Raw material dependencies rest on propylene feedstock for acrylamide monomer production, aluminum hydroxide for polyaluminum chloride synthesis, and salt brine for chlor-alkali electrolysis. Single-source vulnerability characterizes hollow-fiber membrane-compatible polymer grades. Distribution runs through regional chemical distributors serving municipal utilities and direct mill-to-plant relationships for Silesian industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities emerge across Poland's water treatment chemicals landscape as membrane filtration retrofits create specification niches incompatible with legacy supplier portfolios. EU Drinking Water Directive revisions accelerate demand for activated carbon pairing and advanced oxidation process chemicals that incumbent commodity producers cannot readily supply.
For Market Incumbents: Harden technical service capabilities around real-time charge neutralization monitoring systems that municipal operators currently lack training to execute. Deepen backward integration into monomer production to offset propylene feedstock volatility compressing polyacrylamide margins. Capacity addition in Lesser Poland voivodeship addresses geographic vulnerability to chlor-alkali supply concentration in northwestern Poland. For New Entrants and Emerging Players: Establish a beachhead in membrane-compatible polymer formulations for Warsaw and Krakow municipal retrofits where specification windows remain open. Lesser Poland voivodeship offers the most penetrable geography given lagging treatment infrastructure sophistication relative to Silesia and Mazovia. Go-to-market execution should emphasize REACH registration completion ahead of ECHA evaluation timelines that delay commercial deployment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with water treatment divisions lacking membrane filtration formulation expertise. Long-term viability across the analysis window favors specialists with captive monomer production and established ECHA registration portfolios over import-dependent commodity traders. Watch ECHA evaluation acceleration for novel polymer chemistries as the inflection signal indicating regulatory pathway clarity for advanced formulation entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Kemira's Gdansk-area captive acrylamide supply secures cost advantages against propylene volatility. |
| REACH Registration Portfolio Expansion | ECHA substance dossiers create 18-24 month barriers protecting established Polish formulators from import competition. |
| Membrane-Compatible Formulation Development | BASF's Ludwigshafen R&D pipeline supplies polyacrylamide grades tailored to hollow-fiber retrofit specifications. |
| Multi-Year Framework Contracting | Poznan and Wroclaw municipal utilities bundle coagulants, flocculants, and disinfectants under single-supplier agreements. |
| Food-Grade Certification Investment | NSF/ANSI 60 certification captures margin premiums from central Poland dairy and beverage processors. |
Research Methodology
A standing panel of municipal water utility procurement managers, Silesian steelworks environmental compliance officers, pharmaceutical manufacturing facility engineers, and regional chemical distribution channel heads provided ongoing calibration across the study period. Primary interviews with plant operators and technical R&D directors combined with secondary validation from Polish Ministry of Infrastructure regulatory filings, ECHA REACH registration databases, customs and trade flow records, and SEC 10-K disclosures of listed chemical majors. Bottom-up volume modeling triangulated against top-down market sizing derived from end-use industry consumption patterns.
Scenario-bracketing framed analytical development across the projection horizon. Segmentation dimensions modeled include product type tier, grade specification, end-use industry concentration, and regional voivodeship demand clusters. CAGRs were derived from historical trajectory analysis adjusted for regulatory compliance investment cycles and membrane retrofit adoption curves. Forecast inputs incorporated EU Drinking Water Directive implementation timelines and chlor-alkali capacity utilization rates at northwestern Polish production facilities.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, propylene pricing, and Baltic freight rates would shift the trajectory. Forecasts reflect underlying assumptions about regulatory enforcement intensity and membrane technology diffusion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
US Liquid Waste Management Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market