
 Coating Removal System Market | 2026-2036
Coating Removal System Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Removal System Market Analytics
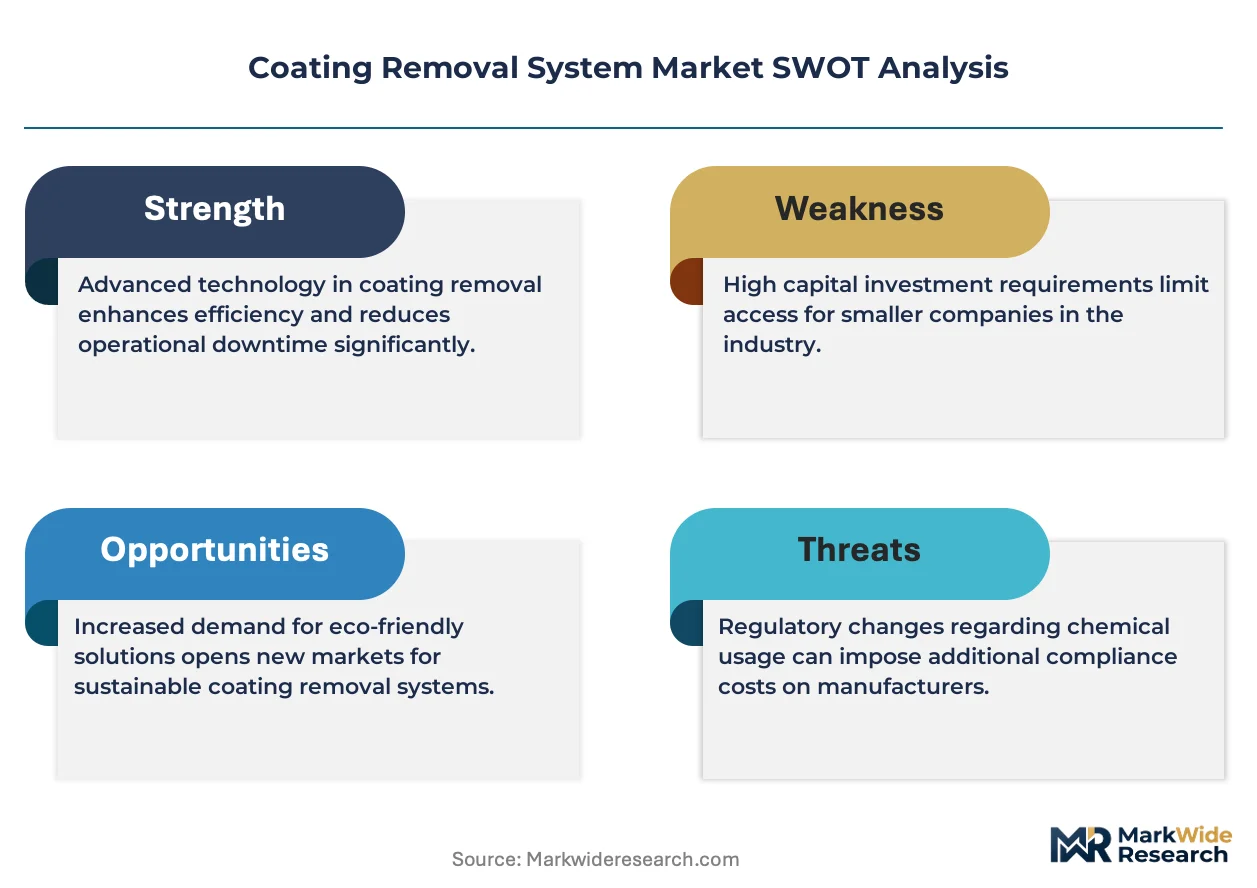
Buyer consolidation among aerospace maintenance, repair, and overhaul providers is repositioning procurement power toward large fleet operators. PPG Industries sustains its position through captive supply of aerospace-grade stripping chemistries. Henkel AG & Co. KGaA differentiates via R&D intensity in solvent-free gel formulations. 3M Company leverages vertical integration into abrasive media production for controlled substrate removal.
Coating removal systems encompass equipment and consumables engineered to strip paints, primers, and protective layers from metal, composite, and concrete substrates without structural damage, typically operating at pressures between 5,000 and 40,000 PSI for waterjet methods or wavelengths of 1,064 nanometers for Nd:YAG laser systems. Their primary industrial purpose centers on surface preparation for re-coating, corrosion remediation, and compliance with substrate inspection protocols. Abrasive blasting occupies the largest installed base across automotive refurbishment and marine repair yards, while laser systems capture expanding share in aerospace maintenance where substrate integrity demands precision. Chemical stripping retains margin concentration in industrial equipment restoration despite regulatory pressure on methylene chloride formulations.
The EPA restricts methylene chloride in consumer and commercial paint removal products under Section 6 of the Toxic Substances Control Act, while OSHA enforces permissible exposure limits for crystalline silica in abrasive blasting operations. The EU REACH regulation and F-Gas Regulation collectively constrain solvent-based formulations and propellant-driven systems across European manufacturing and maintenance sectors. Stakeholders must monitor regulatory phase-out timelines against capital investment cycles for alternative platform technologies.
Market Dynamics
Laser ablation technology is displacing abrasive blasting in aerospace maintenance hangars where substrate integrity demands precision, while REACH chemical restrictions are forcing rapid equipment replacement cycles across European industrial clusters.
Growth Catalysts
- Aerospace MRO expansion:Fleet operators in Germany and France are mandating laser-based stripping for composite airframe inspection protocols, creating pull-through demand for precision removal equipment.
- EPA methylene chloride ban:The Toxic Substances Control Act Section 6 prohibition on solvent-based consumer and commercial paint removers is redirecting demand toward mechanical and thermal alternatives.
- Corrosion remediation mandates:Bridge infrastructure authorities in Japan and Australia are specifying high-pressure waterjet systems for rebar exposure without substrate damage.
Market Restraints
- Capital intensity barrier:Nd:YAG laser systems require upfront investment multiples above abrasive blasting rigs, constraining adoption among independent automotive refurbishers.
- Input cost volatility:Garnet and aluminum oxide abrasive media prices fluctuate with mining output from Australian and Indian deposits, compressing margins for blasting service providers.
- Technical throughput limits:Laser stripping operates at surface removal rates an order of magnitude below mechanical methods, restricting viable application to high-value precision substrates.
Strategic Opportunities
- Wind turbine blade maintenance:Offshore installations in the North Sea corridor are emerging as a greenfield application for robotic laser systems that eliminate silica exposure.
- EU F-Gas Regulation phase-down:The propellant-driven coating removal segment faces forced technology transition, opening share capture for electric-powered alternatives.
- China dual carbon goals:Domestic shipyards are piloting closed-loop waterjet recycling systems to meet MEE wastewater discharge standards.
Industry Challenges
- Laser safety certification timelines:IEC 60825 compliance documentation for Class 4 industrial laser systems extends equipment qualification cycles by 8-14 months.
- Multi-substrate process integration:Maintenance facilities operating across aluminum, titanium, and carbon fiber fleets must qualify distinct removal parameters for each material class.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Removal System Market |
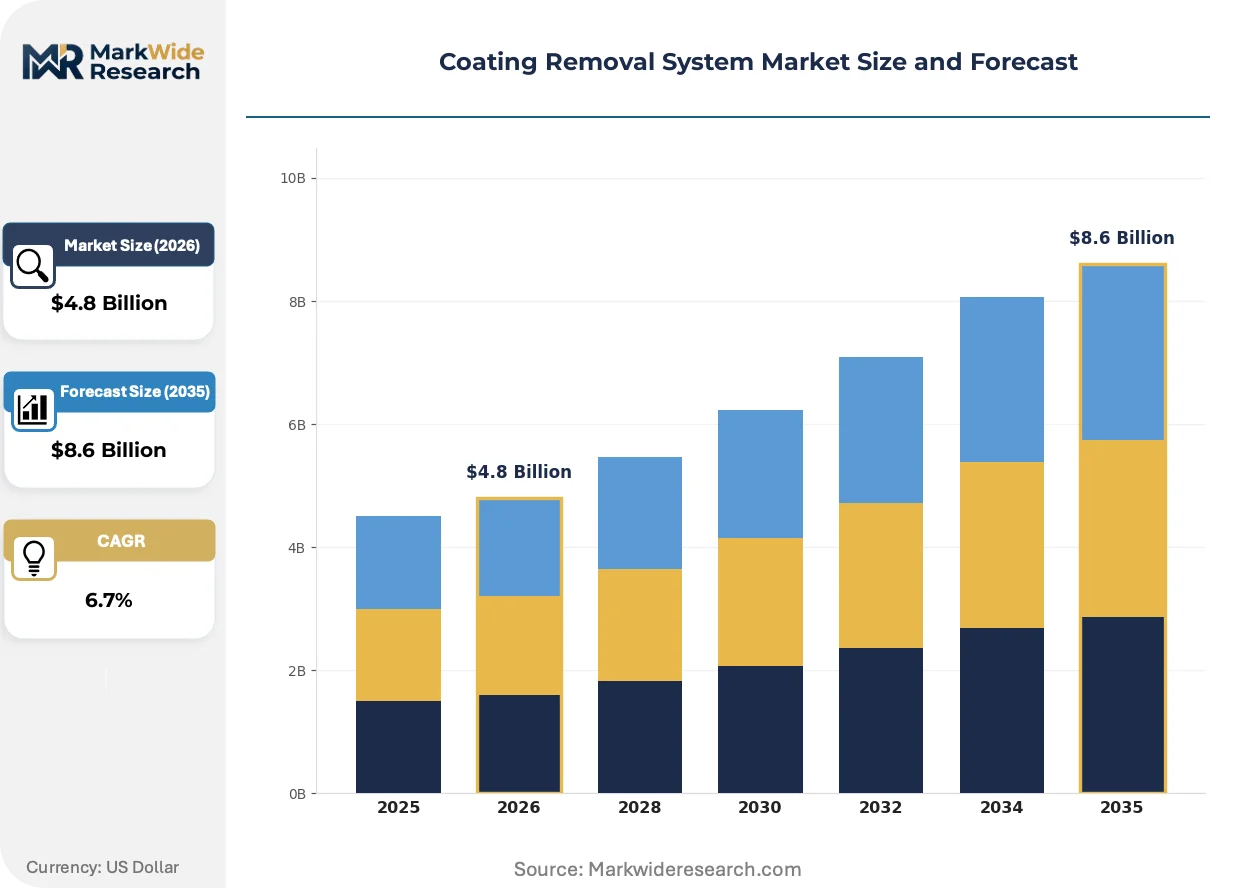
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Abrasive Blasting, Chemical Stripping, Laser Systems, Waterjet Cutting Technology: Ultrasonic Cleaning, Conventional Abrasives, Solvent-Based Systems, Plasma Removal Application: Automotive Refurbishment, Aerospace Maintenance, Marine Repairs, Industrial Equipment End User: Manufacturers, Maintenance Providers, Contractors, DIY Enthusiasts |
| Companies Covered | 3M Company, PPG Industries, Inc., Henkel AG & Co. KGaA, Absolute Coatings, Rust-Oleum, Fiberlock Technologies, United Gilsonite Labs, Changsha Guterui, DOMIN Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Removal System Market Evolving Landscape
Equipment manufacturers are converging robotic positioning systems with real-time substrate monitoring to automate precision removal. This convergence is compressing labor dependency while elevating capital intensity across maintenance operations.
Robotic laser stripping platforms equipped with LIBS (laser-induced breakdown spectroscopy) sensors are electrifying the aerospace MRO segment. Lufthansa Technik and ST Engineering hangars are deploying these systems for selective primer removal on Boeing 787 and Airbus A350 composite structures. The technology is electrifying competitive positioning by enabling single-operator cells that previously required three-person blasting teams.
REACH authorization requirements for methylene chloride and N-methyl-2-pyrrolidone are eliminating solvent-based stripping from European automotive refinishing. German and Italian collision repair chains are retrofitting thermal fluidized bed systems for wheel and component stripping. The regulation is compressing the viable technology set to waterjet, laser, and thermal methods across the EU industrial corridor.
Airlines with consolidated fleets are unbundling coating removal from full-service MRO contracts and awarding directly to specialized stripping providers. This disintermediation is visible most acutely in the US Southeast maintenance cluster, where Delta and American have established captive stripping operations at their Atlanta and Dallas-Fort Worth facilities. The shift is elevating equipment utilization rates for high-capacity automated systems while marginalizing job-shop blasting operators.
Coating Removal System Market Segmentation
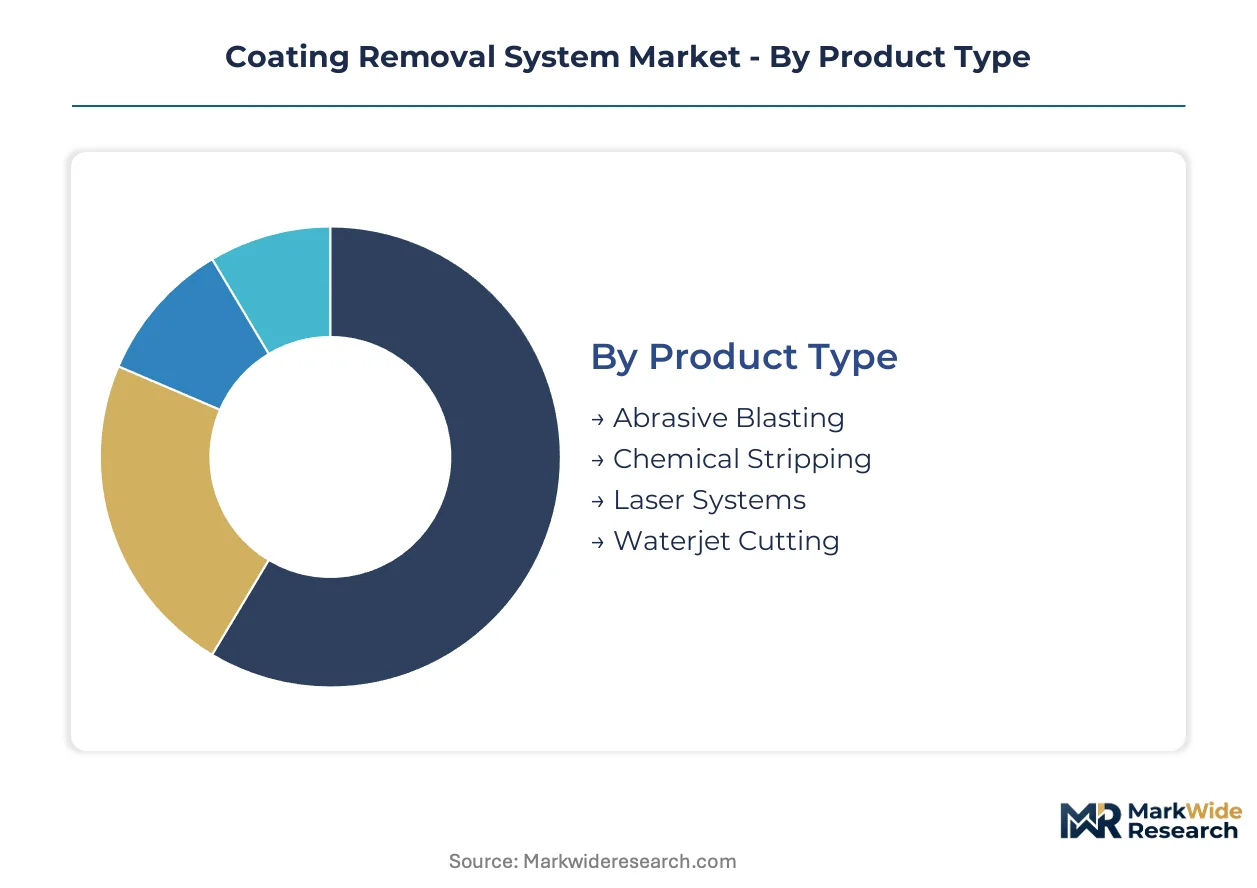
Coating removal procurement patterns diverge sharply across substrate sensitivity requirements and regulatory exposure. Buyers select platforms based on capital availability, throughput demands, and compliance constraints rather than surface area alone.
Product Type:
Buyers differentiate primarily by precision tolerance versus throughput economics, with aerospace and infrastructure authorities occupying opposite ends of this spectrum.
- Abrasive Blasting:Garnet and aluminum oxide media propelled at 5,000-40,000 PSI dominate automotive refurbishment and marine repair yards. Japanese bridge authorities specify these systems for rebar exposure without concrete spalling.
- Laser Systems:Nd:YAG platforms operating at 1,064 nanometers enable selective ablation on Boeing 787 and Airbus A350 composite structures. German fleet operators mandate this technology for airframe inspection protocols where substrate integrity is paramount.
- Chemical Stripping:Solvent-based formulations face EPA Section 6 prohibitions on methylene chloride in US consumer and commercial applications. REACH authorization requirements are eliminating N-methyl-2-pyrrolidone from European automotive refinishing.
- Waterjet Cutting:High-pressure pure water and abrasive-laden streams serve corrosion remediation on infrastructure. Chinese shipyards pilot closed-loop recycling configurations to meet MEE wastewater discharge standards.
Abrasive blasting leads volumes today; laser systems are gaining share fastest.
Technology:
Technology selection tracks regulatory phase-out timelines against equipment replacement cycles, with European industrial clusters facing the most compressed transition windows.
- Ultrasonic Cleaning:Cavitation-based systems remove coatings from precision components without mechanical abrasion. Medical device and electronics manufacturers deploy these for delicate substrate preparation.
- Conventional Abrasives:Silica sand alternatives face OSHA permissible exposure limits for crystalline silica. Australian and Indian garnet mining output volatility compresses service provider margins.
- Solvent-Based Systems:Methylene chloride and N-methylpyrrolidone formulations retain margin concentration in industrial equipment restoration despite regulatory pressure. Thermal fluidized bed retrofits are displacing these in German collision repair chains.
- Plasma Removal:Thermal plasma torches strip refractory coatings from turbine blades and industrial furnaces. Aerospace engine overhaul facilities qualify these for nickel-based superalloy substrates.
Conventional abrasives dominate installed base; ultrasonic cleaning climbs the fastest.
Application:
Application segmentation reflects divergent substrate portfolios, with composite-intensive aerospace operations demanding fundamentally different removal physics than steel-heavy marine repair.
- Aerospace Maintenance:MRO hangars in Germany and France deploy robotic laser platforms with LIBS sensors for selective primer removal. Lufthansa Technik operates single-operator cells that replaced three-person blasting teams.
- Automotive Refurbishment:Collision repair chains across Italy and Germany retrofit thermal stripping systems as REACH eliminates solvent options. Independent refurbishers face capital barriers to laser adoption.
- Marine Repairs:Shipyards specify high-pressure waterjet systems for hull preparation without damaging anti-corrosive primers. Offshore wind installations in the North Sea corridor emerge as greenfield robotic laser applications.
- Industrial Equipment:Manufacturing plants and power generation facilities require coating removal for corrosion remediation and inspection compliance. Chemical stripping retains share where geometric complexity prevents mechanical access.
Aerospace maintenance commands premium pricing; marine repair shows steepest expansion trajectory.
End User:
End user structure concentrates procurement power toward consolidated fleet operators unbundling stripping from full-service MRO contracts.
- Manufacturers:OEMs and tier suppliers operate captive stripping for production rework and quality remediation. Capital intensity favors automated systems with high utilization rates.
- Maintenance Providers:Independent MRO facilities and specialized stripping contractors serve fragmented demand across substrate classes. Technical qualification requirements for multi-material fleets constrain smaller operators.
- Contractors:Project-based service providers face input cost volatility in abrasive media and regulatory compliance documentation burdens. IEC 60825 certification timelines extend equipment qualification cycles.
- DIY Enthusiasts:Consumer segment faces EPA methylene chloride bans redirecting demand toward mechanical scraping and thermal methods. Limited to low-precision applications on residential and light commercial substrates.
Maintenance providers lead transaction volumes today; manufacturers are consolidating procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision laser system demand while the United States drives abrasive blasting volumes through infrastructure rehabilitation programs. Japan maintains specialized waterjet applications for bridge maintenance. China scales closed-loop recycling configurations in shipyard clusters.
United States
Fleet operators in the Southeast maintenance corridor unbundle stripping from full-service MRO contracts. EPA Section 6 prohibitions on methylene chloride redirect commercial demand toward mechanical and thermal alternatives. Atlanta and Dallas-Fort Worth host captive stripping operations at consolidated airline facilities.
Germany
Lufthansa Technik mandates robotic laser platforms with LIBS sensors for composite airframe inspection. REACH authorization requirements eliminate N-methyl-2-pyrrolidone from automotive refinishing chains. Collision repair operators in Baden-Württemberg and North Rhine-Westphalia retrofit thermal fluidized bed systems.
China
Domestic shipyards pilot closed-loop waterjet recycling to meet MEE wastewater discharge standards. Dual carbon goals accelerate equipment replacement cycles in coastal manufacturing zones. Yangtze River Delta facilities deploy high-pressure systems for corrosion remediation on port infrastructure.
Japan
Bridge authorities specify waterjet systems for rebar exposure without concrete spalling. METI corrosion remediation mandates elevate procurement specifications for infrastructure maintenance. Osaka and Nagoya industrial clusters concentrate abrasive media distribution networks serving Pacific maritime repair.
France
Airbus maintenance protocols in Toulouse and Paris regions drive laser ablation qualification for carbon fiber substrates. EU F-Gas Regulation phase-down constrains propellant-driven system deployment. Aerospace MRO hangars integrate automated positioning systems for selective primer removal.
Coating Removal System Market Competitive Landscape
German producers anchor the precision equipment tier; American specialists hold volume positions in abrasive media and chemical formulations. The vendor base splits between consolidated chemical conglomerates with captive aerospace supply and fragmented equipment fabricators serving regional maintenance markets. Three archetypes dominate: diversified materials conglomerates with backward integration into consumables, laser system specialists with IEC certification capabilities, and regional blasting contractors facing input cost volatility. Competitive moves concentrate on portfolio diversification away from restricted chemistries and strategic partnerships for robotic platform integration.
Within the diversified materials tier, 3M Company exemplifies backward integration into abrasive media production, while PPG Industries occupies a position tied to aerospace-grade stripping chemistry supply. Henkel AG & Co. KGaA represents the solvent-free formulation specialist archetype, anchoring R&D intensity in gel-based alternatives. These three entities collectively illustrate how competitive positioning diverges between consumables-centric and equipment-centric value capture models.
| Leading Market Players |
|---|
| 3M Company |
| PPG Industries, Inc. |
| Henkel AG & Co. KGaA |
| Absolute Coatings |
| Rust-Oleum |
| Fiberlock Technologies |
| United Gilsonite Labs |
| Changsha Guterui |
| DOMIN Chemical |
| Others |
Value Network & Pricing Analysis
Consolidated fleet operators in Germany and the United States Southeast maintenance corridor command volume-based contract structures that compress margins for independent blasting contractors while rewarding automated equipment suppliers with captive service arrangements.
Pricing Analysis
Capacity additions in Chinese shipyard clusters are reshaping price floors for waterjet system procurement, forcing European and Japanese manufacturers toward premium-mid-economy pricing differentiation based on IEC 60825 certification tiers and robotic integration depth. Price erosion runs through conventional abrasive blasting tiers due to garnet supply volatility from Australian and Indian mining deposits. Independent automotive refurbishers exhibit acute price sensitivity, while aerospace MRO providers prioritize substrate integrity guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Atlanta, and Shanghai anchor hub-and-spoke patterns for consumables fulfillment, with abrasive media inventories positioned near German automotive refinishing chains and Japanese bridge maintenance authorities. Manufacturing concentration rests on Germany for precision laser platforms, China for waterjet recycling configurations, and the United States for chemical formulation distribution. Single-source vulnerability persists in Nd:YAG laser source components sourced from Japanese optics specialists. Distribution runs through authorized equipment dealers serving captive airline stripping operations and independent contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Coating Removal System Market represents a late-cycle quality story as REACH chemical restrictions and EPA methylene chloride prohibitions redirect procurement toward certified precision equipment with documented substrate safety protocols.
For Market Incumbents: Acquire robotic positioning system capabilities to defend against specialized laser equipment fabricators entering aerospace MRO contracts. Deepen backward integration into garnet and aluminum oxide media production to offset mining output volatility compressing service provider margins. Prioritize IEC 60825 certification documentation capabilities to accelerate equipment qualification cycles against regulatory timelines. For New Entrants and Emerging Players: Direct-to-MRO digital platforms offer the lowest-friction route for thermal fluidized bed system distribution in German and Italian collision repair chains displaced by solvent bans. Target offshore wind turbine blade maintenance in the North Sea corridor as the most penetrable greenfield application for silica-free robotic laser systems. Lead with closed-loop waterjet recycling configurations to capture Chinese shipyard procurement under MEE wastewater standards. For Investors and Strategic Acquirers: Diversified materials conglomerates with captive aerospace supply relationships are the most active acquirers in this space, consolidating formulation specialists and equipment fabricators to control full-stack stripping solutions. The viable investment window extends through the technology transition cycle as regulatory phase-outs compress replacement demand. Monitor REACH authorization timelines for methylene chloride and N-methyl-2-pyrrolidone as the critical inflection signal for solvent-free technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Abrasive Media | Secures supply continuity against Australian and Indian garnet mining volatility. |
| IEC 60825 Certification Investment | Accelerates equipment qualification cycles for Class 4 laser system deployment. |
| Robotic Platform Integration Partnership | Enables single-operator cells that replace three-person blasting teams in aerospace MRO. |
| Solvent-Free Formulation R&D | Positions Henkel and comparable specialists for REACH-authorized chemistry replacement. |
| Closed-Loop Waterjet Recycling | Meets MEE wastewater discharge standards in Chinese Yangtze River Delta shipyards. |
Research Methodology
Direct dialogue with maintenance directors at Lufthansa Technik and ST Engineering, procurement leads at Delta and American Airlines captive facilities, plant managers at German collision repair chains, and aftermarket service heads at 3M and PPG anchored qualitative insights. Secondary validation drew from EPA Section 6 regulatory filings, ECHA REACH authorization databases, SEC 10-K disclosures from diversified materials conglomerates, and customs data tracking garnet and aluminum oxide import flows. Bottom-up equipment shipment analysis and top-down MRO contract value triangulation structured market sizing.
Top-down macroeconomic drivers and bottom-up segment-level demand curves converged across the projection horizon, with technology adoption curves, regulatory phase-out timelines, and fleet operator consolidation patterns as primary segmentation dimensions. CAGRs derived from equipment replacement cycle analysis against compliance deadline clustering and aerospace MRO hangar capacity expansion plans. Pricing trajectories incorporated raw material input volatility and certification premium persistence.
The model assumes a particular technology adoption path; alternative pathways for laser ablation penetration in automotive refurbishment would alter the outlook if capital intensity barriers erode faster than projected. Forecasts reflect documented assumptions regarding REACH enforcement consistency and EPA methylene chloride prohibition scope. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Micellar Cleansing Water Market