
 Industrial Standoff and Spacer Market | 2026-2036
Industrial Standoff and Spacer Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Standoff and Spacer Market Analysis
Vietnam's precision component manufacturing corridor is reshaping supply dynamics for threaded fasteners and spacing hardware. PennEngineering leverages its captive cold-heading capacity to anchor North American aerospace demand for titanium standoffs. Bossard Group sustains European market presence through vendor-managed inventory programs tied to automotive tier-one suppliers. Molex competes in the high-density electronics niche with miniature polymer spacers rated for surface-mount reflow temperatures.
Industrial standoffs and spacers are mechanical fastening elements that maintain fixed distances between panels, circuit boards, or structural assemblies, typically manufactured through cold heading, CNC turning, or injection molding to tolerances of ±0.05 mm. Their primary purpose is to prevent electrical shorting, enable thermal management, and provide structural rigidity in enclosed equipment housings. Aluminum hex standoffs dominate electronics assembly applications where weight reduction and corrosion resistance justify premium positioning over steel alternatives. Plastic spacers represent the fastest-expanding material category as flame-retardant thermoplastics displace metal in consumer electronics and LED lighting fixtures. Threaded spacers command concentrated margin pools in aerospace equipment due to material certification requirements and lot-traceability protocols.
FDA device manufacturing regulations, EU RoHS substance restrictions, and FAA airworthiness certification standards collectively constrain material selection and documentation protocols for standoff and spacer suppliers serving regulated end markets. REACH compliance costs in Europe and EPA hazardous substance reporting in the United States are redirecting procurement toward domesticated supply chains with verified material pedigrees. Stakeholders must monitor evolving PFAS restrictions and dual-use export controls as these frameworks increasingly determine qualified supplier status and contract eligibility across defense and medical device channels.
Market Dynamics
Cold-heading capacity concentration in Germany and Japan is creating supply bottlenecks for aerospace-grade titanium standoffs as EU Green Deal due diligence rules force electronics assemblers to document material pedigrees back to smelter origin.
Growth Catalysts
- EU Green Deal supply chain due diligence:Electronics manufacturers in Vietnam must verify aluminum standoff sourcing, accelerating procurement from certified cold-heading facilities with ISO 9001 and AS9100 traceability protocols.
- Surface-mount reflow temperature requirements:High-density PCB assemblies in telecommunications equipment demand polymer spacers rated for 260°C peak temperatures, expanding flame-retardant thermoplastic adoption.
- Mexico precision manufacturing corridor expansion:Automotive tier-one suppliers near Querétaro are localizing fastener procurement to satisfy USMCA regional content thresholds for electric vehicle battery enclosures.
Market Restraints
- Primary aluminum price volatility:LME aluminum contract swings above 25% annually compress margin pools for standard hex standoff producers without backward integration into billet supply.
- Titanium sponge supply concentration:Aerospace-grade standoff manufacturers depend on Japanese and Russian sponge producers, exposing lead times to geopolitical disruption and export licensing delays.
- REACH SVHC disclosure thresholds:European electronics assemblers face documentation burdens for hexavalent chromium surface treatments, slowing procurement cycles for cadmium-plated steel alternatives.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Contract manufacturers in Tamil Nadu and Karnataka require localized standoff supply chains as smartphone assembly scales toward 600 million units annually.
- Additive manufacturing convergence with topology optimization:Lattice-structured titanium spacers for satellite payloads combine electron beam melting with generative design software, enabling weight reductions beyond machined alternatives.
- Vendor-managed inventory for automotive tier-one suppliers:Bossard Group's bin-stock programs near Stuttgart assembly plants reduce working capital requirements while locking out Asian competitors.
Industry Challenges
- AS9100D certification timeline compression:Aerospace standoff suppliers face 18-month audit cycles to maintain NADCAP special process accreditation for heat treatment and passivation.
- Legacy ERP integration with traceability platforms:Small cold-heading shops struggle to connect ISO 27001-compliant material pedigree systems to customer PLM environments without six-figure middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Standoff and Spacer Market |
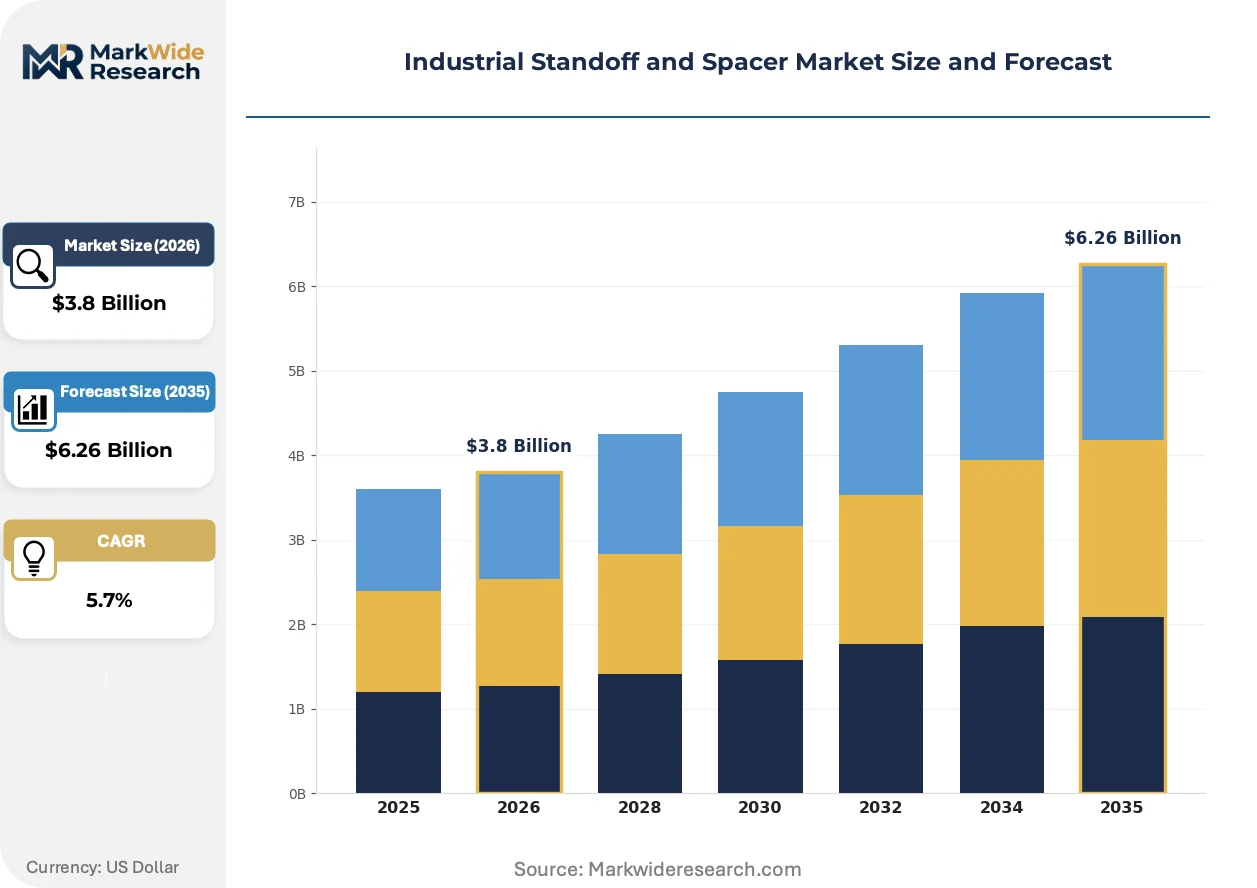
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Standoffs, Hex Standoffs, Round Standoffs, Threaded Spacers Material: Aluminum, Steel, Plastic, Brass Application: Electronics Assembly, Automotive Industry, Aerospace Equipment, Electrical Enclosures End User: Manufacturers, Contractors, Distributors, OEMs |
| Companies Covered | PennEngineering, Bossard Group, Lisi Aerospace, Molex, TE Connectivity, Schneider Electric, 3M Company, Fastenal Company, Wurth Elektronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Standoff and Spacer Market Emerging Trajectories
Digital thread technologies are collapsing the documentation burden for aerospace material certification, while flame-retardant polymer formulations displace metal in consumer electronics thermal management. Procurement patterns are fragmenting as OEMs bypass distributors for direct mill relationships.
Machine vision inspection integrated with cold-heading presses is digitizing quality assurance workflows for threaded aluminum standoffs. Electronics contract manufacturers in Vietnam and Mexico are deploying these systems to satisfy EU Green Deal photographic evidence requirements without manual sorting stations. The technology is digitizing supplier qualification processes, compressing audit cycles from quarterly to continuous monitoring.
REACH SVHC candidate list expansion to 233 substances is forcing surface treatment substitutions across European electronics supply chains. Cadmium and hexavalent chromium plating for steel standoffs face phase-out pressures, accelerating zinc-nickel and trivalent chrome process adoption. German automotive tier-one suppliers are consolidating procurement around electroplaters with ECHA pre-registered substance portfolios.
Consignment inventory models are displacing traditional spot purchasing for high-volume electronics assembly. Taiwanese ODMs now require standoff suppliers to maintain 90-day buffer stocks at Penang and Tijuana logistics hubs, transferring carrying cost risk upstream. This pattern is most visible in LED lighting fixture manufacturing, where seasonal demand spikes punish distributors without captive warehouse capacity.
Industrial Standoff and Spacer Market Segmentation
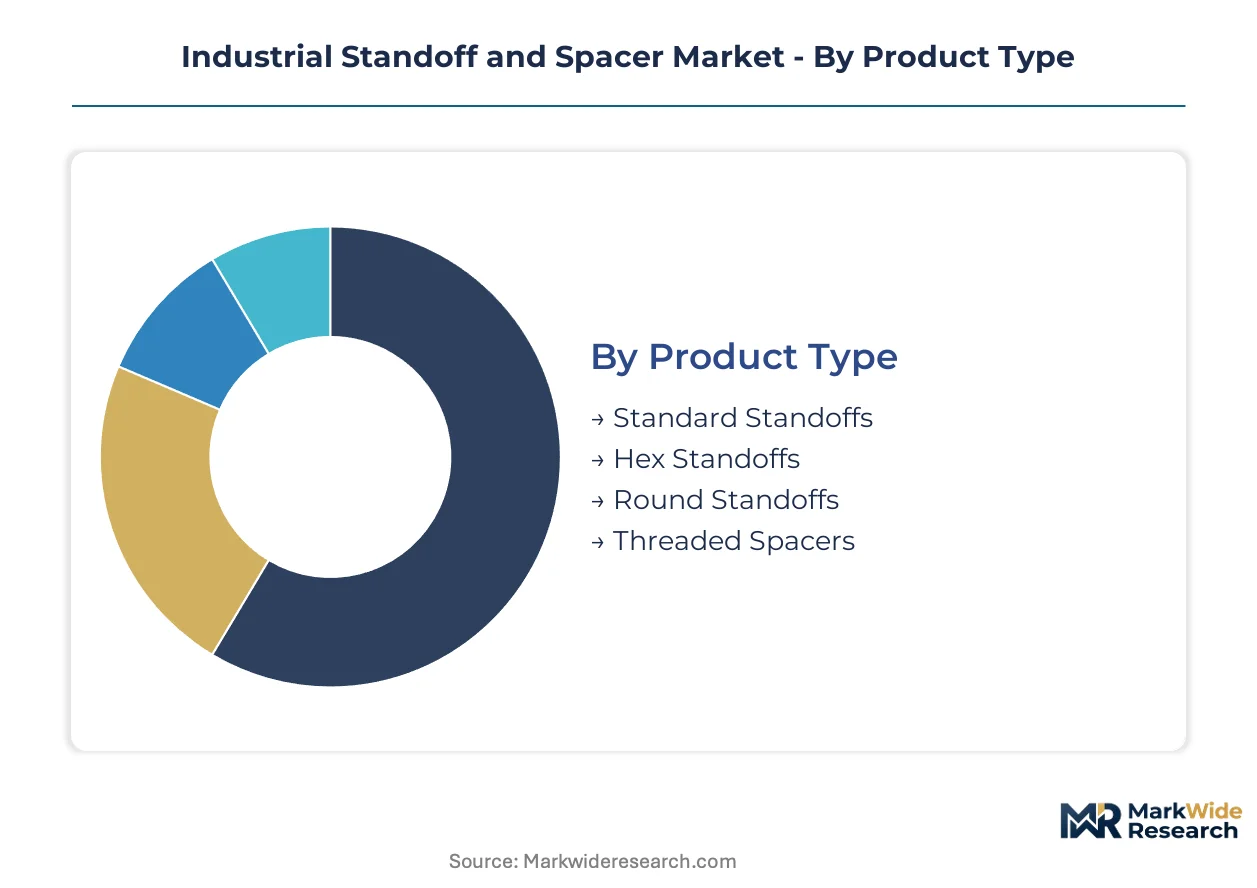
Segmentation in industrial standoffs and spacers reveals how material certification requirements and thermal performance specifications split procurement across radically different supply chains. Electronics assemblers prioritize polymer spacers for reflow compatibility while aerospace buyers demand lot-traceable titanium with NADCAP-accredited heat treatment.
Product Type:
Mature hex geometries dominate established electronics corridors, while emerging lattice-structured variants are penetrating satellite payload applications through additive manufacturing.
- Standard Standoffs:Plain cylindrical aluminum bodies with through-holes or tapped interiors serve cost-sensitive LED lighting and consumer electronics assembly. Vietnamese contract manufacturers procure these in bulk for smartphone chassis where ±0.1 mm tolerances suffice and surface treatments are minimal.
- Hex Standoffs:Six-sided external profiles enable wrench tightening without rotation in confined enclosures. German automotive tier-one suppliers specify these for battery management system housings under EU Green Deal documentation requirements, locking in cold-heading suppliers with AS9100 traceability protocols.
- Round Standoffs:Smooth cylindrical exteriors suit aesthetic-facing applications in medical device housings and retail display fixtures.
- Threaded Spacers:Internal and external threading enables stackable assemblies in aerospace avionics racks where vibration resistance is mandatory.
Hex standoffs handle the majority of throughput; threaded spacers are the fastest mover on share.
Material:
Cost tiers separate commodity metals from certified alloys, with flame-retardant thermoplastics carving out volume in consumer electronics below aerospace-grade titanium pricing.
- Aluminum:6061-T6 and 7075 alloys deliver strength-to-weight ratios critical for handheld electronics and drone assemblies. Mexico's Querétaro precision manufacturing corridor sources these for EV battery enclosures under USMCA regional content rules, with local cold-heading capacity expanding to serve Detroit Three suppliers.
- Steel:Cold-rolled carbon and stainless grades dominate industrial machinery and electrical enclosures where corrosion resistance demands justify weight penalties. REACH SVHC disclosure thresholds are forcing rapid substitution of hexavalent chromium plating for zinc-nickel alternatives across European procurement.
- Plastic:Flame-retardant PPS and LCP formulations rated for 260°C reflow temperatures displace metal in high-density telecommunications PCBs.
- Brass:Free-machining C36000 serves decorative and antimicrobial applications in medical equipment and food processing machinery.
Aluminum commands the dominant procurement volume; plastic is expanding most quickly as surface-mount densities climb.
Application:
Customer type stratification separates spot purchasers from integrated OEMs, with contract manufacturers demanding consignment inventory while aerospace primes enforce direct mill relationships.
- Electronics Assembly:High-volume PCB stacking and enclosure mounting in smartphones, servers, and LED drivers. Taiwanese ODMs now require 90-day buffer stocks at Penang and Tijuana hubs, transferring carrying cost risk upstream to standoff suppliers.
- Automotive Industry:Battery enclosure isolation and infotainment module mounting in electric vehicles. Stuttgart-area tier-one suppliers are consolidating procurement around Bossard Group's vendor-managed inventory programs to reduce working capital requirements.
- Aerospace Equipment:Satellite payload structures and avionics racks where titanium lot traceability and NADCAP special process accreditation are mandatory. Japanese and Russian titanium sponge concentration exposes lead times to export licensing delays.
- Electrical Enclosures:Panel mounting and busbar isolation in industrial control cabinets and switchgear.
Electronics assembly generates the highest unit volumes; aerospace equipment claims the steepest expansion trajectory as satellite constellation deployments accelerate.
End User:
Supply concentration patterns favor distributors with captive warehouse capacity near manufacturing clusters, while OEMs with legacy ERP systems struggle to integrate traceability platforms.
- Manufacturers:Contract electronics manufacturers and precision metal fabricators with direct cold-heading or CNC turning capabilities. India's PLI scheme for electronics manufacturing is driving localization requirements in Tamil Nadu and Karnataka as smartphone assembly scales.
- Contractors:Installation and maintenance service providers procuring through distribution for electrical and industrial equipment projects.
- Distributors:Specialty fastener and electronic component distributors managing consignment and bin-stock programs. Machine vision inspection systems are digitizing quality assurance workflows to satisfy EU Green Deal photographic evidence requirements without manual sorting.
- OEMs:Original equipment manufacturers with direct supplier qualification and material pedigree documentation mandates. Small cold-heading shops face six-figure middleware investments to connect ISO 27001-compliant systems to customer PLM environments.
Manufacturers absorb the dominant share of direct procurement; distributors are gaining share fastest as consignment models displace spot purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese cold-heading facilities dominate aerospace-grade titanium standoff output, while Vietnamese electronics corridors and Mexico's Querétaro precision cluster absorb expanding aluminum and polymer spacer demand.
United States
Detroit Three automakers and satellite constellation builders drive titanium and aluminum standoff procurement. FAA airworthiness certification mandates lot-traceable material pedigrees for aerospace applications. California's Space Coast suppliers and Michigan's battery enclosure fabricators anchor domestic demand for threaded fasteners.
Germany
Stuttgart-area automotive tier-one suppliers consolidate fastener procurement through vendor-managed inventory programs. EU Green Deal due diligence rules force electronics assemblers to document aluminum sourcing back to smelter origin. Bavarian cold-heading shops with AS9100 accreditation capture aerospace margin pools.
Japan
Domestic titanium sponge producers supply aerospace standoff manufacturers facing export licensing delays from alternative sources. METI industrial standards govern precision fastener tolerances for automotive and electronics exports. Nagoya's aerospace cluster demands NADCAP-accredited heat treatment for satellite payload hardware.
Vietnam
Electronics contract manufacturers in Bac Ninh and Hai Phong expand threaded aluminum standoff procurement as local content rules tighten. EU Green Deal supply chain frameworks require photographic evidence of material origins. Machine vision inspection systems digitize quality assurance for continuous monitoring compliance.
Mexico
Querétaro's precision manufacturing corridor localizes fastener supply for EV battery enclosures under USMCA regional content thresholds. Automotive tier-one suppliers near Mexico City reduce working capital through consignment inventory models. Domestic cold-heading capacity expands to serve Detroit Three suppliers without cross-border logistics exposure.
Industrial Standoff and Spacer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in cold-heading and polymer formulation. The vendor base stratifies across three tiers: captive aerospace suppliers with NADCAP accreditation, automotive-focused fastener distributors with bin-stock programs, and commodity electronics component houses. Two strategic archetypes dominate competitive positioning: backward-integrated metal formers controlling billet-to-fastener workflows, and specialty distributors leveraging logistics infrastructure for consignment capture. Capacity expansion and vendor-managed inventory partnerships represent the dominant competitive moves as procurement patterns fragment.
Among North American fabricators, PennEngineering occupies a position within the aerospace-tier archetype, while Bossard Group exemplifies the European distributor model with captive logistics infrastructure. Molex represents the electronics-specialist tier focused on high-density polymer spacing hardware. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| PennEngineering |
| Bossard Group |
| Lisi Aerospace |
| Molex |
| TE Connectivity |
| Schneider Electric |
| 3M Company |
| Fastenal Company |
| Wurth Elektronik |
| Others |
Supply Flow & Price Mechanics
Querétaro's precision manufacturing corridor anchors North American supply for aluminum hex standoffs, with captive cold-heading capacity granting local producers pricing leverage over Detroit Three battery enclosure suppliers facing USMCA regional content thresholds. This geographic concentration enables premium positioning for traceable material pedigrees while compressing margins for spot-market distributors without backward integration into billet supply.
Pricing Analysis
EU Green Deal supply chain due diligence dictates the pricing tier structure across European procurement, separating AS9100-accredited aerospace suppliers from commodity electronics houses. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and lot-traceability depth. Cost compression in standard aluminum hex standoffs is intensifying because LME contract volatility above 25% annually erodes margin pools for non-integrated producers. Contract electronics manufacturers in Vietnam exhibit highest price sensitivity due to local content rule pressures, while aerospace primes in Stuttgart demonstrate lowest sensitivity given NADCAP accreditation requirements.
Supply Chain Analysis
Primary aluminum billet feeds from Canada, Russia, and the Middle East sustain cold-heading operations across Germany, Japan, and Mexico. Titanium sponge for aerospace-grade threaded spacers draws from Japanese producers and alternative sources subject to export licensing delays. Single-source vulnerability in Russian sponge supply exposes lead times to geopolitical disruption. Distribution runs through vendor-managed inventory programs anchored by Bossard Group's bin-stock infrastructure near Stuttgart assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Satellite constellation deployment acceleration and EU Green Deal material pedigree mandates create a dual inflection point reshaping competitive dynamics. The market structure favors suppliers with integrated traceability platforms and captive cold-heading capacity over spot-market distributors.
For Market Incumbents: Entrench position by deepening backward integration into certified titanium sponge supply and expanding machine vision inspection capacity at Vietnamese electronics corridors. Threat from additive manufacturing lattice spacers in satellite payloads demands R&D investment in electron beam melting capabilities. Certification investment in ISO 27001-compliant material pedigree systems locks out smaller cold-heading shops facing six-figure middleware costs. For New Entrants and Emerging Players: India's PLI scheme electronics manufacturing clusters in Tamil Nadu and Karnataka represent the most penetrable entry point for localized aluminum standoff supply. Mid-market automotive tier-two suppliers near Querétaro offer secondary white-space as USMCA content rules tighten. Go-to-market angle centers on 90-day consignment buffer stocks at Penang and Tijuana logistics hubs, transferring carrying cost risk from Taiwanese ODMs. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vendor-managed inventory programs and captive cold-heading capacity create defensive moats against Asian competitors. Target acquisition archetype: mid-cap European fastener distributors with ECHA pre-registered electroplater networks and existing AS9100 accreditation. Signal to watch is REACH SVHC candidate list expansion pace, which accelerates surface treatment substitution demand and favors consolidated procurement around compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Captive supply from Japanese producers insulates aerospace standoff manufacturers against export licensing delays. |
| Machine Vision Quality Assurance Deployment | Digitized inspection at Vietnamese contract manufacturers satisfies EU Green Deal photographic evidence requirements. |
| Vendor-Managed Inventory Expansion | Bossard Group's bin-stock programs near Stuttgart reduce working capital for automotive tier-one suppliers. |
| Additive Manufacturing Capability Buildout | Electron beam melting for lattice-structured satellite spacers enables weight reductions beyond machined alternatives. |
| Surface Treatment Process Substitution | Zinc-nickel and trivalent chrome adoption replaces cadmium plating under REACH SVHC disclosure pressures. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed fastener distributors, and aerospace certification registries. Primary interviews engaged cold-heading plant managers, automotive tier-one procurement leads, electronics contract manufacturer supply chain directors, and aerospace quality assurance officers. Secondary validation drew from ECHA substance databases, FAA airworthiness directives, and EU Green Deal implementation guidance. Bottom-up unit economics from individual production facilities triangulate against top-down demand modeling from end-use industry consumption patterns.
Forecast inputs span product type segmentation across standard, hex, round, and threaded geometries; material tiers from commodity aluminum to certified titanium; and application splits across electronics assembly, automotive, aerospace, and electrical enclosures. CAGRs derive from regression analysis of historical procurement volumes against projected end-use industry expansion. Industry-specific inputs include satellite constellation deployment schedules and PLI scheme localization timelines for Indian electronics manufacturing.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum LME pricing, titanium sponge export licensing timelines, or REACH regulatory enforcement intensity would shift the trajectory. Cross-checking against customs trade flow data and aerospace OEM procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Global Metal Anodizing Market