
 Pelvic Floor Stimulators Market | 2026-2036
Pelvic Floor Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Floor Stimulators Market Outlook
North American medical device manufacturing is consolidating as contract producers scale output for neuromodulation platforms. Medtronic leverages its neurostimulation infrastructure to anchor pelvic floor product development in Minnesota. Laborie sustains European distribution density through urology-gynecology channel control. Renovia Inc. specializes in app-integrated biofeedback systems that compete on consumer usability rather than clinical specification alone.
Pelvic floor stimulators are electro-mechanical or magnetic devices that deliver controlled neuromuscular activation to the levator ani and related structures, typically operating at frequencies between 10-50 Hz for urge suppression and 35-50 Hz for stress incontinence protocols; their commercial purpose is to restore voluntary contractility or suppress detrusor overactivity without surgical intervention. Electrical stimulators dominate installed base across hospital outpatient departments due to reimbursement familiarity and established CPT coding, while wearable biofeedback devices represent the fastest-expanding margin pool as direct-to-consumer channels bypass traditional durable medical equipment distribution. Remote monitoring delivery mode is displacing in-office-only protocols as cloud-connected platforms allow clinicians to titrate home-based therapy parameters.
FDA 510(k) clearance requirements shape product development timelines and predicate device selection for US market entry, while the EU Medical Device Regulation mandates notified body involvement and post-market surveillance systems that extend commercialization cycles in Europe. Japan's PMDA enforces quality management system audits and clinical evidence standards that filter out lower-capability applicants. Stakeholders must monitor evolving digital health reimbursement codes and telehealth parity legislation that determine whether at-home treatment modes achieve sustainable payment rates.
Market Dynamics
Remote monitoring platforms are compressing treatment delivery from clinic-centric models to cloud-titrated home protocols, restructuring reimbursement requirements and hardware specifications simultaneously.
Growth Catalysts
- Telehealth parity legislation:US state-level mandates now mandate equivalent payment for remote pelvic floor therapy sessions, eliminating prior reimbursement gaps that constrained device prescribing.
- Postpartum rehabilitation protocols:Obstetrics departments in Germany and Japan have incorporated electrical stimulation into standard discharge pathways for vaginal delivery patients.
- Wearable biofeedback miniaturization:MEMS pressure sensors and Bluetooth Low Energy chipsets enable continuous ambulatory monitoring previously requiring wired clinic installations.
Market Restraints
- EU MDR compliance costs:Notified body fees and clinical evidence requirements for Class IIa neuromodulation devices have doubled market entry capital requirements for sub-$10 million manufacturers.
- Neodymium magnet supply concentration:Magnetic stimulator producers remain dependent on rare earth processing facilities concentrated in China's Jiangxi province.
- Substitution by pelvic floor physical therapy:Manual therapy delivered by specialized physiotherapists competes directly for stress incontinence cases without device capital expenditure.
Strategic Opportunities
- India's underserved urogynecology infrastructure:Fewer than 200 certified specialists serve a population exceeding 1.4 billion, creating white space for technician-operated stimulation protocols.
- AI-enabled parameter optimization:Machine learning algorithms analyzing EMG patterns promise automated intensity titration that reduces clinician oversight burden.
- Direct-to-consumer subscription channels:Pelvic health apps paired with leased hardware bypass durable medical equipment distributors entirely.
Industry Challenges
- Electromyography interpretation expertise:Clinician training programs for biofeedback signal analysis remain underdeveloped outside tertiary referral centers.
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards for software-as-medical-device components extend clearance timelines unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Floor Stimulators Market |
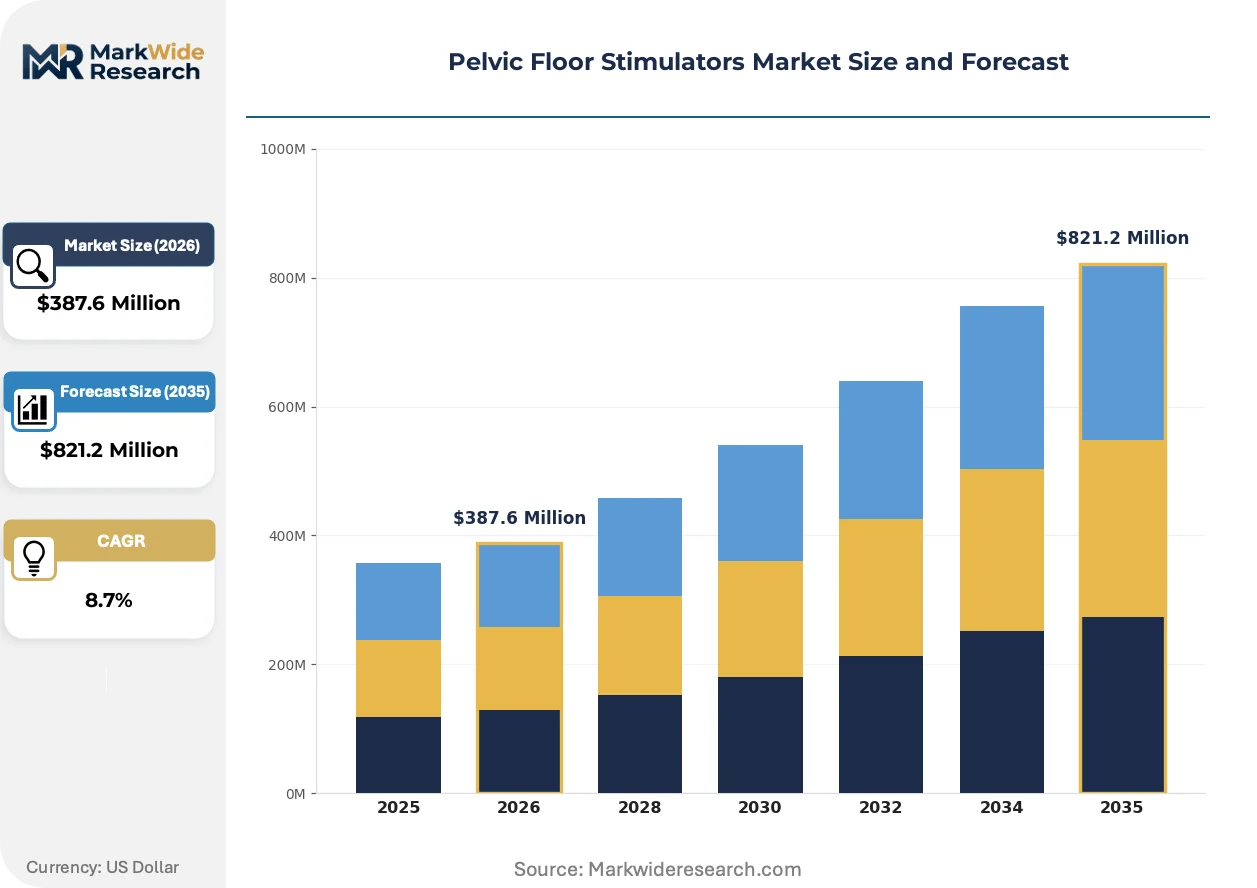
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Stimulators, Magnetic Stimulators, Biofeedback Devices, Accessories End User: Home Users, Hospitals, Clinics, Rehabilitation Centers Therapy Area: Urinary Incontinence, Chronic Pelvic Pain, Overactive Bladder, Postpartum Recovery Delivery Mode: In-Office Treatment, At-Home Treatment, Remote Monitoring, Wearable Devices |
| Companies Covered | Medtronic, Laborie, The Prometheus Group, TensCare Ltd., Verity Medical Ltd., InControl Medical, Athena Feminine Technologies, Renovia Inc., Zynex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Floor Stimulators Market Strategic Shifts
Digital health integration is dissolving boundaries between prescription medical devices and wellness electronics, forcing regulatory frameworks to distinguish therapeutic claims from general wellness positioning.
Multiparameter wearable systems incorporating pressure sensors, accelerometers, and surface EMG electrodes are consolidating previously separate diagnostic and therapeutic functions into single patient-managed platforms. Urogynecology clinics in the United States and Japan now prescribe these unified devices for both initial assessment and ongoing home-based protocol adjustment. This convergence is consolidating vendor relationships as hospitals reduce from three separate suppliers to single-platform contracts.
Japan's PMDA has tightened software change control requirements for cloud-connected stimulation devices, mandating pre-approval for algorithm updates that previously qualified as maintenance. Manufacturers must now submit cybersecurity documentation and clinical validation for each functional modification. European producers seeking Japanese market access are responding by segregating hardware and software regulatory submissions to isolate approval pathway risks.
Patients increasingly initiate pelvic floor therapy through employer-sponsored wellness benefits rather than physician referral, bypassing traditional urology-gynecology gatekeeping. This channel shift pressures device makers to design for consumer unboxing experience and app onboarding rather than clinical workflow integration. The phenomenon is most pronounced in US metropolitan markets where large self-insured employers have added pelvic health to covered preventive care categories.
Pelvic Floor Stimulators Market Segmentation
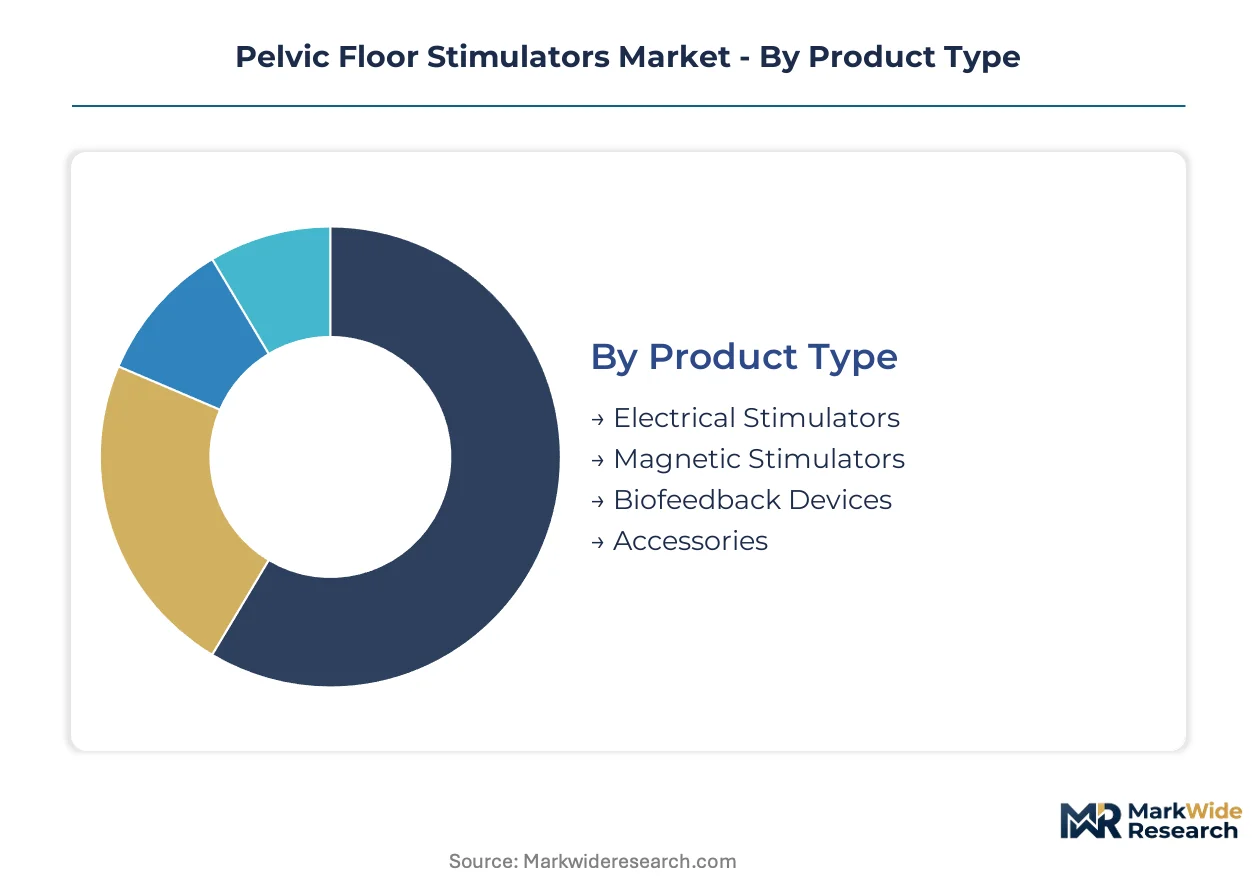
Pelvic floor stimulators serve distinct patient workflows that demand different hardware specifications, reimbursement strategies, and channel economics. Segmentation reveals where margin pools concentrate versus where volume scales, guiding resource allocation across R&D and commercial functions.
Product Type:
Buyers prioritize clinical validation depth against total cost of ownership, creating tiered preference curves across electrical, magnetic, and biofeedback modalities.
- Electrical Stimulators:These devices deliver controlled current through vaginal or anal probes at calibrated frequencies for neuromuscular re-education. Hospital outpatient departments in the United States and Germany anchor demand here, driven by established CPT coding familiarity and physician comfort with predicate device protocols.
- Magnetic Stimulators:Pulsed magnetic fields induce pelvic floor contractions without probe insertion, appealing to patients with vaginal atrophy or discomfort with internal devices. Japanese urogynecology clinics have adopted these systems for stress incontinence protocols where patient compliance with invasive methods proves challenging.
- Biofeedback Devices:Surface EMG sensors paired with visual displays enable patient-guided muscle training through real-time contractility feedback. Direct-to-consumer channels in US metropolitan markets are absorbing shipments as employer wellness benefits expand coverage.
- Accessories:Replacement probes, conductive gels, and electrode arrays constitute recurring revenue streams tied to installed base expansion rather than new patient acquisition.
Volume sits with Electrical Stimulators; growth tilts toward Biofeedback Devices.
End User:
Channel selection determines pricing power, with institutional procurement favoring bundled service contracts and home users driving subscription monetization.
- Home Users:Postpartum women and aging populations with stress incontinence constitute the expanding addressable base. Telehealth parity legislation in multiple US states now reimburses remote pelvic floor therapy, eliminating prior payment gaps that constrained device prescribing for residential use.
- Hospitals:Academic medical centers and community hospital systems require FDA-cleared platforms with established predicate devices for 510(k) pathway efficiency. These institutions anchor magnetic stimulator placements where capital budgets accommodate higher acquisition costs.
- Clinics:Independent urogynecology and pelvic health specialty practices favor electrical stimulators with portable form factors for room-to-room mobility.
- Rehabilitation Centers:Physical therapy chains integrate stimulation into post-surgical recovery protocols, particularly following prostatectomy or hysterectomy procedures.
Revenue concentrates with Hospitals; expansion accelerates fastest among Home Users.
Therapy Area:
Clinical indication shapes device specification requirements, with urge suppression demanding different frequency parameters than stress incontinence protocols.
- Urinary Incontinence:Stress and mixed incontinence variants drive the majority of electrical stimulator prescriptions. German obstetrics departments have incorporated stimulation into standard discharge pathways for vaginal delivery patients, institutionalizing postpartum preventive care.
- Chronic Pelvic Pain:Myofascial dysfunction and neuropathic pain presentations require lower-frequency stimulation protocols with longer session durations. Tertiary referral centers in Japan specialize in these applications.
- Overactive Bladder:Detrusor overactivity suppression operates at 10-50 Hz frequencies distinct from stress protocols, creating product line differentiation opportunities.
- Postpartum Recovery:Levator ani rehabilitation following childbirth represents a preventive care segment with employer wellness channel potential.
Patient volume clusters in Urinary Incontinence; Chronic Pelvic Pain commands premium pricing.
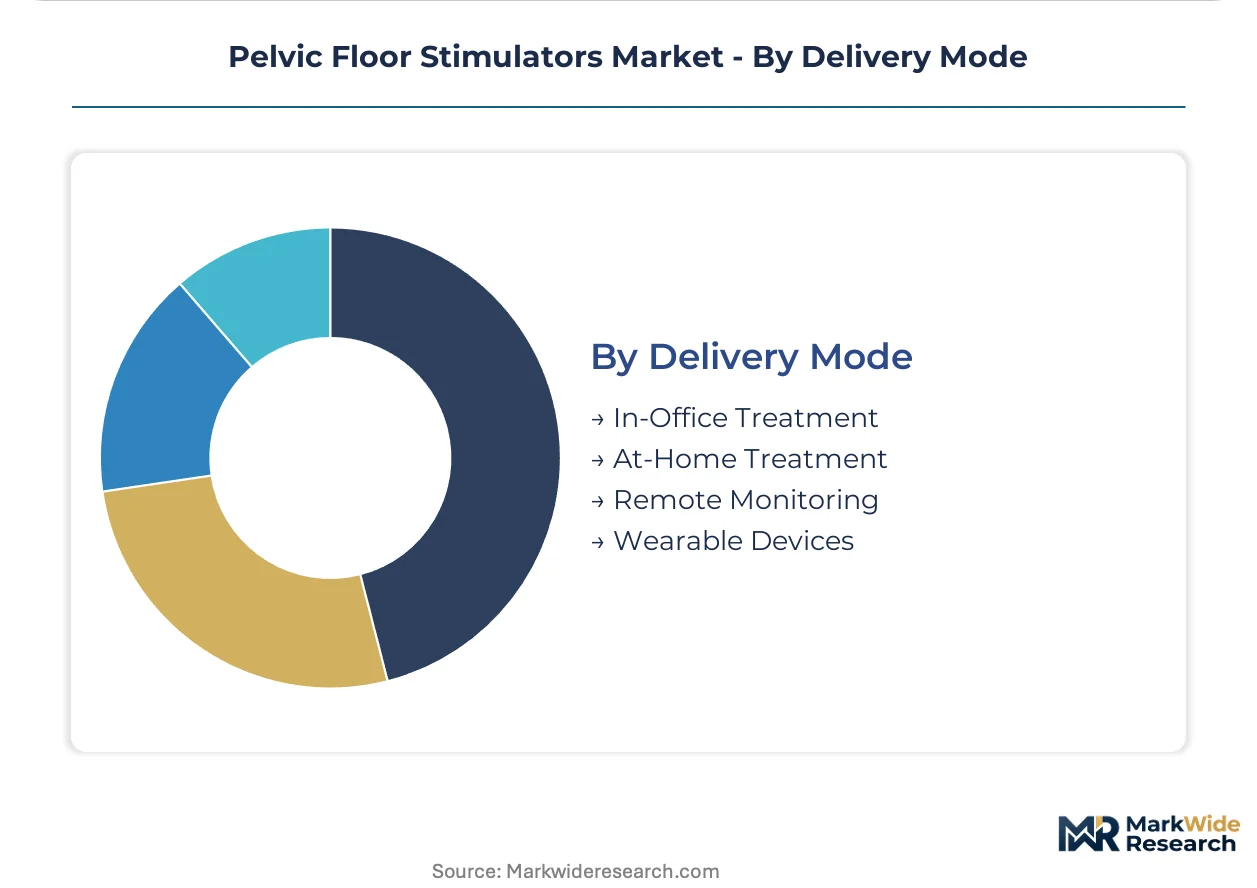
Delivery Mode:
Care setting migration from clinic-centric to home-based protocols is restructuring hardware specifications, connectivity requirements, and reimbursement documentation simultaneously.
- In-Office Treatment:Clinician-administered sessions with wired electrical stimulators retain reimbursement advantages in fee-for-service environments. These installations concentrate in hospital-based urogynecology departments with established physical therapy integration.
- At-Home Treatment:Patient-managed devices with simplified interfaces bypass durable medical equipment distributors through direct-to-consumer channels. MEMS pressure sensors and Bluetooth Low Energy chipsets enable continuous ambulatory monitoring previously requiring wired clinic installations.
- Remote Monitoring:Cloud-connected platforms allow clinicians to titrate therapy parameters without office visits. Japan's PMDA has tightened software change control requirements for these systems, mandating pre-approval for algorithm updates.
- Wearable Devices:Continuous-use garments with embedded sensors consolidate diagnostic and therapeutic functions into single patient-managed platforms.
Installed base remains with In-Office Treatment; steepest expansion trajectory belongs to Remote Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing facilities in China's Jiangxi province concentrate magnetic component supply for stimulator manufacturers worldwide. Device assembly and clinical validation clusters have developed across three continents in response to distinct regulatory and reimbursement environments. The following country-level analysis examines where demand, policy, and production intersect.
United States
Employer-sponsored wellness benefits now cover pelvic health in major metropolitan markets, bypassing traditional physician gatekeeping. FDA 510(k) clearance pathways for wearable biofeedback units streamline commercial entry for software-integrated devices. Minnesota anchors neurostimulation infrastructure as Medtronic leverages existing manufacturing platforms for pelvic floor product development.
Germany
Obstetrics departments have institutionalized electrical stimulation into standard discharge pathways for vaginal delivery patients. EU Medical Device Regulation mandates notified body involvement and post-market surveillance systems that extend commercialization cycles. Bavaria and North Rhine-Westphalia concentrate urology-gynecology channel control through Laborie's European distribution density.
Japan
Aging demographics and pelvic health awareness campaigns accelerate clinical adoption across tertiary referral centers. PMDA enforces quality management system audits and clinical evidence standards that filter out lower-capability applicants. Tokyo and Osaka metropolitan areas specialize in chronic pelvic pain applications requiring lower-frequency stimulation protocols.
United Kingdom
Postpartum rehabilitation programs expand device uptake among women following vaginal delivery. MHRA alignment with EU MDR transitional provisions maintains regulatory continuity for Class IIa neuromodulation devices. London and Southeast England concentrate telehealth platform development for remote monitoring delivery modes.
India
Fewer than 200 certified urogynecology specialists serve a population exceeding 1.4 billion, creating white space for technician-operated stimulation protocols. CDSCO medical device rules increasingly align with international standards for electrical stimulator registration. Maharashtra and Karnataka develop distribution infrastructure for affordable biofeedback device penetration.
Pelvic Floor Stimulators Market Competitive Environment
Global majors compete with regional champions across regulatory sophistication and channel access. The vendor base stratifies between consolidated neurostimulation platforms and fragmented wearable specialists. Three archetypes dominate: diversified medical technology conglomerates with predicate device libraries, pure-play pelvic health innovators competing on consumer usability, and contract manufacturers scaling output for private-label brands. M&A activity concentrates on digital health capabilities, while strategic partnerships secure distribution in underpenetrated Asian markets.
Among diversified medical technology conglomerates, Medtronic anchors neurostimulation infrastructure development in North America. Laborie exemplifies European channel control through urology-gynecology specialization. Renovia Inc. occupies a position within the pure-play digital health tier, representing consumer-facing biofeedback innovation.
| Leading Market Players |
|---|
| Medtronic |
| Laborie |
| The Prometheus Group |
| TensCare Ltd. |
| Verity Medical Ltd. |
| InControl Medical |
| Athena Feminine Technologies |
| Renovia Inc. |
| Zynex Inc. |
| Others |
Value Chain & Pricing Dynamics
Biomedical engineering talent concentration in Minnesota's Twin Cities metro drives labor-cost differentials that widen pricing-tier spreads between premium neuromodulation platforms and economy-grade home-use devices. European contract manufacturers offset this through automated assembly investments that compress mid-tier pricing bands.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier hospital contracts from unbundled direct-to-consumer sales where replacement probe costs fall to patients. Three-tier pricing structure across premium, standard, and economy levels reflects FDA predicate device depth, with 510(k) pathway efficiency commanding brand premiums. Cost compression in economy tiers intensifies because Chinese EMS providers now supply Bluetooth Low Energy chipsets at scale. Home users exhibit highest price sensitivity; academic medical centers prioritize clinical validation over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with neodymium magnet processing concentrated in China's Jiangxi province, where magnetic stimulator producers draw from rare earth separation facilities lacking geographic diversification. Taiwan and South Korea anchor MEMS pressure sensor fabrication for wearable biofeedback units. Tariff exposure on Chinese-sourced electrode arrays threatens margin stability for sub-scale manufacturers. Distribution runs through durable medical equipment distributors in institutional channels, while direct-to-consumer platforms bypass intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pelvic floor stimulators market occupies a technology-transition phase where cloud-connected biofeedback platforms displace wired clinic installations as the dominant care delivery mode.
For Market Incumbents: Acquire digital health software assets to fortify against pure-play wearable entrants threatening hospital channel control. Backward integration into MEMS sensor production secures component supply for remote monitoring platforms. Laborie's European urology-gynecology density and Medtronic's neurostimulation infrastructure both require software companion development to defend reimbursement positioning.
For New Entrants and Emerging Players: Launch via employer-sponsored wellness benefit channels that bypass physician gatekeeping and traditional DME distribution. India's technician-operated stimulation protocols offer the most penetrable geography given specialist scarcity against population scale. Direct-to-consumer subscription models with leased hardware capture recurring revenue without predicate device regulatory burden.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-enabled parameter optimization specialists given automated intensity titration's clinician burden reduction. Long-term viability favors platforms spanning diagnostic assessment through therapeutic delivery rather than single-modality hardware. Watch FDA digital health reimbursement code expansions as inflection signal for at-home treatment mode sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Cloud-connected platforms allow clinicians to titrate home-based therapy parameters through PMDA-compliant change control. |
| CE Marking Pathway | EU MDR notified body involvement extends commercialization cycles but filters out lower-capability competitors. |
| Hospital System Partnership | Academic medical centers require FDA-cleared platforms with established predicate devices for 510(k) efficiency. |
| Reimbursement Strategy | Telehealth parity legislation in US states mandates equivalent payment for remote pelvic floor therapy sessions. |
| Geographic Manufacturing Footprint | Minnesota anchors neurostimulation infrastructure leveraging Medtronic's existing production platforms. |
Study Parameters
FDA 510(k) filings, EU MDR notified body registrations, and Japan PMDA quality management system audits formed the secondary backbone, supplemented by hospital procurement database analysis and GPO contract reviews. Primary interviews with urogynecologists, biomedical engineers, hospital purchasing committees, and DME distribution executives validated demand assumptions. Bottom-up and top-down triangulation reconciled device shipment data with therapy session reimbursement claims.
Bottom-up modeling anchored volume estimates in installed base expansion across delivery modes, while top-down validation checked aggregate spending against CMS Medicare data and employer wellness benefit disclosures. Segmentation across product type, end user, therapy area, and delivery mode captured margin pool migration. CAGRs derived from logistic diffusion curves modeling biofeedback adoption rates and telehealth parity legislative progression. Rare earth supply constraints and MEMS sensor cost curves informed hardware pricing trajectories.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled parameter optimization would alter the outlook if clinician oversight requirements persist. Forecasts reflect assumptions around FDA digital health code expansion and EU MDR implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Deflectable Catheters Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Lactate Meter Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
Asia-Pacific Electrophysiology Market