
 United States Respiratory Devices Market | 2026-2036
United States Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Respiratory Devices Market Analytics
Modular platform architectures that separate hardware bases from disposable interfaces is realigning procurement economics for hospital systems and home care networks. ResMed leverages cloud-connected device ecosystems to sustain recurring revenue streams beyond initial hardware placement. Fisher & Paykel Healthcare anchors its position through vertical integration into humidification circuits and mask systems. GE HealthCare competes on imaging-to-ventilation workflow integration within acute care settings.
Respiratory devices encompass mechanical and electronic systems designed to assist, control, or augment pulmonary ventilation, typically incorporating flow sensors, pressure transducers, and microprocessor-controlled valve assemblies operating at respiratory rates of 6–40 breaths per minute. These systems serve therapeutic functions spanning oxygen delivery, airway pressure maintenance, aerosolized medication administration, and critical life support in clinical and domiciliary environments. CPAP machines and oxygen concentrators command the dominant installed base, with portable configurations representing the fastest-expanding delivery mode as lithium-ion battery chemistries extend ambulatory runtime. Smart technology segments incorporating remote diagnostic algorithms and adaptive pressure titration are capturing disproportionate margin pools relative to mechanical alternatives.
FDA 510(k) premarket notification requirements and NIOSH certification standards for respiratory protective functions shape product development timelines and clinical validation burdens for manufacturers seeking commercial access. The Centers for Medicare & Medicaid Services durable medical equipment fee schedules directly influence home care reimbursement economics and patient cost-sharing exposure. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled respiratory diagnostics and state-level Medicaid expansion variations that alter addressable patient populations.
Market Dynamics
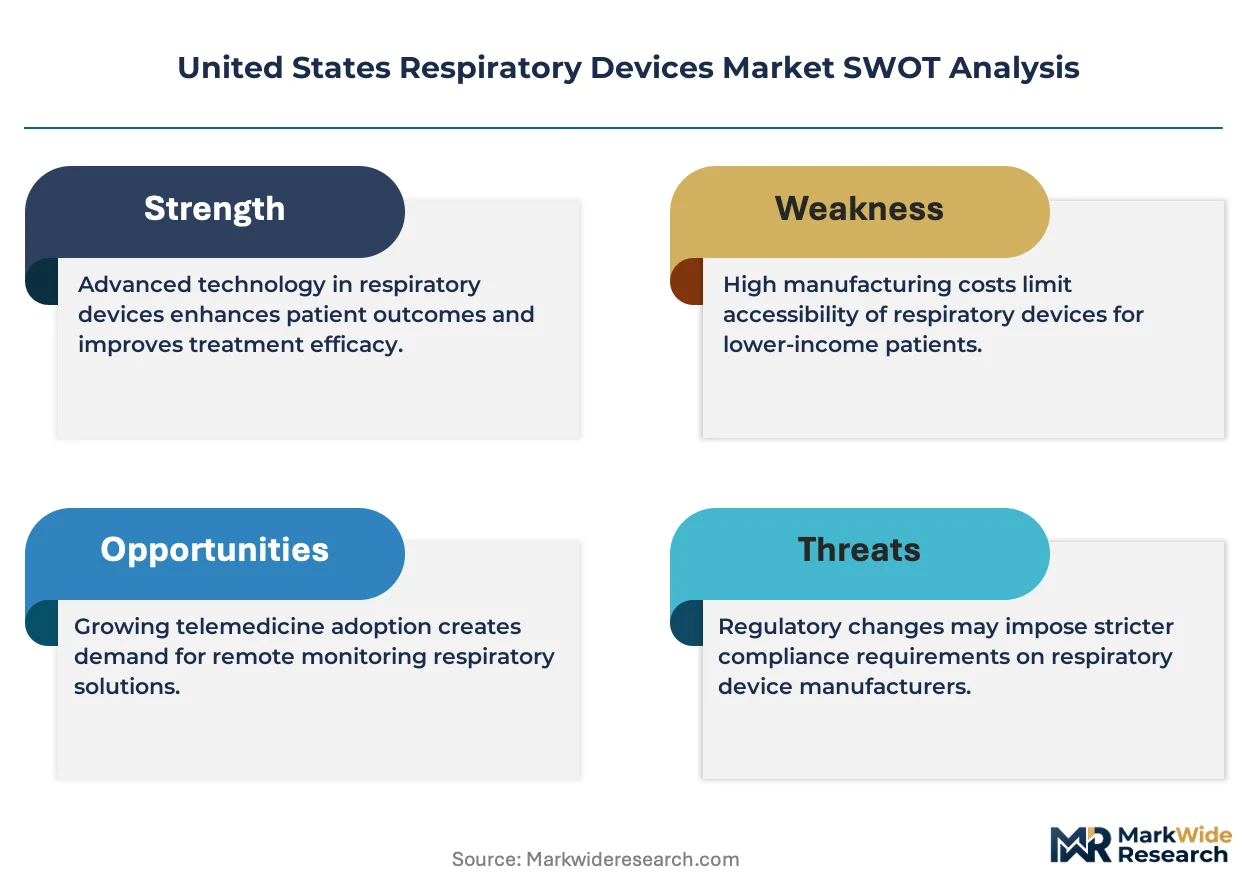
Connected respiratory platforms are compressing traditional device economics by embedding software-enabled diagnostics that shift revenue from hardware sales to recurring monitoring fees. This structural pivot forces manufacturers to rebuild commercial models around data streams rather than unit shipments.
Growth Catalysts
- Medicaid Expansion Variations:State-level coverage expansions in Texas, Florida, and California are enlarging addressable patient populations for durable medical equipment suppliers. Home care networks are scaling intake capacity to capture newly eligible beneficiaries.
- Software-Enabled Diagnostics:FDA clearance pathways for algorithm-driven respiratory monitoring are shortening development timelines. Manufacturers are embedding adaptive pressure titration to capture premium positioning.
- Aging Demographics:Chronic obstructive pulmonary disease prevalence clusters in Sun Belt retirement corridors are concentrating demand for portable oxygen concentrators and CPAP systems.
Market Restraints
- Lithium-Ion Supply Concentration:Battery chemistry sourcing for portable configurations faces geographic concentration risk in East Asian processing facilities. Domestic cell manufacturing capacity remains insufficient for respiratory device volumes.
- CMS Fee Schedule Compression:Centers for Medicare & Medicaid Services reimbursement rates for durable medical equipment directly constrain home care provider margins. Patient cost-sharing exposure limits upgrade cycles.
- Mechanical Ventilator Substitution:High-acuity transport ventilators face displacement pressure from integrated anesthesia workstations in surgical suites. Acute care capital budgets are consolidating around multifunction platforms.
Strategic Opportunities
- Rural Home Care Networks:Underpenetrated counties in Appalachia and the Mountain West present whitespace for remote patient monitoring deployments. Telehealth infrastructure investments are lowering service delivery costs.
- Humidification Circuit Integration:Convergence of heated humidification with mask systems is creating premium bundled offerings. Vertical control over consumables generates recurring revenue attachment.
- NIOSH Certification Tailwinds:Respiratory protective equipment mandates for industrial and healthcare worker safety are expanding addressable markets beyond therapeutic applications.
Industry Challenges
- Firmware Validation Timelines:FDA software-as-medical-device guidance is extending premarket notification burdens for cloud-connected platforms. Cybersecurity documentation requirements are consuming engineering resources.
- Legacy System Interoperability:Electronic health record integration with proprietary device data formats demands custom interface development. Hospital information technology departments are resisting non-standard protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Respiratory Devices Market |
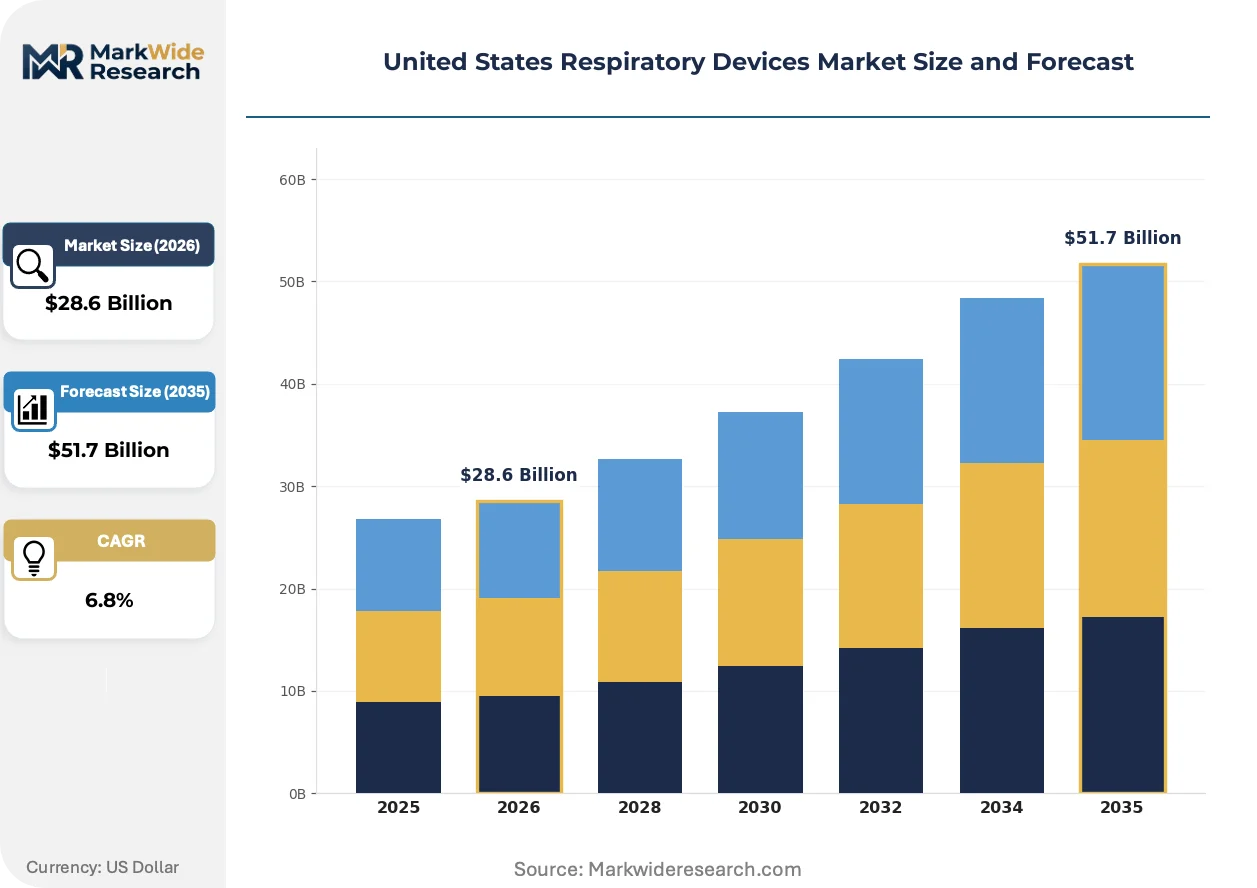
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Machines, Oxygen Concentrators Delivery Mode: Portable, Fixed, Rechargeable, Non-Rechargeable End User: Hospitals, Home Care, Clinics, Long-Term Care Facilities Technology: Mechanical, Electronic, Smart, Hybrid |
| Companies Covered | Fisher & Paykel Healthcare, ResMed, Koninklijke Philips, Drägerwerk AG, GE HealthCare, Medtronic, Getinge, Baxter, Vyaire Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Respiratory Devices Market Evolving Landscape
Remote diagnostic algorithms are embedding directly into respiratory hardware, transforming standalone devices into continuous care nodes. This convergence of sensing, computation, and connectivity is redefining competitive differentiation.
Adaptive pressure titration technology is automating real-time airflow adjustment based on respiratory event detection. Sleep clinics and home care providers are deploying these systems to reduce manual intervention requirements. The technology is automating clinical decision support that previously demanded specialist oversight.
FDA guidance on artificial intelligence-enabled diagnostics is clarifying validation requirements for algorithm-driven respiratory monitoring. Manufacturers are restructuring quality management systems to accommodate continuous learning software updates. Home care segments with direct-to-patient distribution models are most affected, adapting complaint handling procedures for post-market surveillance.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisitions, forcing device vendors to compete on discrete service modules. Group purchasing organizations are centralizing negotiations for respiratory capital equipment. This behavior shift is most visible in integrated delivery networks across Texas and California, where standardization mandates are consolidating supplier rosters.
United States Respiratory Devices Market Segmentation
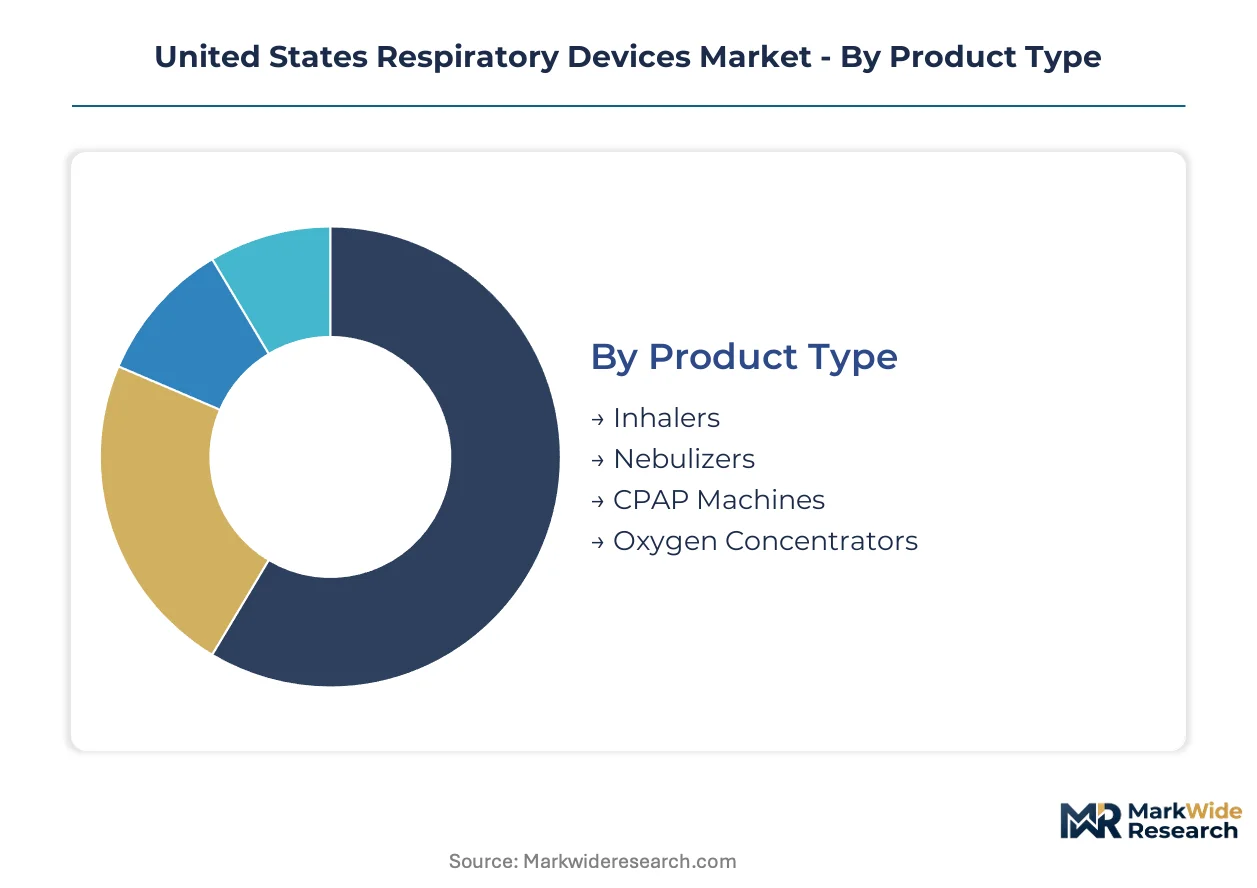
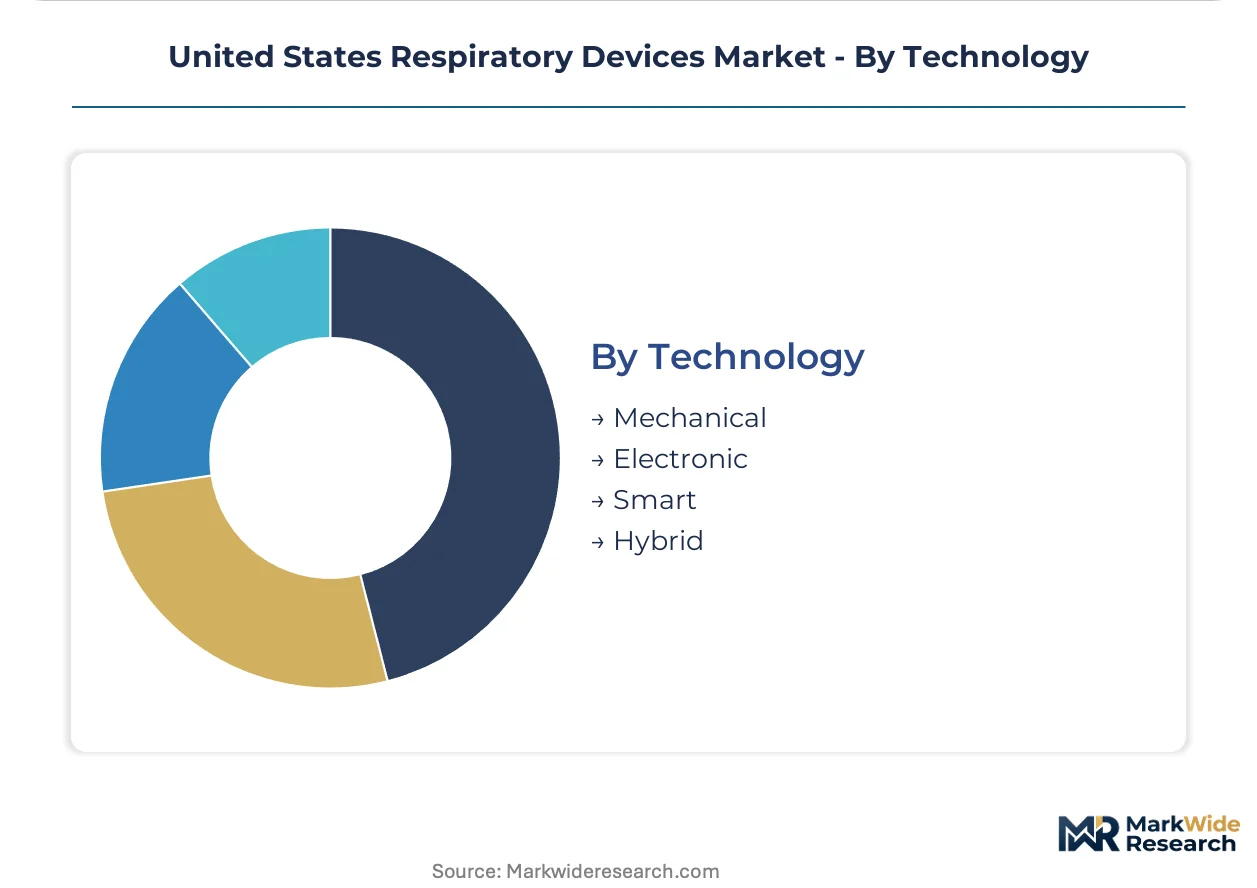
Segmentation in the United States respiratory devices market reveals how procurement priorities diverge between acute care capital budgets and home care reimbursement constraints. Technology sophistication, mobility requirements, and care setting economics each reshape competitive positioning across distinct customer clusters.
Product Type:
Device specifications determine reimbursement coding, patient compliance rates, and supplier margin structures across therapeutic categories.
- CPAP Machines:Microprocessor-controlled blower systems deliver continuous positive airway pressure at 4–20 cm H₂O for obstructive sleep apnea. Demand concentrates in Sun Belt retirement corridors where aging demographics and high obesity prevalence cluster, with Texas and Florida home care networks scaling intake capacity for newly eligible Medicare beneficiaries.
- Oxygen Concentrators:Pressure swing adsorption systems separate nitrogen from ambient air to deliver 85–96% oxygen purity at flow rates of 1–10 L/min. Portable configurations with lithium-ion power packs are expanding most quickly in California's rural counties where ambulatory patient mobility requirements outstrip stationary system deployment.
- Inhalers:Metered-dose and dry-powder systems for bronchodilator and corticosteroid delivery dominate asthma maintenance protocols.
- Nebulizers:Jet and ultrasonic aerosol generators convert liquid medication into respirable particles for patients with severe airway obstruction.
Mature deployment sits with CPAP machines. Newer deployment is concentrated in portable oxygen concentrators.
Delivery Mode:
Mobility architecture directly determines battery chemistry requirements, patient ambulatory autonomy, and total cost of ownership calculations.
- Portable:Compact configurations under 10 pounds incorporate lithium-ion cells enabling 4–8 hour runtime away from fixed power sources. Demand clusters in Mountain West states where geographic dispersion between care facilities and patient residences necessitates ambulatory therapy.
- Rechargeable:Swappable battery systems support multi-day operation through field-replaceable power modules. Home care providers in Appalachia are deploying these systems to reduce service truck dispatch frequency for power-dependent patients.
- Fixed:Stationary concentrators and ventilators operate on continuous AC power for non-ambulatory patients.
- Non-Rechargeable:Disposable alkaline or primary lithium configurations serve emergency backup and transport scenarios.
Fixed systems anchor hospital procurement. Portable configurations are gaining share fastest.
End User:
Care setting economics reshape device specification priorities, from capital equipment depreciation schedules in hospitals to rental reimbursement rates in home care.
- Home Care:Durable medical equipment suppliers manage device provisioning under CMS fee schedules with patient cost-sharing exposure. Networks in Texas and Florida are expanding remote patient monitoring infrastructure to capture Medicaid expansion beneficiaries.
- Hospitals:Integrated delivery networks centralize procurement through group purchasing organizations, unbundling service contracts from hardware acquisitions. California IDNs are consolidating supplier rosters around standardized ventilation platforms.
- Clinics:Outpatient respiratory therapy centers require intermediate-acuity devices for same-day procedure support.
- Long-Term Care Facilities:Skilled nursing operators balance device reliability against limited on-site clinical engineering capacity.
Mature procurement sits with hospitals. Newer deployment is concentrated in home care networks.
Technology:
Software-enabled capabilities are redefining competitive differentiation through remote diagnostic integration and adaptive therapy automation.
- Smart:Cloud-connected platforms embed respiratory event detection algorithms and cellular telemetry for continuous care coordination. FDA 510(k) pathways for software-as-medical-device are shortening clearance timelines for manufacturers restructuring quality systems around continuous learning updates.
- Electronic:Microprocessor-controlled systems with fixed algorithm sets dominate mid-tier positioning between mechanical reliability and premium connectivity.
- Mechanical:Pneumatic and spring-driven systems without electronic components serve backup and resource-constrained settings.
- Hybrid:Configurations combining electronic control with mechanical fallback for critical care redundancy.
Mature installed base sits with electronic systems. Newer deployment is concentrated in smart platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for respiratory devices clusters in coastal states with established medical technology corridors, while patient demand concentrates in Sun Belt retirement zones where chronic disease prevalence and aging demographics intersect.
Texas
Medicaid expansion discussions in Austin are enlarging addressable patient populations for durable medical equipment suppliers. CMS fee schedule variations directly influence home care network expansion decisions. Houston and Dallas medical corridors host distribution hubs serving Gulf Coast patient clusters with high COPD prevalence.
California
Remote patient monitoring infrastructure investments in rural Central Valley counties are lowering service delivery costs for portable oxygen concentrator deployments. FDA software-as-medical-device guidance is shortening clearance timelines for Bay Area-connected health startups. Los Angeles and San Diego anchor the state's acute care capital equipment procurement.
Florida
Aging demographic concentration in retirement corridors drives CPAP machine demand through Medicare fee-for-service and Medicare Advantage channels. State Medicaid managed care variations alter reimbursement economics for home care providers. Tampa and Orlando medical device distribution networks scale intake capacity for seasonal population influxes.
Appalachia
Underpenetrated rural counties present whitespace for telehealth-enabled respiratory monitoring deployments. Appalachian Regional Commission infrastructure grants are expanding broadband access for remote patient platforms. Kentucky and West Virginia coal country exhibits elevated occupational lung disease rates requiring specialized ventilatory support.
Mountain West
Geographic dispersion between care facilities and patient residences necessitates ambulatory therapy configurations with extended battery runtime. Veterans Health Administration facilities in Colorado and Utah anchor federal procurement for high-altitude respiratory applications. Denver and Salt Lake City serve as distribution nodes for Rocky Mountain patient populations.
United States Respiratory Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value capture models. The vendor base organizes around three strategic archetypes: cloud-connected platform operators monetizing recurring data streams, vertically integrated consumables manufacturers capturing attachment revenue, and acute care workflow integrators bundling imaging-to-ventilation solutions. Consolidation pressure intensifies as group purchasing organizations centralize negotiations and unbundle service contracts from hardware placements.
Among the connected platform specialists, ResMed exemplifies the software-enabled diagnostics archetype through cloud ecosystem architectures. Fisher & Paykel Healthcare represents vertical integration into humidification circuits and mask systems. GE HealthCare anchors the acute care integration tier through imaging-to-ventilation workflow positioning within hospital capital budgets.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare |
| ResMed |
| Koninklijke Philips |
| Drägerwerk AG |
| GE HealthCare |
| Medtronic |
| Getinge |
| Baxter |
| Vyaire Medical |
| Others |
Value Network & Pricing Analysis
Group purchasing organization concentration among Texas and California integrated delivery networks enforces contract-based long-term offtake pricing with unbundled service modules. CMS durable medical equipment fee schedules tether home care segment pricing to federal reimbursement benchmarks, compressing margin flexibility for portable oxygen concentrator and CPAP suppliers.
Pricing Analysis
Margin tightening in the home care tier reflects CMS fee schedule compression and patient cost-sharing exposure that limits upgrade cycles. Pricing stratifies across premium smart platforms with remote diagnostic capabilities, standard electronic systems with fixed algorithms, and economy mechanical configurations for backup scenarios. Cost-down pressure on portable configurations accelerates because lithium-ion battery chemistry sourcing faces geographic concentration risk. Home care networks exhibit highest price sensitivity due to direct reimbursement exposure, while hospital procurement committees leverage volume scale for standardization mandates.
Supply Chain Analysis
Single-source vulnerability sits with East Asian lithium-ion cell processing facilities that feed portable oxygen concentrator and CPAP battery packs. Component sourcing draws from China for pressure swing adsorption molecular sieves, South Korea for advanced battery chemistries, and domestic Texas and California corridors for final device assembly. Supply chain risk centers on tariff exposure for Chinese-sourced electronic components and NIOSH-certified respiratory protective subassemblies. Distribution runs through Houston, Dallas, and Los Angeles medical device distribution hubs serving Sun Belt patient clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States respiratory devices market consolidation accelerates as FDA software-as-medical-device guidance extends premarket notification burdens beyond the engineering capacity of mid-tier manufacturers.
For Market Incumbents: Anticipate displacement pressure from integrated anesthesia workstations in surgical suites by deepening cloud-connected platform ecosystems that monetize recurring monitoring fees rather than hardware shipments. Secure backward integration into humidification circuits and mask systems to capture consumables attachment revenue. Invest in FDA 510(k) quality management restructuring to accommodate continuous learning software updates ahead of smaller competitors. For New Entrants and Emerging Players: Enter via underpenetrated Appalachian and Mountain West rural counties where telehealth infrastructure investments are lowering service delivery costs for remote patient monitoring deployments. Target rechargeable portable oxygen concentrator configurations for geographic dispersion scenarios where ambulatory runtime requirements exceed stationary system capabilities. Pursue direct-to-patient distribution models with adaptive pressure titration technology to reduce manual intervention requirements and specialist oversight dependencies. For Investors and Strategic Acquirers: Distressed-cycle entries favor connected health startups with FDA-cleared software-as-medical-device platforms in California Bay Area corridors facing extended validation timelines. Long-term viability across the analysis window hinges on recurring revenue attachment rates from data streams rather than unit shipment economics. Monitor state-level Medicaid expansion variations in Texas and Florida as inflection indicators for durable medical equipment supplier addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | Accelerates clearance timelines for algorithm-driven respiratory monitoring platforms. |
| Hospital System Partnership | Secures placement within integrated delivery network standardization mandates in Texas and California. |
| Software Companion Development | Enables recurring monitoring fee revenue beyond initial CPAP and oxygen concentrator hardware placement. |
| Reimbursement Strategy | Aligns product positioning with CMS durable medical equipment fee schedules and Medicaid expansion variations. |
| CE Marking Pathway | Facilitates future geographic diversification beyond United States regulatory jurisdiction if needed. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, CMS durable medical equipment fee schedule filings, and NIOSH certification standards, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home care network operations directors. Secondary validation drew from SEC 10-K filings of publicly traded device manufacturers, hospital procurement databases, and Medicare claims data. Bottom-up patient population modeling and top-down equipment shipment triangulation anchored market sizing.
Cross-referencing historical Medicare reimbursement trend analysis against clinician and procurement panel input shaped the projection framework. Segmentation dimensions modeled include product type, delivery mode portability architecture, end user care setting economics, and technology sophistication tier. CAGRs were derived from patient prevalence trend extrapolation, equipment replacement cycle analysis, and software-enabled diagnostic adoption curve fitting. Forecast inputs incorporated chronic obstructive pulmonary disease demographic clustering and lithium-ion battery chemistry advancement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA artificial intelligence guidance revisions or lithium-ion supply disruption scenarios. Outcomes reflect documented assumptions around Medicaid expansion timing, CMS fee schedule stability, and software validation burden trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Steerable Needles Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Global Extremities Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Smart Lenses Market
Medical Devices
Genitourinary Prosthetics Market