
 Gracey Curette Market | 2026-2036
Gracey Curette Market Size, Share, and Industry Trends Forecast 2026-2036
Gracey Curette Market Foresight
Dental distributor consolidation is rewriting how Gracey curettes reach end users across developed markets. Hu-Friedy Mfg. Co., LLC leverages its direct sales force to sustain relationships with university dental programs and large clinic chains. Jakobi Dental GmbH anchors its position through precision-forged stainless steel instruments that dominate German-speaking European markets. American Eagle Instruments differentiates via specialized surface engineering that extends instrument longevity under repeated autoclave cycles.
A Gracey curette is a periodontal hand instrument featuring an offset blade angle designed for subgingival scaling and root planing, typically manufactured from surgical-grade stainless steel through precision forging and heat treatment to achieve Rockwell hardness of 45-50 HRC. Its primary purpose is to remove calculus and plaque from specific tooth surfaces while preserving root structure and soft tissue integrity. Standard curettes retain dominant volume share due to established clinical training protocols, though disposable curettes are gaining traction in settings prioritizing cross-contamination elimination. Periodontics generates the largest application revenue pool, while dental clinics represent the most concentrated end-user channel for premium instrument procurement.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape sterilization validation requirements and biocompatibility testing burdens for reusable curettes entering their respective markets. ISO 13485 quality management systems and ISO 17664 processing instructions further constrain how manufacturers document cleaning, disinfection, and sterilization parameters for regulatory dossiers. Stakeholders must monitor evolving reprocessing standards and reimbursement shifts toward preventive periodontal care as determinants of instrument replacement cycles and premium pricing acceptance.
Market Dynamics
Dental clinic consolidation and tightening infection control protocols are compressing procurement cycles while elevating sterilization traceability requirements across developed markets.
Growth Catalysts
- EU Medical Device Regulation (MDR):CE marking under MDR mandates enhanced biocompatibility documentation for reusable instruments, accelerating replacement demand among European dental clinics seeking compliant inventory.
- Japan's periodontal disease screening programs:METI-backed preventive care frameworks expand covered maintenance visits, driving instrument procurement at university-affiliated dental hospitals.
- Titanium nitride surface coatings:Advanced PVD deposition extends edge retention through repeated autoclave cycles, reducing per-procedure instrument cost for high-volume periodontal practices.
Market Restraints
- Surgical-grade stainless steel price volatility:Nickel and chromium input cost swings compress margin stability for precision-forged instrument manufacturers.
- German-speaking European supply concentration:Precision forging expertise clusters in Baden-Württemberg and Bavaria, creating geographic vulnerability to regional logistics disruptions.
- Laser scaling systems:Er:YAG and diode laser platforms reduce hand instrument dependency for subgingival calculus removal in premium clinic segments.
Strategic Opportunities
- Single-use curette expansion:Cross-contamination elimination priorities in Saudi Arabia and UAE dental chains create demand for gamma-sterilized disposable alternatives.
- Digital instrument tracking:RFID-embedded handles enable automated sterilization cycle counting, opening recurring SaaS revenue streams alongside hardware sales.
- US IRS Section 179 deduction:Accelerated equipment depreciation schedules incentivize small dental practices to refresh instrument inventories ahead of tax year-end.
Industry Challenges
- Master grinder apprenticeship gaps:Precision hand-finishing skills required for blade offset geometry face generational attrition in European instrument manufacturing hubs.
- FDA 510(k) sterilization validation timelines:Reusable instrument submissions require extended bioburden and endotoxin testing, stretching regulatory approval cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gracey Curette Market |
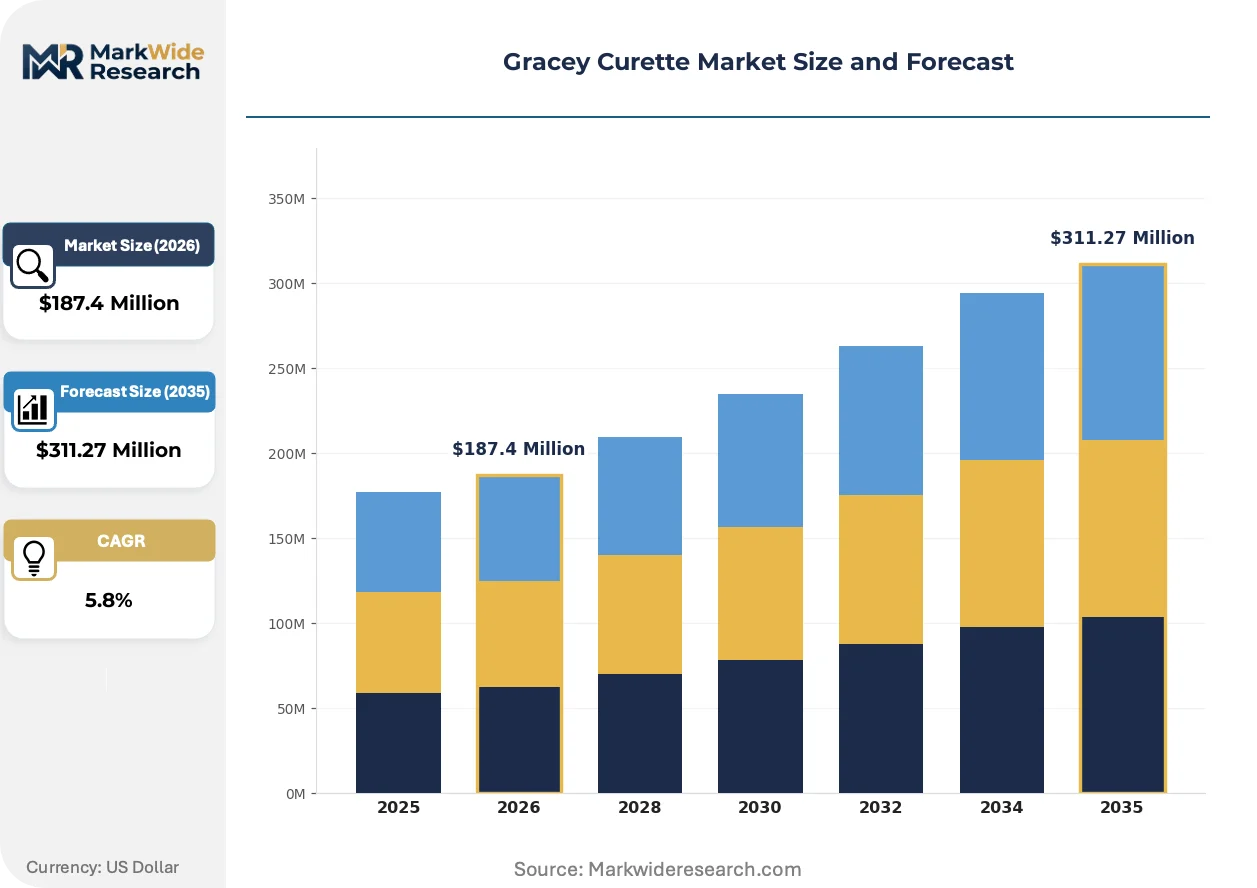
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Curettes, Ultrasonic Curettes, Disposable Curettes, Electrosurgical Curettes Application: Periodontics, Oral Surgery, Restorative Dentistry, Endodontics End User: Dental Clinics, Hospitals, Research Laboratories, Educational Institutions Material: Stainless Steel, Plastic, Titanium, Composite |
| Companies Covered | GDC Dental, ASA Dental, Hu-Friedy Mfg. Co., LLC, Jakobi Dental GmbH, Karl Schumacher Dental, Dentsply Sirona, American Eagle Instruments, Paradise Dental Technologies, LM-Instruments Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gracey Curette Market Shifts & Advancements
Material science advances and digital traceability systems are redefining instrument lifecycle economics while regulatory documentation burdens reshape competitive positioning among manufacturers.
Carbon fiber-reinforced PEEK handles are rendering obsolete traditional metal handle designs in ergonomic-focused product lines. Periodontal specialists in Germany and Switzerland are adopting these lightweight alternatives at accelerating rates. The shift is rendering obsolete established forging-to-handle assembly workflows while compressing differentiation opportunities for legacy stainless steel handle suppliers.
REACH Annex XVII nickel release restrictions are tightening surface composition requirements for prolonged skin-contact instruments. Manufacturers must now document chromium and cobalt migration limits through third-party testing. German and French dental distributors are prioritizing suppliers with pre-submitted ECHA compliance dossiers, filtering catalog offerings ahead of formal enforcement deadlines.
Subscription-based instrument replacement programs are displacing traditional capital purchase models among US dental service organizations. Large clinic chains negotiate all-inclusive per-procedure fees covering sterilization, sharpening, and automatic replacement at wear thresholds. This restructuring is most visible in Texas and Florida where DSO consolidation has concentrated buying power among three major procurement consortia.
Gracey Curette Market Segmentation
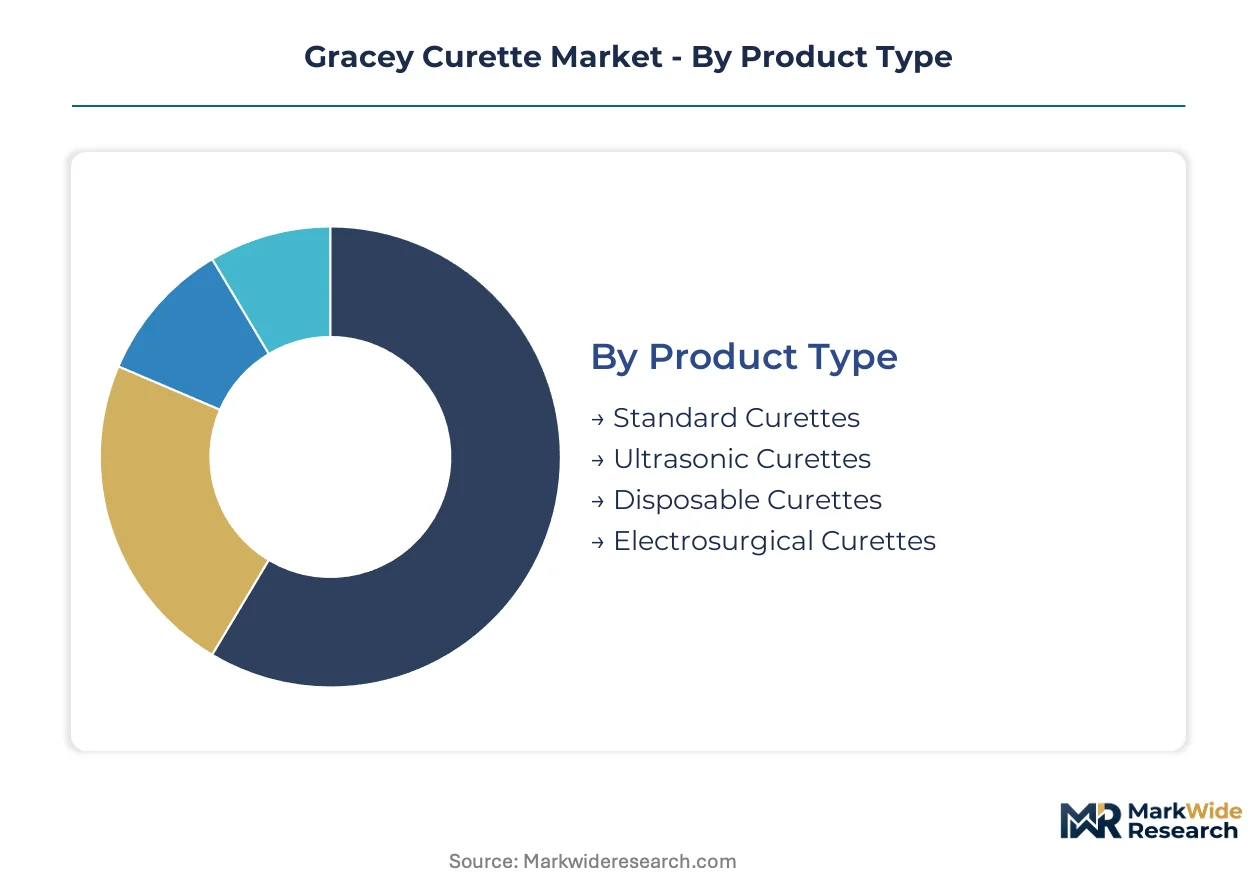
Instrument specification tiers and end-use settings determine procurement patterns across the Gracey curette market. Each dimension shapes sterilization protocols, replacement cycles, and margin structures for manufacturers and distributors.
Product Type:
Cost tier differentiation separates premium precision-forged instruments from single-use alternatives and powered systems.
- Standard Curettes:Precision-forged surgical-grade stainless steel with Rockwell hardness of 45-50 HRC achieves blade offset geometry for subgingival scaling. Dental clinics in Germany and the United States maintain dominant procurement volumes due to established periodontal training curricula and reimbursement frameworks supporting regular maintenance visits.
- Disposable Curettes:Gamma-sterilized single-use instruments eliminate cross-contamination risks and reprocessing labor costs. Demand concentrates in Saudi Arabia and UAE dental chains where infection control protocols prioritize instrument disposal over autoclave logistics.
- Ultrasonic Curettes:Piezoelectric tip attachments for scaler units reduce hand fatigue during extended scaling procedures.
- Electrosurgical Curettes:Radiofrequency-enabled tips integrate cutting and coagulation for gingival resection applications.
Standard curettes hold installed capacity. Disposable curettes are rotating up the share rankings.
Application:
Procedure complexity and reimbursement coding determine instrument specification requirements across dental specialties.
- Periodontics:Subgingival scaling and root planing procedures demand offset blade angles calibrated to specific tooth surfaces. University-affiliated dental hospitals in Japan expand instrument procurement under METI-backed preventive screening programs that extend covered maintenance visit allowances.
- Oral Surgery:Soft tissue management and minor osseous procedures require robust blade geometry with enhanced tip durability.
- Restorative Dentistry:Crown margin cleanup and cement removal utilize modified curette profiles with reduced working ends.
- Endodontics:Apical surgery and retrograde preparation access specialized micro-curette configurations.
Periodontics commands procedure volume leadership. Oral surgery is climbing the fastest in specialty instrument pricing.
End User:
Customer type dictates procurement scale, sterilization infrastructure investment, and instrument tracking system adoption.
- Dental Clinics:Independent practices and dental service organizations generate concentrated demand for premium hand instruments. Texas and Florida DSO consortia negotiate subscription-based replacement programs covering sterilization, sharpening, and automatic refresh at wear thresholds.
- Hospitals:Operating room suites and outpatient dental departments require FDA 510(k) cleared instruments with validated reprocessing instructions.
- Research Laboratories:Biomechanical testing and materials science studies utilize standardized instrument geometries for comparative analysis.
- Educational Institutions:University dental programs in North America and Europe source training sets through direct manufacturer relationships.
Dental clinics anchor procurement volume. Hospitals are gaining share through surgical suite integration.
Material:
Supply concentration and surface engineering capabilities differentiate material tiers for specific clinical environments.
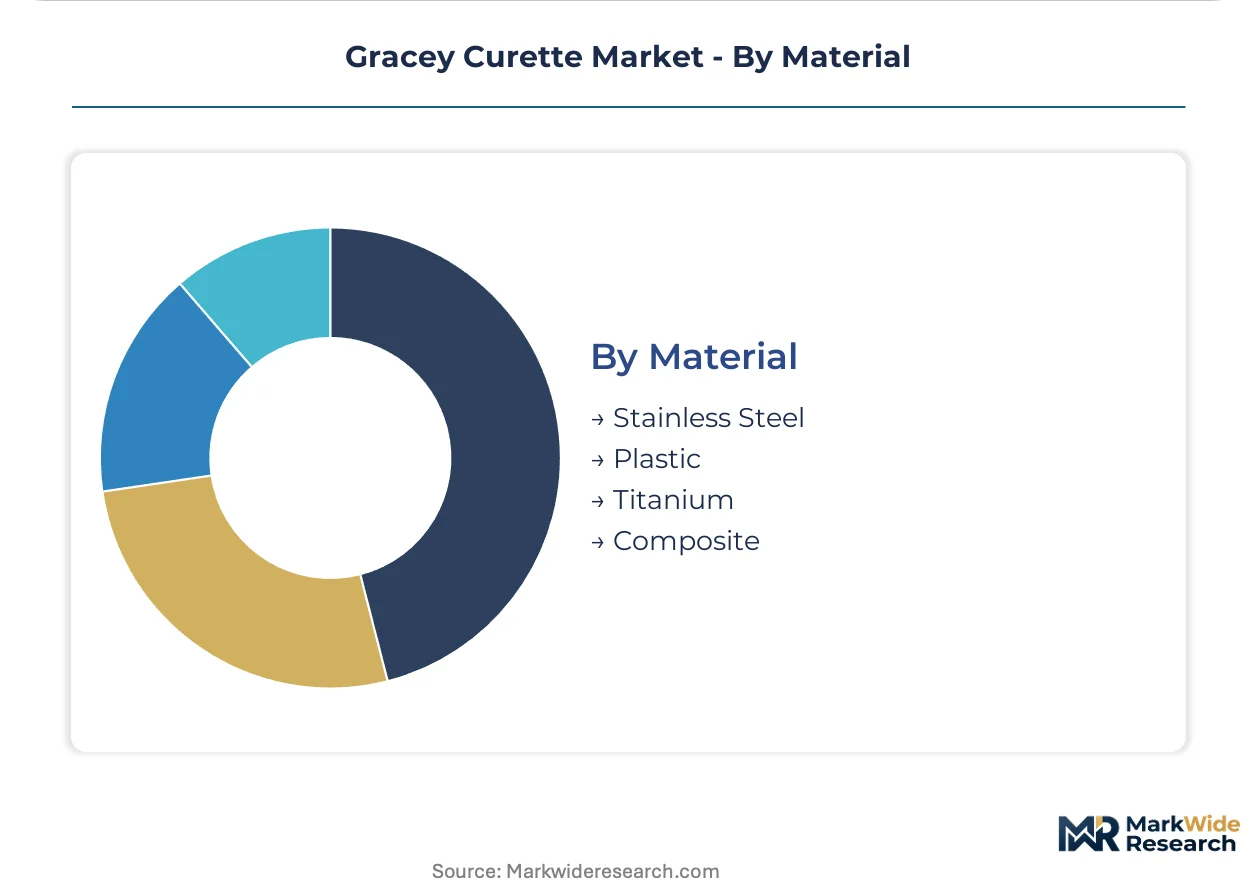
- Stainless Steel:Surgical-grade alloys with controlled nickel and chromium content dominate precision-forged instrument production. REACH Annex XVII compliance documentation filters German and French distributor catalog offerings ahead of formal nickel release enforcement deadlines.
- Titanium:Biocompatible metal with superior strength-to-weight ratio supports ergonomic handle designs for extended procedures.
- Plastic:Single-use instrument bodies reduce per-procedure costs in high-turnover clinical settings.
- Composite:Carbon fiber-reinforced PEEK handles displace traditional metal assemblies in ergonomic-focused product lines.
Stainless steel retains manufacturing scale leadership. Titanium is expanding most quickly in premium segment positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision-forged instruments command premium pricing against US distributor-consolidated procurement, creating a transatlantic arbitrage in replacement cycle economics.
Germany
University dental hospitals in Berlin and Hamburg expand instrument procurement under tightened MDR compliance deadlines. ECHA REACH Annex XVII nickel release documentation filters distributor catalogs ahead of 2025 enforcement. Precision forging expertise clusters in Baden-Württemberg and Bavaria, where Jakobi Dental GmbH anchors supply chains for German-speaking European markets.
United States
Texas and Florida dental service organizations negotiate subscription-based replacement programs covering sterilization and automatic refresh. FDA 510(k) sterilization validation timelines stretch approval cycles to 18-24 months for reusable instruments. Hu-Friedy Mfg. Co., LLC leverages direct sales forces to sustain relationships with university dental programs and large clinic chains.
Japan
METI-backed periodontal disease screening programs expand covered maintenance visits at university-affiliated dental hospitals. PMDA medical device regulations align with international sterilization validation standards. Tokyo and Osaka metropolitan areas concentrate demand for precision hand instruments serving aging demographic treatment protocols.
Saudi Arabia
Cross-contamination elimination priorities in Riyadh and Jeddah dental chains drive demand for gamma-sterilized disposable alternatives. SFDA medical device registration requirements mirror EU MDR documentation burdens. King Faisal Specialist Hospital procurement frameworks set infection control standards across Gulf Cooperation Council markets.
Switzerland
Swissmedic certification requirements exceed EU baseline standards for reusable surgical instruments. Zurich and Geneva periodontal practices adopt carbon fiber-reinforced PEEK handle designs at accelerating rates. Precision instrument manufacturers in Basel-Land canton supply ergonomic-focused product lines to alpine European markets.
Gracey Curette Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precision-forged blade manufacturing. The vendor base arranges across three tiers: multinational dental conglomerates with broad instrument portfolios, mid-cap European precision forgers with regional lock-in, and specialized surface engineering shops extending autoclave cycle longevity. Consolidation pressures favor scale players with direct sales infrastructure, while regulatory documentation burdens filter smaller manufacturers from premium European procurement channels. Strategic moves center on sterilization validation partnerships and subscription-based replacement program negotiations with dental service organizations.
Among German-speaking European fabricators, Jakobi Dental GmbH exemplifies the precision-forging archetype with regional market anchoring. American Eagle Instruments represents specialized surface engineering capabilities targeting autoclave durability extension. Hu-Friedy Mfg. Co., LLC occupies the scale-driven platform position with university and large-chain direct sales relationships. These three archetypes—regional precision forger, technology specialist, and integrated platform—capture distinct margin pools across procurement channel segments.
| Leading Market Players |
|---|
| GDC Dental |
| ASA Dental |
| Hu-Friedy Mfg. Co., LLC |
| Jakobi Dental GmbH |
| Karl Schumacher Dental |
| Dentsply Sirona |
| American Eagle Instruments |
| Paradise Dental Technologies |
| LM-Instruments Oy |
| Others |
Supply & Pricing Matrix
Baden-Württemberg precision forging capacity constrains downstream pricing power for German-speaking European distributors facing MDR compliance deadlines. Stainless steel input cost swings transmit directly to instrument replacement program negotiations, compressing margin buffers for mid-tier manufacturers without surface engineering differentiation.
Pricing Analysis
Customization-premium spreads separate configured-to-order precision-forged instruments from catalog-standard equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and autoclave cycle longevity guarantees. Cost compression in standard stainless steel tiers intensifies because nickel price volatility feeds through surgical-grade alloy contracts. Dental service organizations in Texas and Florida exhibit lowest price sensitivity through subscription bundling, while independent German clinics face highest sensitivity due to reimbursement rate stagnation.
Supply Chain Analysis
Tariff exposure between Germany and United States dominates supply chain risk calculus for precision-forged instrument flows. Manufacturing gravity centers on Germany, United States, and Japan, with Baden-Württemberg and Bavaria housing master grinder apprenticeship clusters. Surgical-grade stainless steel, titanium nitride coating substrates, and carbon fiber-reinforced PEEK feedstock anchor raw material dependencies. Single-source vulnerability concentrates in European precision forging expertise facing generational attrition. Distribution runs through dental service organization procurement consortia and university-affiliated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gracey curette market structure rewards defensive moats built on regulatory entrenchment. FDA 510(k) sterilization validation timelines and MDR biocompatibility documentation create switching costs that protect incumbent relationships with dental clinics and hospital systems.
For Market Incumbents: Insulate market position through backward integration into titanium nitride coating deposition capacity and captive precision forging in Bavaria. Laser scaling systems threaten hand instrument volume in premium clinic segments. Vertical integration into surface engineering extends autoclave durability guarantees that differentiate against disposable alternatives. Certification investment in pre-submitted ECHA REACH dossiers filters competitor access to German and French distributor catalogs. For New Entrants and Emerging Players: Build out gamma-sterilized disposable curette production targeting Saudi Arabia and UAE dental chains where cross-contamination elimination priorities override autoclave infrastructure investment. Single-use instrument penetration remains lowest in Gulf Cooperation Council markets relative to developed European baselines. Direct hospital procurement relationships bypass distributor consolidation barriers that entrench legacy players. For Investors and Strategic Acquirers: Carve-out targets emerge from dental conglomerate instrument divisions facing portfolio rationalization pressure. Five-to-ten year viability hinges on subscription-based replacement program adoption among dental service organizations. Acquisition archetype: precision forgers with MDR-compliant documentation and university program relationships. Signal to watch: DSO procurement consortia consolidation velocity in Sun Belt states.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Documentation Investment | Pre-submitted ECHA dossiers secure German and French distributor catalog placement ahead of enforcement. |
| Subscription-Based Replacement Programs | Per-procedure fee structures lock in Texas and Florida DSO procurement consortia through automatic refresh guarantees. |
| Titanium Nitride Coating Capacity Expansion | PVD deposition in-house extends edge retention claims that justify premium positioning against standard stainless steel. |
| RFID-Enabled Instrument Tracking Systems | Automated sterilization cycle counting opens recurring SaaS revenue alongside hardware sales to hospital systems. |
| Master Grinder Apprenticeship Pipeline | Precision hand-finishing skill preservation defends blade offset geometry quality against generational attrition in European hubs. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with periodontal specialists, dental clinic procurement managers, biomedical engineers, and precision forging plant managers. Secondary validation drew from ISO standards repositories, GPO contract databases, and dental distributor catalog specifications. Bottom-up instrument shipment analysis triangulated against top-down periodontal procedure volume estimates across the analysis window.
Assumptions held sterilization validation timelines, nickel alloy pricing volatility bands, and dental reimbursement framework stability within observed historical patterns across the modeling period. Segmentation dimensions modeled include product type tier, application specialty, end-user channel, and material composition grade. CAGRs derived from procedure volume growth trajectories and instrument replacement cycle compression rates. Industry-specific inputs encompassed autoclave cycle longevity testing data and MDR compliance cost pass-through elasticity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by disposable curette specialists or breakthrough laser scaling efficacy would shift outcomes. Material shifts in FDA sterilization validation requirements, REACH nickel release enforcement severity, or DSO procurement consolidation velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Intrauterine Devices (IUD) Market