
 Italy Respiratory Devices Market | 2026-2036
Italy Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Respiratory Devices Market Foresight
Italian medical device manufacturing is hardening around respiratory specialization. Medtronic PLC sustains deep R&D investment in ventilator platforms. Koninklijke Philips NV anchors its European respiratory footprint through advanced sleep therapy systems. GE Healthcare competes on diagnostic-therapeutic integration across hospital networks.
Respiratory devices encompass mechanically or electrically powered apparatus designed to deliver, monitor, or assist pulmonary gas exchange, typically operating at flow rates between 5-60 L/min depending on clinical indication. These systems serve acute intervention, chronic disease management, and home-based therapeutic continuity. Inhalers and oxygen concentrators command established revenue pools due to COPD prevalence, while smart devices and portable solutions attract fastest-growing interest from homecare providers seeking remote monitoring capability. CPAP machines occupy a mature but margin-rich segment where technology leadership determines replacement cycles.
Italy's national health service operates under EU MDR compliance overseen by notified bodies, while the Ministry of Health enforces post-market surveillance through regional pharmacovigilance networks. The EU AI Act introduces additional scrutiny for algorithm-driven diagnostic features in smart respiratory platforms. Stakeholders must weigh MDR transition costs against the strategic value of AI-enabled remote patient monitoring capabilities.
Market Dynamics
EU MDR compliance timelines are compressing certification windows for Italian respiratory device manufacturers, forcing accelerated quality management system overhauls ahead of notified body capacity constraints.
Growth Catalysts
- COPD Prevalence:Chronic obstructive pulmonary disease burden across Lombardy and Veneto sustains institutional demand for oxygen concentrators and nebulizer systems in hospital and homecare settings.
- EU AI Act:Algorithm-enabled remote patient monitoring features in smart inhalers and CPAP platforms create regulatory pathways for premium device categories under emerging conformity assessment frameworks.
- Homecare Migration:Italy's regional health authorities are redirecting post-acute respiratory therapy from inpatient wards to domiciliary settings, expanding addressable device volume.
Market Restraints
- Notified Body Bottleneck:EU MDR designation delays for Italian manufacturers extend time-to-market for Class IIa and IIb respiratory devices by 12-18 months versus previous Medical Device Directive timelines.
- Semiconductor Input Volatility:Flow sensor and microcontroller supply concentration in East Asian foundries exposes Italian ventilator and sleep therapy producers to input cost swings and allocation rationing.
- Technical Limitation:Battery energy density constraints restrict portable oxygen concentrator runtime below clinical thresholds for ambulatory COPD patients requiring continuous flow above 3 L/min.
Strategic Opportunities
- Southern Italy Underpenetration:Campania, Sicily, and Calabria exhibit 40% lower respiratory device utilization rates per capita versus northern regions, presenting expansion targets for distribution network buildout.
- Telehealth Integration:Convergence of cellular-connected inhalers with regional electronic health record systems enables outcome-based reimbursement pilots by Tuscany and Emilia-Romagna health authorities.
- Pharmacy Channel Innovation:Direct-to-patient rental models for CPAP and oxygen therapy equipment through retail pharmacy networks bypass traditional hospital procurement bottlenecks.
Industry Challenges
- Biocompatibility Testing Backlog:ISO 10993 cytotoxicity and sensitization studies for polymer components in masks and tubing face laboratory capacity constraints, delaying technical file completion.
- Legacy System Integration:Hospital IT departments in Piedmont and Liguria struggle to integrate cloud-based respiratory device data streams with existing patient monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Respiratory Devices Market |
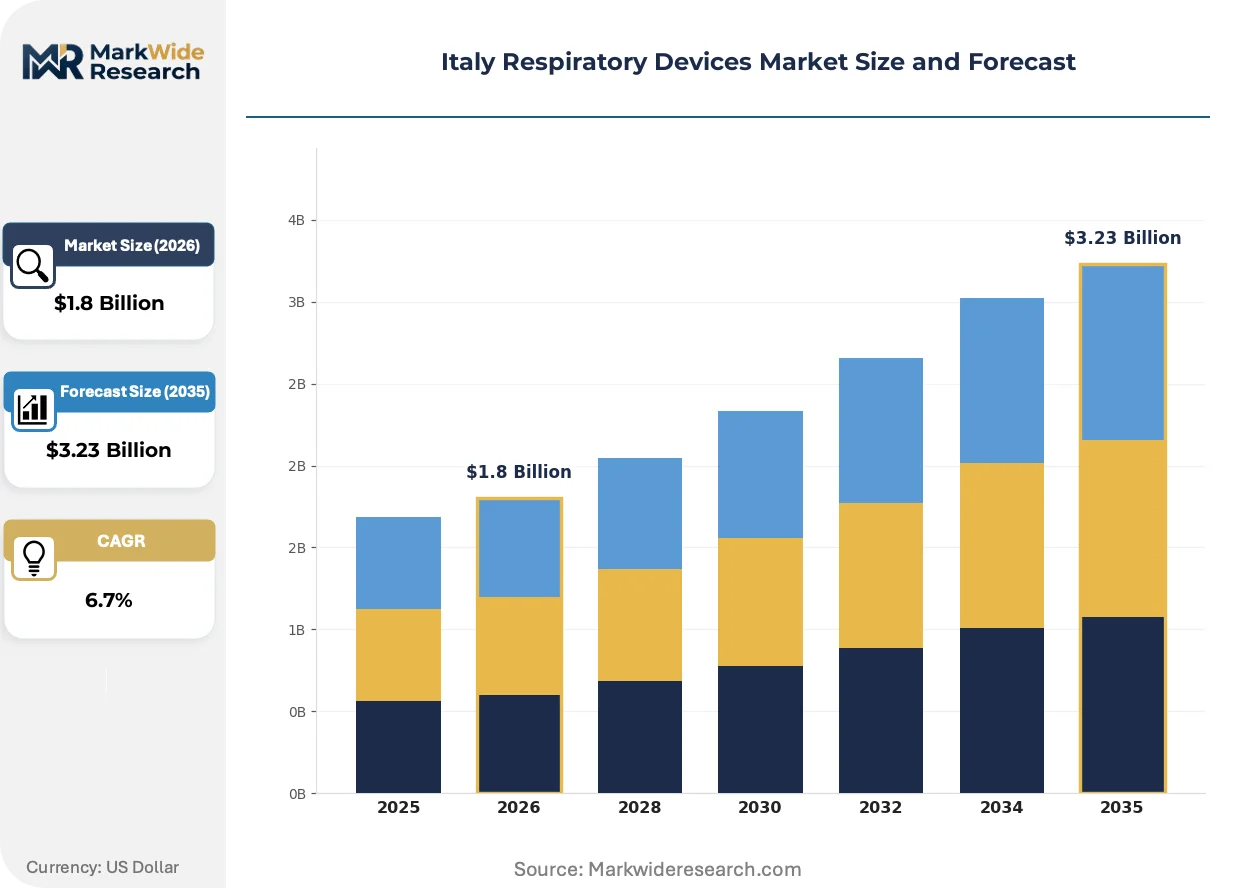
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, CPAP Machines End User: Hospitals, Homecare Settings, Rehabilitation Centers, Pharmacies Technology: Mechanically-Driven, Electrically-Powered, Smart Devices, Portable Solutions Application: Asthma Treatment, COPD Management, Sleep Apnea Therapy, Emergency Care |
| Companies Covered | GE Healthcare, Fisher & Paykel Healthcare Ltd, Medtronic PLC, Invacare Corporation, Dragerwerk AG, Koninklijke Philips NV, ICU Medical (Smiths Medical Inc), GlaxoSmithKline PLC, Fosun Pharmaceutical (Breas Medical AB), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Respiratory Devices Market Shifts & Advancements
Connected health architectures are reconfiguring how respiratory therapy is delivered, monitored, and reimbursed across Italian healthcare networks. Device intelligence and data interoperability now determine competitive positioning.
Portable oxygen concentrators with pulse-dose delivery algorithms are decentralizing acute respiratory support from hospital wards to patient homes. Homecare providers in Lombardy and Veneto are deploying these systems for early discharge programs. The technology is decentralizing clinical oversight responsibilities onto patients and family caregivers while compressing readmission-related revenue for inpatient facilities.
EU MDR Article 10 quality management system requirements are mandating enhanced post-market surveillance infrastructure for all respiratory device classes. Italian manufacturers must maintain systematic procedures for collecting and reviewing experience from devices in production. Class III implantable and active device categories face the steepest documentation burdens, with several notified bodies withdrawing from high-risk respiratory certification scopes.
Regional purchasing consortia across Italy's 20 autonomous health systems are consolidating procurement authority for high-volume respiratory consumables. Hospital networks in Emilia-Romagna and Tuscany now negotiate framework agreements covering nebulizer kits, oxygen cannulas, and filter assemblies for 3-5 year horizons. This concentration is squeezing distributor margins and favoring manufacturers with direct tendering capabilities and in-country technical service presence.
Italy Respiratory Devices Market Segmentation
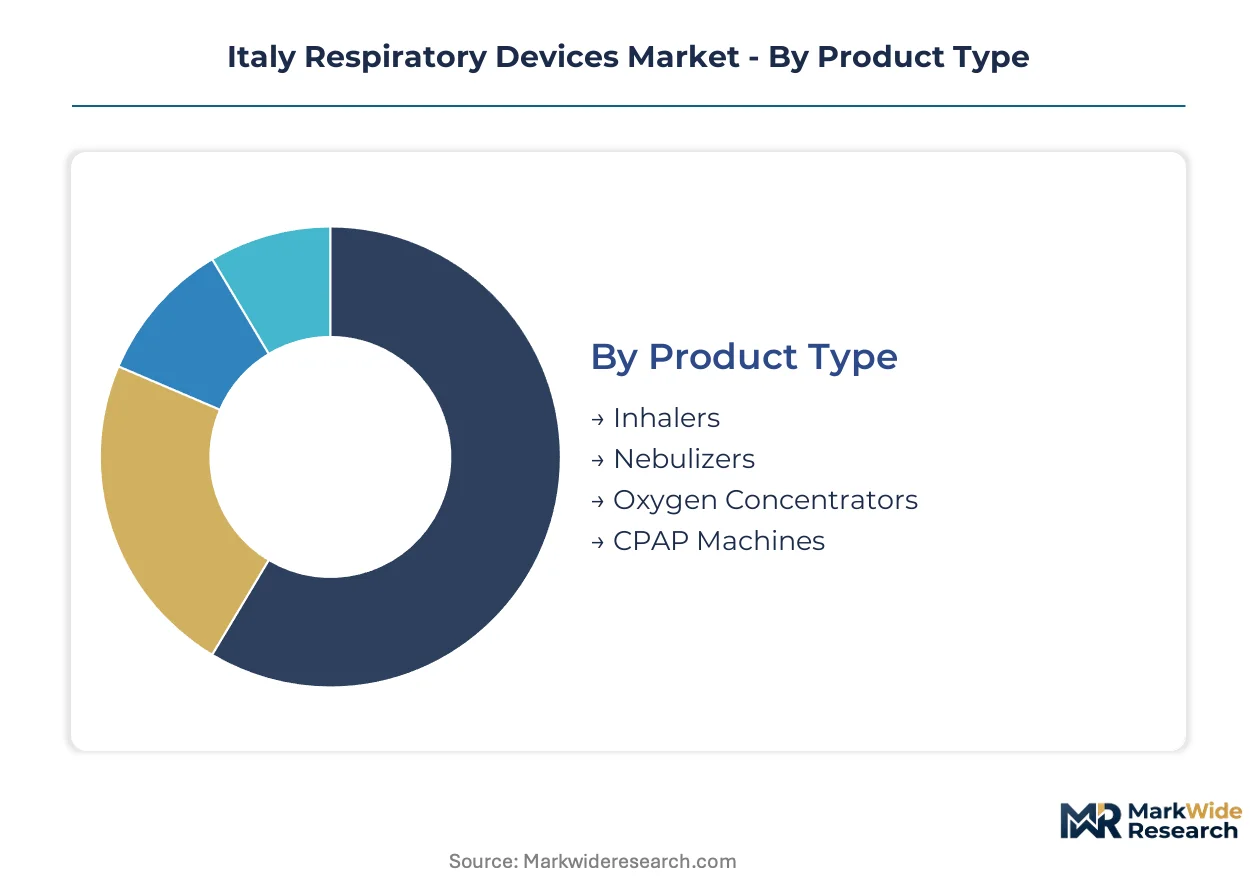
Respiratory device segmentation in Italy reflects divergent clinical workflows across acute and chronic care pathways. Product architecture, care setting, and connectivity requirements create distinct commercial battlegrounds for manufacturers navigating EU MDR compliance.
Product Type:
Customization intensity varies sharply across this category, from mass-produced metered-dose inhalers to patient-titrated CPAP platforms requiring individualized pressure algorithms.
- Inhalers:Pressurized canister systems and dry powder devices dominate ambulatory COPD and asthma maintenance. Demand concentrates in hospital outpatient clinics across Lombardy and Veneto where regional formularies drive procurement volume.
- Oxygen Concentrators:Molecular sieve technology extracts nitrogen from ambient air to deliver 90-96% oxygen at 1-5 L/min continuous flow. Homecare providers in Milan and Turin deploy these for post-acute discharge programs under regional health authority contracts.
- Nebulizers:Jet and ultrasonic variants aerosolize bronchodilator medications for patients with severe airflow limitation.
- CPAP Machines:Continuous positive airway pressure systems with heated humidification and auto-titrating algorithms serve obstructive sleep apnea patients.
Leading the category by volume: Inhalers. Growing fastest: CPAP Machines.
End User:
Cost tier stratification separates capital-intensive hospital installations from distributed homecare economics where rental models predominate.
- Hospitals:Intensive care units and respiratory wards deploy ventilators, high-flow nasal cannula systems, and invasive monitoring platforms. Procurement flows through regional purchasing consortia in Emilia-Romagna and Tuscany with 3-5 year framework agreements.
- Homecare Settings:Domiciliary oxygen therapy and sleep apnea management shift clinical oversight to patients and family caregivers. Regional health authorities in Lombardy redirect post-acute respiratory therapy from inpatient wards to home-based delivery.
- Rehabilitation Centers:Pulmonary rehabilitation programs utilize incentive spirometry and respiratory muscle training devices.
- Pharmacies:Retail networks in Campania and Sicily experiment with direct-to-patient rental models for CPAP and portable oxygen equipment.
Dominating procurement value: Hospitals. Expanding most quickly: Homecare Settings.
Technology:
Application context determines power architecture, from bedside AC-dependent systems to battery-operated ambulatory platforms.
- Smart Devices:Cellular-connected inhalers and cloud-integrated CPAP platforms transmit adherence data to regional electronic health record systems. Tuscany and Emilia-Romagna health authorities pilot outcome-based reimbursement for connected respiratory therapy.
- Portable Solutions:Pulse-dose oxygen concentrators and travel CPAP units with lithium-ion battery packs enable patient mobility. Battery energy density constraints restrict runtime below clinical thresholds for ambulatory COPD patients requiring continuous flow above 3 L/min.
- Mechanically-Driven:Pneumatic nebulizers and manual resuscitation bags operate without electrical power for emergency field deployment.
- Electrically-Powered:Compressor-based oxygen concentrators and fixed-installation ventilators require reliable AC supply.
Commanding premium pricing: Smart Devices. Climbing the fastest: Portable Solutions.
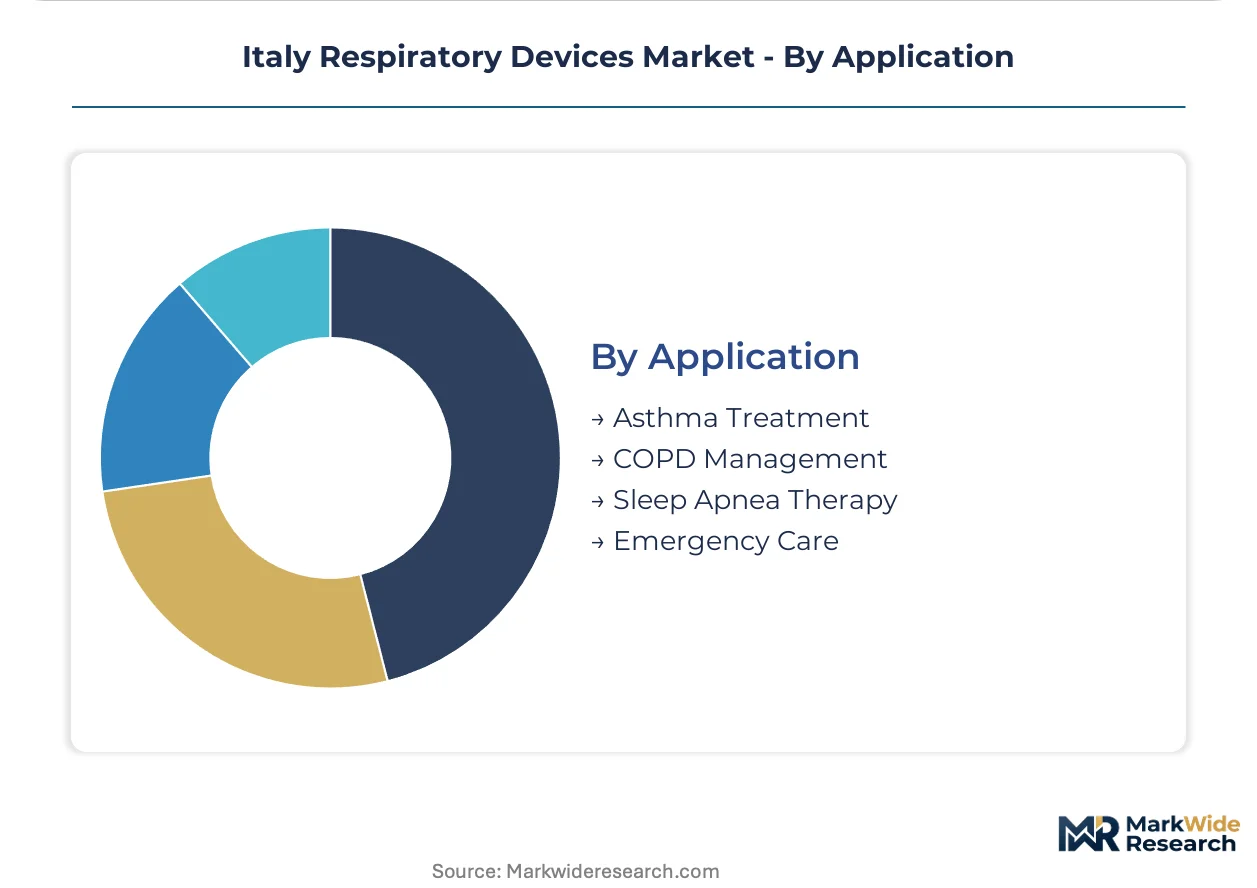
Application:
Patient volume and reimbursement intensity separate chronic maintenance indications from acute intervention scenarios.
- COPD Management:Chronic obstructive pulmonary disease represents the dominant clinical indication for long-term oxygen therapy and bronchodilator delivery. Disease burden across Lombardy and Veneto sustains institutional demand for oxygen concentrators and nebulizer systems.
- Sleep Apnea Therapy:Obstructive sleep apnea diagnosis drives CPAP machine utilization with replacement cycles determined by technology leadership in algorithm sophistication.
- Asthma Treatment:Pediatric and adult maintenance protocols rely on inhaled corticosteroid and bronchodilator delivery through metered-dose and dry powder devices.
- Emergency Care:Pre-hospital and emergency department interventions utilize mechanical ventilation and high-flow oxygen delivery for acute respiratory failure.
Generating highest device volume: COPD Management. Steepest expansion trajectory: Sleep Apnea Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan's concentration of polymer processors and precision component fabricators anchors northern Italy's respiratory device manufacturing base, with molecular sieve production and flow sensor assembly clustering across Lombardy and Piedmont industrial corridors.
Lombardy
Homecare oxygen concentrator deployments and CPAP rental networks concentrate around Milan's regional health authority procurement hubs. EU MDR notified bodies in the region process Class IIa and IIb respiratory device certifications under compressed timelines. Medtronic PLC maintains R&D facilities in Milan's life sciences district, anchoring ventilator platform development for European hospital networks.
Piedmont
Sleep apnea diagnostic volumes and pulmonary rehabilitation program referrals sustain device demand across Turin's hospital network. The Ministry of Health enforces post-market surveillance protocols through regional pharmacovigilance networks headquartered in the city. Manufacturing subcontractors in Turin's industrial periphery produce heated humidification chambers and polymer mask assemblies for EU-wide distribution.
Veneto
COPD prevalence in Padua and Verona drives institutional procurement of nebulizer systems and bronchodilator delivery platforms. Regional purchasing consortia negotiate 3-5 year framework agreements covering high-volume respiratory consumables. Cloud-integrated CPAP platforms from Philips anchor telehealth pilots with Veneto's electronic health record infrastructure.
Emilia-Romagna
Outcome-based reimbursement pilots for connected inhalers operate through Bologna's regional health authority, linking cellular device data to clinical payment models. The EU AI Act introduces additional conformity assessment layers for algorithm-driven diagnostic features in smart respiratory platforms. GE Healthcare competes on diagnostic-therapeutic integration across hospital networks in Modena and Parma.
Campania
Pharmacy channel rental models for portable oxygen equipment bypass traditional hospital procurement bottlenecks in Naples and surrounding provinces. Underpenetration versus northern regions creates expansion targets for distribution network buildout. Regional health authorities redirect post-acute respiratory therapy from inpatient wards to domiciliary settings, expanding addressable device volume.
Italy Respiratory Devices Market Competitive Landscape
Global majors compete with regional champions across certification capability and homecare service infrastructure. The vendor base organizes into three tiers: diversified healthcare conglomerates with full respiratory portfolios, mid-scale specialists concentrating on sleep therapy or oxygen delivery, and regional distributors with technical service presence. Strategic moves center on MDR transition acceleration and telehealth platform integration rather than price competition.
Among diversified healthcare conglomerates, Medtronic PLC, Koninklijke Philips NV, and GE Healthcare exemplify the integrated-device-and-data archetype. These entities occupy positions where ventilator platform sophistication, sleep therapy algorithm development, and diagnostic-therapeutic system integration determine replacement cycle capture. Their scale enables direct tendering with Italy's regional purchasing consortia and sustained investment in EU MDR quality management system overhauls ahead of notified body capacity constraints.
| Leading Market Players |
|---|
| GE Healthcare |
| Fisher & Paykel Healthcare Ltd |
| Medtronic PLC |
| Invacare Corporation |
| Dragerwerk AG |
| Koninklijke Philips NV |
| ICU Medical (Smiths Medical Inc) |
| GlaxoSmithKline PLC |
| Fosun Pharmaceutical (Breas Medical AB) |
| Others |
Supply & Pricing Matrix
Molecular sieve miniaturization in portable oxygen concentrators is compressing unit economics while concentrating procurement leverage among Lombardy-based homecare providers. This technology shift simultaneously reduces per-device material costs and elevates service-bundling premiums for remote monitoring capabilities.
Pricing Analysis
Warranty and technical service bundling separates premium CPAP platforms from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks EU MDR certification grade and algorithm sophistication. Cost compression in economy tiers is intensifying because regional purchasing consortia negotiate multi-year framework agreements. Homecare providers in Campania and Sicily exhibit highest price sensitivity, while hospital networks in Emilia-Romagna prioritize connectivity features over unit cost.
Supply Chain Analysis
EU MDR quality management system certification gates component sourcing for polymer mask assemblies and heated humidification chambers. Molecular sieve materials draw from China and the USA, while flow sensors and microcontrollers rest on Taiwan and South Korea foundries. Single-source vulnerability in East Asian semiconductor supply exposes Italian ventilator producers to allocation rationing. Distribution runs through regional purchasing consortia in northern Italy and direct pharmacy rental networks in the south.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints for EU MDR Class IIb respiratory device certifications prop pricing power for manufacturers with existing conformity assessments. This supply-constrained environment favors incumbents with completed technical files.
For Market Incumbents: Anticipate margin pressure from cloud-native entrants by securing backward integration into polymer mask production and molecular sieve assembly. Prioritize certification investment for algorithm-driven diagnostic features ahead of EU AI Act implementation. Channel control through direct tendering relationships with Tuscany and Emilia-Romagna purchasing consortia anchors replacement cycle capture. For New Entrants and Emerging Players: Launch via pharmacy channel rental models in Campania and Sicily where hospital procurement bottlenecks exclude established vendors. Target underpenetrated southern regions with portable oxygen concentrators featuring simplified patient interfaces. White-space concentration in domiciliary sleep apnea therapy offers fastest penetration pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified healthcare conglomerates seeking EU MDR-certified respiratory portfolios. Long-term viability hinges on telehealth platform integration capabilities and direct regional health authority contracting relationships. Watch notified body designation expansion rates as inflection indicator for certification backlog resolution.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical file completion unlocks access to Lombardy and Veneto procurement frameworks. |
| Hospital System Partnership | Direct integration with Emilia-Romagna electronic health records enables outcome-based reimbursement pilots. |
| Software Companion Development | Cloud-based adherence monitoring for CPAP platforms differentiates against pneumatic-only competitors. |
| Backward Integration | In-house polymer mask production shields margins from ISO 10993 testing laboratory capacity constraints. |
| Reimbursement Strategy | Alignment with Tuscany regional health authority telehealth pilots accelerates homecare device adoption. |
Research Methodology
Document review covered EU MDR guidance documents, notified body designation records, and regional health authority procurement databases, complemented by interviews with respiratory device product managers, hospital biomedical engineers, GPO contracts managers, and homecare provider operations directors. Secondary sources included Ministry of Health pharmacovigilance reports, Lombardy regional purchasing consortium tenders, and ISO 10993 biocompatibility testing standards. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure allocations.
Cross-referencing historical certification timelines with expert panel input on notified body capacity constraints shaped the analytical framework. Segmentation modeling tracked product type, end user setting, technology architecture, and clinical application across the projection horizon. CAGRs derived from patient population epidemiology, replacement cycle assumptions, and regional reimbursement policy trajectories. Forecast inputs incorporated COPD prevalence projections and sleep apnea diagnosis rates by Italian region.
Notified body withdrawal from high-risk respiratory scopes, semiconductor supply allocation disruptions, and EU AI Act implementation delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding MDR transition timelines and regional health authority budget trajectories. A model refresh is warranted upon material change in notified body designation capacity or EU AI Act conformity assessment finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical AR Systems Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Silastic Implant Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
EEG Amplifiers Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Global Bowel Management System Market
Medical Devices
US Nebulizer Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market