
 Tumor Ablation Market | 2026-2036
Tumor Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor Ablation Market Intelligence
The specialized training required for interventional radiologists is reorganizing how ablation procedures are adopted and scaled across healthcare systems. Medtronic leverages its extensive clinical training programs and global distribution network to support device adoption. Johnson & Johnson competes through its broad portfolio of surgical oncology tools, integrating ablation with other treatment modalities. Boston Scientific differentiates with its focus on developing advanced radiofrequency and microwave ablation systems for specific tumor types.
Tumor ablation encompasses minimally invasive procedures that destroy cancerous tissue using targeted energy or chemical agents. These methods, which include applying radiofrequency waves with specific frequencies to induce thermal coagulation, offer a crucial alternative to surgical resection. The product landscape shows radiofrequency and microwave ablation as mature technologies commanding significant market share. Liver and kidney tumor applications drive substantial volume, with hospitals and dedicated cancer treatment centers serving as the primary end-user locations.
Market access for new ablation devices is governed by stringent regulatory approvals from bodies like the US FDA, Europe's EMA under the Medical Device Regulation (MDR), and China's NMPA. These agencies mandate extensive clinical data to validate the safety and efficacy of devices before they can be commercialized. Consequently, navigating the evolving reimbursement policies and securing coverage for new indications will be a critical determinant of future market penetration for manufacturers.
Market Dynamics
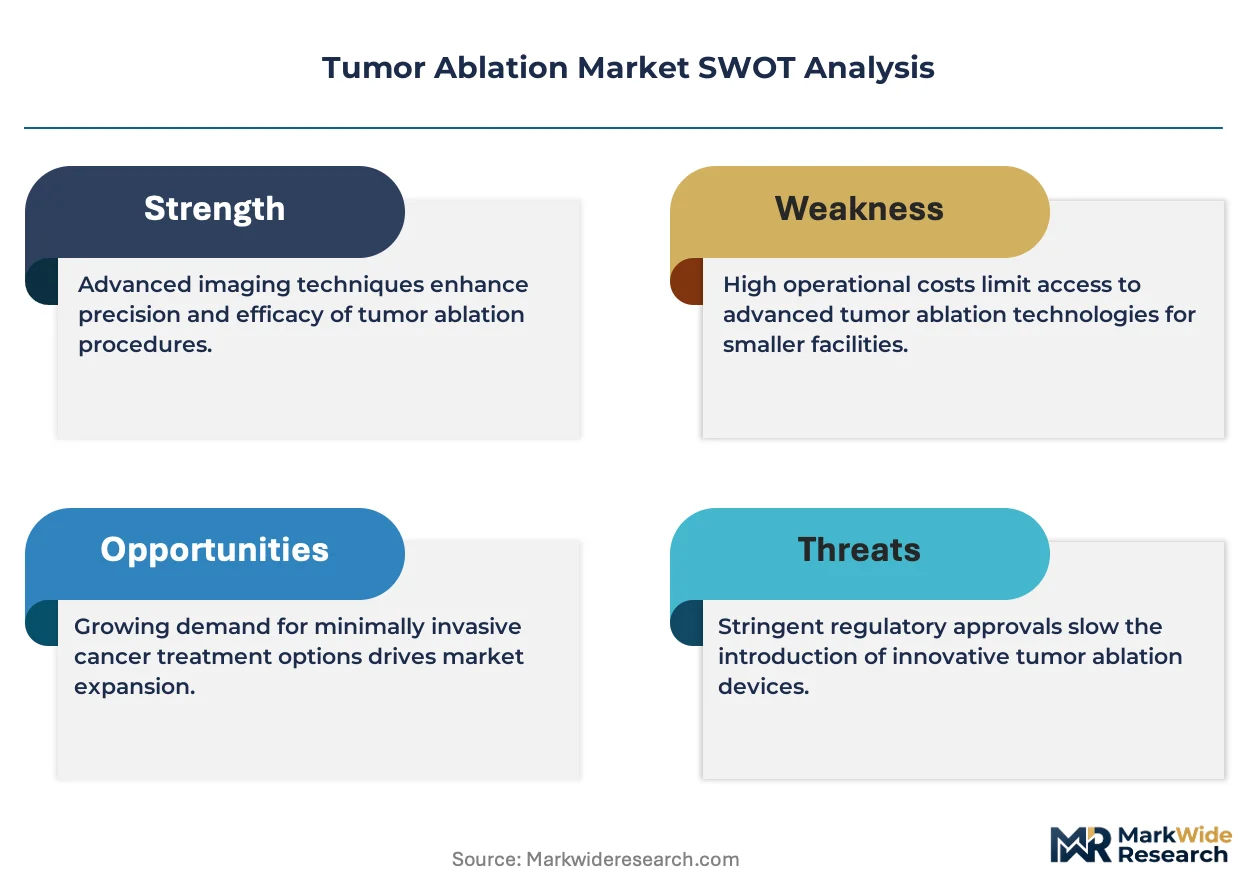
The central structural force shaping the tumor ablation market is the convergence of advanced imaging technologies with minimally invasive therapeutic devices. This integration enables real-time guidance, enhancing treatment precision and expanding the addressable patient population beyond traditional surgical candidates.
Growth Catalysts
- Value-Based Healthcare Models:Policy shifts in geographies like the United States towards reimbursement models that reward better patient outcomes and lower total costs favor minimally invasive ablation procedures over more expensive, invasive surgeries.
- Advanced Imaging Integration:The incorporation of technologies like CT-fluoroscopy, MRI-guidance, and AI-powered image analysis into ablation workflows improves targeting accuracy, reduces procedure times, and enhances safety for complex tumor locations.
- Rising Cancer Incidence in Aging Populations:A growing elderly population worldwide, which often presents with comorbidities unsuitable for major surgery, increases the clinical demand for less invasive cancer treatment alternatives like tumor ablation.
Market Restraints
- High Capital Investment:The substantial upfront cost for acquiring and maintaining sophisticated ablation systems, including generators and imaging equipment, presents a significant financial barrier for smaller hospitals and clinics.
- Stringent Regulatory Hurdles:Navigating the complex and lengthy approval processes of bodies like the US FDA and complying with Europe's Medical Device Regulation (MDR) delays the commercialization of new devices.
- Competition from Systemic Therapies:The rapid advancement and efficacy of immunotherapies and targeted drug therapies in oncology present a powerful alternative to local treatments, potentially reducing the patient pool for ablation.
Strategic Opportunities
- Expansion in Emerging Economies:Significant healthcare infrastructure investments in Southeast Asian and Latin American countries create new market entry points for ablation device manufacturers as cancer care capabilities expand.
- Ablation-Immunotherapy Combination:Combining tumor ablation with systemic immunotherapies to stimulate a host anti-tumor immune response, known as an abscopal effect, represents a promising new therapeutic paradigm.
- New Clinical Indications:Research into the application of ablation technologies for treating benign conditions, such as uterine fibroids or benign prostatic hyperplasia, and for pain palliation opens new revenue streams.
Industry Challenges
- Interventional Radiologist Skill Gap:A shortage of interventional radiologists with the specialized training required to perform complex, image-guided ablation procedures limits the scalability of these services across healthcare systems.
- Reimbursement Variability:Inconsistent and often inadequate reimbursement codes for novel ablation procedures across different countries and even within regions of the US complicates financial planning for providers.
- Lack of Protocol Standardization:The absence of universally accepted treatment protocols and outcome reporting standards across different ablation modalities hinders the comparison of clinical data and slows widespread adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor Ablation Market |
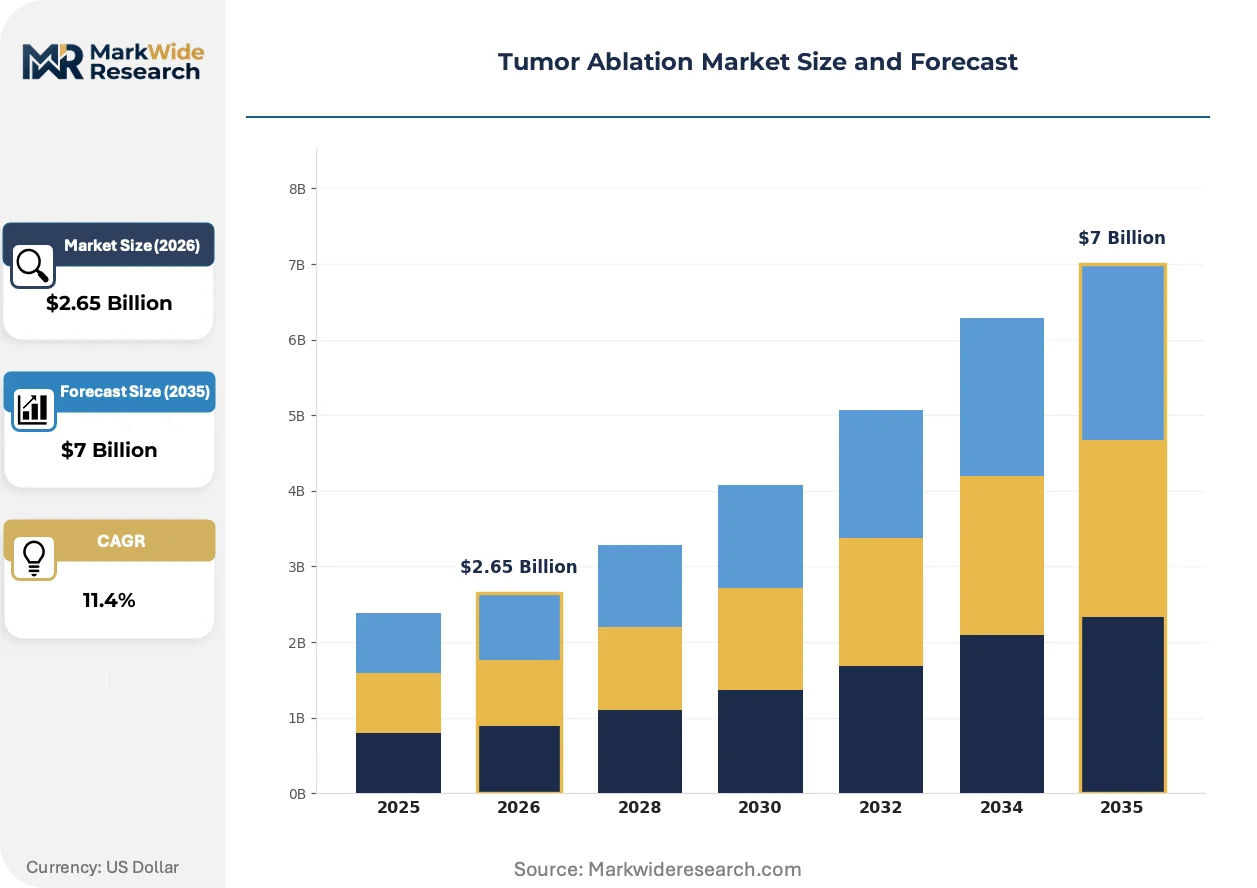
| Market Size in 2026 | $2.65 Billion |
| Market Size in 2035 | $7 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Microwave, Cryoablation, Laser, High-Intensity Focused Ultrasound, Chemical Ablation Application: Liver Tumors, Lung Tumors, Kidney Tumors, Bone Tumors, Prostate Tumors, Pancreatic Tumors End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Cancer Treatment Centers, Diagnostic Imaging Centers Technology: Imaging-Guided, Ultrasound-Guided, CT-Guided, MRI-Guided, Electromagnetic Tracking |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific, AngioDynamics, Stryker, Olympus Corporation, Bioventus, Merit Medical Systems, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor Ablation Market Strategic Shifts & Innovations
A fundamental shift toward non-thermal and ultra-precise ablation methods is defining the next generation of locoregional cancer therapy. This evolution prioritizes tissue preservation and the ability to treat tumors adjacent to critical structures, expanding the scope of minimally invasive oncology.
Irreversible electroporation (IRE) is a non-thermal ablation technology that uses high-voltage electrical pulses to induce apoptosis in cancer cells. Major academic cancer centers are adopting IRE for tumors near vital organs and blood vessels where thermal damage is unacceptable. This technology is supplanting older thermal techniques in complex cases due to its unique ability to spare surrounding connective tissue and structures.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance on all medical devices. This regulation increases the development timeline and cost for manufacturers seeking to introduce new ablation systems into the European market. Consequently, device companies are embedding rigorous clinical data collection into their product lifecycle from the outset to meet these heightened standards.
Ambulatory surgical centers (ASCs) are increasingly becoming the site of care for routine tumor ablation procedures, a shift from the traditional inpatient hospital setting. This change is propelled by payor policies encouraging lower-cost outpatient services and by patient demand for more convenient treatment options. This trend is most visible in the United States, where ASCs represent a key growth segment for manufacturers of portable ablation equipment.
Tumor Ablation Market Segmentation
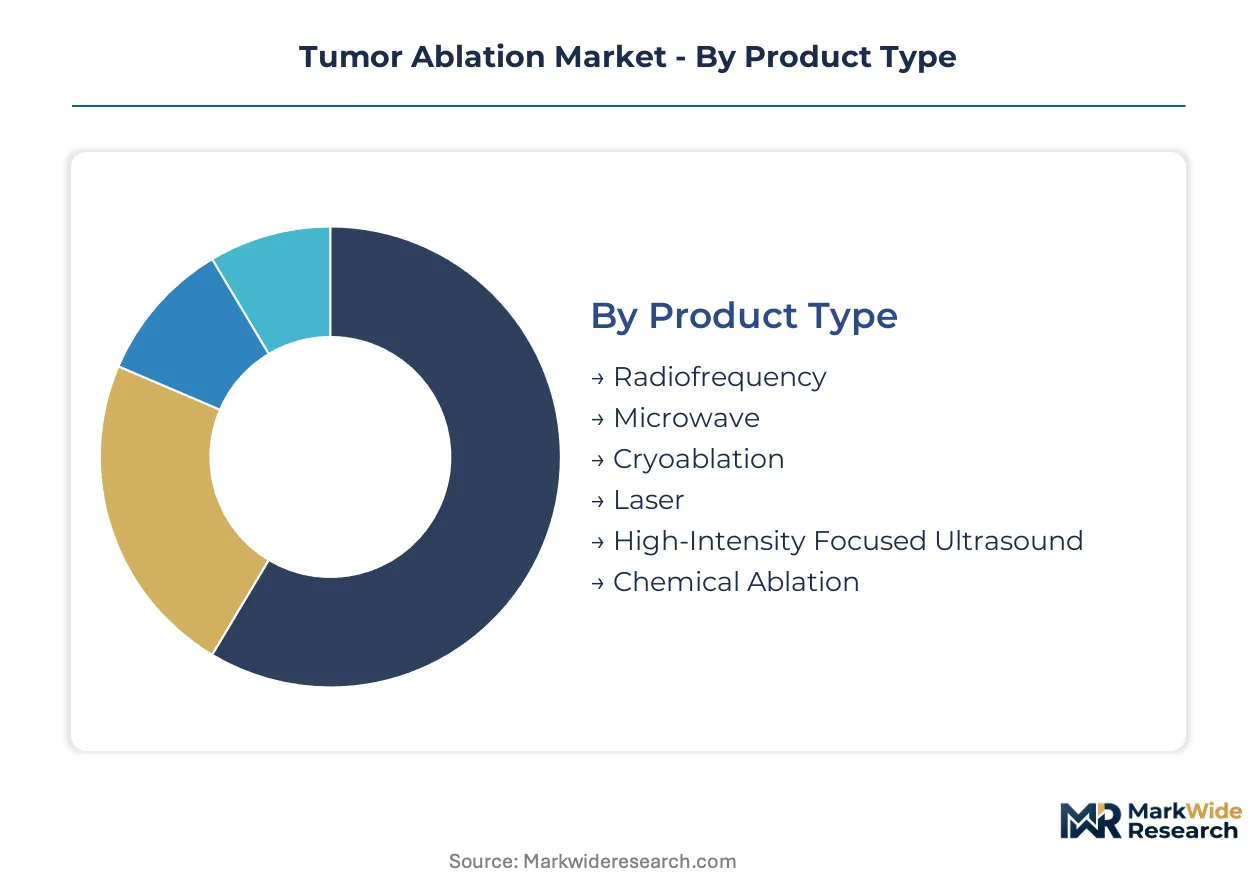
The tumor ablation market's segmentation reveals distinct drivers and technological focuses across various treatment modalities and clinical applications. Understanding these segments provides clarity on resource allocation and strategic investment opportunities for device manufacturers. Each category reflects specific patient needs and healthcare infrastructure capabilities.
Product Type:
Margin pools within product types often concentrate in advanced, non-thermal ablation systems due to their precision and reduced collateral damage. These technologies command premium pricing reflecting their development costs and specialized clinical utility.
- Radiofrequency:Radiofrequency ablation uses high-frequency alternating current to generate heat, inducing thermal coagulation. Demand concentrates in established hospital settings across Europe and the United States for liver and kidney tumors.
- Microwave:Microwave ablation employs electromagnetic waves to create frictional heat, achieving larger, faster ablation zones. Its clinical application expands in China's modern cancer treatment centers for larger tumors.
- Cryoablation:Cryoablation uses extreme cold to destroy cancerous cells, preserving surrounding collagenous structures.
- Laser:Laser ablation delivers focused light energy to induce thermal destruction of tumor tissue, particularly for smaller lesions.
- High-Intensity Focused Ultrasound:High-Intensity Focused Ultrasound (HIFU) is a non-invasive method using focused acoustic energy to thermally ablate tumors.
- Chemical Ablation:Chemical ablation involves injecting substances like ethanol directly into tumors to induce cellular necrosis.
The dominant share belongs to Radiofrequency, while Microwave is closing the gap fastest.
Application:
Application segmentation highlights varying treatment complexities and associated costs, influencing reimbursement strategies and device development priorities. Procedures for highly vascularized organs often require specialized tools.
- Liver Tumors:Ablation for liver tumors represents significant volume, used for hepatocellular carcinoma and metastatic lesions unsuitable for surgery. Demand is substantial in China and Japan, driven by advanced imaging integration.
- Kidney Tumors:Kidney tumor ablation offers a minimally invasive option for small renal masses, preserving renal function. Its adoption is high in the United States and Germany, supported by favorable reimbursement policies.
- Lung Tumors:Lung tumor ablation treats primary or metastatic lung lesions, especially for patients with compromised lung function.
- Bone Tumors:Bone tumor ablation provides pain palliation and local tumor control for primary or metastatic bone lesions.
- Prostate Tumors:Prostate tumor ablation uses targeted energy to destroy cancerous tissue within the prostate gland.
- Pancreatic Tumors:Pancreatic tumor ablation addresses difficult-to-treat lesions, often for local control or pain management.
Liver and Kidney tumor applications collectively constitute the largest segment of ablation procedures, with growing interest in pancreatic tumor treatment.
End User:
End-user segmentation reflects the volume and complexity of procedures performed, influencing equipment design and service support requirements. Larger facilities handle a broader range of cases.
- Hospitals:Hospitals serve as primary end-users due to their comprehensive infrastructure, including advanced imaging suites and multidisciplinary teams. They manage complex cases across various tumor types in countries like France and Canada.
- Ambulatory Surgical Centers:Ambulatory Surgical Centers (ASCs) increasingly perform routine tumor ablation procedures, driven by payor policies for lower-cost outpatient services. This shift is notable in the United States and Australia.
- Specialty Clinics:Specialty clinics focus on specific cancer types or ablation modalities, offering specialized expertise.
- Cancer Treatment Centers:Dedicated cancer treatment centers integrate ablation into comprehensive oncology care pathways, often conducting clinical research.
- Diagnostic Imaging Centers:Diagnostic imaging centers primarily support procedural guidance, sometimes offering limited ablation services for straightforward cases.
Hospitals remain the largest segment, but Ambulatory Surgical Centers are experiencing significant growth due to cost efficiencies and patient preferences.
Technology:
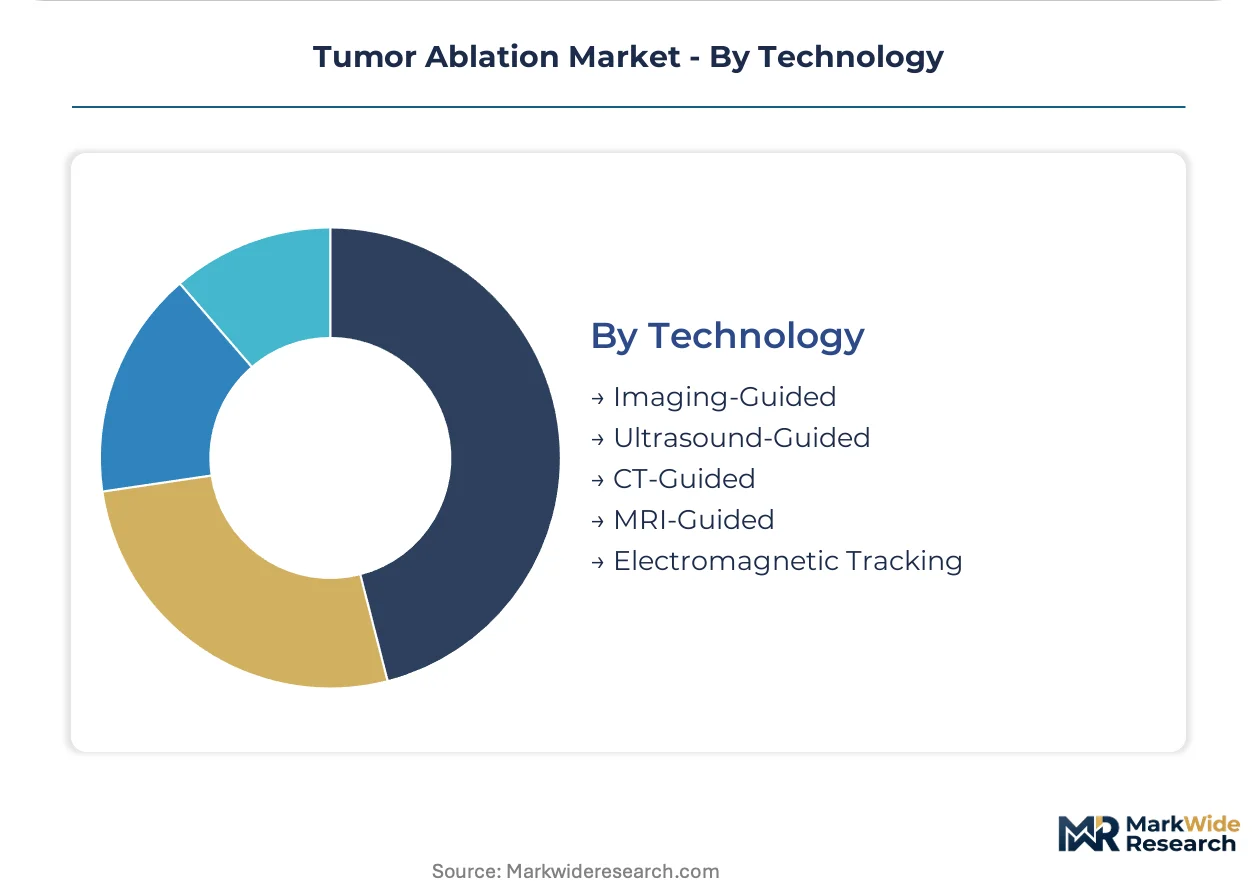
Technology segmentation highlights areas of supply concentration, driven by intellectual property and specialized manufacturing capabilities. Advanced imaging integration defines the precision of modern ablation.
- CT-Guided:CT-guided ablation utilizes computed tomography for precise real-time visualization of tumor location and needle placement. This enhances accuracy for deep-seated tumors and is widely adopted in Germany and Japan.
- MRI-Guided:MRI-guided ablation employs magnetic resonance imaging, offering superior soft tissue contrast for precise targeting and real-time thermal monitoring. Its use expands in academic centers in the United Kingdom and Sweden.
- Ultrasound-Guided:Ultrasound-guided ablation provides real-time visualization, offering a cost-effective and portable guidance method.
- Imaging-Guided:Imaging-guided technologies broadly encompass all modalities that provide visual assistance during ablation procedures.
- Electromagnetic Tracking:Electromagnetic tracking systems enhance navigation accuracy for ablation probes, particularly in areas with respiratory motion.
Imaging-guided techniques form the foundation of modern ablation, with CT-guided and MRI-guided systems leading advancements in precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA mandates extensive clinical data for new device market access, influencing the tumor ablation landscape. The global market experiences varied adoption rates, driven by healthcare infrastructure and specific regulatory frameworks. Precision in treatment is a universal demand.
China
Demand for microwave ablation is high in China, driven by modern cancer treatment centers handling larger tumors. The NMPA's accelerated approval pathways for innovative medical devices support market entry and rapid commercialization. Major investments in Beijing and Shanghai are expanding advanced oncology capabilities and increasing procedure volumes.
United States
Value-based healthcare models in the United States favor minimally invasive ablation procedures. The US FDA's stringent approval process ensures device safety and efficacy before market introduction. Key medical hubs like Boston and Houston are centers for clinical trials and technology adoption.
Germany
Germany exhibits high adoption of CT-guided ablation for deep-seated tumors, driven by advanced imaging integration. Europe's EMA, under the Medical Device Regulation (MDR), imposes stricter requirements for clinical evidence. University hospitals in Munich and Berlin are leading centers for precision ablation techniques.
Japan
Japan shows substantial demand for liver tumor ablation, supported by advanced imaging integration and an aging population. The PMDA regulates medical devices, focusing on safety and clinical utility for new technologies and indications. Major medical institutions in Tokyo and Osaka are pioneering new ablation protocols for complex cases.
United Kingdom
The United Kingdom is expanding MRI-guided ablation use in academic centers, particularly for soft tissue contrast. The EMA's Medical Device Regulation (MDR) also impacts device availability and post-market surveillance in the UK. London and Manchester medical facilities are at the forefront of combining ablation with immunotherapy.
Tumor Ablation Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the tumor ablation market structure. These integrated leaders offer broad portfolios, while specialized innovators focus on niche technologies like non-thermal ablation for specific indications. Portfolio diversification across treatment modalities remains a key strategic archetype for major players. Geographic expansion into emerging economies also represents a dominant competitive move, alongside strategic partnerships to enhance technological reach.
On the integrated-leader vector, Medtronic and Johnson & Johnson exemplify companies with extensive clinical training programs and broad surgical oncology portfolios. These global entities utilize their vast resources to integrate ablation with other treatment modalities. Boston Scientific Corporation, a US-based entity, sits within the specialized innovator archetype, focusing on advanced radiofrequency and microwave ablation systems for specific tumor types. These companies leverage their established distribution networks to support device adoption across diverse healthcare settings, influencing market penetration and technology diffusion.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific |
| AngioDynamics |
| Stryker |
| Olympus Corporation |
| Bioventus |
| Merit Medical Systems |
| Integra LifeSciences |
| Others |
Cost & Logistics Intelligence
Europe's Medical Device Regulation (MDR) significantly gates device supply qualification and influences price differentiation across the tumor ablation market. This stringent regulatory environment ensures device safety while impacting market entry costs for manufacturers.
Pricing Analysis
Geographic price spreads for tumor ablation devices vary significantly, reflecting diverse healthcare system structures and reimbursement policies. The dominant pricing model is per-unit transactional for devices, influenced by associated procedure costs. Price differentiation stems from technology precision, such as non-thermal capabilities, and stringent regulatory approval tiers from bodies like the US FDA. Pricing pressure intensifies from value-based healthcare models, which prioritize cost-effective outcomes, making Ambulatory Surgical Centers more price-sensitive than large university hospitals.
Supply Chain Analysis
Strategic stockpiling of critical components, rather than just-in-time delivery, characterizes the tumor ablation device supply chain due to specialized manufacturing requirements. Geographic supply concentration includes Germany for advanced medical optics, the United States for high-end imaging components, and China for certain consumable parts. Raw material dependencies include specialized metals for probes and high-purity electrical components for energy generators. Regulatory restrictions, particularly Europe's MDR, represent a structural risk by adding complexity and cost. Distribution typically runs through direct sales forces to hospitals and specialized distributors for smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tumor ablation market requires a strong substitution defense, as the rapid advancement of systemic immunotherapies and targeted drug therapies presents a powerful alternative to local treatments. Incumbents must continually innovate to maintain relevance.
For Market Incumbents:Secure leadership by expanding clinical training programs for interventional radiologists, mitigating the skill gap threat. Integrate ablation technologies with advanced imaging systems and AI-powered analysis to enhance precision and demonstrate superior outcomes. Invest in research and development for non-thermal ablation and combination therapies with immunotherapies, addressing the competition from systemic treatments. Control distribution channels to ensure broad access and support for complex device installations.
For New Entrants and Emerging Players:Anchor in underserved geographic markets like Southeast Asian economies, where healthcare infrastructure investments create new entry points. Target new clinical indications, such as benign conditions like uterine fibroids or pain palliation, offering specialized solutions. Develop portable ablation equipment suitable for Ambulatory Surgical Centers, capitalizing on the shift towards outpatient care. A go-to-market angle focused on cost-effectiveness and ease of use in these specific niches will facilitate adoption.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting in an upward direction across advanced non-thermal ablation sub-segments, reflecting high R&D and regulatory costs. The long-term viability of tumor ablation remains strong, positioned as an essential tool within comprehensive oncology care pathways over the next decade. Target acquisition archetypes include specialized firms developing novel non-thermal technologies or those integrating AI-powered imaging guidance. The signal to watch is the expansion of reimbursement policies for combination ablation-immunotherapy treatments.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Training Expansion | Addresses interventional radiologist skill gaps, directly supporting broader device adoption and procedure scalability. |
| Advanced Imaging Integration | Enhances treatment precision and safety for complex tumor locations, expanding the addressable patient population. |
| Non-Thermal Ablation R&D | Develops precise methods like IRE, preserving tissue near critical structures and expanding treatment options. |
| Emerging Market Entry | Captures demand from significant healthcare infrastructure investments in regions like Southeast Asia. |
| Reimbursement Strategy Development | Secures coverage for novel ablation procedures and new indications, critical for market penetration. |
Research Approach
Desk research of medical journal databases, regulatory filings (US FDA, Europe's EMA, China's NMPA), and industry reports preceded structured interviews with interventional radiologists, hospital procurement managers, device R&D leads, and regulatory affairs specialists. This approach combined primary insights with secondary validation, ensuring a robust data foundation. Bottom-up market sizing was triangulated with top-down validation against total healthcare expenditure trends.
Variance decomposition across the analysis window identified key drivers impacting tumor ablation market growth. Segmentation dimensions modeled included product type, application, end-user, technology, and major geographic regions. Compound annual growth rates were derived through multi-variable regression analysis. Cancer incidence rates and healthcare expenditure growth served as critical industry-specific forecast inputs.
Material uncertainties — including unforeseen regulatory policy shifts, new therapeutic breakthroughs, or significant changes in reimbursement structures — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis. Revision becomes warranted when key market dynamics or clinical practice guidelines cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Oncology Devices Market
Oncology
Bone Metastasis Market
Oncology
Europe Radiotherapy Market
Oncology
Testicular Cancer Treatment Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Metastatic Breast Cancer Market
Oncology
Glioblastoma Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Solid Tumor Market
Oncology
Hadron Therapy Market
Oncology
Pituitary Cancer Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Pancreatic Cancer Market
Oncology
Paranasal Sinus Cancer Market