
 Global Scleral Lens Market | 2026-2036
Global Scleral Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scleral Lens Market Foresight
Certified scleral lens fitters is rotating from shortage toward managed expansion as training programs at academic medical centers scale output. Bausch + Lomb leverages its integrated manufacturing network to sustain bulk supply of oxygen-permeable materials. Visionary Optics specializes in custom toric and multifocal designs for irregular cornea patients. Blanchard Contact Lenses dominates the independent practitioner channel through direct technical support and fitting consultation.
A scleral lens is a large-diameter rigid gas permeable contact lens that vaults entirely over the cornea and rests on the sclera, typically measuring 14.5–25 mm in diameter with oxygen transmissibility exceeding 100 Dk/t to maintain corneal health during extended wear. The device serves primarily to correct vision in patients with corneal irregularities while protecting the ocular surface through a fluid-filled reservoir. Rigid gas permeable designs anchor the value pool due to established reimbursement and proven clinical outcomes, though custom-made segments attract premium pricing for complex ectasia cases. Keratoconus applications lead volume as screening rates improve, while dry eye syndrome represents the fastest-growing indication as meibomian gland dysfunction diagnoses expand among digital device users.
FDA 510(k) pathways govern US market entry for scleral lenses as Class II medical devices, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for custom ophthalmic devices. Japan's PMDA maintains distinct pharmaceutical and medical device classifications that shape registration timelines for foreign manufacturers. Stakeholders must monitor evolving ISO 18369 standards for contact lens biocompatibility testing as regulators tighten post-market surveillance expectations.
Market Dynamics
The Global Scleral Lens Market pivots on oxygen-permeable polymer innovation, where Dk/t thresholds above 100 now define clinical viability and reimbursement eligibility across major prescribing markets.
Growth Catalysts
- FDA 510(k) Clearance Pathway:Streamlined Class II medical device review accelerates custom lens introductions for irregular cornea indications in the United States.
- Corneal Ectasia Screening:Improved diagnostic imaging protocols expand addressable patient pools among specialty contact lens practitioners.
- Meibomian Gland Dysfunction:Digital device usage drives dry eye syndrome diagnoses, creating fluid-filled reservoir demand for ocular surface protection.
Market Restraints
- Silicone-Hydrogel Raw Material Concentration:Limited qualified polymer suppliers create input cost volatility and supply security exposure.
- EU MDR Clinical Evidence Burden:Stricter biocompatibility documentation requirements extend registration timelines for custom ophthalmic devices.
- Soft Toric Lens Substitution:Advances in disposable soft lens technology capture mild-to-moderate astigmatism cases outside specialty care.
Strategic Opportunities
- Japan PMDA Registration:Distinct pharmaceutical-medical device classification system offers first-mover positioning for compliant foreign manufacturers.
- Academic Medical Center Training:Expanded fellowship programs address certified fitter scarcity through institutional credentialing pipelines.
- ISO 18369-4 Biocompatibility:Anticipated standard revisions create competitive differentiation for early-adopting testing laboratories.
Industry Challenges
- Fitter Certification Bottlenecks:Hands-on scleral lens training requirements outpace educational program output, constraining prescriber base expansion.
- Custom Manufacturing Capex:Lathe-based production systems for toric and multifocal geometries demand specialized capital equipment with extended depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scleral Lens Market |
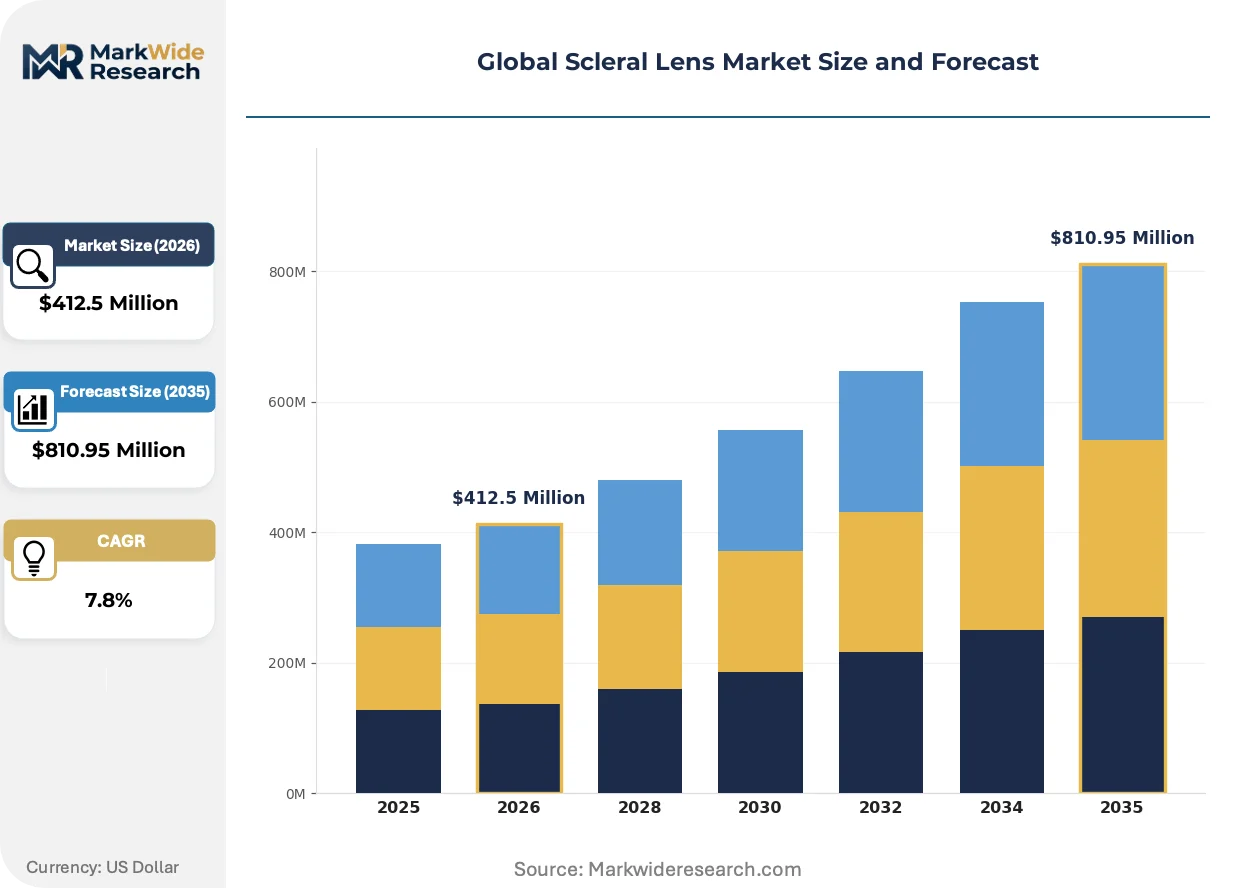
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Gas Permeable, Hybrid, Soft, Custom-Made Application: Keratoconus, Post-Surgical, Dry Eye Syndrome, Irregular Cornea End User: Ophthalmology Clinics, Optical Retail Stores, Eye Care Centers, Specialized Hospitals Distribution Channel: Direct Sales, E-Commerce, Wholesale Distributors, Optical Chains |
| Companies Covered | BostonSight, AccuLens, Bausch + Lomb, SynergEyes, Blanchard Contact Lenses, Visionary Optics, Art Optical Contact Lens, Valley Contax, ABB Optical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scleral Lens Market Shifts & Advancements
Wavefront-guided topography integration is compressing fitting appointment duration while improving first-lens success rates, fundamentally altering practice economics for specialty contact lens providers.
Hyper-Dk fluorosilicone acrylate copolymers are displacing conventional RGP materials in extended-wear protocols. Academic medical centers and high-volume specialty practices adopt these formulations aggressively. The shift is displacing legacy manufacturing contracts tied to lower-Dk polymer supply agreements.
EU Medical Device Regulation post-market surveillance requirements now mandate systematic clinical follow-up data for custom ophthalmic devices. Manufacturers must establish traceability systems linking individual lens parameters to patient outcomes. Germany's notified bodies enforce these provisions most stringently, forcing design dossier revisions across the value chain.
Direct-to-practitioner technical support models now bypass traditional distributor networks for complex fitting cases. Independent optometry practices and hospital-based specialty clinics access manufacturer consultants through dedicated hotlines and telemedicine platforms. This channel compression is most advanced in the United States, where reimbursement complexity demands real-time coding guidance.
Global Scleral Lens Market Segmentation
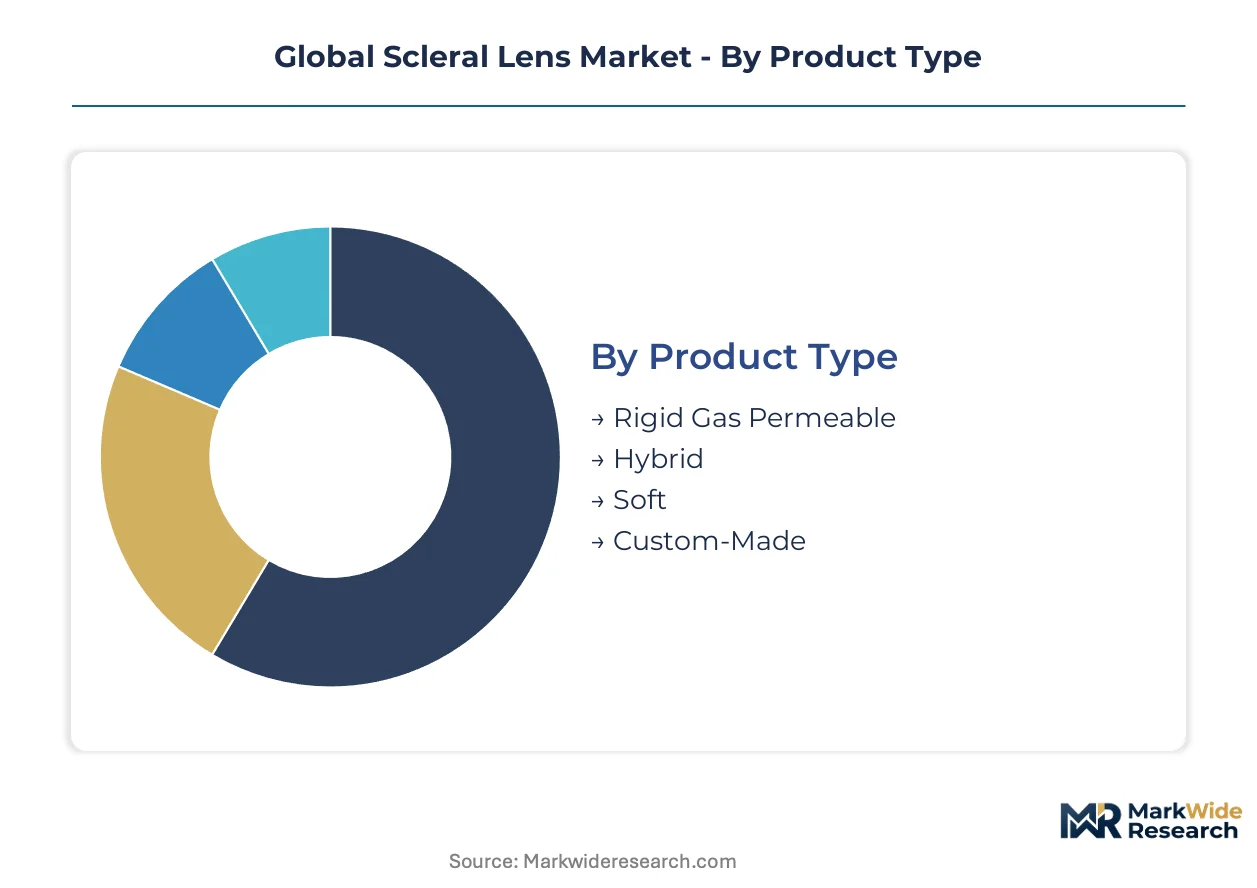
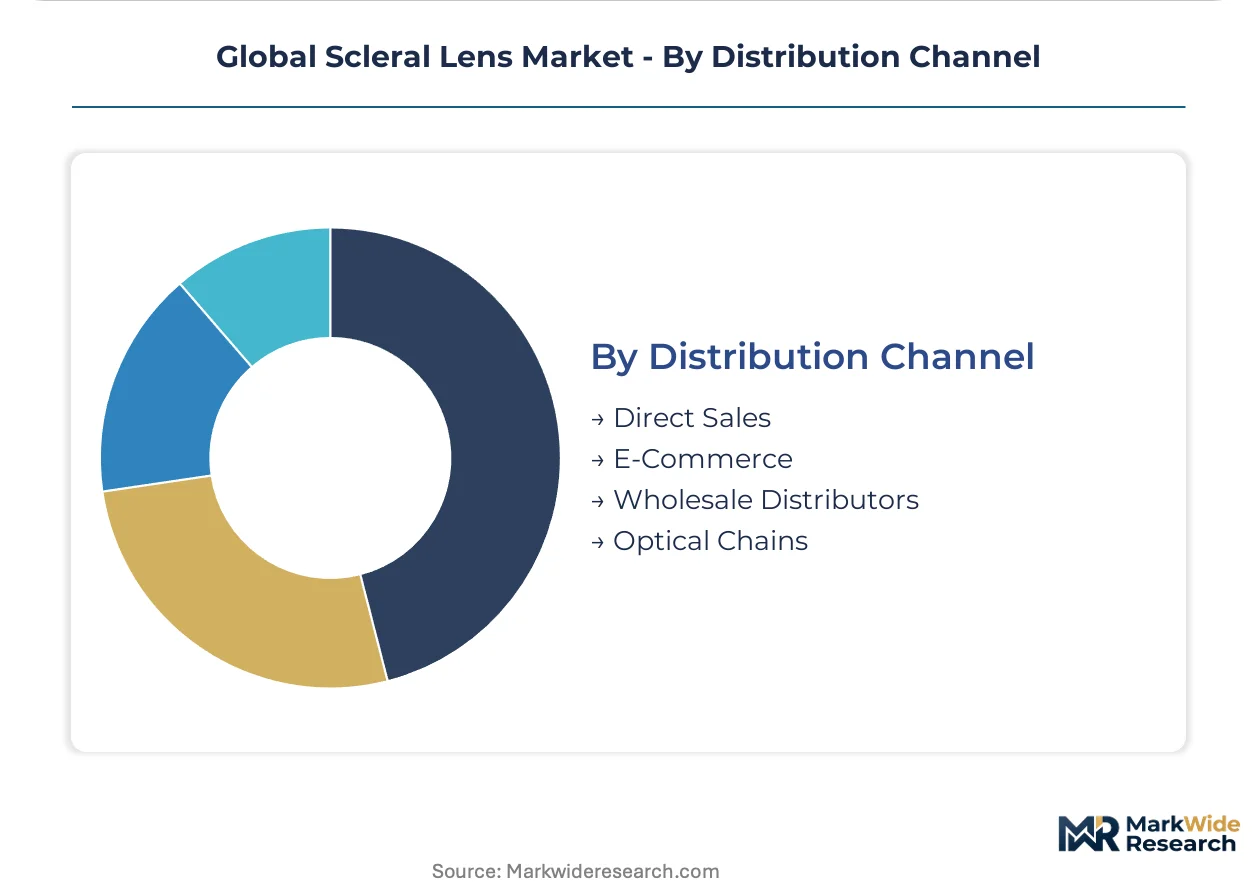
Scleral lens segmentation reveals distinct channel economics across product tiers. Custom geometries command premium positioning through direct practitioner relationships, while standardized designs flow through consolidated optical retail networks.
Product Type:
Channel mix varies sharply by material technology — high-Dk polymers route through specialty fitters requiring technical support, while conventional formulations leverage distributor scale.
- Rigid Gas Permeable:Fluorosilicone acrylate copolymers with Dk/t exceeding 100 anchor reimbursement eligibility across US Medicare and German statutory insurance frameworks. Demand concentrates among corneal ectasia patients in academic medical centers where established fitting protocols justify extended chair time.
- Custom-Made:Toric and multifocal geometries manufactured via CNC lathe from patient-specific topography data capture premium pricing for irregular astigmatism cases. Germany's notified bodies enforce MDR traceability requirements most stringently here, extending registration timelines but creating competitive moats for compliant manufacturers.
- Hybrid:Rigid center-soft skirt designs bridge comfort and optical performance for transitioning soft lens wearers.
- Soft:Silicone-hydrogel scleral configurations target mild dry eye cases outside specialty care channels.
Rigid gas permeable dominates installed base. Custom-made is where expansion concentrates.
Application:
Cost tier stratification separates reimbursed medical indications from out-of-pocket wellness applications, with keratoconus screening expansion reshaping volume distribution.
- Keratoconus:Corneal topography screening protocols in US optometry schools and Japanese ophthalmology residency programs expand addressable pools for progressive ectasia management. FDA 510(k) pathways streamline device introductions specifically for this indication.
- Dry Eye Syndrome:Meibomian gland dysfunction diagnoses among digital device users in Tokyo, Seoul, and Silicon Valley drive fluid-filled reservoir demand. Fluid-ventilated designs from US manufacturers now target this segment through direct-to-practitioner technical support models.
- Post-Surgical:LASIK ectasia and corneal transplant patients require complex fitting protocols.
- Irregular Cornea:Trauma and dystrophy cases represent stable referral volume from hospital-based specialty clinics.
Keratoconus anchors practitioner training curricula. Dry eye syndrome is climbing the fastest.
End User:
Customer type determines service intensity — hospital-based specialists demand manufacturer consultation integration, while retail channels prioritize inventory turnover.
- Ophthalmology Clinics:Cornea specialists in US academic medical centers and German university hospitals drive complex case volume. Fellowship-trained fitters here generate highest per-patient revenue through custom toric and multifocal designs.
- Specialized Hospitals:Japan's national hospital organizations and NHS foundation trusts in England consolidate procurement for post-surgical and trauma indications. PMDA and MHRA registration requirements shape vendor qualification processes.
- Eye Care Centers:Independent optometry practices access manufacturer hotlines for real-time coding guidance.
- Optical Retail Stores:Chain networks capture standardized fittings through bulk purchasing agreements.
Ophthalmology clinics concentrate premium case complexity. Specialized hospitals are gaining procurement scale fastest.
Distribution Channel:
Supply concentration among qualified polymer producers dictates channel viability, with direct models requiring captive technical staff.
- Direct Sales:Manufacturer-employed consultants support complex fittings through telemedicine platforms, bypassing distributor margins. This model dominates US reimbursement complexity where real-time coding guidance determines claim acceptance.
- Wholesale Distributors:Consolidated optical supply houses in Germany and Japan manage inventory for standardized RGP designs. EU MDR post-market surveillance requirements now mandate traceability systems linking individual lens parameters to patient outcomes.
- E-Commerce:Limited to replacement lens orders for established wearers with stable parameters.
- Optical Chains:Volume purchasing agreements capture mild-to-moderate astigmatism cases.
Direct sales commands complex case economics. Wholesale distributors handle volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the dominant prescribing geography, where established reimbursement frameworks and specialty contact lens practitioner networks concentrate clinical adoption. Germany and Japan follow with distinct regulatory architectures that shape market entry timelines and competitive positioning.
United States
Corneal ectasia screening expansion in academic medical centers and independent optometry practices drives patient pool growth. FDA 510(k) Class II medical device review streamlines custom lens introductions for irregular cornea indications. Fellowship-trained fitters in Boston, New York, and California generate highest per-patient revenue through complex toric and multifocal designs.
Germany
Statutory insurance reimbursement for rigid gas permeable lenses with Dk/t exceeding 100 anchors demand among corneal ectasia patients. EU Medical Device Regulation post-market surveillance mandates systematic clinical follow-up data and traceability systems linking lens parameters to outcomes. Notified bodies in Berlin and Munich enforce these provisions most stringently, extending registration timelines for foreign manufacturers.
Japan
Meibomian gland dysfunction diagnoses among digital device users in Tokyo and Osaka drive fluid-filled reservoir demand for ocular surface protection. PMDA maintains distinct pharmaceutical and medical device classifications that reshape registration timelines for compliant foreign entrants. National hospital organizations consolidate procurement for post-surgical and trauma indications.
United Kingdom
NHS foundation trusts concentrate procurement volume for post-surgical and irregular cornea cases. MHRA registration requirements align with EU MDR traceability mandates post-Brexit, preserving stringent clinical evidence burdens. London and Manchester host the largest hospital-based specialty clinics driving complex fitting protocols.
South Korea
Digital device penetration in Seoul and Busan expands dry eye syndrome diagnoses among younger demographics. MFDS medical device classification system offers streamlined pathways for oxygen-permeable polymer innovations. Local optical chains increasingly source high-Dk scleral configurations through direct manufacturer relationships.
Global Scleral Lens Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with manufacturing scale separating prescription fulfillment capabilities. The upper tier commands polymer supply agreements and direct practitioner technical support infrastructure. Specialist players occupy custom geometry niches requiring CNC lathe production and topography-driven manufacturing. Competitive moves center on backward integration into oxygen-permeable material supply and captive training program development to address fitter certification bottlenecks.
Among US-based integrated manufacturers, Bausch + Lomb occupies a position exemplifying scale-driven polymer supply and distribution network leverage. Visionary Optics and Blanchard Contact Lenses represent the specialist archetype, anchoring custom design capabilities through direct practitioner relationships and technical consultation models. These three players collectively illustrate the market's bifurcation between volume-scale supply chains and premium custom fabrication.
| Leading Market Players |
|---|
| BostonSight |
| AccuLens |
| Bausch + Lomb |
| SynergEyes |
| Blanchard Contact Lenses |
| Visionary Optics |
| Art Optical Contact Lens |
| Valley Contax |
| ABB Optical Group |
| Others |
Supply & Pricing Matrix
Capacity utilization at fluorosilicone acrylate polymer plants in the United States and Germany shapes both supply concentration and price floors for oxygen-permeable scleral lens materials. High-Dk formulations command premium positioning through direct practitioner channels, while conventional RGP materials flow through consolidated optical distributors at compressed margins.
Pricing Analysis
Geographic price spreads between US Medicare-reimbursed fittings and German statutory insurance frameworks reach three-to-one multiples for custom toric geometries. Three-tier pricing structure across premium custom-made, standard RGP, and economy hybrid configurations separates certification-grade practitioners from retail optical chains. Pricing pressure stems from soft toric lens substitution in mild astigmatism cases outside specialty care. Optical retail chains exhibit highest price sensitivity, while academic medical centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Inventory lead times for CNC lathe production systems extend eighteen to twenty-four months, constraining custom manufacturing capacity expansion. Fluorosilicone acrylate copolymer supply concentrates in the United States, Germany, and Japan, with qualified polymer producers limited to three integrated manufacturers. Raw material dependencies center on silicone monomers, fluorinated additives, and precision lathe cutting tools. Single-source vulnerability for Dk/t-exceeding-100 polymer grades creates supply security exposure. Distribution runs through direct sales for complex fittings and wholesale distributors for standardized RGP volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Scleral Lens Market operates as a defensive-moat story anchored in regulatory entrenchment. FDA 510(k) clearance pathways and EU MDR clinical evidence requirements create structural barriers that protect incumbent positions from rapid commoditization.
For Market Incumbents: Compound network effects by embedding manufacturer consultants directly into academic medical center fellowship training curricula. Deepen backward integration into oxygen-permeable polymer supply to secure input cost stability against silicone-hydrogel raw material concentration. Threats from soft toric lens substitution in mild astigmatism cases demand defensive certification investments to maintain specialty practitioner loyalty. For New Entrants and Emerging Players: Anchor in Japan's PMDA registration pathway, where distinct pharmaceutical-medical device classifications offer first-mover positioning for compliant foreign manufacturers. Target South Korea's expanding dry eye syndrome segment among digital device users in Seoul and Busan. Penetrate through direct-to-practitioner technical support models that bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors custom geometry specialists with captive CNC lathe production and topography-driven manufacturing capabilities. Long-term viability hinges on backward integration into polymer supply and training program development. Watch fitter certification output rates at academic medical centers as the inflection indicator for prescriber base expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive fluorosilicone acrylate production secures Dk/t thresholds above 100 for reimbursement eligibility. |
| Academic Medical Center Training Partnership | Fellowship program embedding creates certified fitter pipelines that lock in prescriber loyalty. |
| PMDA Registration Pathway Investment | Compliant foreign manufacturers gain first-mover positioning in Japan's distinct classification system. |
| Direct-to-Practitioner Technical Support | Real-time coding guidance for US reimbursement complexity bypasses distributor margin capture. |
| EU MDR Traceability System Deployment | Systematic clinical follow-up data satisfies Germany's notified body enforcement for custom devices. |
Research Methodology
Cross-validation between primary interviews with cornea specialists, contact lens fitters, and optical supply distributors and secondary validation through FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement databases anchors the qualitative findings. Bottom-up triangulation across product type, application, and end-user segmentation converges with top-down macroeconomic and regulatory trend assessment.
Sensitivity analysis around polymer supply concentration and fitter certification bottlenecks informs the analytical framework across the projection horizon. Segmentation dimensions modeled include material technology tier, indication severity, practitioner certification level, and regional regulatory cluster. CAGRs derive from patient pool expansion trajectories, screening protocol adoption curves, and reimbursement framework stability. Forecast inputs incorporate corneal ectasia diagnosis rates and meibomian gland dysfunction prevalence among digital device users.
Material uncertainties — regulatory timeline revisions, polymer supply disruptions, and soft lens technology substitution — sit outside the modeled envelope. Forecasts reflect assumptions about certification program scaling and reimbursement stability that industry stakeholders may revise. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Contraceptive Rings Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Brachytherapy Market
Medical Devices
Cervical Retractors Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Retinal Implant Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
US Contact Lenses Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Global Body Composition Analyzers Market