
 Japan Respiratory Devices Market | 2026-2036
Japan Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Respiratory Devices Market Foresight
Aftermarket service revenue is narrowing as manufacturers shift toward subscription-based remote monitoring platforms. ResMed Inc leverages cloud-connected ventilation analytics to sustain recurring revenue streams beyond hardware sales. Terumo Corporation anchors its position through intensive R&D spending on compact oxygen delivery systems tailored to Japanese home care standards.
Respiratory devices encompass mechanical and electromechanical apparatus engineered to assist, monitor, or replace pulmonary function, with critical specifications including flow rates of 2–60 L/min for oxygen concentrators and pressure control ranges of 5–40 cm H₂O for invasive ventilators, serving primarily to treat chronic obstructive pulmonary disease, sleep apnea, and acute respiratory failure in clinical and domestic settings. Ventilators command the deepest margin pools due to intensive care unit reliance and technical complexity, while oxygen concentrators represent the fastest-expanding product type as Japan's home care infrastructure expands under long-term care insurance reforms. The geriatrics patient demographic absorbs disproportionate volume, though pediatrics generates premium pricing through specialized miniaturization and safety certification requirements.
PMDA medical device approvals and JIS T 0601 electrical safety standards govern product entry, with METI industrial policy incentivizing domestic manufacturing reshoring for critical care equipment. Stakeholders must monitor reimbursement code expansions for telehealth-integrated respiratory therapy, as these decisions will determine which device categories capture sustainable margin pools in Japan's progressively decentralized care delivery model.
Market Dynamics
Japan's Ministry of Health, Labour and Welfare reimbursement revisions for remote patient monitoring are redirecting procurement toward connected oxygen concentrators, compressing traditional hardware-only sales cycles and forcing manufacturers to restructure revenue models around subscription-based analytics platforms.
Growth Catalysts
- Long-term care insurance reforms:Expanded home care coverage under Japan's LTCI system accelerates device procurement for geriatric patients requiring domiciliary oxygen therapy.
- Tokyo metropolitan hospital density:The Kanto region's concentrated clinical infrastructure sustains volume pull for invasive ventilators and high-acuity respiratory support equipment.
- PMDA fast-track pathways:Accelerated approval timelines for breakthrough respiratory devices reduce commercialization lag for novel ventilation modes and portable oxygen systems.
Market Restraints
- Domestic manufacturing concentration:Critical component sourcing for ventilator compressors and sensors clusters in a limited supplier base, exposing procurement to single-source vulnerabilities.
- JIS T 0601 electrical safety compliance costs:Rigorous testing protocols for electromagnetic compatibility and isolation requirements inflate pre-market expenditure for foreign entrants.
- Stationary oxygen cylinder substitution:Liquid oxygen delivery systems retain cost advantages in institutional settings, constraining portable concentrator penetration in high-volume hospital contracts.
Strategic Opportunities
- Telehealth-integrated respiratory therapy:Reimbursement code expansions for remote monitoring create sustainable margin pools for cloud-connected ventilation analytics platforms.
- Kyushu and Tohoku prefecture penetration:Aging population density in underpenetrated rural regions offers volume expansion for home care oxygen concentrator deployment.
- AI-enabled predictive maintenance:Convergence of machine learning algorithms with ventilator telemetry enables proactive device servicing, reducing emergency repair incidence.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in respiratory physiology and mechanical ventilation programming commands premium compensation, constraining R&D team scaling.
- PMDA quality management system audits:Extended certification timelines for manufacturing site inspections delay product launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Respiratory Devices Market |
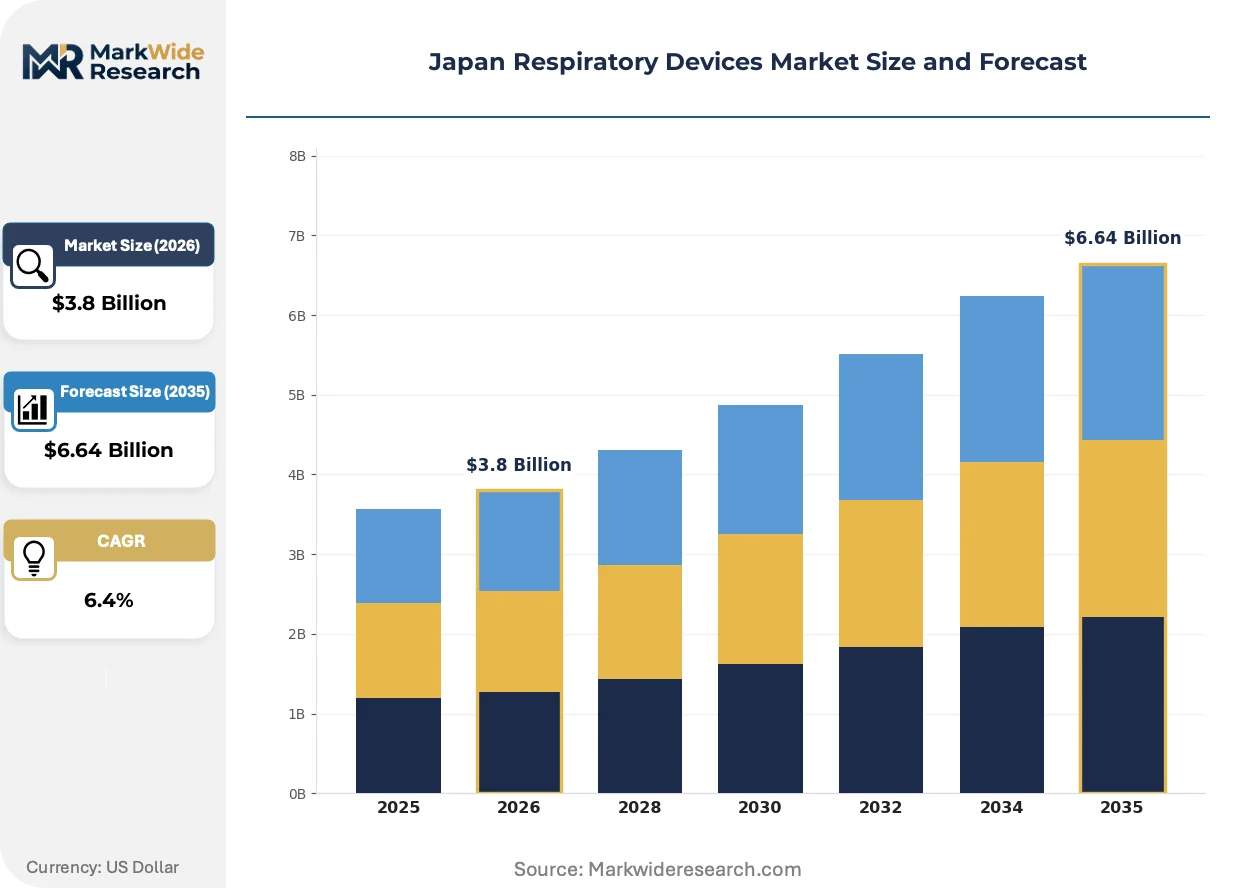
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Ventilators, Oxygen Concentrators Patient Demographic: Adults, Pediatrics, Geriatrics, Hospitalized Patients Distribution Channel: Pharmacies, Hospitals, E-commerce, Direct Sales Usage Environment: Home Care, Clinical Settings, Emergency Services, Rehabilitation Centers |
| Companies Covered | Getinge AB, Dragerwerk AG, Terumo Corporation, ResMed Inc, Fisher & Paykel Healthcare Ltd, GE Healthcare, Koninklijke Philips NV, CHEST M.I. Inc, Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Respiratory Devices Market Shifts & Advancements
Connected device architectures and predictive analytics are displacing reactive maintenance models across Japan's respiratory device landscape, while reimbursement policy accelerates platform-based service delivery over transactional hardware sales.
Miniaturized oxygen concentrator technology is hybridizing with battery-integrated portability features to enable uninterrupted ambulatory therapy. Geriatric patients in Tokyo's dense urban corridors adopt these systems at accelerating rates. The convergence is compressing stationary device markets while opening subscription revenue streams for remote monitoring services.
PMDA's streamlined approval pathways for software-as-a-medical-device are accelerating cloud-connected ventilation platform commercialization. Manufacturers now embed real-time adherence tracking and automated pressure adjustment algorithms. Intensive care units in Osaka and Nagoya prefectures prioritize these systems for ventilator weaning protocols.
Hospital procurement departments are consolidating vendor relationships around full-service respiratory management contracts. Device manufacturers displace standalone equipment sales with bundled analytics and maintenance offerings. This consolidation concentrates most visibly in Kanto region academic medical centers negotiating multi-year platform agreements.
Japan Respiratory Devices Market Segmentation
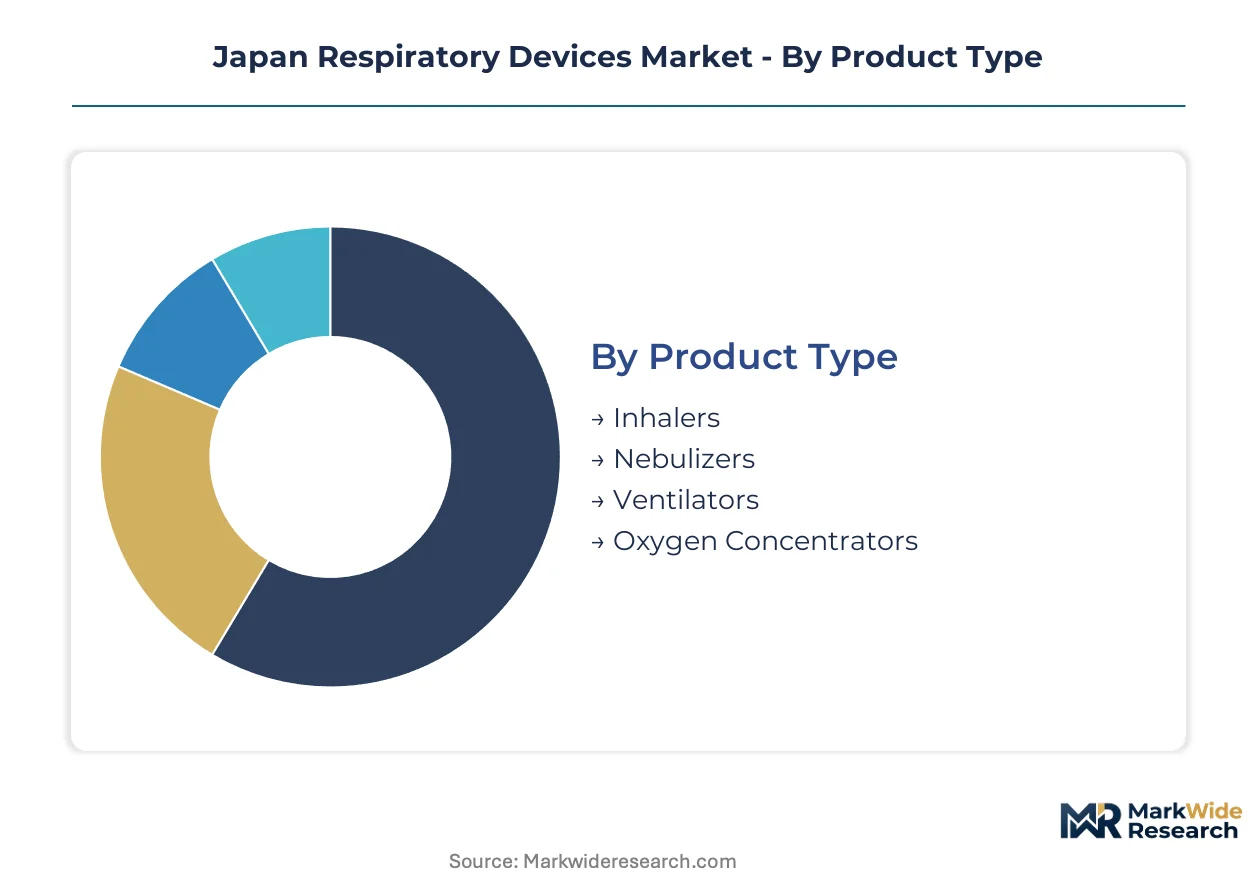
Respiratory device procurement patterns diverge sharply across product categories, patient populations, and care settings. Understanding these fault lines clarifies where manufacturers must restructure revenue models and where distributors face margin compression.
Product Type:
Oxygen concentrators turn inventory fastest through home care channels, while ventilators sit on hospital procurement cycles stretching 18–24 months.
- Oxygen Concentrators:Electromechanical systems extracting nitrogen from ambient air to deliver 90–95% oxygen at 2–10 L/min flow rates. Tokyo's geriatric home care agencies drive replacement demand under LTCI reimbursement expansions.
- Ventilators:Positive-pressure devices controlling tidal volume and respiratory rate via invasive or non-invasive interfaces. Osaka and Nagoya academic medical centers sustain volume for ICU-grade systems with advanced weaning protocols.
- Nebulizers:Aerosol delivery devices converting liquid medication into respirable particles. Pediatric asthma management in Kanto region clinics sustains compact ultrasonic unit demand.
- Inhalers:Pressurized metered-dose or dry-powder devices for bronchodilator administration. Pharmacies across Japan dispense these at highest frequency for COPD maintenance therapy.
Ventilators anchor the volume base while oxygen concentrators gain share at the steepest rate.
Patient Demographic:
Cost tiers stratify sharply, with pediatric devices commanding 40–60% premiums over adult equivalents due to miniaturization and safety certification requirements.
- Geriatrics:Patients aged 65+ requiring domiciliary oxygen therapy or non-invasive ventilation. Rural Tohoku prefectures exhibit accelerating device penetration as LTCI coverage expands.
- Adults:Working-age patients managing sleep apnea or occupational lung disease. Corporate health insurance schemes in Tokyo metropolitan area subsidize CPAP procurement.
- Hospitalized Patients:Acute care recipients requiring temporary respiratory support. Kanto region hospital density concentrates demand for high-acuity ventilator configurations.
- Pediatrics:Neonatal and pediatric patients needing specialized miniaturized equipment. Japan's declining birth rate constrains volume despite premium pricing power.
Geriatrics absorbs the dominant revenue share while adult sleep apnea segments expand most quickly.
Distribution Channel:
Volume concentrates through institutional procurement, though margin pools are shifting toward direct manufacturer-patient relationships.
- Hospitals:Centralized procurement departments negotiating multi-year equipment contracts. Kanto and Kansai region academic medical centers dominate high-value ventilator acquisitions.
- Pharmacies:Community and hospital-affiliated dispensaries handling inhaler and nebulizer sales. Reimbursement code alignment with LTCI drives prescription volume.
- Direct Sales:Manufacturer-to-patient channels for home oxygen therapy systems. Remote monitoring subscription bundles now accompany hardware transactions.
- E-commerce:Online platforms for consumables and replacement accessories. Urban geriatric patients in Tokyo increasingly favor digital procurement for cannulas and filters.
Hospitals anchor the volume base while direct sales channels climb the fastest.
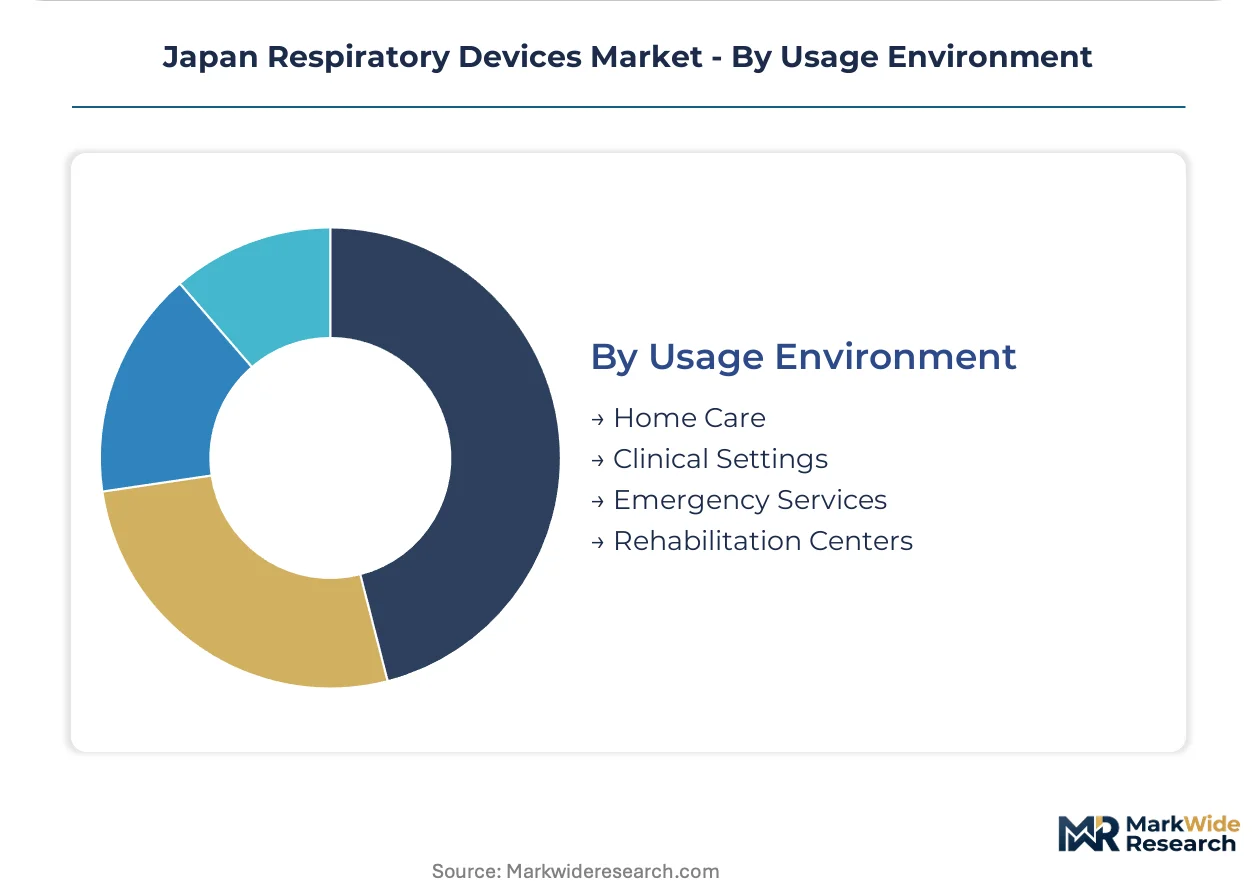
Usage Environment:
Supply concentration differs by care setting, with home care requiring distributed logistics networks and clinical settings demanding intensive technical support.
- Home Care:Domiciliary oxygen therapy and non-invasive ventilation settings. METI incentives for remote patient monitoring accelerate connected device deployment.
- Clinical Settings:Hospital wards and outpatient departments administering acute and chronic respiratory therapy. PMDA quality management system audits govern equipment certification.
- Emergency Services:Pre-hospital and ambulance-based respiratory support. Portable ventilator specifications prioritize battery endurance and ruggedization.
- Rehabilitation Centers:Post-acute facilities managing ventilator weaning and respiratory muscle training. Kyushu prefecture aging demographics expand addressable volume.
Clinical settings anchor the volume base while home care environments gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home care procurement in rural prefectures exhibits higher price elasticity than Tokyo metropolitan hospital contracts, where ventilator specifications dominate purchasing criteria regardless of cost.
Kanto/Tokyo
Tokyo's dense hospital network sustains volume pull for invasive ventilators and high-acuity respiratory support equipment. PMDA medical device approvals govern product entry for manufacturers targeting this cluster. Academic medical centers in the capital negotiate multi-year platform agreements for cloud-connected ventilation analytics.
Kansai/Osaka
Osaka prefecture's intensive care units prioritize ventilator weaning protocols with real-time adherence tracking capabilities. METI industrial policy incentivizes domestic manufacturing reshoring for critical care equipment deployed across Kansai region hospitals. Nagoya's medical device corridor supplies component ecosystems for ventilator compressor assemblies.
Kyushu
Aging population density in underpenetrated rural regions offers volume expansion for home care oxygen concentrator deployment. Long-term care insurance reforms accelerate device procurement for geriatric patients requiring domiciliary oxygen therapy in Fukuoka prefecture. Regional distributors build logistics networks to serve dispersed home care agencies.
Tohoku
Rural prefectures exhibit accelerating device penetration as LTCI coverage expands for domiciliary respiratory therapy. JIS T 0601 electrical safety standards govern product certification for manufacturers entering this price-sensitive segment. Sendai metropolitan area anchors procurement coordination for northern Japan's home care infrastructure.
Chubu/Nagoya
Central Japan's manufacturing base produces compact oxygen delivery systems tailored to Japanese home care standards. PMDA quality management system audits govern equipment certification for devices manufactured in this industrial corridor. Toyota-related supplier networks extend into medical device component fabrication.
Japan Respiratory Devices Market Competitive Landscape
Global diversified medical technology conglomerates and specialized respiratory device manufacturers split the market between platform-scale service delivery and focused therapeutic innovation. The vendor base concentrates around three strategic archetypes: integrated hospital solution providers, home care subscription platform operators, and regional component specialists. Consolidation pressures intensify as procurement departments favor bundled analytics and maintenance offerings over standalone equipment transactions. M&A activity targets cloud-connected ventilation telemetry capabilities, while strategic partnerships secure distribution access in underpenetrated prefectures.
Among global diversified manufacturers, Getinge AB, Dragerwerk AG, and Koninklijke Philips NV occupy positions spanning critical care ventilation through home respiratory therapy. These conglomerates exemplify the integrated hospital solution archetype, leveraging platform-scale service contracts to displace point-product competitors. ResMed Inc and Terumo Corporation represent contrasting specialization strategies—ResMed anchors the home care subscription model through cloud-connected analytics, while Terumo exemplifies regional R&D intensity with compact oxygen systems engineered for Japanese regulatory and reimbursement parameters. The competitive dynamic between these archetypes determines margin capture across Tokyo's academic medical centers versus Kyushu's expanding home care agencies.
| Leading Market Players |
|---|
| Getinge AB |
| Dragerwerk AG |
| Terumo Corporation |
| ResMed Inc |
| Fisher & Paykel Healthcare Ltd |
| GE Healthcare |
| Koninklijke Philips NV |
| CHEST M.I. Inc |
| Medtronic PLC |
| Others |
Supply & Pricing Matrix
German and Japanese compressor component sourcing clusters anchor ventilator manufacturing costs, concentrating margin capture among suppliers with PMDA-certified quality management systems while forcing downstream manufacturers toward subscription-based revenue to offset hardware margin compression.
Pricing Analysis
Remote monitoring subscription tiers now drive lifetime value in Japan's respiratory device market. Three-tier pricing structure across premium analytics, standard connectivity, and economy hardware-only levels stratifies buyer segments. Pricing pressure stems from METI reimbursement revisions favoring connected oxygen concentrators over traditional equipment sales. Hospital procurement departments in Kanto exhibit lowest price sensitivity due to bundled platform contracts, while rural home care agencies in Tohoku face acute cost constraints.
Supply Chain Analysis
Extended payment terms from Japanese hospital procurement departments strain supplier working capital, accelerating supply-chain finance facility adoption among ventilator component manufacturers. Manufacturing concentrates in Japan, Germany, and the United States for precision compressor assemblies and sensor modules. Production draws from rare earth elements for magnetic components, medical-grade polymers for housing materials, and semiconductor chips for control systems. Single-source vulnerability in precision flow sensor supply creates structural risk. Distribution runs through GPO-coordinated hospital contracts and direct-to-patient home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's respiratory device market is crossing into platform-economics territory as cloud-connected ventilation analytics displace transactional hardware sales, with interoperability between remote monitoring systems and hospital EMR infrastructure determining competitive survival.
For Market Incumbents: Harden defensive positions by acquiring cloud-connected telemetry capabilities to offset hardware margin erosion from subscription model transitions. Deepen backward integration into precision compressor manufacturing to reduce single-source dependency flagged by METI reshoring incentives. Prioritize JIS T 0601 certification investments to maintain procurement access against emerging connected-device entrants.
For New Entrants and Emerging Players: Pursue white-space penetration in Kyushu and Tohoku prefecture home care agencies where LTCI reimbursement expansion outpaces incumbent distribution coverage. Target direct-to-patient sales channels for portable oxygen concentrators with remote monitoring bundles, exploiting price sensitivity gaps in rural geriatric segments. Leverage PMDA software-as-a-medical-device fast-track pathways to accelerate cloud platform commercialization.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized respiratory analytics platform operators with proven hospital system integration and recurring revenue visibility across the analysis window. Target acquisition profiles emphasize cloud-connected ventilation telemetry capabilities and established LTCI reimbursement code alignment. Monitor METI reimbursement expansion announcements for telehealth-integrated respiratory therapy as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Alignment with MHLW remote monitoring code expansions secures sustainable margin pools for connected oxygen concentrators. |
| Hospital System Partnership | Multi-year platform agreements with Kanto academic medical centers displace point-product competitors through bundled analytics. |
| Software Companion Development | PMDA SaMD fast-track pathways accelerate real-time adherence tracking and automated pressure adjustment algorithm deployment. |
| CE Marking Pathway | European regulatory reciprocity enables Japanese manufacturers to leverage domestic R&D for export market expansion. |
| Backward Integration | In-house production of precision compressor assemblies reduces exposure to German and Japanese supplier concentration risks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with respiratory device manufacturers, hospital procurement managers, biomedical engineers, and GPO contracts administrators; and secondary validation through PMDA medical device approval databases, MHLW reimbursement code filings, METI industrial policy disclosures, and hospital procurement contract registries. Bottom-up demand modeling triangulated against top-down market sizing across product type, patient demographic, distribution channel, and usage environment dimensions.
Forecast inputs incorporated historical volume trajectories, reimbursement policy revision timelines, and demographic aging curves across the projection horizon. Segmentation modeling captured oxygen concentrators, ventilators, nebulizers, and inhalers by geriatric, adult, hospitalized, and pediatric populations through institutional, pharmacy, direct sales, and e-commerce channels. CAGRs were derived from fitted growth curves applied to base-year estimates. Industry-specific inputs included LTCI coverage expansion rates and PMDA approval velocity for connected device platforms.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by diversified medical technology conglomerates would shift outcomes beyond modeled ranges. Macroeconomic deviation in yen-denominated procurement budgets, regulatory acceleration of software-as-a-medical-device pathways, or breakthrough miniaturization in battery-integrated oxygen delivery would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
External Defibrillator Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Autosamplers Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Appendage Management Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
Oxygen Conservers Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Smart Lenses Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Breast Prosthesis Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
High Pressure Contrast Media Injectors Market