
 Global Embolic Protection Device Market | 2026-2036
Global Embolic Protection Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Embolic Protection Device Market Foresight
Hospital procurement consortiums is rewriting how embolic protection devices reach cath labs across North America and Western Europe. Medtronic leverages its integrated structural heart portfolio to bundle protection devices with delivery systems, sustaining volume commitments from integrated delivery networks. Boston Scientific Corporation anchors its position through deep relationships with academic medical centers, while Abbott Laboratories differentiates via catheter compatibility breadth across its own stent platforms.
An embolic protection device is a temporary or deployable mechanical system, typically constructed from nitinol mesh or polyurethane membranes mounted on guidewire-based delivery catheters, designed to capture and remove debris dislodged during endovascular interventions. Its primary commercial purpose is reducing periprocedural stroke and distal embolization risk during carotid, coronary, and peripheral vascular procedures. Distal filter devices occupy the largest revenue share due to established clinical familiarity and broad physician training, while proximal occlusion devices represent the fastest-expanding category as operators seek complete flow cessation during high-risk plaque manipulation. Carotid artery stenosis applications generate the deepest margin pools because procedure reimbursement and device ASPs both exceed those in peripheral interventions.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and clinical trial investment for every manufacturer seeking market access in the United States and European Union. Japan's PMDA adds a separate layer of domestic clinical data requirements that filters non-Japanese entrants from its hospital procurement channels. Stakeholders must monitor how evolving CMS national coverage determinations for transcatheter procedures will redefine which settings—hospital outpatient departments versus ambulatory surgical centers—qualify for device reimbursement.
Market Dynamics
Hospital procurement consortiums are consolidating purchasing power across cath lab networks, forcing manufacturers to restructure commercial terms around volume commitments and bundled device-delivery system contracts rather than standalone unit sales.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance requirements for permanent implantable filters are accelerating replacement cycles and expanding the addressable patient pool for temporary protection systems.
- Germany's cath lab density leadership:Reimbursement parity for carotid interventions in German hospital outpatient departments sustains procedure volumes exceeding most European peers.
- Nitinol mesh manufacturing advances:Improved wire-forming precision is enabling smaller-diameter delivery profiles that access more tortuous anatomies previously unreachable with first-generation devices.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains cluster among a limited set of specialty metal processors, exposing device manufacturers to input price volatility and allocation risk.
- Japan PMDA domestic clinical data requirements:Mandatory local trial evidence for market entry filters non-Japanese manufacturers from hospital procurement channels regardless of FDA 510(k) or EU MDR clearance status.
- Distal embolization during filter retrieval:Incomplete debris capture during device extraction remains a documented technical limitation that constrains physician confidence in high-risk plaque cases.
Strategic Opportunities
- India's underpenetrated peripheral vascular segment:Rising diabetes prevalence and expanding interventional radiology training programs create whitespace for embolic protection adoption in renal and lower-limb interventions.
- CMS national coverage determination expansion:Pending reimbursement clarity for transcatheter procedures in ambulatory surgical centers could unlock site-of-care migration from hospital outpatient departments.
- Integration with robotic navigation platforms:Convergence between filter-based protection systems and magnetic or robotic catheter steering technologies enables remote procedure capabilities and operator skill democratization.
Industry Challenges
- Interventional cardiologist training bandwidth:Procedural complexity and competing device learning curves strain cath lab staff capacity to master proximal occlusion techniques alongside established distal filter workflows.
- EU MDR technical documentation timelines:Extended conformity assessment durations for legacy device recertification compress revenue recognition windows and strain regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Embolic Protection Device Market |
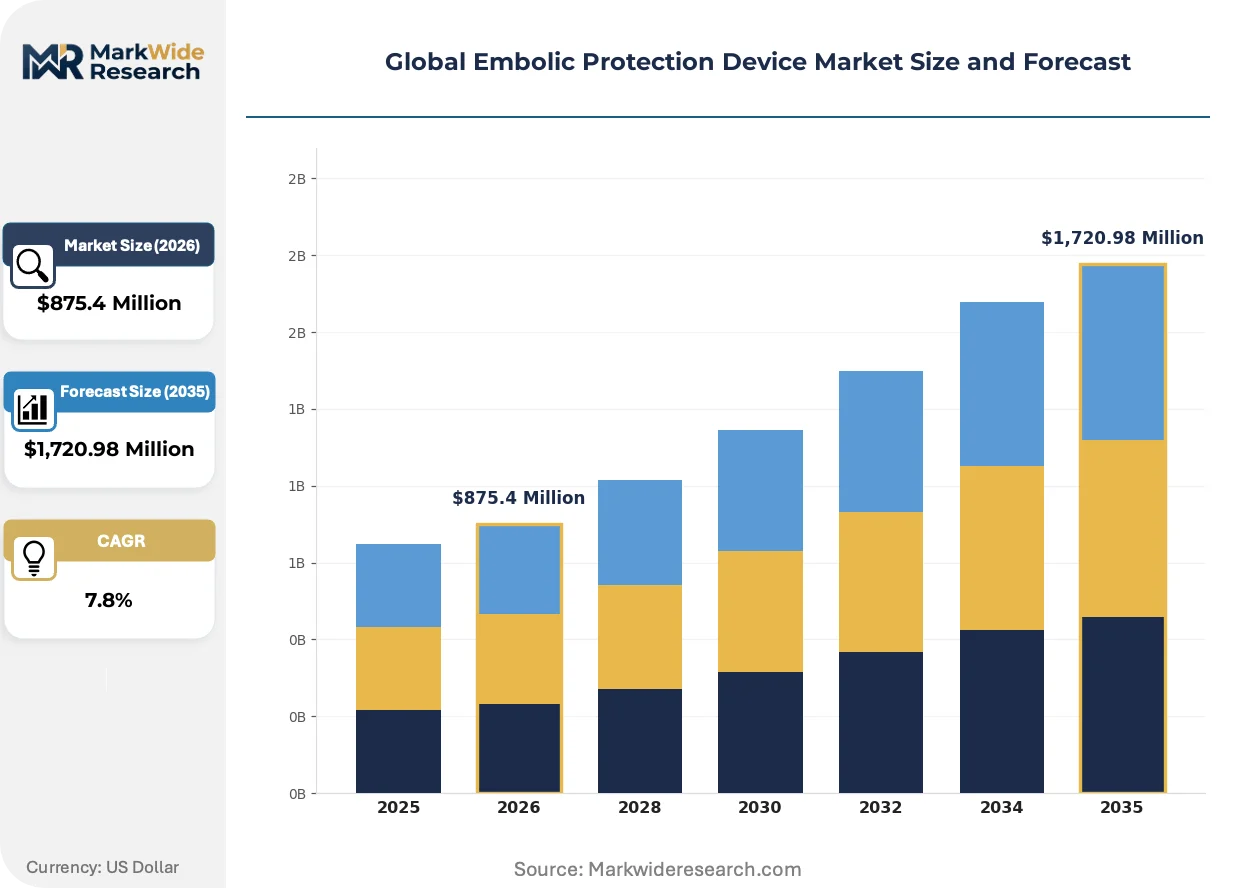
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,720.98 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distal Filter Devices, Proximal Occlusion Devices, Flow Arrest Devices, Combined Protection Systems Application: Carotid Artery Stenosis, Coronary Artery Disease, Peripheral Artery Disease, Neurovascular Interventions End User: Cardiovascular Clinics, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Specialty Hospitals Deployment: Hospital-Based, Clinic-Based, Mobile Interventional Units, Outpatient Facilities |
| Companies Covered | W. L. Gore & Associates, Cardinal Health, Medtronic, Contego Medical, Silk Road Medical, Boston Scientific Corporation, Terumo Corporation, Edwards Lifesciences Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Embolic Protection Device Market Shifts & Advancements
Device architecture is converging around single-operator deployment systems that reduce cath lab staff requirements, while regulatory frameworks on both sides of the Atlantic are rewriting the evidentiary bar for market access.
Polyurethane membrane filtration is collapsing the performance gap between distal filters and proximal occlusion systems. Academic medical centers in Germany and the United States are adopting membrane-based devices for complete flow cessation during high-risk carotid interventions. This materials shift is collapsing the historical trade-off between debris capture efficiency and procedural simplicity that has segmented the market for two decades.
FDA 510(k) clearance pathways are tightening evidentiary standards for predicate device reliance in embolic protection submissions. The agency's enhanced scrutiny of clinical equivalence claims is extending development timelines and expanding pivotal trial investment requirements. Device categories with limited predicate diversity face the steepest compliance cost escalation.
Integrated delivery networks are consolidating vendor relationships around structural heart procedure bundles that include protection devices as contract line items. Academic medical centers and community hospital systems are displacing standalone device purchasing with multi-year supply agreements tied to valve and stent delivery system volumes. This concentration is most visible in United States markets where Medicare bundled payment models have accelerated IDN formation.
Global Embolic Protection Device Market Segmentation
Device architecture and deployment setting determine reimbursement pathways, technical training requirements, and procurement contract structures across cath lab networks. Each segmentation dimension reveals distinct margin profiles and competitive dynamics that shape manufacturer commercial strategy.
Product Type:
After-sales service intensity varies sharply across product architectures, with occlusion systems demanding higher technical support for deployment training and retrieval troubleshooting than filter-based alternatives.
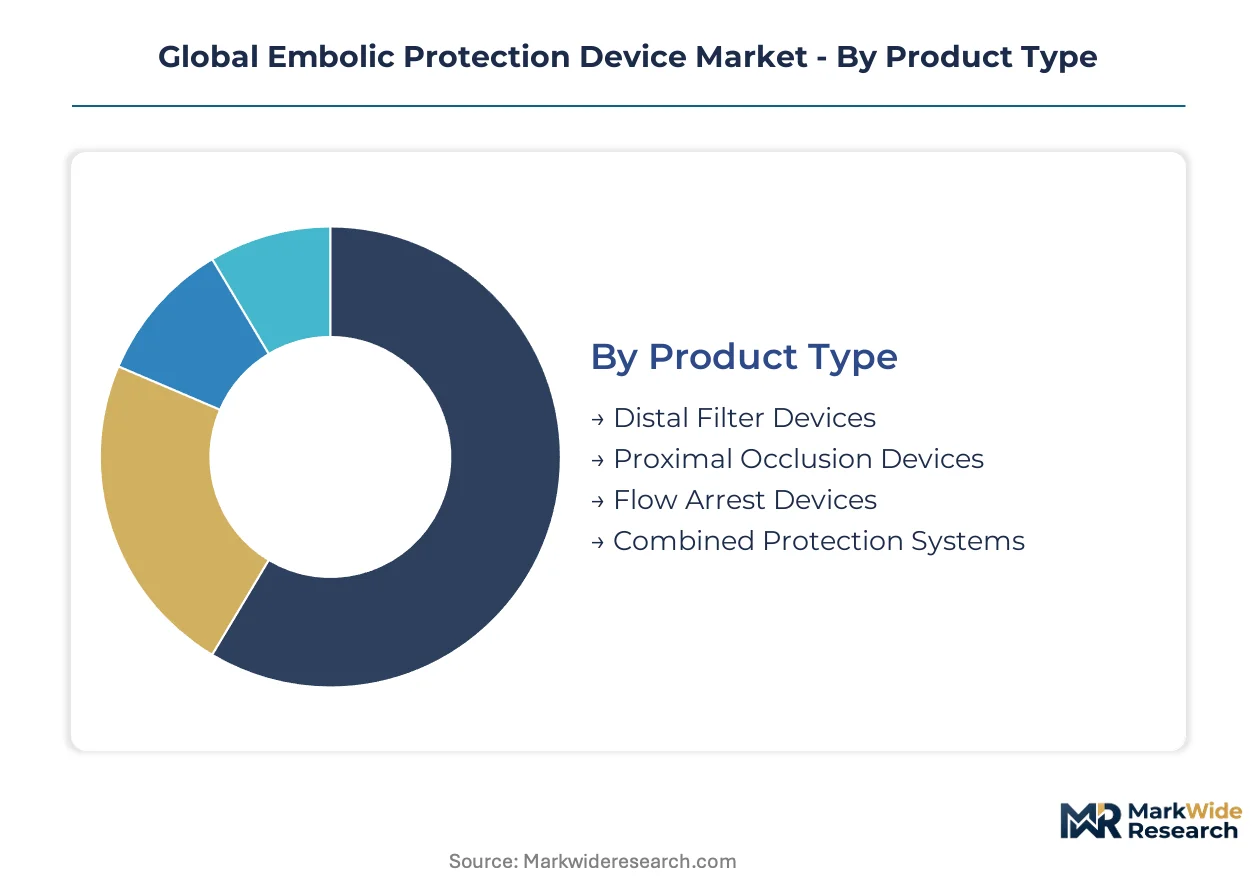
- Distal Filter Devices:Nitinol mesh baskets mounted on guidewire platforms capture embolic debris downstream of lesion sites while maintaining antegrade flow. German specialty hospitals and United States academic medical centers concentrate demand for these systems due to established physician familiarity and broad catheter compatibility. Reimbursement parity for carotid interventions in German hospital outpatient departments sustains volume commitments.
- Proximal Occlusion Devices:Balloon or flow-arrest mechanisms achieve complete cerebral or coronary flow cessation during high-risk plaque manipulation. Operators in Japan and United States tertiary centers drive adoption as materials science improves membrane filtration efficiency. EU MDR clinical evidence mandates for permanent filters accelerate replacement demand for these temporary systems.
- Flow Arrest Devices:Specialized balloon catheters interrupt antegrade flow without distal filtration elements.
- Combined Protection Systems:Hybrid architectures integrating proximal occlusion with distal filtration capabilities.
By volume, Distal Filter Devices leads. By growth pace, Proximal Occlusion Devices is ahead.
Application:
Procedure reimbursement tiers and device ASPs stratify sharply across anatomical targets, with cerebral applications commanding premium pricing over peripheral interventions.
- Carotid Artery Stenosis:Transfemoral and transcarotid approaches deploy protection devices during stenting of extracranial carotid lesions. German cath lab density and reimbursement structures exceed European peers, concentrating demand in Bavarian and North Rhine-Westphalia hospital networks. CMS national coverage determinations shape United States site-of-care migration between hospital outpatient departments and ambulatory surgical centers.
- Coronary Artery Disease:Saphenous vein graft interventions and high-risk native vessel PCI utilize distal protection to prevent no-reflow phenomenon. Academic medical centers in the United States and Japan anchor procedural volumes as operators manage degenerated conduit atheroembolization.
- Peripheral Artery Disease:Renal and lower-limb interventions employ protection during atherectomy and stenting of heavily calcified lesions.
- Neurovascular Interventions:Intracranial stenting and thrombectomy adjuncts represent emerging applications with evolving evidence bases.
Carotid applications dominate revenue contribution. Peripheral interventions are climbing the fastest.
End User:
Procurement scale and contract negotiation leverage concentrate in integrated delivery networks, displacing standalone device purchasing across multiple facility types.
- Specialty Hospitals:Dedicated cardiovascular centers perform high-complexity structural heart and carotid procedures with dedicated cath lab staffing. United States Medicare bundled payment models and German DRG-based reimbursement sustain device volume commitments through multi-year supply agreements.
- Ambulatory Surgical Centers:Freestanding interventional facilities seek streamlined protection devices compatible with same-day discharge protocols. Pending CMS national coverage determination expansion could unlock site-of-care migration from hospital outpatient departments.
- Cardiovascular Clinics:Office-based labs with limited procedure volumes purchase through distributor channels.
- Diagnostic Imaging Centers:Non-invasive facilities occasionally host interventional procedures with borrowed device inventory.
Specialty Hospitals capture the deepest procurement contracts. Ambulatory Surgical Centers are gaining share fastest.
Deployment:
Fixed infrastructure requirements and capital equipment investment thresholds segment addressable settings by procedure complexity and emergency readiness.
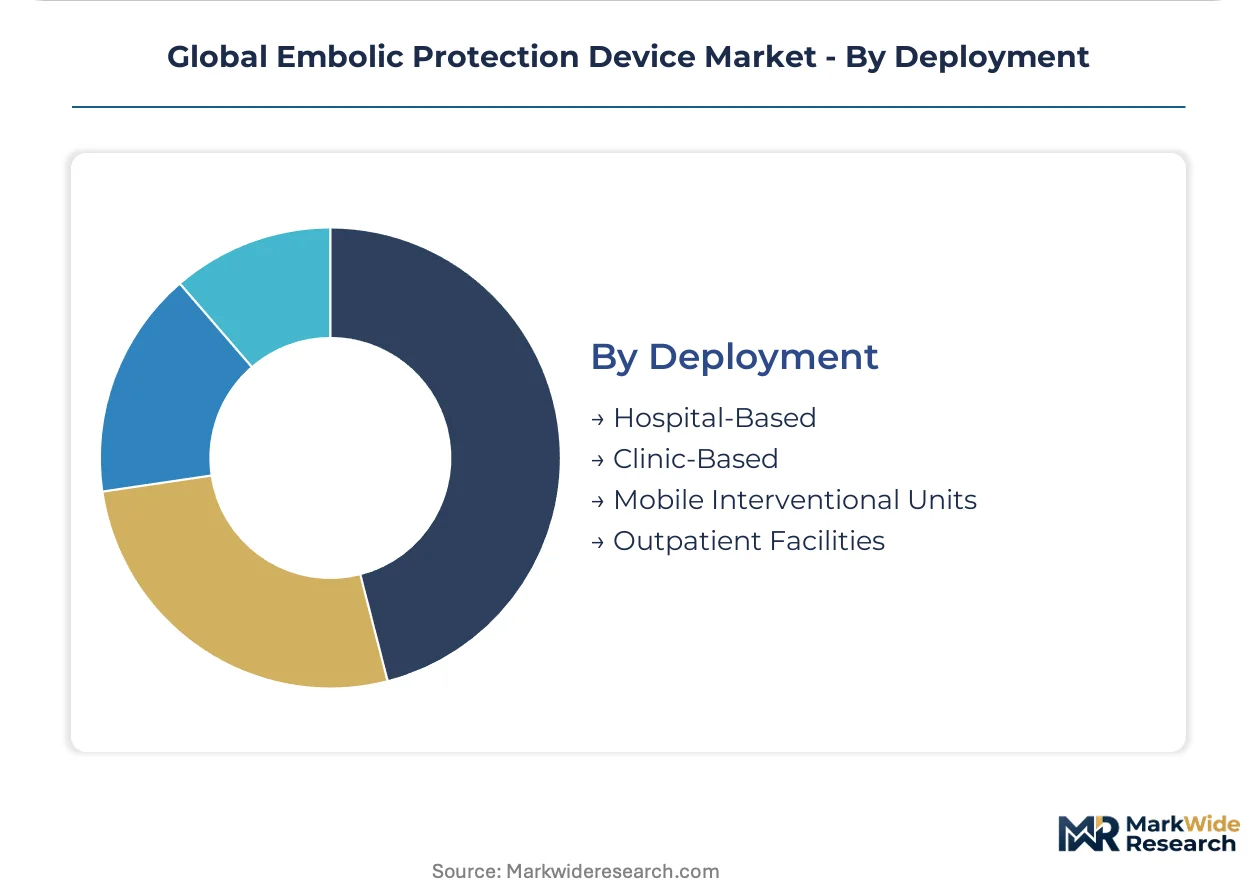
- Hospital-Based:Inpatient and outpatient cath labs with 24-hour surgical backup manage high-risk carotid and complex coronary interventions. Germany's hospital outpatient department reimbursement parity sustains procedure volumes exceeding ambulatory alternatives.
- Clinic-Based:Office-based interventional suites with limited emergency response capabilities concentrate on lower-risk peripheral procedures.
- Mobile Interventional Units:Containerized cath labs serve rural or temporary deployment scenarios with standardized device inventories.
- Outpatient Facilities:Standalone centers without overnight admission capacity pursue same-day discharge protocols.
Hospital-Based deployment holds volume leadership. Outpatient Facilities show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German hospital outpatient departments where reimbursement parity sustains premium device ASPs, while Japanese procurement channels filter non-domestic entrants through PMDA-mandated local trial requirements.
United States
Academic medical centers in Boston and Cleveland anchor procedural volumes for high-risk carotid interventions. FDA 510(k) clearance pathways shape product development timelines through enhanced scrutiny of predicate device claims. Integrated delivery networks across the Midwest and Southeast consolidate vendor relationships around structural heart procedure bundles.
Germany
Bavarian and North Rhine-Westphalia hospital networks sustain the deepest cath lab density in Europe. EU MDR conformity assessments compress revenue recognition windows for legacy device recertification. Specialty hospitals in Munich and Düsseldorf drive adoption of distal filter devices through established physician training pathways.
Japan
Tertiary centers in Tokyo and Osaka utilize proximal occlusion systems for complete flow cessation during complex plaque manipulation. PMDA domestic clinical data requirements filter non-Japanese manufacturers from hospital procurement channels. METI-supported interventional radiology training programs expand operator capacity for membrane-based protection devices.
India
Rising diabetes prevalence in Maharashtra and Karnataka creates whitespace for peripheral vascular protection adoption. CDSCO regulatory pathways for Class C medical devices extend market entry timelines for foreign manufacturers. Interventional radiology training programs in Mumbai and Bangalore expand addressable operator pools for renal and lower-limb interventions.
China
Yangtze River Delta hospital clusters in Shanghai and Suzhou pilot robotic navigation integration with filter-based protection systems. NMPA innovation pathway designations accelerate review timelines for domestically developed devices. Domestic nitinol mesh processors in Jiangsu province reduce input material dependence for regional device manufacturers.
Global Embolic Protection Device Market Competitive Landscape
Integrated cardiovascular conglomerates and specialized structural heart players split the market between bundled portfolio offerings and focused protection system innovation. The vendor base concentrates around three archetypes: diversified medtech giants with structural heart portfolios, dedicated embolic protection specialists, and diversified catheter manufacturers leveraging compatibility breadth. Competitive dynamics center on multi-year supply agreements with integrated delivery networks and regulatory capacity expansion for EU MDR technical documentation.
Among diversified medtech conglomerates, Medtronic and Boston Scientific Corporation exemplify portfolio-scale competitive positioning, while Abbott Laboratories anchors the catheter compatibility vector. W. L. Gore & Associates occupies a specialist position within the membrane filtration segment. These named entities represent strategic archetypes rather than exhaustive market coverage, with each exemplifying distinct approaches to cath lab procurement consolidation and regulatory evidence generation.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Cardinal Health |
| Medtronic |
| Contego Medical |
| Silk Road Medical |
| Boston Scientific Corporation |
| Terumo Corporation |
| Edwards Lifesciences Corporation |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Jiangsu province's nitinol mesh processing clusters anchor global supply capacity for superelastic alloy components, translating upstream concentration into asymmetric pricing power for device manufacturers serving German hospital outpatient departments and United States academic medical centers.
Pricing Analysis
Configured-to-order pricing for patient-specific delivery systems commands a 25-40% premium over standard catalog configurations. The dominant structure is contract-based long-term offtake tied to integrated delivery network volume commitments, with price differentiation hinging on catheter compatibility breadth and EU MDR certification tier. Pricing pressure stems from hospital procurement consortium consolidation, which compresses margins for standalone device sales. Ambulatory surgical centers exhibit the highest price sensitivity due to same-day discharge reimbursement constraints, while German specialty hospitals sustain premium tolerance through DRG-based reimbursement parity.
Supply Chain Analysis
Contract manufacturing concentrates among nitinol wire-forming specialists in Jiangsu province, precision catheter extrusion houses in Massachusetts and Minnesota, and membrane lamination facilities in Ireland and Germany. Geographic supply concentration clusters in China for raw nitinol alloy, the United States for catheter delivery systems, and Germany for polyurethane membrane filtration elements. Raw material dependencies include nickel-titanium superelastic alloy, medical-grade polyurethane, and radiopaque marker bands. Single-source vulnerability in nitinol alloy supply chains exposes manufacturers to allocation risk during specialty metal processor capacity constraints. Distribution runs through hospital procurement consortiums and group purchasing organizations that consolidate cath lab purchasing across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against next-generation proximal occlusion systems that threaten to displace established distal filter architectures through superior debris capture efficiency.
For Market Incumbents: Harden EU MDR technical documentation capabilities to compress legacy device recertification timelines and prevent revenue recognition gaps. Deepen backward integration into nitinol wire-forming to secure alloy supply against specialty metal processor allocation risk. Anchor hospital system partnerships through bundled structural heart procedure contracts that embed protection devices as non-negotiable line items, neutralizing standalone price competition from emerging membrane filtration specialists. For New Entrants and Emerging Players: Build out peripheral vascular protection offerings for India's underpenetrated renal and lower-limb intervention segments, where rising diabetes prevalence expands addressable procedure volumes faster than established cerebral markets. Target interventional radiology training programs in Mumbai and Bangalore as channel entry points. Pursue CDSCO regulatory pathway efficiency by partnering with domestic Indian manufacturers for Class C device registration, circumventing extended foreign entrant timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hospital procurement consortium concentration favors scaled portfolios with catheter compatibility breadth and multi-year supply agreement capacity. Acquisition targets should demonstrate EU MDR technical documentation readiness and established relationships with German hospital networks or United States integrated delivery networks. The signal to watch is CMS national coverage determination expansion for transcatheter procedures in ambulatory surgical centers, which would accelerate site-of-care migration and reshape device form factor requirements.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates legacy device recertification timelines and prevents revenue compression from conformity assessment delays. |
| Hospital System Partnership Expansion | Secures multi-year supply agreements with integrated delivery networks through bundled structural heart procedure contracts. |
| Peripheral Vascular Portfolio Development | Captures whitespace in India's renal and lower-limb intervention segments ahead of domestic competitor scale-up. |
| Nitinol Alloy Supply Security | Mitigates single-source vulnerability through captive wire-forming capacity or long-term offtake with Jiangsu processors. |
| Robotic Navigation Platform Integration | Enables remote procedure capabilities and operator skill democratization through convergence with magnetic catheter steering. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional cardiologists, cath lab managers, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement consortium contract disclosures, CMS national coverage determination records, and nitinol alloy trade flow data. Bottom-up procedure volume estimates were triangulated against top-down market value reconstructions.
Calibration against historical procedure adoption curves and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include device architecture, anatomical application, deployment setting, and end-user facility type, with additional stratification by regulatory pathway cluster. CAGRs were derived from slope-consistent growth trajectory fitting rather than endpoint interpolation. Key forecast inputs incorporated cath lab density projections, reimbursement policy evolution, and interventional radiology training program expansion rates.
Sensitivities concentrate around EU MDR recertification timeline extensions, CMS national coverage determination delays for ambulatory surgical centers, and nitinol alloy supply allocation disruptions. Forecasts embed assumptions regarding physician training bandwidth for proximal occlusion technique adoption and hospital procurement consortium consolidation velocity. Quarterly review of FDA 510(k) clearance issuance patterns, German DRG reimbursement adjustments, and PMDA domestic clinical data requirement modifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Asthma Spacers Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Italy Drug Delivery Devices Market