
 Microservices Architecture Market | 2026-2036
Microservices Architecture Market Size, Share, and Industry Trends Forecast 2026-2036
Microservices Architecture Market Intelligence
The shift from monolithic applications to distributed systems is reconfiguring how enterprise software is developed, deployed, and scaled. Amazon Web Services leverages its dominant cloud infrastructure to offer a comprehensive suite of tools for building microservices. Microsoft Corporation competes by integrating its Azure platform with extensive developer services. IBM Corporation differentiates through its focus on hybrid cloud environments and enterprise-grade support for complex deployments.
Microservices architecture is a design approach structuring an application as a suite of small, independently deployable services. These services communicate using lightweight mechanisms, often an HTTP resource API, to achieve discrete business capabilities. This model enhances agility and scalability for complex software systems. Hybrid cloud deployments are gaining traction, while API gateways and container orchestration represent critical solution components for the demanding Retail & E-commerce sector.
Data governance regulations impose significant design constraints on microservices deployments. The EU's GDPR dictates strict data processing and residency rules, while the US HIPAA sets standards for health information, shaping service boundaries. These frameworks compel developers to build compliance into the architecture from the ground up. The central challenge for organizations becomes balancing the architectural benefits of speed and flexibility against the rising complexity of multi-jurisdictional compliance.
Market Dynamics
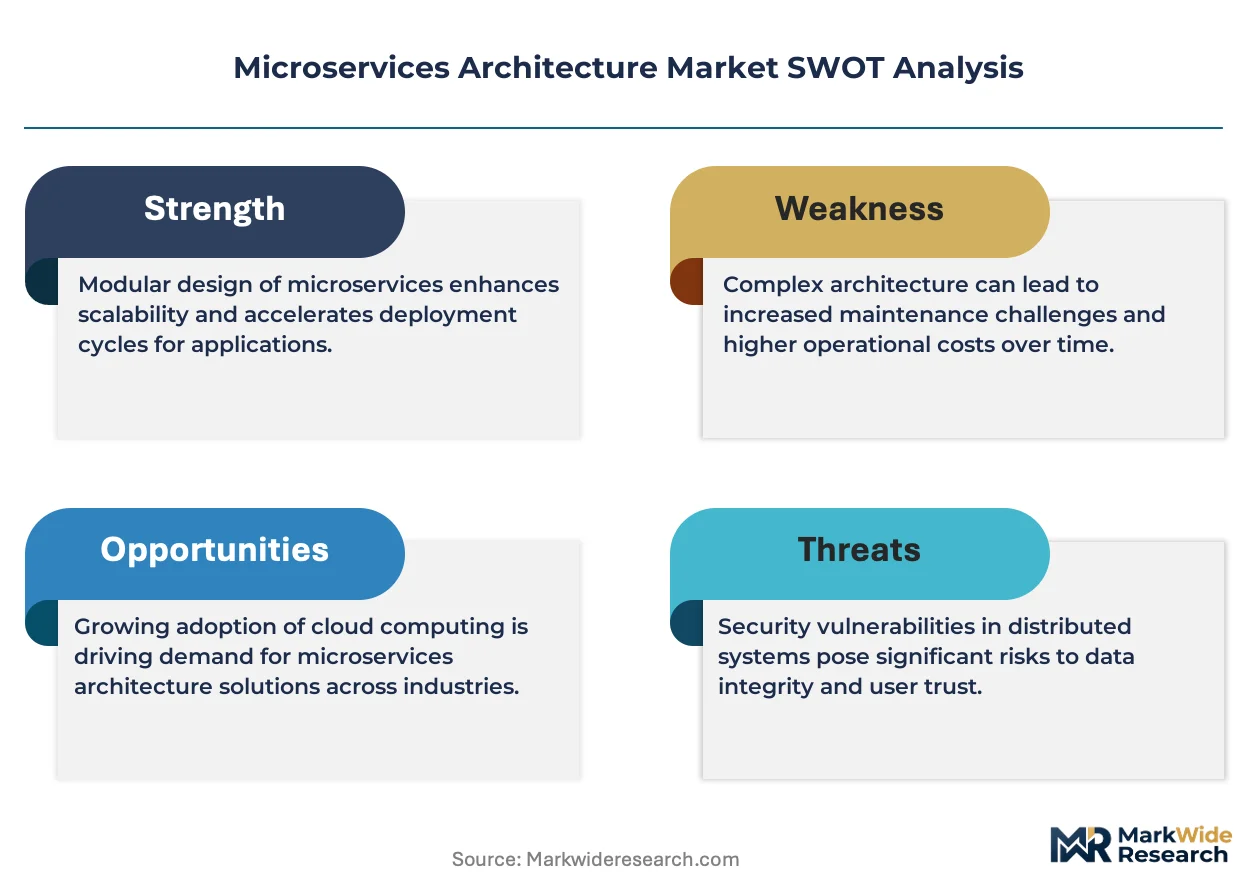
The central structural force shaping the market is the architectural tension between the pursuit of development velocity and the non-negotiable demands of multi-jurisdictional data governance, compelling a design-for-compliance approach from the outset of any new software initiative.
Growth Catalysts
- Container Orchestration Platforms:The widespread adoption of technologies like Kubernetes provides a standardized, scalable foundation for deploying and managing distributed services, significantly lowering the barrier to entry for organizations transitioning from monolithic systems.
- Legacy System Modernization:The Banking & Financial Services sector's urgent need to replace aging, inflexible core systems with agile, scalable architectures creates sustained demand for microservices-based solutions to improve competitiveness and customer experience.
- Concentrated Developer Ecosystems:Technology hubs within the United States and Germany, with their deep pools of software engineering talent and established cloud infrastructure, function as epicenters for innovation and adoption, driving architectural best practices.
Market Restraints
- Distributed System Complexity:The inherent complexity of managing service discovery, data consistency, and network latency in a distributed environment presents a significant technical barrier, requiring specialized skills and sophisticated tooling that many organizations lack.
- Regulatory Compliance Overhead:Adhering to data residency and processing rules, such as the EU's GDPR and the US's HIPAA, across geographically dispersed services complicates architectural design and increases operational overhead.
- High Initial Transition Costs:The substantial upfront investment required for new infrastructure, specialized tooling for observability and continuous integration, and extensive developer retraining deters many organizations from undertaking a full-scale migration from monoliths.
Strategic Opportunities
- AI and Machine Learning Integration:The convergence of microservices with AI/ML workloads offers a significant opportunity to build highly scalable, real-time intelligent applications, creating demand for specialized MLOps platforms that support distributed model deployment.
- Public Sector and Healthcare Expansion:Underpenetrated verticals like government and healthcare represent a major growth vector, as agencies seek to modernize large-scale, mission-critical applications for improved service delivery and data management.
- Serverless Computing Synergy:The rising adoption of Function-as-a-Service (FaaS) presents an opportunity for solutions that bridge serverless functions and containerized microservices, enabling developers to choose the optimal pattern for each specific business capability.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of experienced DevOps engineers and solution architects who can effectively design, secure, and operate complex, large-scale microservices deployments remains a primary operational bottleneck for enterprises.
- Legacy Integration Friction:The challenge of safely and efficiently integrating new, independently deployed services with deeply entrenched legacy systems creates complex hybrid environments that are difficult to monitor, manage, and secure.
- Expanded Security Attack Surface:Securing the vast network of inter-service communication APIs and endpoints against threats is a major operational hurdle, demanding a shift from perimeter-based security to a zero-trust model.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microservices Architecture Market |
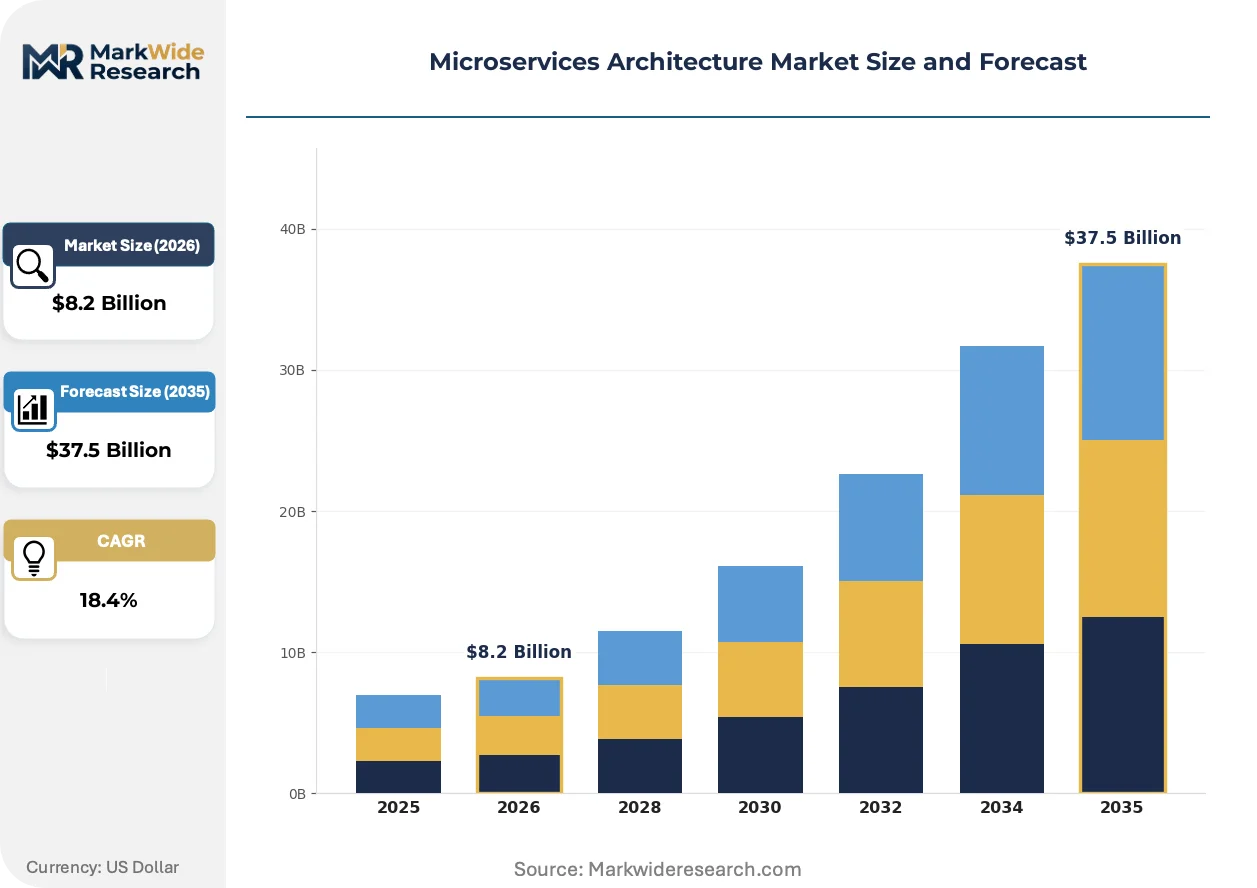
| Market Size in 2026 | $8.2 Billion |
| Market Size in 2035 | $37.5 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Service Mesh, API Gateway, Container Orchestration, Monitoring & Logging, Security & Compliance Application: Banking & Financial Services, Retail & E-Commerce, Telecommunications, Media & Entertainment, Education Technology End User: Software Development Firms, Cloud Service Providers, Independent Software Vendors, System Integrators |
| Companies Covered | Tata Consultancy Services Limited, Software AG, IBM Corporation, Netflix, Amazon Web Services, Microsoft Corporation, Salesforce.com, Datawire, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microservices Architecture Market Strategic Shifts & Innovations
The market's evolution reflects a maturation from simply decomposing monolithic applications to implementing sophisticated patterns and platforms. This shift emphasizes governance, security, and developer productivity to manage the inherent complexity of distributed systems at enterprise scale.
API gateways serve as a critical control plane, acting as a unified entry point for managing and securing external traffic to internal microservices. Enterprise teams within the Retail & E-commerce sector are adopting these tools to govern API access and enforce usage policies. The focus of these solutions is migrating from basic request routing toward advanced traffic shaping, canary deployments, and integrated security policy enforcement.
The forthcoming EU AI Act establishes a risk-based framework for artificial intelligence systems, creating new compliance imperatives. This regulation forces organizations to ensure data lineage, model explainability, and auditable decision-making within their software architectures. The Banking & Financial Services industry, a major user of algorithmic models, is consequently designing service architectures that embed transparency and traceability to meet these standards.
A fundamental shift in enterprise behavior is the move toward creating internal developer platforms (IDPs) to standardize the software delivery lifecycle. This platform engineering approach replaces fragmented, project-specific tooling with a centralized, self-service portal for building and deploying applications on approved infrastructure. The trend is most visible in large software organizations in the United States, where it boosts developer velocity and enforces architectural best practices.
Microservices Architecture Market Segmentation
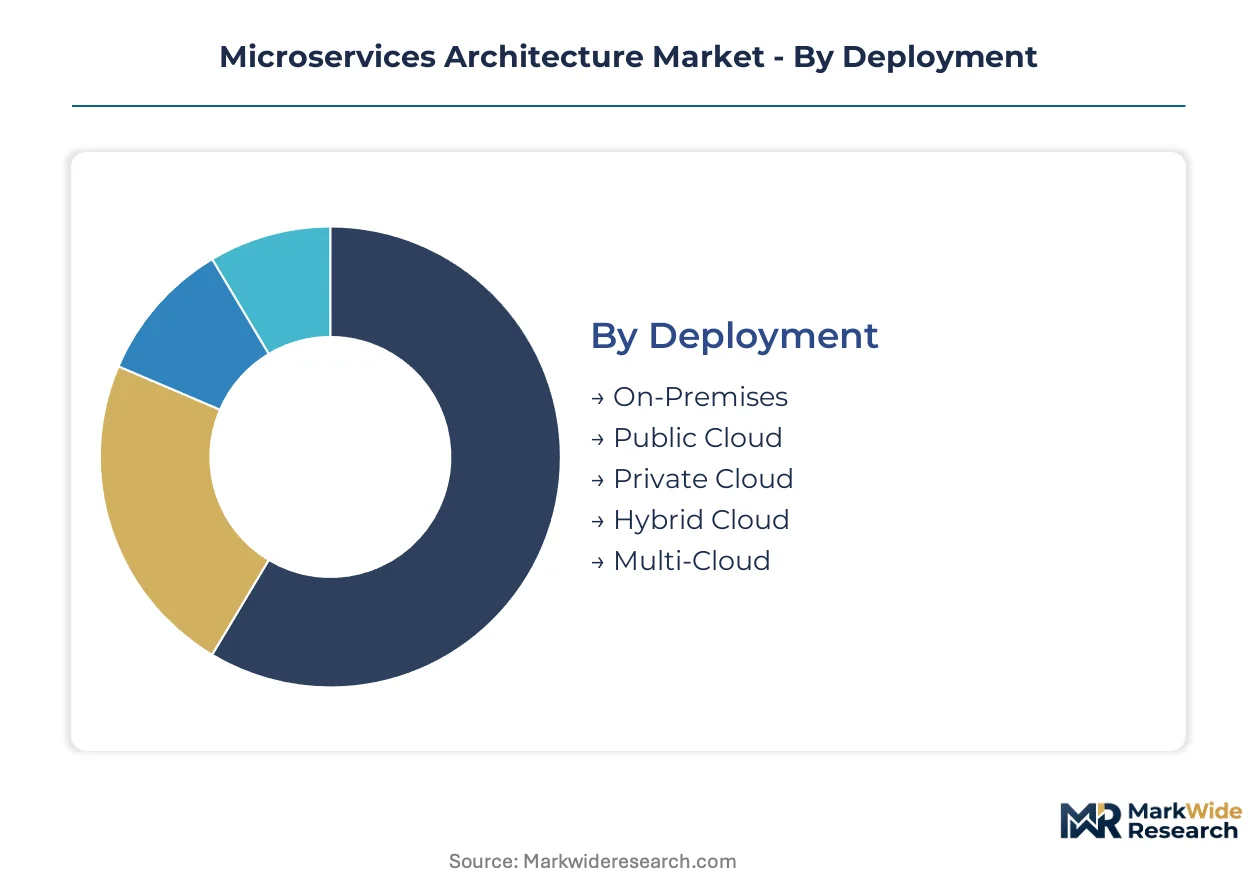
The Microservices Architecture Market is a dynamic landscape, segmented by key operational dimensions that define how these distributed systems are constructed, deployed, and consumed. Understanding these classifications is essential for analyzing market adoption patterns and identifying opportunities across various technology stacks and industry verticals.
Deployment:
The deployment model for microservices determines the underlying infrastructure and operational characteristics of the distributed application landscape.
- Public Cloud:This model involves deploying microservices on third-party cloud infrastructure, offering high scalability and reduced operational overhead. Demand is concentrating in technology hubs within the United States due to extensive cloud provider ecosystems and developer talent.
- Hybrid Cloud:This approach combines public cloud resources with private cloud or on-premises infrastructure, enabling organizations to leverage the benefits of both environments. The Banking & Financial Services sector utilizes hybrid cloud for strict data governance requirements while modernizing legacy systems.
- On-Premises:Microservices are deployed and managed entirely within an organization's own data centers, providing maximum control and security. This model is preferred by highly regulated industries with stringent data residency rules.
- Private Cloud:Dedicated cloud infrastructure, either on-premises or hosted by a third party, serves a single organization. Large enterprises with specific compliance needs often choose this deployment type.
- Multi-Cloud:This strategy involves using multiple public cloud providers simultaneously, enhancing resilience and avoiding vendor lock-in. Companies seek multi-cloud to optimize costs and leverage specialized services from different providers.
On-Premises commands the established base. The steepest expansion runs through Hybrid Cloud.
Solution Type:
The functional solution type categorizes the specialized tools and platforms that enable the effective development, management, and operation of microservices architectures.
- Container Orchestration:Platforms like Kubernetes automate the deployment, scaling, and management of containerized applications, providing a foundational layer for distributed services. Technology hubs in Germany are adopting these solutions to streamline complex software deployments.
- API Gateway:This solution acts as a single entry point for external API calls, handling request routing, composition, and protocol translation for microservices. The Retail & E-commerce sector relies on API gateways for managing high volumes of external traffic and enforcing security policies.
- Service Mesh:An infrastructure layer that enables managed, observable, and secure communication between microservices, offloading these concerns from application code. Large software organizations in the United States are utilizing service meshes to enhance developer productivity.
- Monitoring & Logging:Tools that collect, aggregate, and analyze data from microservices to ensure performance, identify issues, and maintain system health. These solutions are critical for managing the distributed system complexity inherent in microservices.
- Security & Compliance:Solutions focused on protecting microservices from threats and ensuring adherence to regulatory requirements like GDPR and HIPAA. The Banking & Financial Services industry integrates these tools to embed compliance into architectural design.
Solutions like Container Orchestration form the foundational layer. Demand for API Gateway is expanding most quickly.
Application:
The industry application of microservices architecture highlights the specific sectors that are leveraging this architectural paradigm for their software systems.
- Banking & Financial Services:This sector uses microservices to modernize legacy systems, enhance agility, and build new digital banking products. Financial institutions are designing service architectures to meet EU AI Act transparency requirements.
- Retail & E-Commerce:Microservices enable retailers to scale their online platforms, manage diverse product catalogs, and rapidly deploy new features. The sector uses API gateways and container orchestration for demanding transactional workloads.
- Telecommunications:Telecom operators adopt microservices for building flexible network services, managing customer relationship platforms, and supporting 5G infrastructure. This enables rapid service innovation and deployment.
- Media & Entertainment:Companies in this sector leverage microservices for content delivery networks, streaming platforms, and personalized user experiences. Scalability and rapid feature deployment are critical for competitive advantage.
- Education Technology:EdTech platforms utilize microservices to deliver modular learning content, manage student data, and integrate various educational tools. This architecture supports flexible and personalized learning environments.
Banking & Financial Services represents a mature segment. Retail & E-Commerce is gaining share fastest.
End User:
The primary end user type delineates the organizational entities that procure and implement microservices architecture solutions to support their business operations.
- Software Development Firms:These companies adopt microservices to enhance their development velocity, build scalable applications, and manage complex software portfolios. They often create internal developer platforms to standardize workflows.
- Cloud Service Providers:These providers offer the underlying infrastructure and managed services that facilitate microservices deployments for their customers. Amazon Web Services and Microsoft Corporation leverage their platforms for comprehensive microservices tools.
- Independent Software Vendors:ISVs integrate microservices into their product offerings to improve modularity, scalability, and ease of maintenance for their commercial software. This allows for more frequent updates and feature releases.
- System Integrators:SIs specialize in designing, implementing, and integrating microservices architectures for their enterprise clients. They address challenges like legacy integration friction and distributed system complexity.
Software Development Firms drives significant initial adoption. Cloud Service Providers is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' advanced software development ecosystem exports architectural best practices, influencing widespread microservices adoption across European and Asian technology hubs. This paradigm shift supports digital transformation initiatives in diverse industry verticals globally. Organizations prioritize agility and scalability in their distributed system deployments.
United States
The United States demonstrates robust demand for microservices, driven by its extensive software development ecosystems and large cloud provider presence. HIPAA regulations shape data handling requirements within healthcare microservices deployments. Technology hubs like Silicon Valley and Seattle foster innovation in distributed system design and implementation.
Germany
German enterprises increasingly adopt microservices to streamline complex software deployments, particularly in automotive and manufacturing sectors. The EU AI Act imposes new compliance imperatives for AI systems integrated into microservices, demanding explainability and auditability. Technology centers in Munich and Berlin lead the development of container orchestration solutions.
United Kingdom
The United Kingdom's financial services sector actively modernizes legacy systems with microservices, enhancing agility for digital banking products. UK data protection laws, mirroring GDPR, influence service boundaries and data residency decisions. London and Manchester serve as key hubs for fintech innovation and cloud-native development.
India
India exhibits significant microservices adoption, fueled by its rapid digital transformation initiatives across telecommunications and e-commerce. The upcoming Data Protection Bill will mandate strict data residency and processing rules for distributed applications. Major IT centers in Bengaluru and Hyderabad are becoming epicenters for cloud-native software development.
Japan
Japanese enterprises are modernizing their core systems using microservices, particularly within the automotive and manufacturing industries. The Act on Protection of Personal Information (APPI) governs data handling practices, impacting architectural design choices. Tokyo and Osaka are critical centers for advanced software engineering and cloud infrastructure.
Microservices Architecture Market Key Industry Players
On the supply side, the industry is tiered, encompassing global cloud infrastructure giants, specialized software vendors, and numerous system integrators. This structure supports diverse enterprise needs, from foundational cloud services to bespoke microservices implementations. Key strategic archetypes include comprehensive platform providers, focused solution specialists, and expert integration partners. Companies pursue portfolio diversification and strategic partnerships to enhance their market reach and solution offerings.
Within the comprehensive platform provider archetype, Amazon Web Services and Microsoft Corporation exemplify the scale and breadth of cloud infrastructure offerings for microservices deployment. These global entities provide extensive toolsets, from container orchestration to API gateways, integrating deeply with their respective cloud ecosystems. IBM Corporation, a major technology firm, occupies a significant position through its focus on hybrid cloud environments and enterprise-grade support, catering to complex, regulated deployments. These firms collectively anchor the market's foundational technology layer, offering critical infrastructure and developer services that enable widespread microservices adoption across various industries.
| Leading Market Players |
|---|
| Tata Consultancy Services Limited |
| Software AG |
| IBM Corporation |
| Netflix |
| Amazon Web Services |
| Microsoft Corporation |
| Salesforce.com |
| Datawire |
| Oracle |
| Others |
Cost & Logistics Intelligence
Global cloud network infrastructure, serving as the digital freight corridor, shapes the cost dynamics of microservices deployment, directly influencing where supply concentrates and how pricing is differentiated across service tiers.
Pricing Analysis
The technology-generation pricing gap differentiates current-generation container orchestration platforms, offered via SaaS-tiered models, from more bespoke, project-based integration services for prior-generation monolithic systems. Price differentiation stems from the level of customization required for complex enterprise integrations and the specialized after-sales support provided. Pricing pressure intensifies for basic platform services due to robust open-source alternatives and intense competition among cloud providers. Small and mid-sized startups exhibit the highest price sensitivity, while large enterprises in highly regulated sectors prioritize value and compliance over cost.
Supply Chain Analysis
Cloud infrastructure providers, acting as the foundational "contract manufacturers" for digital services, concentrate capacity in the United States, Germany, and India. The supply chain draws from critical raw materials like open-source software frameworks, a global pool of specialized developer talent, and scalable cloud compute resources. A significant structural risk is the scarcity of experienced DevOps engineers, creating bottlenecks in implementation and ongoing management. Distribution primarily runs through direct sales channels from major cloud providers and specialized software vendors, complemented by system integrators offering bespoke implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Microservices Architecture Market is experiencing a cyclical recovery, driven by renewed enterprise IT spending and a strategic focus on digital transformation initiatives.
For Market Incumbents: Harden core platform offerings by deepening integration with adjacent cloud services and acquiring niche specialists in areas like service mesh or AI/ML operations. This strategy counters the threat of fragmentation from specialized open-source tools and the scarcity of high-end talent. Leverage existing cloud ecosystem lock-in to provide comprehensive, enterprise-grade solutions, focusing R&D on advanced security and compliance features.
For New Entrants and Emerging Players: Public sector modernization projects and large-scale healthcare data management solutions represent the most penetrable entry points. Mid-sized enterprises in emerging technology hubs seeking compliance-as-a-service offerings also present significant white-space opportunities. A focused go-to-market angle should emphasize vertical-specific compliance automation and simplified migration pathways for legacy systems.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger technology conglomerates divesting non-core microservices tooling or from specialized consulting firms with deep vertical expertise. The long-term viability of this market remains strong over the next 5-10 years, underpinned by continuous demand for scalable and agile software. Consolidation of internal developer platforms (IDPs) will be a key signal to watch as an inflection indicator for market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Platform Integration | Integrating microservices platforms with security and observability tools reduces operational complexity for enterprises. |
| Strategic Partnership with Cloud Providers | Collaborating with major cloud providers expands market reach and ensures compatibility with foundational infrastructure. |
| Acquisition of Niche Compliance Firms | Acquiring specialized firms strengthens offerings in data governance and regulatory adherence for regulated industries. |
| Geographic Expansion into Emerging Hubs | Expanding into regions like India captures demand from rapidly digitizing local enterprises and developer ecosystems. |
| Product Launch: AI/ML Microservices Platform | Introducing platforms tailored for distributed AI/ML workloads addresses the growing need for intelligent, scalable applications. |
Research Approach
Initial hypotheses were tested against primary input from CTOs, DevOps engineers, solution architects, and compliance officers, and refined through iterative validation. This process combined in-depth interviews with secondary validation from SEC filings of major cloud providers, industry analyst reports, academic research on distributed systems, and regulatory body publications like GDPR and HIPAA. A robust triangulation approach integrated both bottom-up market sizing and top-down validation.
The demand-supply-balance framing informed the quantitative modeling approach across the projection horizon, incorporating historical trends and projected adoption rates. Segmentation dimensions modeled included deployment model, solution type, application, end-user, and regional regulatory environment. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of these factors, with key forecast inputs including enterprise IT spending forecasts and global developer talent pool growth projections.
Stress conditions across major regulatory shifts and economic downturns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological evolution and market acceptance. Quarterly review of enterprise cloud spending and regulatory announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
China EDA Electronic Design Automation Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Hybrid Events Software Market
Digital Solutions
Load Balancer Market
Digital Solutions
Global Online Dating Services Market