
 Computer Assisted Translation Software Market | 2026-2036
Computer Assisted Translation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Assisted Translation Software Market Outlook
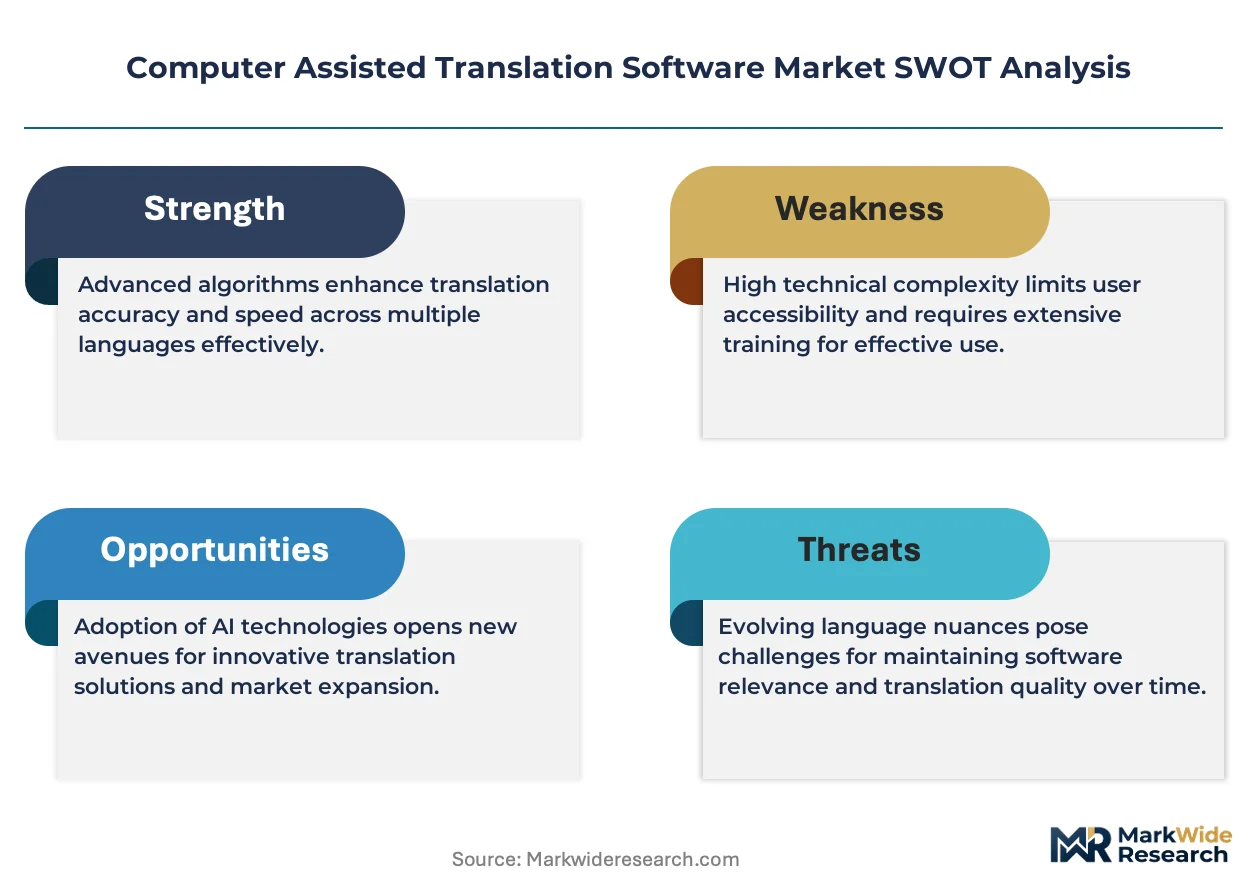
Platform licensing revenue is rewriting margin distribution across the Computer Assisted Translation Software value chain. SDL Trados leverages decades of translation memory specialization to anchor enterprise relationships across European manufacturing documentation workflows. DeepL competes on neural machine translation quality, sustaining premium positioning in European language pairs. Phrase (Memsource) extends cloud-native architecture to capture mid-market language service providers seeking scalable project orchestration.
Computer Assisted Translation Software encompasses tools that augment human translators through translation memory databases, terminology databases, and machine translation engines integrated into unified editing environments. These systems process source text through algorithmic suggestion layers while preserving human editorial control, serving commercial purposes from regulatory document localization to software interface translation. Machine translation segments are attracting R&D investment as neural architectures improve output fluency, while translation memory remains the mature margin pool where vendor lock-in sustains recurring revenue. Cloud-based deployment is expanding fastest among language service providers needing distributed team access, whereas on-premises installations persist in financial services and defense sectors with stringent data residency requirements.
The EU AI Act imposes transparency obligations on automated translation systems processing personal data, compelling vendors to document training data provenance and human oversight protocols. ISO 17100 quality standards for translation services shape procurement criteria, directing enterprise buyers toward certified toolchains with auditable workflow logs. Stakeholders must monitor how GDPR Article 22 automated decision-making interpretations apply to fully autonomous translation pipelines in legal and medical domains.
Market Dynamics
The EU AI Act is forcing vendors to reengineer neural translation pipelines around documented training provenance and human oversight protocols, compressing product development cycles while elevating compliance costs across European deployments.
Growth Catalysts
- Automotive documentation localization:German industrial exporters are mandating translation memory integration into supplier quality management systems, creating captive demand for enterprise-grade CAT toolchains.
- GDPR Article 22 interpretations:Legal and medical translation buyers are procuring auditable workflow logs to demonstrate human editorial control over machine-generated outputs.
- Cloud-native architecture migration:Mid-market language service providers are abandoning on-premises installations for distributed team access and elastic project orchestration.
Market Restraints
- Data residency compliance costs:Financial services and defense sector buyers require on-premises installations with localized server infrastructure, fragmenting vendor R&D allocation across deployment modes.
- Neural training data scarcity:Low-resource language pairs lack sufficient parallel corpora for fluency-competitive machine translation, constraining geographic expansion.
- ISO 17100 certification timelines:Translation service providers face 12-18 month audit cycles before enterprise buyers will authorize tool procurement.
Strategic Opportunities
- EU Green Deal documentation mandates:Sustainability reporting requirements in 27 member states are generating new demand for multilingual ESG disclosure translation.
- Medical device labeling convergence:MDR compliance is forcing harmonized multilingual IFU production, creating specialized workflow automation demand.
- Neural-TM hybrid architectures:Real-time suggestion engines that weight translation memory hits against neural fluency scores are opening premium pricing tiers.
Industry Challenges
- Computational linguist scarcity:Vendors struggle to hire specialists capable of tuning neural architectures for domain-specific terminology consistency.
- Legacy TMS integration friction:Enterprise buyers demand API compatibility with decades-old translation memory databases, slowing cloud migration roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Assisted Translation Software Market |
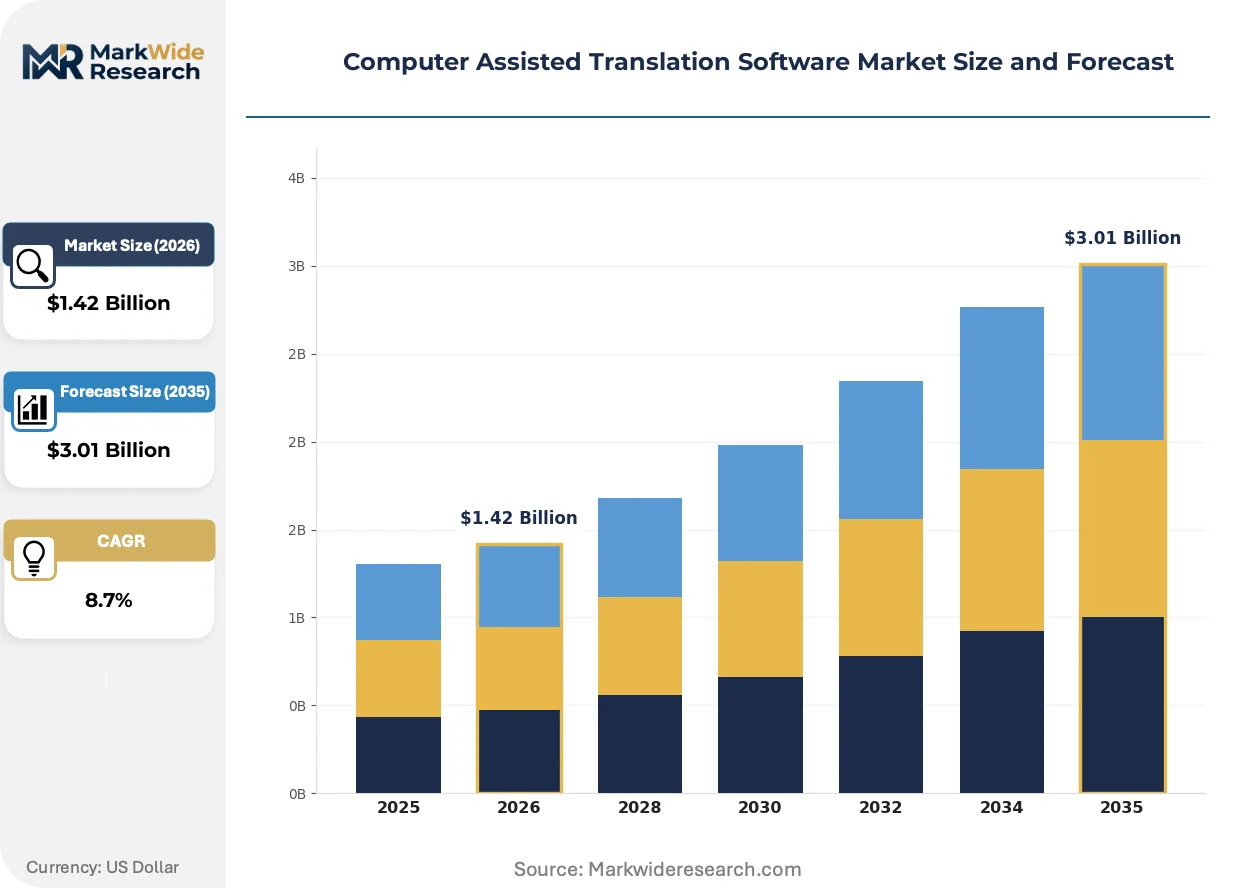
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machine Translation, Translation Memory, Terminology Management, Post-Editing End User: Enterprises, Freelancers, Language Service Providers, Educational Institutions Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Integration Level: API, Desktop Application, Web Application, Plugin |
| Companies Covered | Wordfast, DeepL, Phrase (Memsource), Across Systems, SDL Trados, Smartling, memoQ, Crowdin, SYSTRAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Assisted Translation Software Market Strategic Shifts
Neural machine translation architectures are compressing the value capture timeline for human-in-the-loop editing, while regulatory transparency mandates are redefining competitive differentiation around auditability rather than raw output quality.
Adaptive neural engines with real-time fine-tuning capabilities are rendering obsolete static phrase-based machine translation systems that required batch retraining for domain adaptation. Automotive documentation teams in Stuttgart and Wolfsburg are piloting these systems for same-day supplier manual localization. The technology is compressing project turnaround commitments from weeks to hours, forcing traditional translation memory vendors to accelerate neural integration roadmaps or cede mid-market share.
The EU AI Act's transparency obligations for automated systems processing personal data are compelling vendors to document training data provenance and maintain human oversight logs. This regulatory pressure is elevating procurement criteria toward certified toolchains with immutable workflow audit trails. Legal translation buyers in Frankfurt and medical localization teams in Basel are now requiring ISO 17100-aligned documentation before contract authorization.
Subscription-based pricing for cloud-native platforms is displacing perpetual license models among mid-market language service providers seeking operational expenditure predictability. This shift is compressing vendor cash conversion cycles while expanding addressable market reach to smaller agencies previously priced out of enterprise toolchains. The transformation is most visible in Germany, where fragmented translation vendor landscapes favor flexible scaling over capital-intensive on-premises deployment.
Computer Assisted Translation Software Market Segmentation
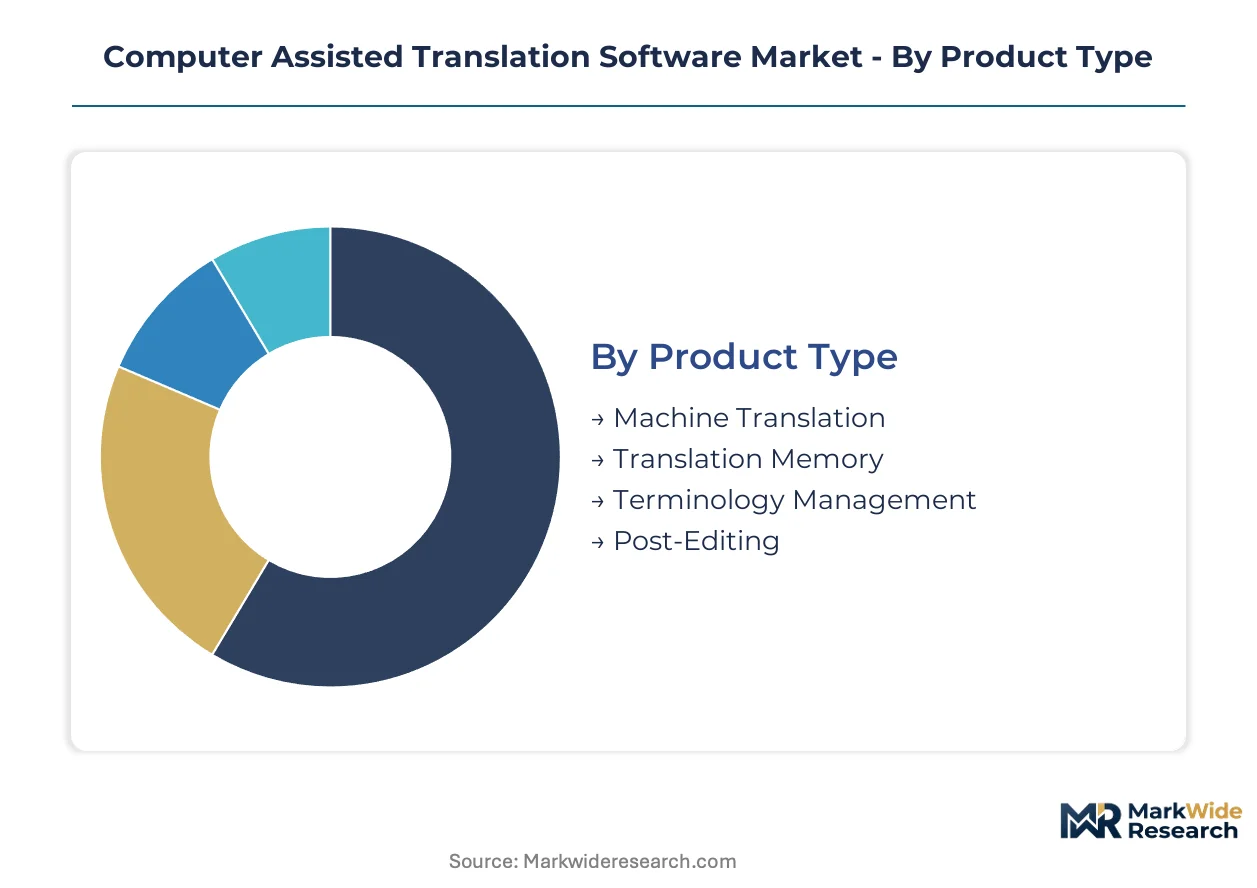
Segmentation in computer assisted translation software reveals how vendor R&D investment splits across deployment architectures and integration requirements. Procurement patterns diverge sharply between enterprise buyers demanding on-premises data control and mid-market language service providers prioritizing elastic cloud scaling.
Product Type:
After-sales service intensity varies dramatically across product categories, with neural engine maintenance requiring continuous computational linguist support while translation memory systems demand minimal ongoing vendor intervention.
- Machine Translation:Neural architectures process source text through deep learning models to generate target language fluency without human pre-translation. German automotive documentation teams in Stuttgart and Wolfsburg are mandating real-time neural integration into supplier quality systems, compressing localization timelines from weeks to hours. The segment demands the highest vendor support density for model retraining and domain adaptation.
- Translation Memory:Database systems store previously translated segments as reusable linguistic assets, enabling cost reduction through fuzzy matching algorithms. Enterprise buyers in Basel and Frankfurt prioritize TM integration for regulatory document versioning where consistency across audit cycles outweighs raw speed. The segment sustains the most predictable recurring revenue streams through seat-based licensing.
- Terminology Management:Controlled vocabulary systems enforce brand and regulatory term consistency across distributed translation teams.
- Post-Editing:Human-in-the-loop interfaces that refine machine-generated output through specialized editing environments for quality assurance.
Translation Memory holds the largest share; momentum sits with Machine Translation.
End User:
Cost tier stratification separates capital-intensive enterprise deployments from operational-expenditure-focused freelancer subscriptions.
- Enterprises:Large organizations operating centralized localization departments with dedicated procurement authority over multi-year tool contracts. Financial services buyers in London and Zurich require on-premises installations with localized server infrastructure to satisfy data residency mandates, fragmenting vendor deployment roadmaps.
- Language Service Providers:Mid-market translation agencies orchestrating distributed freelancer networks through cloud-native project management platforms. These buyers in Berlin and Munich are abandoning perpetual licenses for subscription pricing that matches project volume volatility.
- Freelancers:Individual translators purchasing single-seat licenses with limited integration requirements.
- Educational Institutions:University translation programs training students on industry-standard toolchains through academic licensing arrangements.
Enterprises dominate current procurement value; Language Service Providers are expanding most quickly.
Deployment:
Volume concentration in cloud-native architectures is displacing on-premises installations among buyers without stringent data sovereignty requirements.
- Cloud-Based:Fully hosted solutions delivering browser-accessible translation environments without client-side infrastructure. Mid-market agencies across Germany favor this model for distributed team access and elimination of capital expenditure.
- On-Premises:Locally installed server infrastructure maintaining complete data control within organizational firewalls. Defense sector and classified government translation workflows in France and Switzerland mandate this architecture.
- Hybrid:Mixed deployments combining cloud accessibility for project management with on-premises processing for sensitive content.
- SaaS:Software-as-a-service delivery with multi-tenant architecture and automatic feature updates.
Cloud-Based configurations hold the largest share; Hybrid deployments are gaining share fastest.
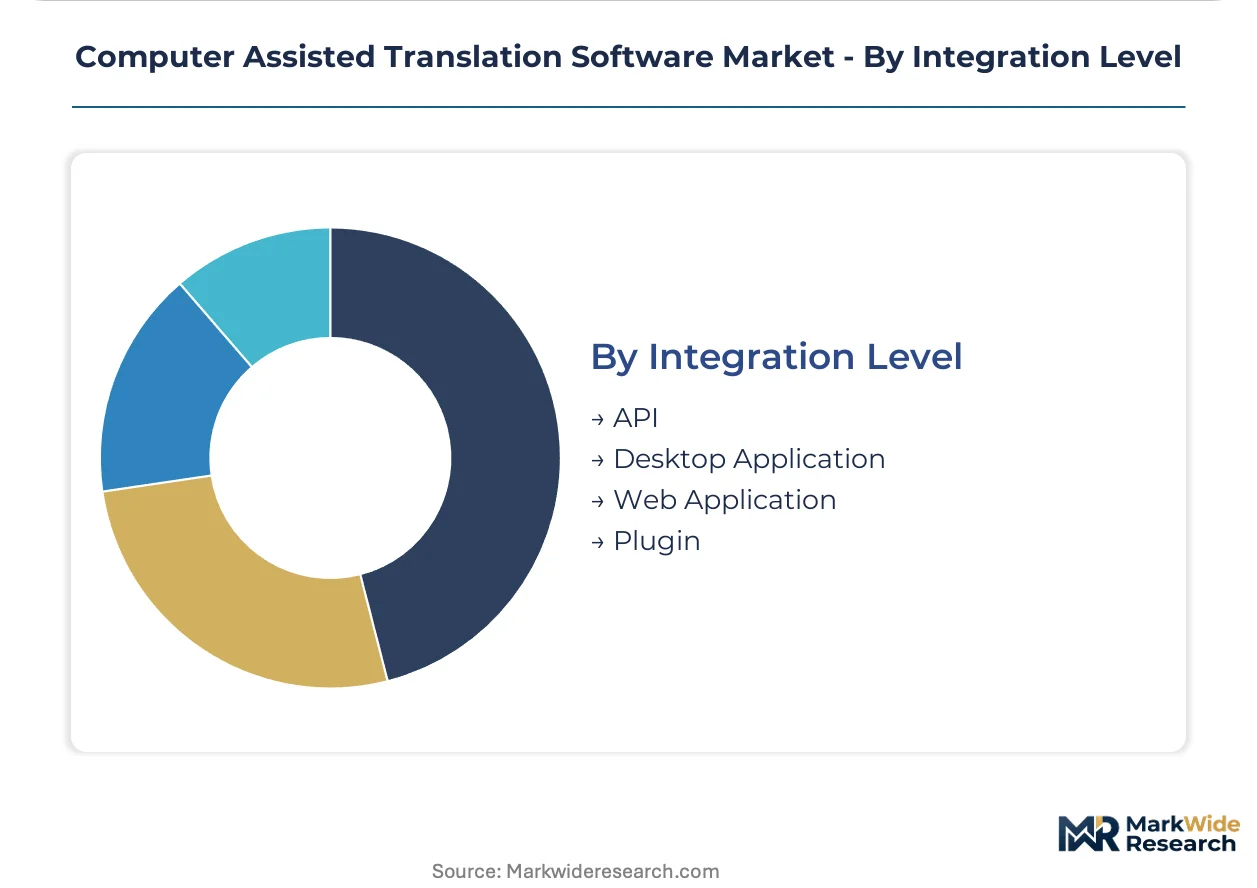
Integration Level:
Customer type differentiation separates API-first buyers building custom workflows from plug-and-seek desktop users.
- API:Programmatic interfaces enabling headless translation pipelines embedded within content management and e-commerce systems. Enterprise developers in Amsterdam and Copenhagen prioritize REST API coverage for automated documentation generation.
- Desktop Application:Native software installations providing offline editing capabilities with local file system integration.
- Web Application:Browser-based editing environments requiring no local installation for immediate translator onboarding.
- Plugin:Extension modules embedding translation functionality directly within Microsoft Word, Adobe InDesign, and content management platforms.
API integrations command premium pricing tiers; Web Application access is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes Computer Assisted Translation Software through industrial documentation workflows, while the United States and United Kingdom prioritize cloud-native platforms for technology localization, creating divergent procurement patterns across major markets.
Germany
Automotive documentation teams in Stuttgart and Wolfsburg mandate translation memory integration into supplier quality management systems. The EU AI Act compels vendors to document training data provenance for neural translation pipelines processing personal data. Enterprise buyers in Frankfurt require ISO 17100-aligned audit trails before authorizing tool procurement for legal and medical translation workflows.
United States
Technology companies in Silicon Valley and Seattle deploy API-first translation pipelines for software interface localization at scale. FDA guidance on medical device labeling drives demand for auditable workflow logs demonstrating human editorial control. Financial services buyers in New York require hybrid deployments combining cloud accessibility with on-premises processing for sensitive regulatory filings.
United Kingdom
Language service providers in London and Manchester accelerate migration from perpetual licenses to subscription-based cloud platforms. The UK Information Commissioner's Office interprets GDPR Article 22 automated decision-making provisions for translation workflows handling personal data. Publishing and media localization clusters in Oxford and Cambridge prioritize neural machine translation fluency for rapid content turnaround.
France
Defense sector translation workflows in Paris and Toulouse mandate on-premises installations with localized server infrastructure for classified content. ANSM and CNIL oversight of medical and personal data processing shapes vendor compliance roadmaps. Luxury goods documentation teams in Lyon apply terminology management systems to enforce brand consistency across multilingual marketing materials.
Switzerland
Pharmaceutical localization teams in Basel require Swissmedic-aligned quality documentation for multilingual IFU production under MDR compliance. Financial services buyers in Zurich maintain on-premises CAT toolchains to satisfy data residency mandates. Precision engineering exporters in Geneva integrate translation memory systems into technical documentation workflows for global distribution.
Computer Assisted Translation Software Market Competitive Environment
Capability concentration sits with specialized translation memory vendors; scale advantage sits with cloud-native platform providers. The market structures around three tiers: established European vendors with decades of enterprise relationships, mid-market cloud specialists capturing language service provider migrations, and API-first entrants targeting developer-embedded workflows. Dominant competitive moves include neural-TM hybrid architecture development and compliance certification acceleration for EU AI Act readiness.
Within the specialized tier, SDL Trados and memoQ occupy positions anchored by translation memory specialization and enterprise workflow integration. DeepL exemplifies the quality-centric neural engine archetype competing on European language pair fluency. Phrase (Memsource) represents the cloud-native scale play targeting mid-market language service providers with elastic project orchestration capabilities.
| Leading Market Players |
|---|
| Wordfast |
| DeepL |
| Phrase (Memsource) |
| Across Systems |
| SDL Trados |
| Smartling |
| memoQ |
| Crowdin |
| SYSTRAN |
| Others |
Value Chain & Pricing Dynamics
Stuttgart and Wolfsburg automotive clusters anchor neural translation engine development capacity, concentrating vendor R&D investment and compressing margin structures for mid-market language service providers downstream.
Pricing Analysis
Long-term enterprise offtake contracts dominate procurement for financial services and defense sector buyers, while subscription-based SaaS tiers capture mid-market language service providers seeking operational expenditure predictability. Price differentiation rests on ISO 17100 certification grade and neural engine customization depth. Pricing pressure stems from cloud-native entrants undercutting perpetual license models. Freelancers exhibit highest price sensitivity; enterprise buyers with data residency mandates show lowest.
Supply Chain Analysis
Parallel corpora and annotated training datasets feed from Germany, the United States, and the United Kingdom as primary upstream inputs, with computational linguist talent pools and GPU cloud infrastructure as critical secondary dependencies. Supply chain risk centers on single-source vulnerability for low-resource language pair datasets. Distribution runs through direct vendor sales to enterprises and channel partnerships reaching mid-market agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational linguist scarcity constrains neural architecture tuning velocity, creating bottlenecks for vendors attempting domain-specific fluency improvements across European language pairs.
For Market Incumbents: Harden translation memory lock-in through API compatibility layers that slow cloud migration roadmaps for enterprise buyers with legacy database investments. Accelerate EU AI Act compliance certification to preempt regulatory displacement by audit-ready challengers. Prioritize captive supply of computational linguist talent through university partnership pipelines. For New Entrants and Emerging Players: Mid-market language service providers in Berlin and Munich represent the most penetrable entry point, as these buyers abandon perpetual licenses for elastic subscription pricing. Medical device labeling workflows under MDR compliance create specialized demand for auditable neural-TM hybrid architectures. Lead with browser-accessible web applications requiring zero infrastructure investment to accelerate trial-to-conversion cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native platform providers with demonstrated API-first integration capabilities over legacy desktop vendors. Long-term viability hinges on neural engine differentiation rather than translation memory scale. ISO 17100 certification velocity serves as the critical inflection signal separating acquisition-ready targets from compliance-lagged laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Neural-TM Hybrid Architecture Development | Real-time suggestion engines weighting memory hits against fluency scores command premium pricing tiers from automotive documentation teams. |
| EU AI Act Compliance Certification | Documented training provenance and human oversight protocols satisfy Frankfurt legal translation buyers and Basel medical localization teams. |
| Cloud-Native Platform Migration | Subscription pricing eliminates capital expenditure barriers for Berlin and Munich mid-market language service providers. |
| API-First Integration Expansion | REST API coverage enables embedded translation pipelines within Amsterdam and Copenhagen enterprise content management systems. |
| Computational Linguist Talent Acquisition | Domain-specific terminology consistency tuning requires specialists scarce across Stuttgart and Wolfsburg automotive clusters. |
Study Parameters
Initial hypotheses were tested against primary input from localization project managers, computational linguists, enterprise procurement officers, and language service provider executives and refined through secondary validation across SEC filings, EU regulatory databases, translation industry association reports, and cloud platform usage disclosures. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating neural engine R&D investment cycles and regulatory compliance timeline compression.
Practitioners should monitor EU AI Act enforcement interpretations and GDPR Article 22 legal precedent developments for early signals requiring forecast revision. Cross-checking against ISO certification database growth rates and cloud platform subscriber disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
3D Animation Software Market
Software & Services
Automotive Operating Systems Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Language Translation Software Market
Software & Services
Outsourced Software Testing Services Market
Software & Services
Desktop Publishing Software Market
Software & Services
United States Donation Management Software Market
Software & Services
Office Productivity Software Market
Software & Services
Global Project Software Market
Software & Services
Global Local SEO Software Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Europe Contract Lifecycle Management Software Market
Software & Services
Indoor Cycling Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Global Product Information Management (PIM) Software Market
Software & Services
Global Rapid Application Development Market