
 Global E-Signature Platform Market | 2026-2036
Global E-Signature Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Signature Platform Market Foresight
The EU Green Deal is pivoting enterprise procurement toward paperless audit trails and carbon-accountable contract workflows. DocuSign Inc leverages its cloud-native architecture to sustain leadership in workflow automation across European financial institutions. Adobe Inc anchors its competitive position through deep integration with document management ecosystems. OneSpan Inc specializes in high-assurance identity verification for regulated banking clients.
An e-signature platform is a software system that cryptographically binds a signer's identity to a document using public-key infrastructure and timestamped hash algorithms, creating legally enforceable electronic records. The primary commercial purpose is to eliminate physical document transit, reduce execution cycles from days to minutes, and embed tamper-evident proof into contractual workflows. Cloud-based deployment dominates volume due to elastic scaling and API-first integration, while on-premise installations retain preference among government bodies with data sovereignty constraints. Workflow automation solutions capture expanding margin pools as enterprises chain e-signatures into broader business process orchestration.
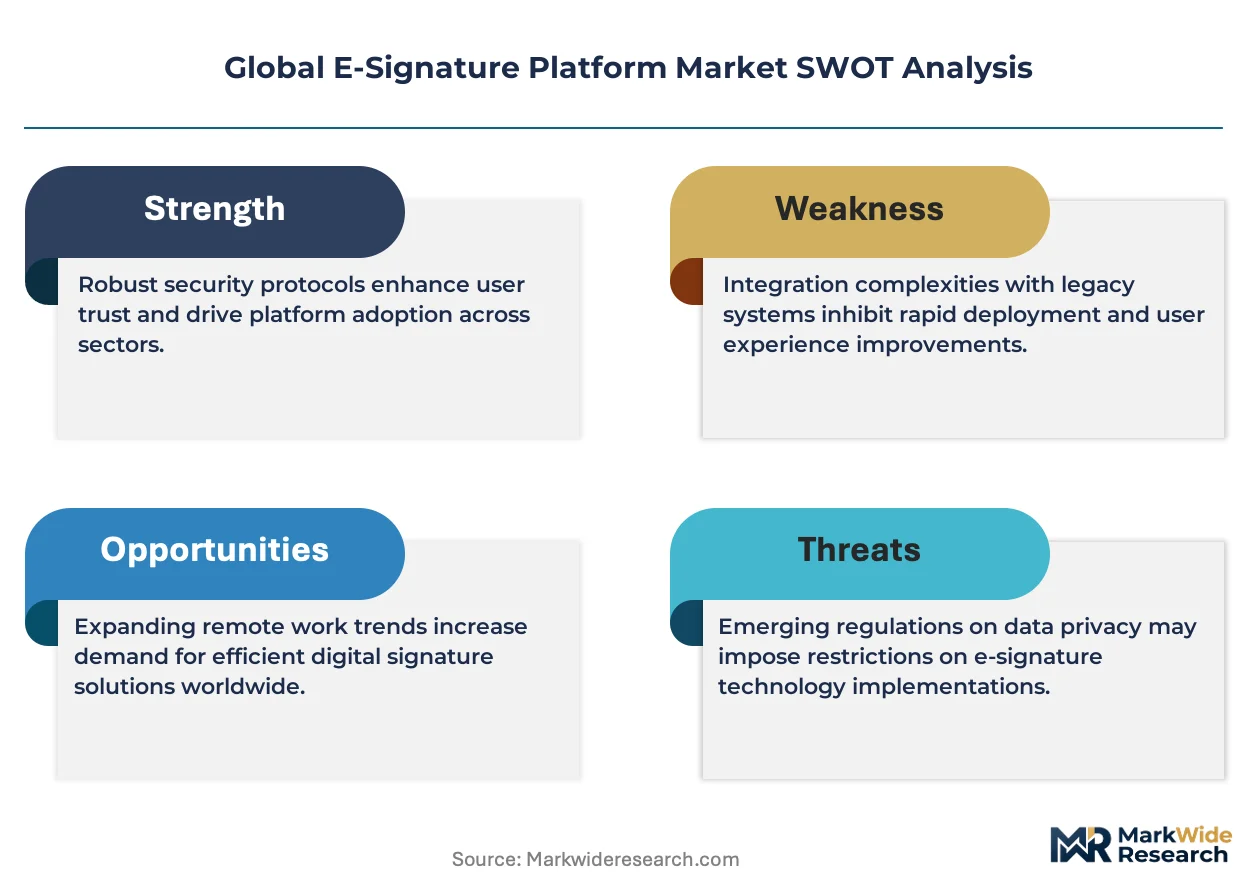
GDPR in Europe, the ESIGN Act in the United States, and India's IT Act collectively establish the legal validity of electronic signatures while imposing divergent standards for identity verification and data residency. The EU AI Act further shapes demand by classifying certain automated identity verification systems as high-risk, forcing platform providers to embed human oversight and algorithmic transparency. Stakeholders must monitor regulatory fragmentation between jurisdictions where e-signatures carry full legal weight versus markets where admissibility remains contested.
Market Dynamics
Regulatory fragmentation between jurisdictions is compressing platform architecture decisions, forcing providers to engineer modular compliance stacks that can toggle between GDPR's strict identity verification and the ESIGN Act's lighter evidentiary standards without code rewrites.
Growth Catalysts
- EU AI Act classification:High-risk system designations for automated identity verification are mandating human-in-the-loop workflows, creating specialized demand for audit-ready e-signature platforms among European banking infrastructure providers.
- Financial services digitization:Contract execution workflows in commercial lending and trade finance are eliminating wet-ink requirements, with loan origination systems embedding e-signature APIs directly into customer-facing portals.
- India's IT Act amendments:Enhanced legal recognition for electronic records in property transactions and government procurement is accelerating state-level adoption of paperless approval chains.
Market Restraints
- Public-key infrastructure concentration:Certificate authority services cluster in a handful of commercial providers, creating single-point-of-failure risk for cryptographic trust chains underpinning signature validity.
- Legacy system integration costs:On-premise document management systems in regulated industries require expensive middleware development to achieve API connectivity with cloud-native signing platforms.
- Cross-border admissibility gaps:E-signatures executed under US ESIGN standards face evidentiary challenges in jurisdictions lacking reciprocal recognition treaties, fragmenting contract enforceability.
Strategic Opportunities
- German Mittelstand manufacturing:Mid-sized industrial exporters remain underpenetrated for supply-chain contract automation, with procurement digitization mandates from automotive OEMs creating pull-through demand.
- Blockchain timestamp convergence:Distributed ledger anchoring of signature hashes is generating new product categories for immutable audit trails in commodities trading and carbon credit verification.
- Embedded insurance workflows:Policy issuance and claims settlement platforms are white-labeling e-signature modules, opening distribution through insurtech API marketplaces rather than direct enterprise sales.
Industry Challenges
- Cryptographic engineering talent scarcity:Qualified developers capable of implementing zero-knowledge proof architectures for privacy-preserving identity verification command premium compensation, constraining R&D velocity at mid-tier vendors.
- Multi-jurisdiction certification timelines:Achieving eIDAS qualified trust service provider status in Europe while maintaining SOC 2 Type II compliance in North America requires parallel audit tracks extending 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Signature Platform Market |
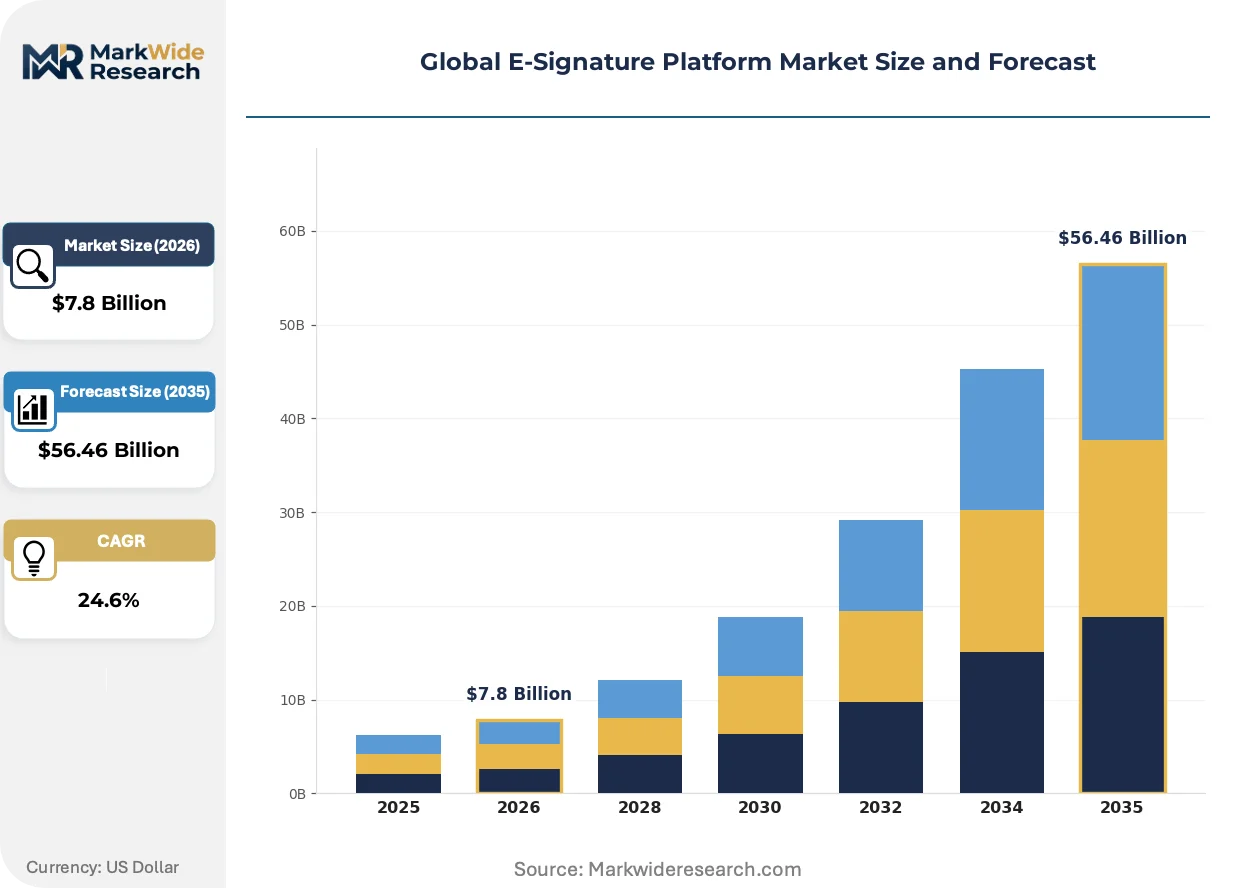
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $56.46 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution: Workflow Automation, Document Management, Identity Verification, Compliance Management, Audit Trail Application: Contract Execution, HR Onboarding, Financial Approvals, Legal Agreements, Procurement Process End User: Financial Institutions, Legal Firms, Real Estate Agencies, Educational Institutions, Government Bodies |
| Companies Covered | DocuSign Inc, Adobe Inc, OneSpan Inc, Zoho Corporation Pvt Ltd, Entrust Corporation, PandaDoc Inc, Thales, DigiCert, SignEasy Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Signature Platform Market Shifts & Advancements
Artificial intelligence is embedding into identity verification pipelines, shifting competitive advantage from signature capture speed toward real-time fraud detection accuracy during the authentication moment.
Biometric liveness detection is automating the elimination of synthetic identity fraud in high-value contract workflows. Investment banks and commercial real estate firms are deploying voiceprint and facial geometry matching as standard onboarding steps. This compression of identity assurance into sub-second verification is automating the removal of manual document review bottlenecks that previously delayed transaction closing.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated identity verification systems deployed in financial services. Providers must now maintain technical documentation proving human oversight capabilities and bias testing protocols. European banking supervisors are enforcing these requirements through periodic audits, with non-compliance triggering suspension of qualified trust service status.
Enterprise buyers are consolidating vendor relationships around platforms offering embedded workflow orchestration rather than standalone signature tools. Procurement teams in United States healthcare and German automotive supply chains are favoring solutions that chain e-signatures into broader business process automation. This preference shift is most visible in multi-year enterprise agreements where signing functionality is bundled with contract lifecycle management and clause extraction capabilities.
Global E-Signature Platform Market Segmentation
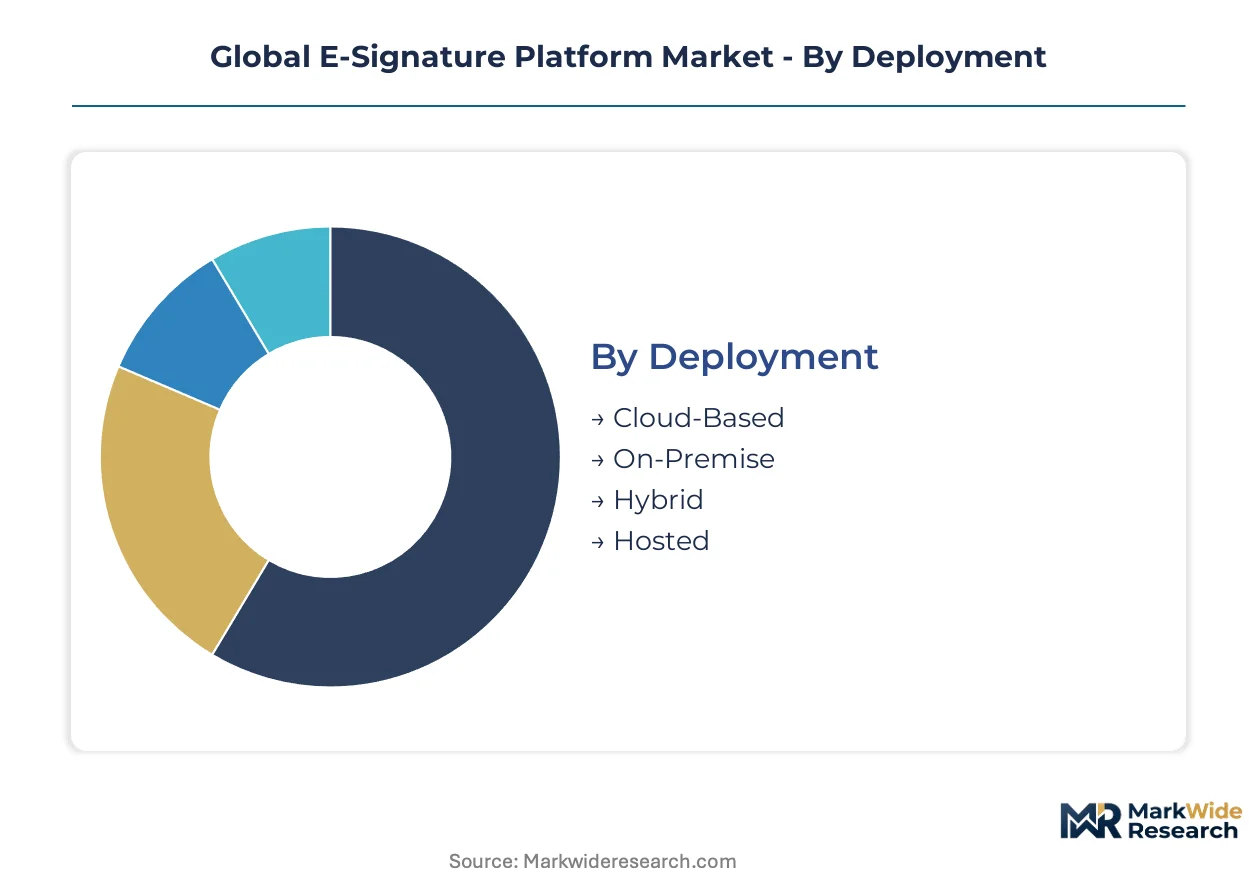
E-signature platform segmentation reveals how deployment architecture, solution bundling, and end-user compliance requirements reshape vendor economics. Understanding these divides exposes where margin pools concentrate and which configurations face commoditization pressure.
Deployment:
Supply concentration in certificate authority services and hyperscale cloud infrastructure is compressing deployment economics, with cryptographic trust chains clustering among a handful of commercial providers.
- Cloud-Based:Elastic scaling and API-first integration architectures dominate transaction volume. Financial institutions in Germany and the United States are standardizing on multi-tenant configurations to eliminate infrastructure overhead while maintaining ESIGN Act and eIDAS compliance through embedded trust service modules.
- On-Premise:Air-gapped installations with dedicated hardware security modules retain preference among government bodies with strict data sovereignty constraints. India's state-level procurement digitization is driving demand for sovereign-hosted deployments that keep signature hashes within national borders.
- Hybrid:Split architectures route sensitive identity verification on-premise while pushing document rendering to cloud edge nodes.
- Hosted:Single-tenant managed services offer compliance isolation without capital expenditure burden.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution:
Enterprise procurement teams are consolidating spend around bundled capabilities rather than standalone signature capture, compressing pricing for point solutions.
- Workflow Automation:Business process orchestration that chains e-signatures into broader approval pipelines commands expanding margin pools. German automotive OEMs are mandating procurement digitization that embeds signing into supply-chain contract lifecycle management.
- Identity Verification:Biometric liveness detection and document authentication modules face EU AI Act high-risk classification requirements. European banking supervisors are enforcing human-in-the-loop capabilities through periodic audits of algorithmic transparency documentation.
- Document Management:Repository integration with version control and collaborative editing.
- Compliance Management:Automated regulatory mapping across GDPR, ESIGN, and IT Act jurisdictions.
- Audit Trail:Immutable timestamped records with blockchain anchoring for commodities trading verification.
Workflow Automation captures the steepest expansion trajectory as enterprises replace fragmented tooling.
Application:
Application-level segmentation tracks how regulatory recognition of electronic records varies by document type, fragmenting enforceability across jurisdictions.
- Contract Execution:Commercial lending and trade finance workflows are eliminating wet-ink requirements through API-embedded signing portals. Loan origination systems in the United States are standardizing on real-time execution to compress closing cycles from days to minutes.
- Financial Approvals:Treasury authorization and investment committee sign-offs demand high-assurance identity verification with video-recorded consent capture. Investment banks are deploying voiceprint matching as standard onboarding steps for high-value transactions.
- HR Onboarding:Remote hiring workflows with I-9 verification and benefits enrollment.
- Legal Agreements:Law firm retainer and engagement letter execution with malpractice carrier integration.
- Procurement Process:Purchase order authorization and vendor master data updates.
Financial Approvals is gaining share fastest as capital markets digitization accelerates.
End User:
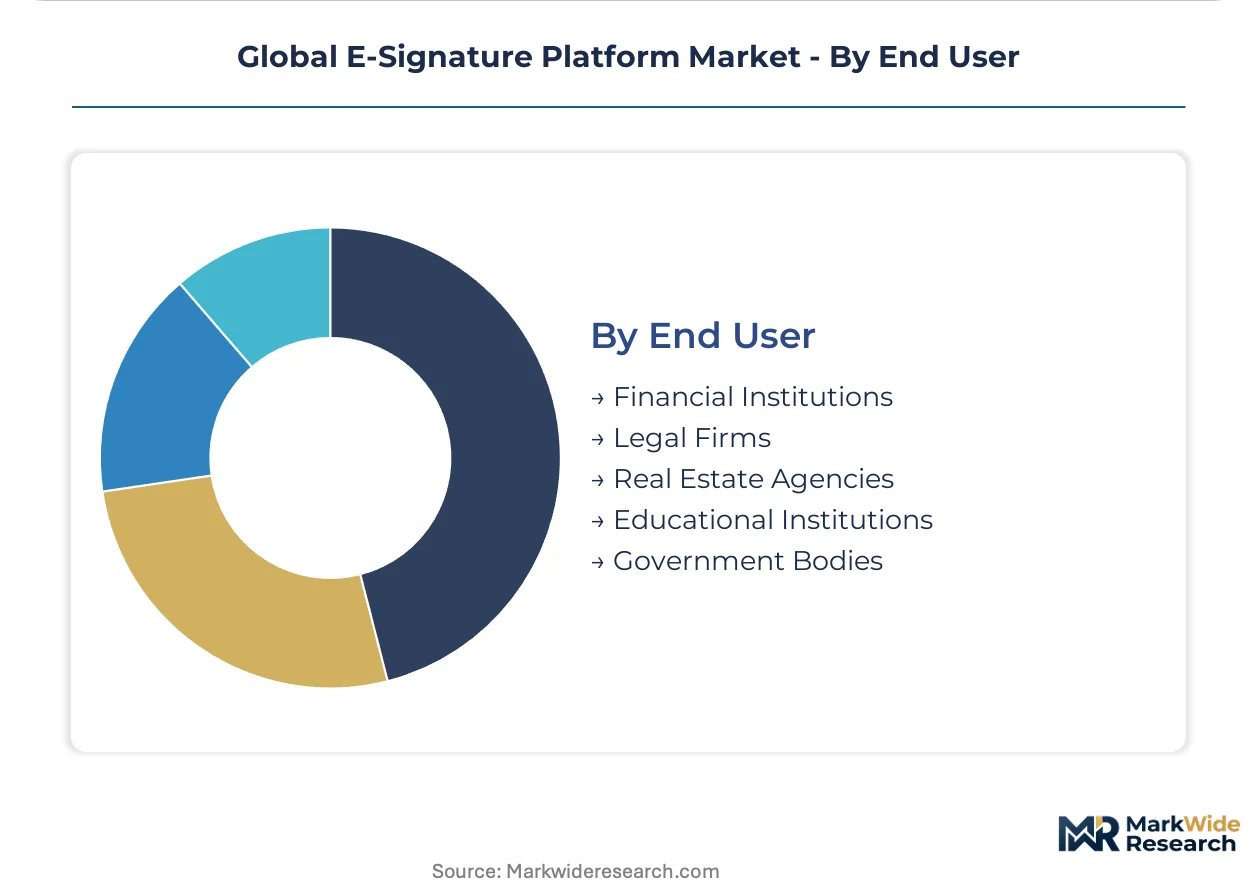
End-user concentration in regulated industries creates divergent certification requirements, with multi-jurisdiction compliance timelines extending 18-24 months for qualified trust service status.
- Financial Institutions:Commercial banks and insurance carriers require eIDAS qualified trust service provider status in Europe alongside SOC 2 Type II compliance in North America. RBI and SEBI guidelines in India are mandating audit-ready platforms for digital lending workflows.
- Government Bodies:Federal and state agencies demand on-premise or sovereign-cloud deployments with FISMA or equivalent security categorization. India's IT Act amendments are accelerating paperless approval chains in property transactions and public procurement.
- Legal Firms:Bar association ethics requirements for client file retention and privilege protection.
- Real Estate Agencies:Title company integration and escrow coordination for closing workflows.
- Educational Institutions:Transcript authentication and enrollment verification with registrar system integration.
Today's anchor: Financial Institutions. Tomorrow's expansion vector: Government Bodies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-signature infrastructure originated in the United States during the dot-com era, with Silicon Valley startups pioneering cloud-based contract execution before European and Asian markets developed indigenous capabilities.
United States
Commercial lending digitization and healthcare payer-provider contracting drive transaction volume. The ESIGN Act and state-level UETA frameworks provide uniform legal recognition for electronic records. New York and San Francisco host the densest concentration of financial services technology procurement teams.
Germany
Automotive supply chain digitization mandates from OEMs create pull-through demand for procurement automation. The eIDAS regulation establishes qualified trust service standards for cross-border recognition. Bavaria and Baden-Württemberg industrial clusters anchor Mittelstand adoption of paperless audit trails.
India
Digital lending expansion by NBFCs and scheduled commercial banks accelerates API-embedded signing workflows. The IT Act amendments enhance legal validity for property transactions and government procurement. Mumbai and Bangalore financial technology corridors concentrate platform deployment.
United Kingdom
Legal services digitization and real estate conveyancing automation sustain enterprise demand. The Electronic Communications Act maintains enforceability standards post-Brexit. London's insurance and capital markets clusters drive high-assurance identity verification requirements.
Japan
Corporate governance digitization and cross-border trade finance automation expand platform adoption. METI guidelines on electronic transactions shape compliance architecture. Tokyo and Osaka metropolitan areas concentrate financial institution procurement decisions.
Global E-Signature Platform Market Competitive Landscape
Capital-heavy certificate authority operators compete with asset-light software platforms for cryptographic trust chain dominance. Market structure tilts toward consolidation at the infrastructure layer while application-layer competition fragments across vertical specializations. Three archetypes emerge: cloud-native workflow orchestrators, hardware security module specialists, and trust service providers with qualified eIDAS status. Dominant competitive moves include strategic API partnership programs and vertical acquisition of identity verification capabilities.
Within the cloud-native tier, DocuSign Inc and Adobe Inc exemplify workflow automation scale. OneSpan Inc occupies a position among high-assurance identity verification specialists serving regulated banking infrastructure. These three anchors represent divergent strategic postures: horizontal platform breadth, document ecosystem integration, and vertical compliance depth.
| Leading Market Players |
|---|
| DocuSign Inc |
| Adobe Inc |
| OneSpan Inc |
| Zoho Corporation Pvt Ltd |
| Entrust Corporation |
| PandaDoc Inc |
| Thales |
| DigiCert |
| SignEasy Inc |
| Others |
Supply & Pricing Matrix
Enterprise procurement consolidation around bundled workflow automation is compressing standalone signature tool margins and forcing providers to absorb certificate authority costs into subscription tiers. This demand-side shift toward orchestration platforms restructures supplier economics, privileging vendors with captive trust service infrastructure over those licensing cryptographic modules from third parties.
Pricing Analysis
Subscription-based SaaS tiers anchored to user volume and compliance certification grade dominate commercial terms. Three-tier pricing structure across qualified trust service, advanced electronic signature, and basic electronic signature levels separates eIDAS-compliant deployments from ESIGN-aligned configurations. Cost compression in the mid-market intensifies as DocuSign and Adobe bundle signing into broader contract lifecycle suites. Small and mid-sized enterprises exhibit highest price sensitivity, while financial institutions in Germany and the United States prioritize audit-ready documentation over per-seat economics.
Supply Chain Analysis
eIDAS qualified trust service provider status and SOC 2 Type II certification function as dual gating mechanisms that filter vendor participation in regulated procurement channels. Certificate authority services cluster in the United States, Germany, and the Netherlands, with hardware security module manufacturing concentrated among semiconductor fabricators in Taiwan and South Korea. Single-source vulnerability in cryptographic chip supply creates continuity risk for on-premise deployments. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships in financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global E-Signature Platform Market compounds steadily as regulatory digitization mandates across the European Union, United States, and India institutionalize paperless contract execution as default operating procedure.
For Market Incumbents: To counter embedded insurtech workflow competition, DocuSign and Adobe should deepen API partnership density with loan origination system vendors while accelerating qualified trust service provider certification in India to preempt local challenger emergence. Backward integration into certificate authority operations would reduce cryptographic trust chain dependency. For New Entrants and Emerging Players: Begin with white-label deployment through German Mittelstand manufacturing procurement digitization mandates, where automotive OEM supplier requirements create pull-through demand without direct enterprise sales infrastructure. Blockchain-anchored audit trail modules for carbon credit verification represent adjacent whitespace with limited incumbent penetration. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical compliance specialists possessing parallel eIDAS and SOC 2 certification tracks already completed. Long-term viability hinges on workflow automation bundling rather than point-signature functionality. Monitor EU AI Act enforcement intensity against automated identity verification systems as inflection signal for human-in-the-loop capability premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Qualified Trust Service Certification | eIDAS compliance unlocks European banking infrastructure procurement and cross-border legal recognition. |
| API-First Integration Architecture | Native connectivity with Salesforce and SAP ecosystems captures enterprise workflow automation spend. |
| Biometric Liveness Detection Acquisition | Voiceprint and facial geometry capabilities satisfy EU AI Act high-risk system requirements for investment banks. |
| Blockchain Timestamp Anchoring | Immutable audit trails penetrate commodities trading and carbon credit verification use cases. |
| Sovereign Cloud Deployment | India IT Act compliance for state-level property transaction digitization creates public sector revenue. |
Research Methodology
Multiple input streams — primary interviews with trust service provider executives, bank procurement officers, and regulatory compliance leads; secondary synthesis of eIDAS supervisory body audit reports, SEC 10-K infrastructure disclosures, and RBI digital lending guidelines; plus customs data on hardware security module trade flows — were reconciled through bottom-up transaction volume modeling and top-down market sizing validation.
Historical growth trajectories were cross-referenced against expert panel assessments of EU AI Act implementation pacing and India's IT Act amendment enforcement intensity. Segmentation modeling incorporated deployment architecture, solution bundling configuration, end-user industry vertical, and regional regulatory framework cluster across the projection horizon. CAGR derivation rested on elasticity estimates for contract execution digitization in commercial lending and procurement automation penetration in German automotive supply chains.
Several conditions sit outside the modeled scope, including potential eIDAS regulatory revision, reciprocal recognition treaty negotiations between the United States and civil law jurisdictions, and quantum computing timeline disruption of RSA cryptographic standards. A model refresh is warranted upon material change in EU AI Act high-risk system classification enforcement or India's state-level procurement digitization acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Interactive Projector Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Europe API Management Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Molecular Information Systems Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
Platform Architecture Market