
 Interactive Kiosk Market | 2026-2036
Interactive Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Kiosk Market Intelligence
The capital-intensity divergence between full-system integrators and component assemblers is unwinding competitive tiers across the interactive kiosk landscape. NCR Voyix Corporation leverages its banking heritage to dominate payment-integrated kiosk architectures in retail and hospitality. Diebold Nixdorf sustains manufacturing scale through captive ATM production lines that feed self-service terminal platforms. Zebra Technologies Corp. anchors enterprise mobility expertise into ruggedized kiosk enclosures for warehouse and logistics endpoints.
An interactive kiosk is a freestanding computerized terminal combining touchscreen displays, embedded processors, and peripheral modules—card readers, printers, barcode scanners—to execute self-directed transactions or information retrieval without human assistance. These systems typically operate on Intel or ARM-based computing cores with projected capacitive touch layers rated for millions of actuations, serving commercial purposes from reducing labor costs to capturing behavioral analytics at physical service points. Self-service kiosks lead product-type revenue as quick-service restaurants and grocery chains replace staffed lanes with order-and-pay terminals. Payment kiosks represent the fastest-expanding segment, driven by cashless transit systems and utility bill settlement platforms in municipal deployments. Indoor deployment configurations retain the dominant share, though outdoor specifications are gaining traction as municipalities install weather-hardened information terminals in public squares and transit hubs.
The FCC governs electromagnetic emissions and wireless connectivity certifications for kiosk terminals deployed across the United States, while the EU AI Act imposes algorithmic transparency requirements on facial recognition-enabled units sold into European public spaces. ETSI standards for NFC contactless interoperability shape payment kiosk design parameters for cross-border acceptance. Stakeholders must monitor evolving biometric privacy legislation in multiple jurisdictions, as facial recognition kiosks face mounting compliance burdens that could redirect R&D investment toward voice and gesture alternatives.
Market Dynamics
The interactive kiosk market is undergoing structural compression as self-service checkout hardware refresh cycles in North American grocery chains accelerate replacement demand while tightening touchscreen durability specifications from IEC reshape component sourcing for outdoor municipal deployments.
Growth Catalysts
- Transit cashless mandates:Municipal transportation authorities across the United States are deploying payment-integrated terminals to eliminate cash handling, driving terminal volume in subway stations and bus depots.
- Quick-service restaurant lane conversion:Burger chains and coffee retailers are replacing staffed order points with customer-operated terminals, compressing labor cost structures at high-traffic locations.
- EU AI Act transparency requirements:Algorithmic disclosure rules for facial recognition-enabled units are redirecting vendor R&D investment toward alternative biometric modalities, expanding addressable use cases.
Market Restraints
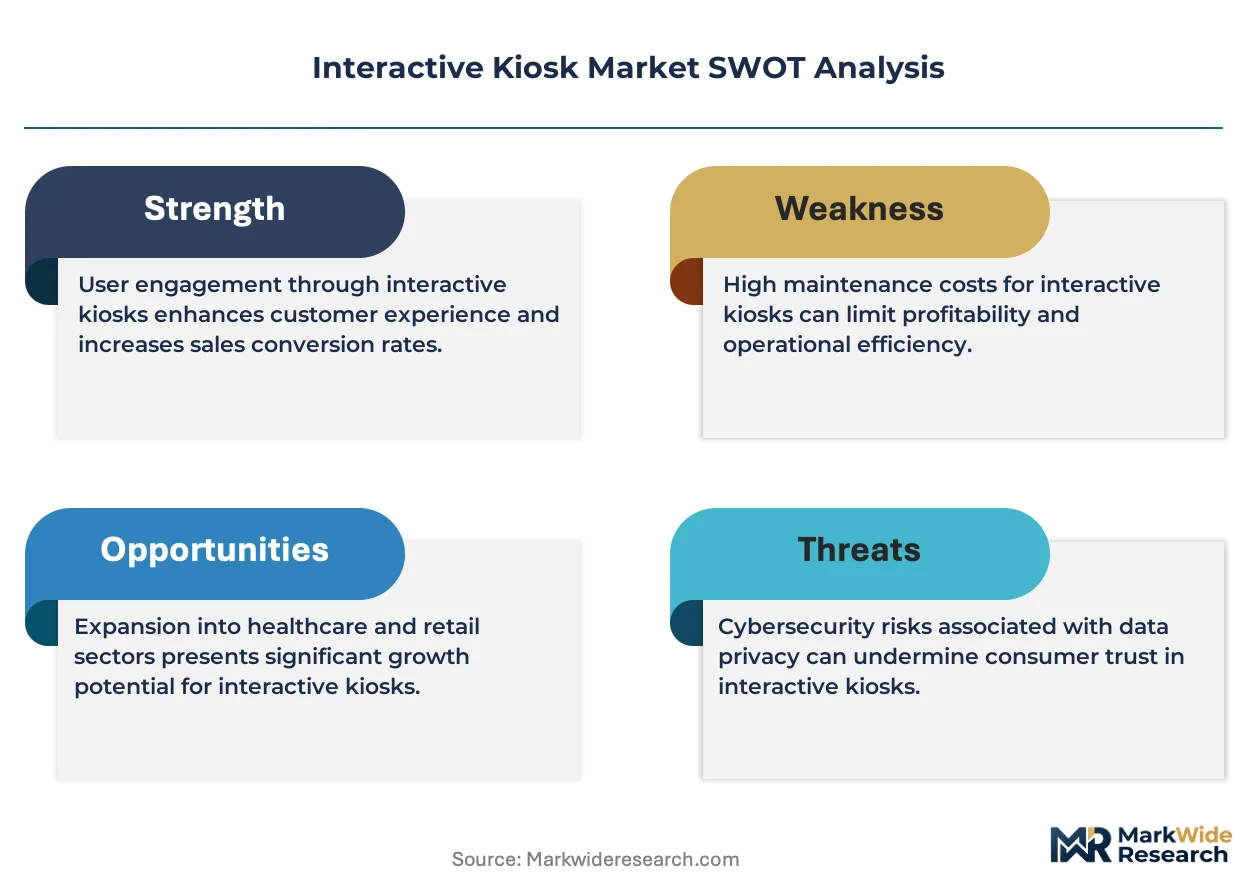
- Projected capacitive touch layer supply concentration:Specialty glass and sensor controller production clusters in East Asia create input bottlenecks during demand surges.
- Outdoor enclosure cost inflation:Weather-hardened IP65-rated housings require marine-grade aluminum and conformal coating processes that inflate unit economics versus indoor configurations.
- Biometric privacy litigation exposure:Illinois BIPA and similar state-level statutes in the United States impose statutory damages frameworks that elevate liability risk for facial recognition deployments.
Strategic Opportunities
- Voice and gesture modality convergence:Touchless input technologies are opening deployment pathways in healthcare and foodservice environments where surface contact presents contamination concerns.
- India municipal digitization:Smart city initiatives under the Ministry of Housing and Urban Affairs are funding information terminal networks in transit hubs and public squares.
- Utility bill settlement platforms:Cashless payment kiosks for electricity and water authorities represent underpenetrated endpoints in Latin American and Southeast Asian urban centers.
Industry Challenges
- Embedded systems firmware integration:Peripheral module interoperability between card readers, printers, and barcode scanners demands specialized engineering talent scarce outside established integrators.
- IEC 60950-1 to IEC 62368-1 transition:Safety certification retesting timelines for existing product lines compress launch windows and strain compliance department bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Kiosk Market |
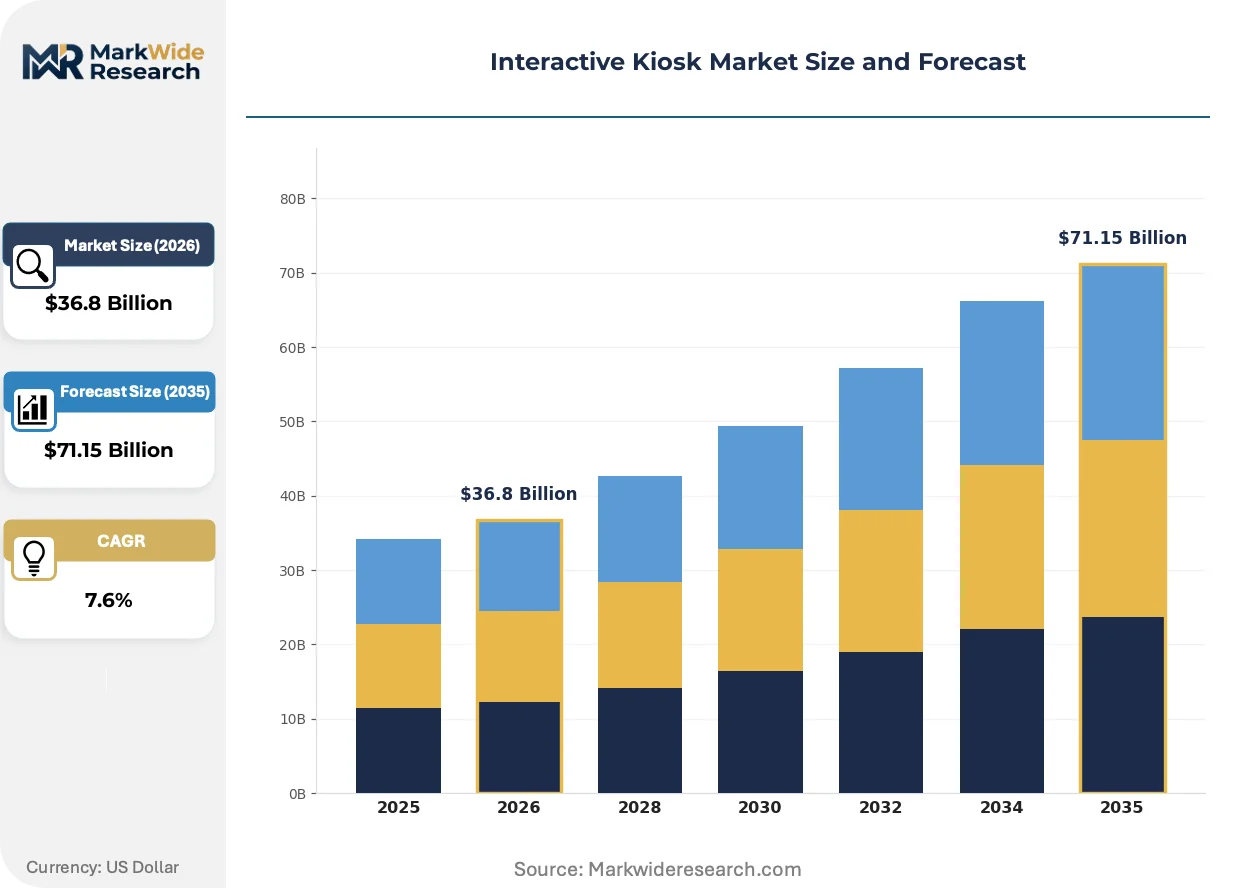
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $71.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Service Kiosks, Information Kiosks, Ticketing Kiosks, Payment Kiosks Industry Vertical: Retail, Healthcare, Hospitality, Transportation Deployment: Indoor, Outdoor, Mobile, Fixed Technology: Touchscreen, Voice Recognition, Facial Recognition, NFC |
| Companies Covered | Advantech Co., Ltd., KIOSK Information Systems, NCR Voyix Corporation, Olea Kiosks Inc., Meridian Kiosks, Diebold Nixdorf, Glory Ltd., Embross, Zebra Technologies Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Kiosk Market Strategic Shifts & Innovations
Hardware architecture decisions in interactive kiosk design are pivoting toward processing decentralization and biometric modality diversification, with vendors repositioning around edge computing capabilities and contactless input standards.
System-on-module architectures based on ARM computing cores are supplanting legacy Intel x86 configurations in entry-level and mid-tier terminals. Quick-service restaurant chains and budget grocery operators are adopting these lower-power platforms to reduce thermal management costs and extend deployment lifecycles. The shift is compressing margin structures for traditional industrial PC suppliers while opening design wins for semiconductor vendors with integrated peripheral controller portfolios.
The EU AI Act's algorithmic transparency mandates are forcing facial recognition-enabled kiosk vendors to document training data provenance and decision logic for European public space deployments. Manufacturers are responding by segmenting product lines: disclosure-compliant units for EU markets and unrestricted configurations for jurisdictions without equivalent statutes. This regulatory fragmentation is elevating SKU complexity and regional inventory management costs.
Airport terminal operators are unbundling hardware acquisition from software maintenance and field service contracts, shifting toward separate procurement streams for capital equipment and operational support. This disintermediation is compressing integrator margins on initial sales while creating recurring revenue contests among service specialists. The pattern is most visible in United States hub airports where consolidated terminal management authorities wield concentrated purchasing leverage.
Interactive Kiosk Market Segmentation
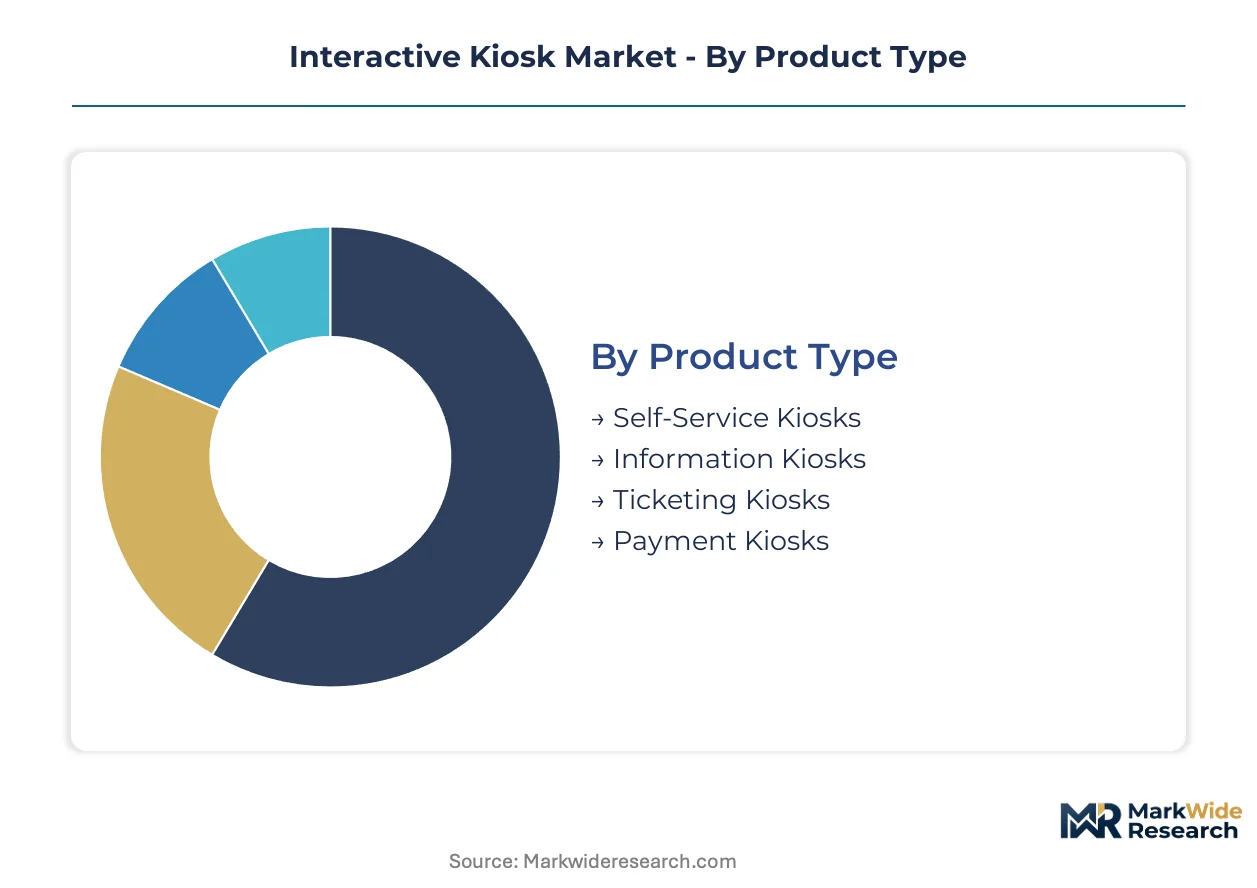
Segmentation in the interactive kiosk market reveals how hardware specifications, environmental ratings, and biometric capabilities fragment procurement decisions across end-users. Understanding these divides exposes where component suppliers and system integrators capture differentiated margin pools.
Product Type:
Margin concentration sits with terminals that integrate payment infrastructure and peripheral modules, where certification complexity creates barriers for pure hardware assemblers.
- Self-Service Kiosks:These units combine projected capacitive touch layers with embedded processors and peripheral controllers for order-and-pay workflows. Demand concentrates in United States quick-service restaurant chains and grocery self-checkout lanes, where labor cost compression drives replacement cycles.
- Payment Kiosks:Terminals integrating card readers, NFC controllers, and cash handling modules for transit and utility settlement. Municipal transportation authorities in the United States are deploying these for cashless fare collection, while Latin American utility operators represent underpenetrated endpoints.
- Information Kiosks:Wayfinding and directory terminals with lower peripheral integration.
- Ticketing Kiosks:Purpose-built units for entertainment venue and transit fare issuance.
The dominant share belongs to Self-Service Kiosks, while Payment Kiosks are climbing the fastest as transit authorities eliminate cash handling.
Industry Vertical:
Application requirements diverge sharply between consumer-facing throughput environments and regulated settings where compliance documentation elevates procurement scrutiny.
- Retail:Self-checkout and order-ahead terminals dominate unit volume. United States grocery chains and big-box operators are accelerating hardware refresh cycles, while IEC touchscreen durability standards tighten component specifications for high-actuation deployments.
- Transportation:Fare collection and wayfinding terminals in airport terminals and transit hubs. United States hub airports are unbundling hardware acquisition from service contracts, compressing integrator margins on initial sales.
- Hospitality:Check-in and concierge terminals for hotels and quick-service restaurants.
- Healthcare:Patient check-in and wayfinding units where surface contact concerns are redirecting procurement toward touchless modalities.
Retail commands the largest installed base, though Transportation is gaining share fastest as municipal digitization funds expand terminal networks.
Deployment:
Environmental protection ratings and mounting configurations split the market between cost-optimized indoor specifications and weather-hardened platforms with inflated unit economics.
- Indoor:Standard IP20-IP54 rated terminals for climate-controlled environments. These configurations retain the dominant deployment share due to lower enclosure costs and simplified thermal management.
- Outdoor:IP65-rated housings with marine-grade aluminum and conformal coating for public squares and transit hubs. IEC standards for touchscreen durability are reshaping component sourcing as municipalities install weather-hardened information terminals.
- Mobile:Battery-powered or cart-mounted units for temporary deployment.
- Fixed:Permanently anchored installations with hardwired power and connectivity.
Indoor deployments hold the majority position, while Outdoor specifications are expanding most quickly as smart city initiatives fund public terminal networks.
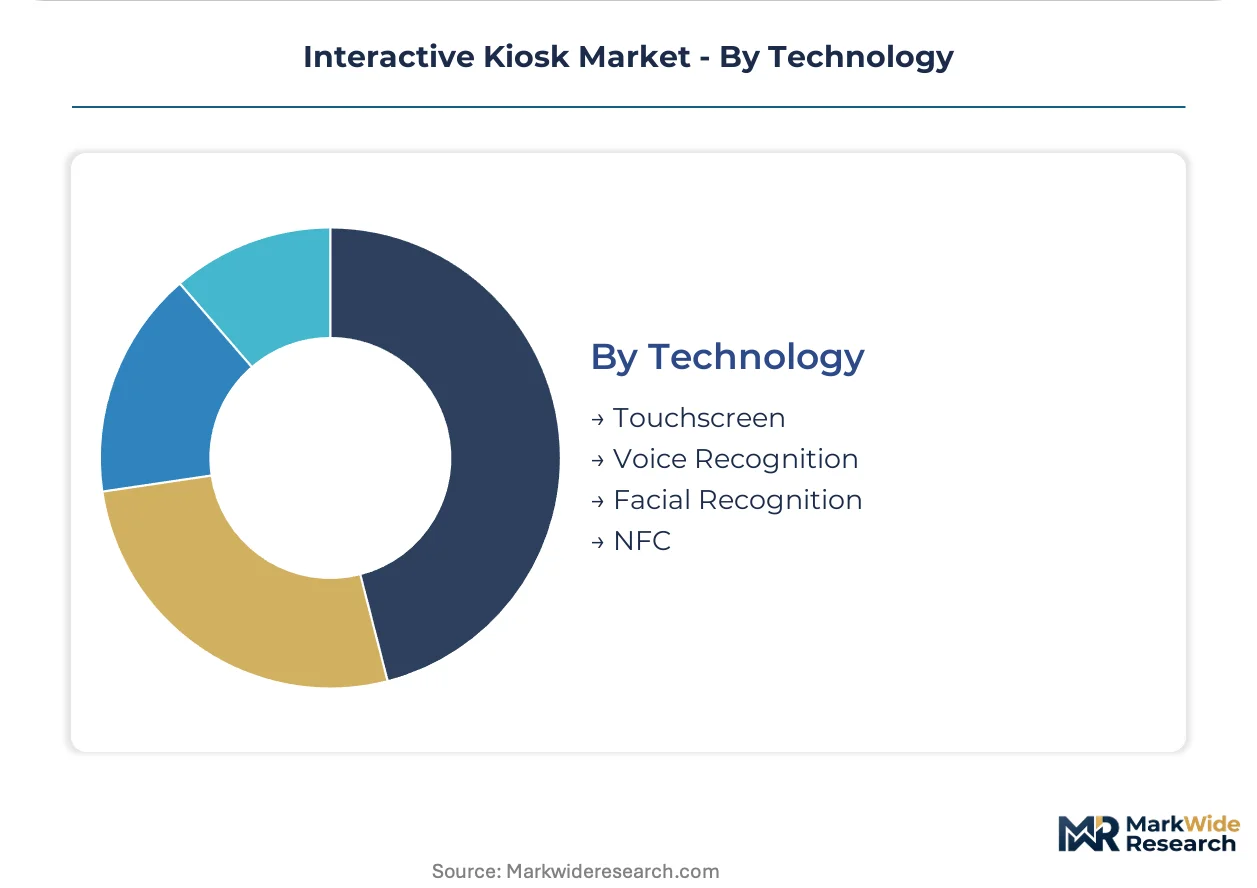
Technology:
Input modality selection increasingly reflects regulatory pressure on biometric systems and contamination concerns in healthcare and foodservice settings.
- Touchscreen:Projected capacitive layers rated for millions of actuations, operating on Intel or ARM computing cores. This remains the default interface across retail and hospitality endpoints.
- Facial Recognition:Camera-enabled biometric authentication for security and payment verification. The EU AI Act's algorithmic transparency mandates are forcing vendors to document training data provenance for European deployments, elevating SKU complexity.
- Voice Recognition:Microphone arrays with natural language processing for hands-free interaction.
- NFC:Contactless payment and access control modules governed by ETSI interoperability standards for cross-border acceptance.
Touchscreen retains the dominant technology position, while Voice Recognition is gaining traction fastest as healthcare operators seek contactless alternatives to surface-based input.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States airport terminals and quick-service restaurant chains, while procurement leverage dissipates in fragmented municipal deployments across emerging markets. Hardware refresh cycles accelerate in North American grocery chains. Regulatory fragmentation intensifies as the EU AI Act and Illinois BIPA reshape biometric-enabled terminal specifications.
United States
Transit cashless mandates drive terminal volume in subway stations and bus depots across metropolitan transportation authorities. The FCC governs electromagnetic emissions and wireless connectivity certifications for kiosk terminals deployed nationwide. Chicago O'Hare and Atlanta Hartsfield-Jackson anchor airport terminal procurement where consolidated management authorities unbundle hardware acquisition from service contracts.
Germany
Industrial automation demand from manufacturing logistics endpoints sustains ruggedized kiosk deployment in warehouse environments. The EU AI Act imposes algorithmic transparency requirements on facial recognition-enabled units sold into European public spaces. Bavaria's automotive supplier clusters incorporate self-service terminals for inventory management and worker check-in workflows.
China
Smart city municipal digitization funds expand outdoor information terminal networks in public squares and transit hubs. GB standards and MIIT regulations shape computing core and touchscreen interoperability specifications for domestic deployments. Shenzhen's electronics manufacturing corridor concentrates projected capacitive touch layer and sensor controller production capacity.
India
Ministry of Housing and Urban Affairs smart city initiatives fund information terminal networks in transit hubs and public squares across tier-1 and tier-2 urban centers. BIS certification requirements tighten component specifications for payment-integrated deployments. Maharashtra's Mumbai-Pune corridor concentrates system integrator activity for railway station and municipal utility kiosk rollouts.
Japan
Aging demographic pressures accelerate self-service terminal deployment in convenience retail and banking to offset labor availability constraints. METI efficiency standards and JIS certification frameworks shape enclosure durability and energy consumption specifications. Tokyo's metropolitan rail network maintains concentrated demand for cashless transit fare collection terminals.
Interactive Kiosk Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the interactive kiosk landscape. Full-system integrators with captive payment infrastructure dominate premium-tier deployments where certification complexity creates barriers to entry. Component assemblers compete on unit economics for standardized indoor configurations. Strategic moves concentrate on vertical integration into touch layer supply and geographic expansion through municipal smart city contracts.
Within the integrated-system tier, NCR Voyix Corporation and Diebold Nixdorf occupy positions shaped by banking and ATM heritage that feeds self-service terminal platforms. Zebra Technologies Corp. anchors enterprise mobility expertise into ruggedized enclosures for warehouse and logistics endpoints. These three exemplify how specialized heritage determines competitive positioning across retail, financial services, and industrial verticals.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| KIOSK Information Systems |
| NCR Voyix Corporation |
| Olea Kiosks Inc. |
| Meridian Kiosks |
| Diebold Nixdorf |
| Glory Ltd. |
| Embross |
| Zebra Technologies Corp. |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with projected capacitive touch layer manufacturers lock in supply access and price visibility for kiosk integrators serving United States quick-service restaurant chains and airport terminal operators. These arrangements insulate procurement teams from spot-market volatility in East Asian sensor controller supply while compressing margin flexibility for smaller assemblers unable to commit to volume thresholds.
Pricing Analysis
The customization-premium spread between configured-to-order payment-integrated terminals and standard information kiosks runs wide, with certification complexity for FCC emissions and PCI-DSS compliance driving tiered pricing stratification across premium, standard, and economy levels. Price differentiation hinges on peripheral module integration density and IEC 62368-1 safety certification tier, with outdoor IP65-rated configurations commanding substantial premiums over indoor IP54 specifications. Pricing pressure stems from grocery chain hardware refresh cycles accelerating replacement demand and squeezing integrator margins on volume deployments. Quick-service restaurant chains exhibit highest price sensitivity due to standardized terminal specifications, while airport authorities with unbundled procurement models show lowest sensitivity given operational support contracts.
Supply Chain Analysis
Inbound logistics costs through the Shenzhen-Hong Kong-Long Beach trade lane shape landed cost structures for projected capacitive touch layers and ARM-based system-on-module computing cores. Supply concentrates in China for touchscreen sensor controllers and glass substrates, Taiwan for semiconductor foundry capacity, and South Korea for display panel components. Raw material dependencies include marine-grade aluminum for outdoor enclosures, conformal coating chemicals for weatherproofing, and specialty glass for high-actuation touch layers. Single-source vulnerability in East Asian touch layer production clusters elevates disruption risk during demand surges. Distribution runs through direct OEM relationships for tier-one integrators and regional distributor networks for mid-tier assemblers serving municipal and retail endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The interactive kiosk market sits at an inflection where EU AI Act biometric transparency mandates and transit cashless mandates are simultaneously redirecting R&D investment and accelerating terminal deployment velocity.
For Market Incumbents: Secure captive supply agreements for projected capacitive touch layers and sensor controllers to defend against East Asian input bottlenecks during demand surges. Invest in IEC 62368-1 safety certification retesting capabilities to compress launch windows and maintain compliance department bandwidth. Build voice and gesture modality portfolios to preempt regulatory fragmentation in facial recognition-enabled deployments across European public spaces.
For New Entrants and Emerging Players: Anchor in Latin American utility bill settlement platforms and Indian smart city municipal digitization initiatives where incumbent presence remains thin. Target healthcare patient check-in workflows where surface contact concerns are redirecting procurement toward touchless input technologies. Pursue white-label manufacturing partnerships with established enclosure suppliers to bypass capital-intensive IP65-rated housing production.
For Investors and Strategic Acquirers: Capital is best deployed toward system integrators with vertical integration into payment infrastructure and captive field service networks that capture recurring revenue from unbundled procurement models. Long-term viability favors vendors with demonstrated compliance navigation across FCC, EU AI Act, and Illinois BIPA regulatory frameworks. Watch for inflection signals in voice recognition accuracy benchmarks and NFC contactless interoperability certification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Touchless Modality Development | Voice and gesture input capabilities open healthcare and foodservice deployment pathways where surface contact presents contamination concerns. |
| Payment Infrastructure Integration | PCI-DSS certified card reader and NFC module integration captures municipal transit cashless mandate volume in United States subway stations. |
| Outdoor Enclosure Certification | IP65-rated marine-grade aluminum housings with conformal coating access smart city information terminal networks in public squares. |
| Regulatory Compliance Segmentation | EU AI Act disclosure-compliant product lines for European markets preserve facial recognition revenue while unrestricted configurations serve other jurisdictions. |
| Service Contract Unbundling | Separate hardware acquisition and operational support procurement streams capture recurring revenue from United States hub airport terminal operators. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with kiosk system integrators, quick-service restaurant procurement directors, airport terminal management authorities, municipal transportation planners, and component suppliers; and secondary validation through FCC equipment authorization databases, ETSI NFC interoperability specifications, IEC safety standard documentation, and SEC filings from publicly traded terminal manufacturers. Bottom-up triangulation across unit deployment estimates by vertical and geography intersected with top-down market sizing through hardware bill-of-materials analysis and integrator revenue disclosures.
The projection horizon spans the full forecast window with CAGRs derived from segment-level growth rate modeling across product type, industry vertical, deployment configuration, and technology modality dimensions. Forecast inputs incorporated hardware refresh cycle timing from North American grocery chains, transit cashless mandate implementation schedules from United States metropolitan authorities, and regulatory compliance cost trajectories from EU AI Act and Illinois BIPA enforcement patterns. Segmentation modeling captured self-service versus payment versus information kiosk specifications, indoor versus outdoor environmental ratings, and touchscreen versus voice versus facial recognition input technologies.
Material uncertainties — tariff exposure on East Asian touch layer imports, biometric privacy litigation outcomes under state-level statutes, and transit authority budget allocation shifts — sit outside the modeled envelope. Forecasts reflect assumptions about IEC standard adoption timelines and peripheral module interoperability convergence. Recalibration cycles align with material shifts in municipal digitization funding, quick-service restaurant labor cost structures, and regulatory enforcement intensity across jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
System Integrator Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
Construction Design App Market
Digital Solutions
Load Balancer Market
Digital Solutions
Product Prototyping Market
Digital Solutions
IT Asset Management Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Bangladesh ICT Market