
 Hybrid Events Software Market | 2026-2036
Hybrid Events Software Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Events Software Market Insights
Buyer concentration among Fortune 500 technology and pharmaceutical sectors is pivoting toward unified event technology stacks that collapse registration, streaming, and analytics into single vendor relationships. Cvent leverages its deep integration with hotel chain distribution systems to sustain enterprise renewals. Hopin competes through rapid feature iteration in networking tools. Bizzabo differentiates via native revenue attribution capabilities that connect event participation to CRM pipeline outcomes.
Hybrid events software orchestrates simultaneous physical and digital audience experiences through real-time video ingestion, multi-CDN failover architecture, and bi-directional engagement telemetry with sub-200ms latency targets. Its primary commercial purpose centers on preserving sponsorship yield and attendee monetization when physical capacity constraints or geographic dispersion limit in-person participation. Cloud-based deployment captures the dominant margin pool as hyperscale infrastructure amortization drives unit economics below on-premises alternatives. Event management software as a discrete category faces compression as platform vendors bundle scheduling, speaker management, and exhibitor portals into core offerings.
FCC guidelines on closed captioning and accessibility for live-streamed content shape product roadmaps for US-facing platforms, while GDPR and the EU AI Act impose consent-layer requirements on facial recognition and sentiment analysis features deployed at European venues. EventMobi navigates this complexity through regional data residency options. Stakeholders must monitor how NIS2 cybersecurity directives in Europe and emerging state-level biometric privacy laws in Illinois and Texas will force architectural segmentation of global platform instances.
Market Dynamics
Enterprise procurement teams are consolidating around integrated event technology platforms that collapse registration, streaming, and analytics into single vendor relationships, compressing point-solution margins and reshaping competitive positioning.
Growth Catalysts
- EU AI Act compliance layers:European venues now mandate consent frameworks for facial recognition and sentiment analysis, accelerating platform refresh cycles among organizers serving GDPR jurisdictions.
- Industrial trade show digitization:German manufacturing event organizers are replacing legacy infrastructure with cloud-native hybrid stacks to preserve sponsorship yield under physical capacity constraints.
- Multi-CDN failover architecture:Real-time video ingestion with sub-200ms latency targets is overtaking single-point streaming solutions as the technical baseline for enterprise RFPs.
Market Restraints
- Hyperscale infrastructure lock-in:Cloud-based deployment economics depend on AWS, Azure, or Google Cloud amortization, creating supplier concentration risk for margin-sensitive mid-market vendors.
- Biometric privacy fragmentation:Illinois BIPA and emerging Texas state laws force architectural segmentation of global platform instances, raising engineering overhead for US-EU dual deployments.
- On-premises residual demand:Data sovereignty mandates in regulated industries sustain captive demand for self-hosted alternatives, limiting cloud-native total addressable market expansion.
Strategic Opportunities
- Revenue attribution convergence:Native CRM pipeline connectivity that links event participation to closed-won deals is creating differentiation white space against generic streaming providers.
- NIS2 cybersecurity segmentation:European directive implementation is forcing platform vendors to offer regional data residency options, favoring compliant challengers over non-adapted incumbents.
- Hotel chain distribution integration:Deep connectivity with accommodation booking systems remains underexploited outside North American enterprise accounts, opening channel expansion in Asia-Pacific corporate travel corridors.
Industry Challenges
- Real-time engineering talent scarcity:Sub-200ms latency engineering for bi-directional engagement telemetry requires specialized video infrastructure expertise concentrated in streaming-native labor markets.
- Accessibility compliance velocity:FCC closed captioning guidelines for live-streamed content demand continuous product roadmap investment without corresponding pricing power recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Events Software Market |
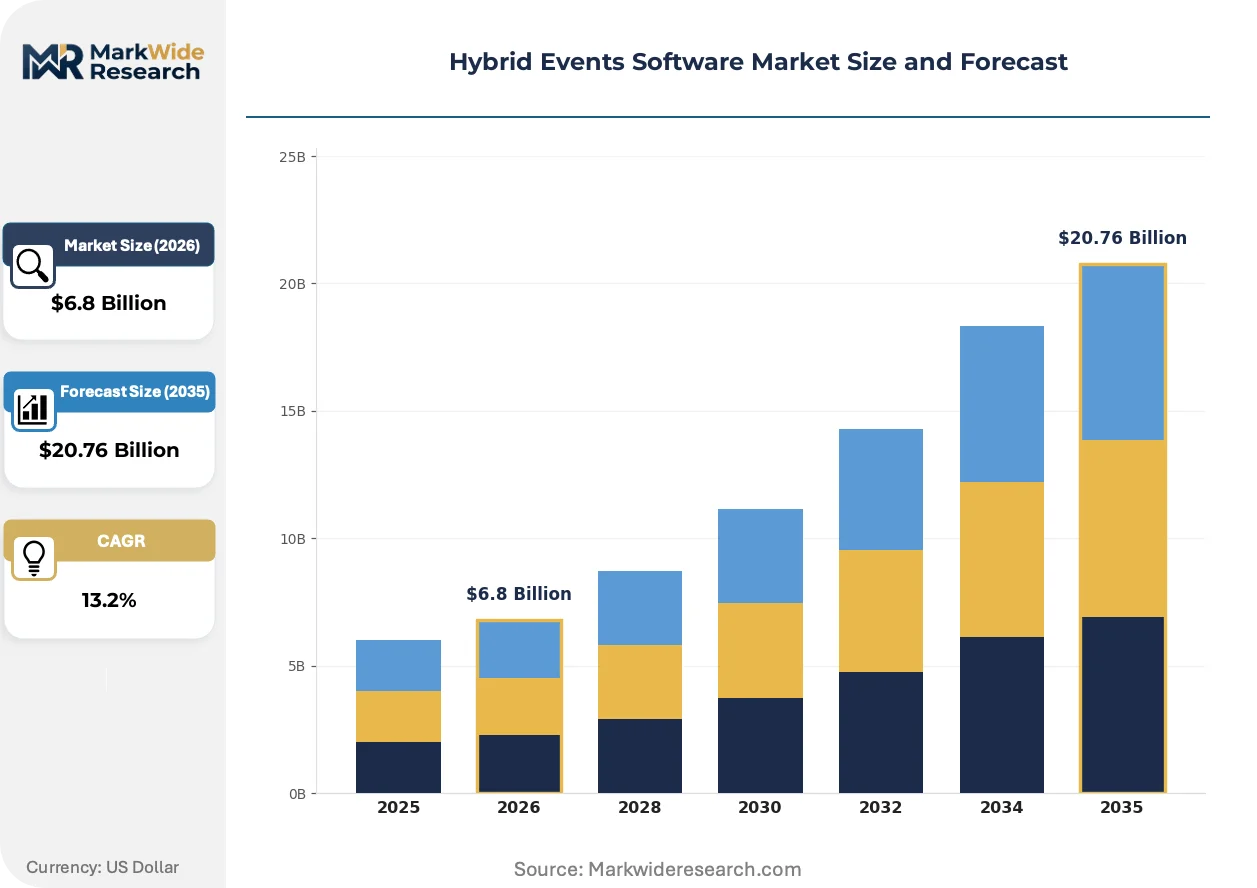
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Webinar Platforms, Virtual Event Platforms, Hybrid Event Solutions, Event Management Software Deployment: Cloud-Based, On-Premises, SaaS, Managed Services End User: Corporates, Educational Institutions, Event Organizers, Non-Profits Feature: Networking Tools, Analytics Dashboard, Ticketing System, Engagement Features |
| Companies Covered | Cvent, Stova, Hopin, Bizzabo, Eventbrite, EventMobi, b2match, Zoom Video Communications, RingCentral, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Events Software Market Trends and Innovations
Platform vendors are racing to embed AI-enhanced engagement analytics while navigating divergent regulatory frameworks across Atlantic and Pacific jurisdictions.
Edge-computing video processing is overtaking centralized cloud transcoding for real-time audience interaction features. Fortune 500 pharmaceutical and technology sectors are piloting these architectures for Q&A latency reduction in high-value investor events. The shift is compressing infrastructure costs for organizers running concurrent physical-digital experiences at industrial scale.
GDPR and the EU AI Act are imposing explicit consent-layer requirements on facial recognition and sentiment analysis features deployed at European venues. Event organizers in Germany and France must now document algorithmic decision-making transparency for attendee emotion tracking. Vendors without regional data residency options are losing RFP eligibility in public-sector procurement.
Buyer concentration among enterprise IT procurement teams is collapsing separate event management software categories into unified technology stacks. Scheduling, speaker management, and exhibitor portals are bundling into core platform offerings, displacing standalone point solutions. This consolidation is most visible in North American technology and pharmaceutical verticals where vendor relationship rationalization is accelerating.
Hybrid Events Software Market Segmentation
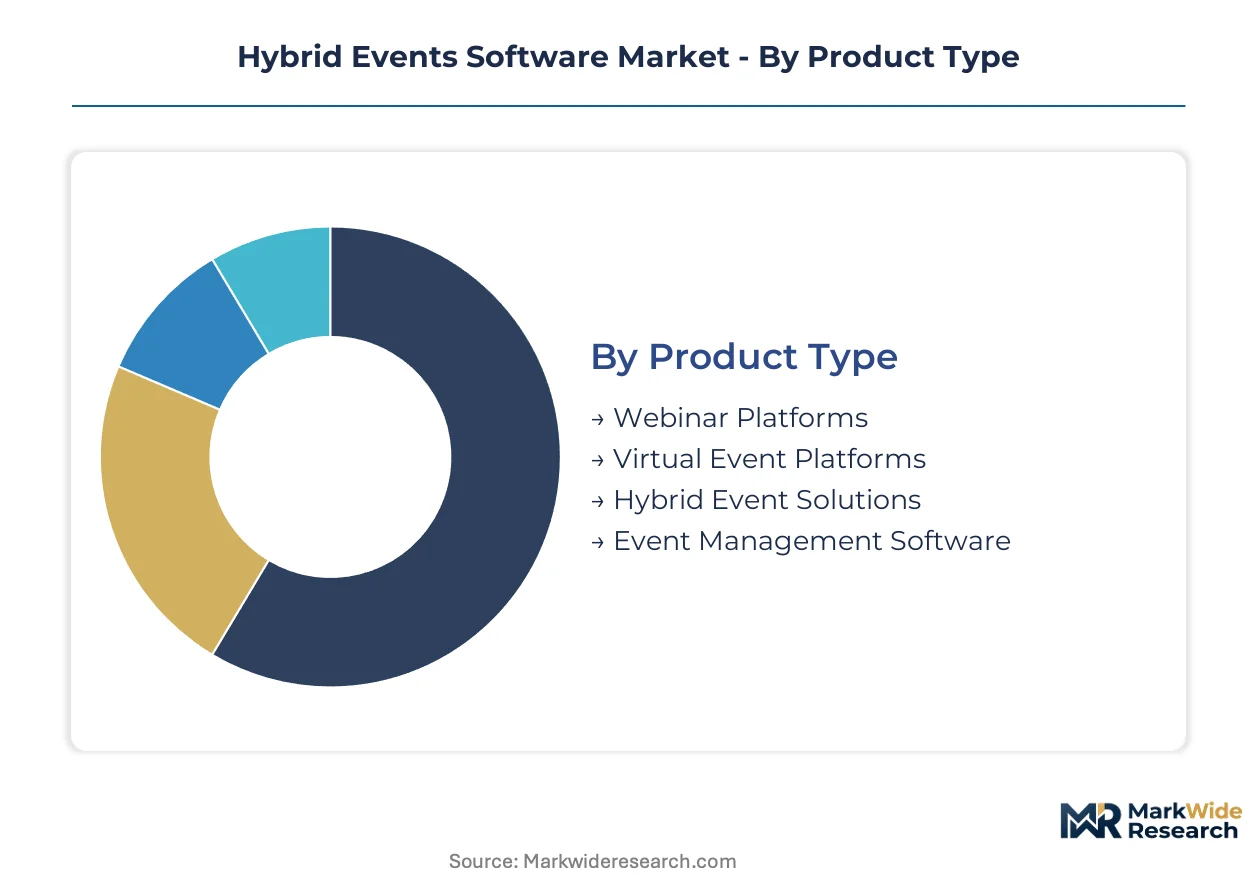
Segmentation in hybrid events software reveals how procurement teams prioritize technical capabilities against deployment constraints. Product architecture and feature depth determine vendor selection criteria across enterprise, mid-market, and institutional buyer tiers.
Product Type:
Volume deployment concentrates in webinar and virtual event platforms, while premium pricing attaches to integrated hybrid solutions that collapse multiple workflows into unified stacks.
- Hybrid Event Solutions:Orchestrate simultaneous physical and digital audience experiences through real-time video ingestion, multi-CDN failover architecture, and bi-directional engagement telemetry with sub-200ms latency targets. Demand concentrates among Fortune 500 technology and pharmaceutical sectors in Germany and the United States, driven by sponsorship yield preservation under physical capacity constraints.
- Virtual Event Platforms:Deliver browser-based immersive environments with spatial audio, 3D exhibition halls, and AI-powered matchmaking algorithms. Educational institutions in France and corporate training divisions in India represent the fastest-expanding customer base, pressured by geographic dispersion of student and employee populations.
- Webinar Platforms:Single-presenter or panel broadcast tools with limited interactivity.
- Event Management Software:Scheduling, speaker coordination, and exhibitor portal modules facing category compression as platform vendors bundle functionality.
Mature deployment sits with Webinar Platforms. Newer deployment is concentrated in Hybrid Event Solutions.
Deployment:
Cloud-native architectures capture margin advantages through hyperscale infrastructure amortization, while residual on-premises demand persists in regulated industries with data sovereignty mandates.
- Cloud-Based:Multi-tenant SaaS architectures leveraging AWS, Azure, or Google Cloud for elastic compute and storage scaling. European enterprise procurement teams in Germany and France are accelerating refresh cycles to meet EU AI Act compliance layers for facial recognition and sentiment analysis features.
- SaaS:Subscription-licensed software with continuous feature delivery and API extensibility. Mid-market event organizers in the United Kingdom and Netherlands favor this model for predictable operational expenditure and rapid deployment timelines.
- On-Premises:Self-hosted infrastructure for regulated sectors with captive data residency requirements.
- Managed Services:White-glove implementation and live event operations support for complex productions.
Cloud-Based deployment represents the fastest-growing trajectory. On-Premises installations are contracting outside public-sector and defense-adjacent verticals.
End User:
Corporate buyers drive premium pricing through unified technology stack consolidation, while educational and non-profit segments prioritize cost-optimized feature subsets.
- Corporates:Enterprise IT procurement teams consolidating vendor relationships around integrated platforms that collapse registration, streaming, and analytics into single contracts. Technology and pharmaceutical verticals in the United States and Germany are displacing point solutions with unified event technology stacks.
- Event Organizers:Third-party agencies managing industrial trade shows and association conferences. German manufacturing event organizers are digitizing legacy infrastructure at scale to preserve sponsorship yield under physical capacity constraints.
- Educational Institutions:Universities and business schools deploying virtual commencement and alumni engagement programs.
- Non-Profits:Fundraising gala and donor stewardship applications with constrained technology budgets.
Corporate procurement commands the steepest pricing tiers. Educational adoption is expanding most quickly as institutions permanentize hybrid instructional models.
Feature:
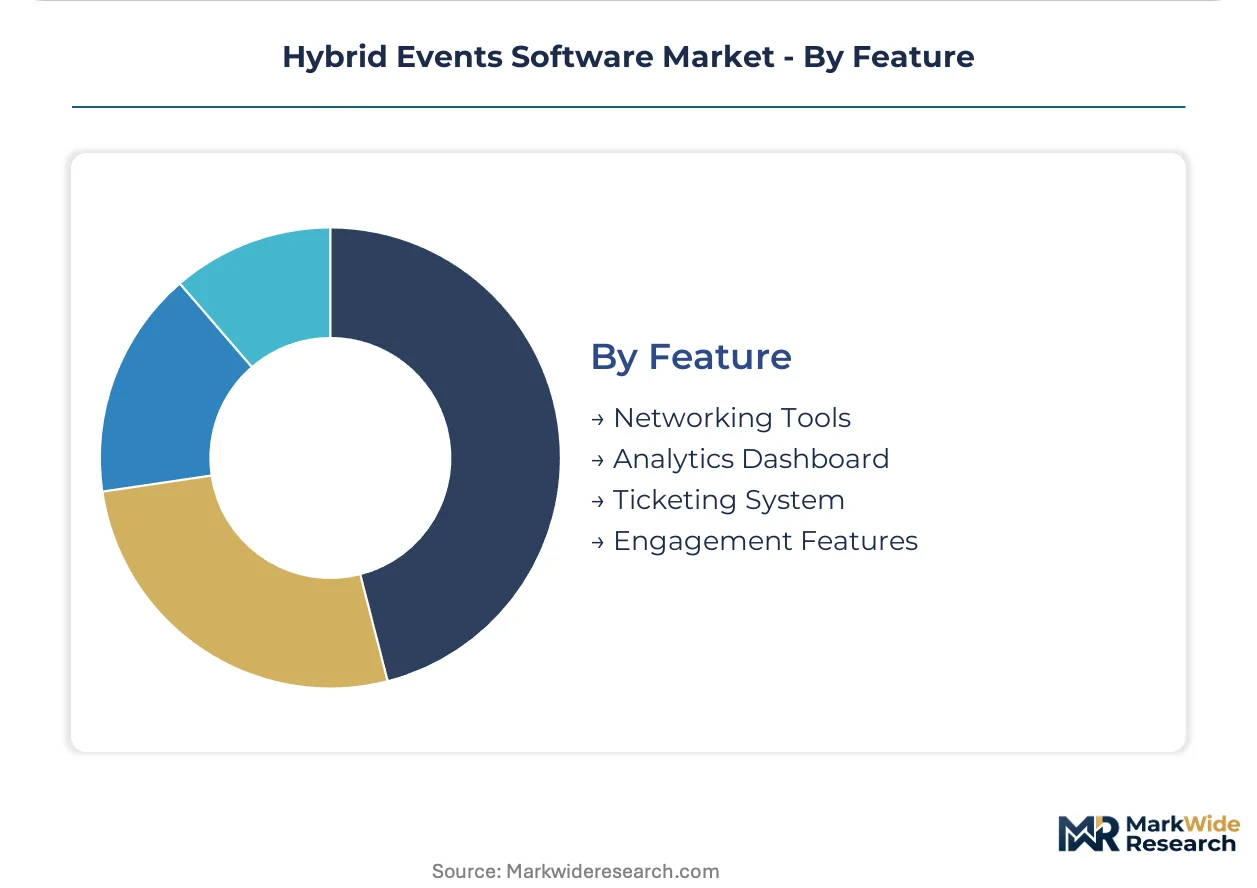
Revenue attribution and networking capabilities differentiate premium offerings, while basic ticketing functionality commoditizes across vendor tiers.
- Analytics Dashboard:Native CRM pipeline connectivity linking event participation to closed-won deals, with GDPR-compliant consent frameworks for facial recognition and sentiment analysis. North American pharmaceutical and technology sectors pilot these architectures for investor relations events requiring Q&A latency reduction.
- Networking Tools:AI-powered attendee matching, video speed networking, and persistent community spaces. European venues now mandate explicit consent-layer documentation for algorithmic decision-making transparency in emotion tracking applications.
- Engagement Features:Polling, Q&A, gamification, and live reaction telemetry.
- Ticketing System:Registration, payment processing, and access control modules facing bundling pressure from integrated platforms.
Ticketing System deployment is mature and commoditized. Analytics Dashboard adoption is climbing the fastest as procurement teams demand demonstrable ROI linkage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure concentration in Northern Virginia and hyperscale data center buildouts across Frankfurt anchor procurement patterns for hybrid events software platforms serving enterprise accounts.
United States
Fortune 500 technology and pharmaceutical sectors drive unified technology stack consolidation. FCC closed captioning guidelines for live-streamed content shape product roadmaps for US-facing platforms. Northern Virginia's data center corridor hosts the dominant share of multi-CDN failover architecture serving North American enterprise RFPs.
Germany
Industrial trade show organizers digitize legacy event infrastructure at scale to preserve sponsorship yield under physical capacity constraints. EU AI Act compliance layers mandate consent frameworks for facial recognition and sentiment analysis at European venues. Munich and Frankfurt manufacturing event clusters accelerate platform refresh cycles among organizers serving GDPR jurisdictions.
United Kingdom
Mid-market event organizers favor SaaS deployment models for predictable operational expenditure and rapid deployment timelines. NIS2 cybersecurity directives force architectural segmentation of platform instances. London's corporate travel and financial services corridors concentrate demand for hotel chain distribution integration.
France
Educational institutions deploy virtual commencement and alumni engagement programs with permanentized hybrid instructional models. GDPR and CNIL guidance impose explicit consent-layer documentation for algorithmic decision-making transparency in emotion tracking. Paris and Lyon university clusters pilot edge-computing video processing for Q&A latency reduction.
India
Corporate training divisions expand geographic dispersion of employee populations through browser-based immersive environments. The country's national data protection framework shapes consent architecture for facial recognition features. Bangalore and Hyderabad technology campuses drive fastest-expanding customer base for virtual event platforms in the Asia-Pacific corridor.
Hybrid Events Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent networking and analytics specializations. The vendor base stratifies across three tiers: integrated platform incumbents with hotel distribution connectivity, streaming-native challengers with rapid feature iteration, and point-solution specialists facing category compression. Dominant competitive moves include M&A activity consolidating registration and analytics workflows, plus strategic partnerships embedding revenue attribution into CRM ecosystems.
Within the integrated platform tier, Cvent and Bizzabo exemplify archetypes anchoring enterprise procurement consolidation around unified technology stacks. Hopin occupies a position representing streaming-native challengers competing through networking tool innovation. EventMobi sits within the compliance-adapted specialist segment, navigating regional data residency requirements across GDPR and emerging biometric privacy jurisdictions.
| Leading Market Players |
|---|
| Cvent |
| Stova |
| Hopin |
| Bizzabo |
| Eventbrite |
| EventMobi |
| b2match |
| Zoom Video Communications |
| RingCentral |
| Others |
Pricing and Supply Chain Analysis
Enterprise-midmarket capability divergence splits the hybrid events software landscape into subscription bundles with white-glove implementation versus self-serve SaaS tiers with limited API access. This bifurcation manifests in procurement patterns where Fortune 500 technology and pharmaceutical buyers in Germany and the United States consolidate around unified stacks with embedded hotel chain distribution connectivity, while mid-market event organizers in the United Kingdom and Netherlands gravitate toward predictable operational expenditure models with rapid deployment timelines.
Pricing Analysis
White-glove implementation and live event operations support anchor premium pricing tiers, with managed services unbundled from base SaaS subscriptions in mid-market segments. Three-tier pricing structure across premium, standard, and economy levels tracks integration depth and latency performance, with sub-200ms bi-directional engagement telemetry commanding substantial premiums. Cost compression in the webinar platform tier intensifies because hyperscale infrastructure amortization drives cloud-native unit economics below on-premises alternatives. Mid-market event organizers exhibit the highest price sensitivity, while enterprise IT procurement teams prioritize demonstrable ROI linkage over per-seat costs.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for integrated hybrid solutions, with API extensibility and regional data residency options increasingly table stakes. Hyperscale infrastructure draws from AWS, Azure, and Google Cloud concentration in Northern Virginia and Frankfurt, creating supplier concentration risk for margin-sensitive vendors. Real-time video ingestion engines, multi-CDN failover architecture, and edge-computing processing nodes constitute critical component dependencies. Single-source vulnerability in hyperscale cloud provisioning threatens operational continuity for platforms lacking multi-provider redundancy. Distribution runs through channel partners embedding revenue attribution into CRM ecosystems and direct sales teams serving Fortune 500 accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into video infrastructure engineering and forward integration into CRM pipeline connectivity is reshaping competitive positioning as vendors race to collapse registration, streaming, and analytics into unified technology stacks.
For Market Incumbents: Anchor enterprise renewals through deep hotel chain distribution system integration while accelerating regional data residency deployments to meet NIS2 cybersecurity directives and EU AI Act compliance layers. Streaming-native challengers with rapid networking tool iteration threaten mid-market share; counter by embedding native revenue attribution capabilities that connect event participation to closed-won deals. Prioritize certification investment in GDPR-compliant consent frameworks for facial recognition and sentiment analysis features. For New Entrants and Emerging Players: Launch via API-first distribution targeting mid-market event organizers in the Asia-Pacific corporate travel corridor where hotel chain connectivity remains underexploited outside North American accounts. White space concentrates in edge-computing video processing for Q&A latency reduction in high-value investor events, with educational institutions in France and corporate training divisions in India representing the fastest-expanding customer base for browser-based immersive environments. For Investors and Strategic Acquirers: Re-rating potential sits with compliance-adapted specialists given NIS2 and emerging biometric privacy fragmentation forcing architectural segmentation of global platform instances. Long-term viability favors vendors with regional data residency options spanning GDPR jurisdictions and Illinois BIPA exposure. Monitor procurement consolidation velocity among Fortune 500 technology and pharmaceutical sectors as the inflection indicator for platform versus point-solution winner-take-most dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Collapsing registration, streaming, and analytics into unified stacks displaces point solutions in enterprise procurement. |
| Acquisition of Specialist Firm | Consolidating networking tool innovators accelerates feature parity against streaming-native challengers. |
| Geographic Expansion | Establishing Frankfurt and Munich data residency captures German industrial trade show digitization demand. |
| Strategic Partnership | Embedding revenue attribution into Salesforce and HubSpot ecosystems differentiates against generic streaming providers. |
| Product Launch | Edge-computing video processing for sub-200ms latency targets addresses pharmaceutical investor relations requirements. |
Research Methodology
Document review covered SEC filings from public event technology vendors, hyperscaler capex disclosures, and EU regulatory guidance on AI Act implementation, complemented by interviews with CTOs at Fortune 500 enterprises, IT procurement officers managing vendor consolidation initiatives, platform engineers specializing in real-time video infrastructure, and channel partners embedding event technology into corporate travel workflows. Secondary validation drew from trade association data on industrial trade show digitization, hospital procurement databases for healthcare event applications, and customs records tracking cross-border software licensing. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Segmentation outputs reflect deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions modeled across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating EU data sovereignty framework compliance costs and AI-enhanced engagement analytics refresh cycle acceleration. Forecast inputs included cloud infrastructure pricing trajectories from hyperscale providers and enterprise RFP velocity tracking unified versus point-solution procurement preferences.
Regulatory enforcement variance, hyperscale infrastructure pricing volatility, and real-time engineering talent scarcity concentration are the dominant revision risks to base case assumptions. Forecasts reflect documented procurement consolidation patterns and compliance-driven refresh cycle assumptions subject to revision. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Document Management System Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Lecture Capture Solutions Market