
 Commercial Augmented Reality Glasses Market | 2026-2036
Commercial Augmented Reality Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Augmented Reality Glasses Market Insights
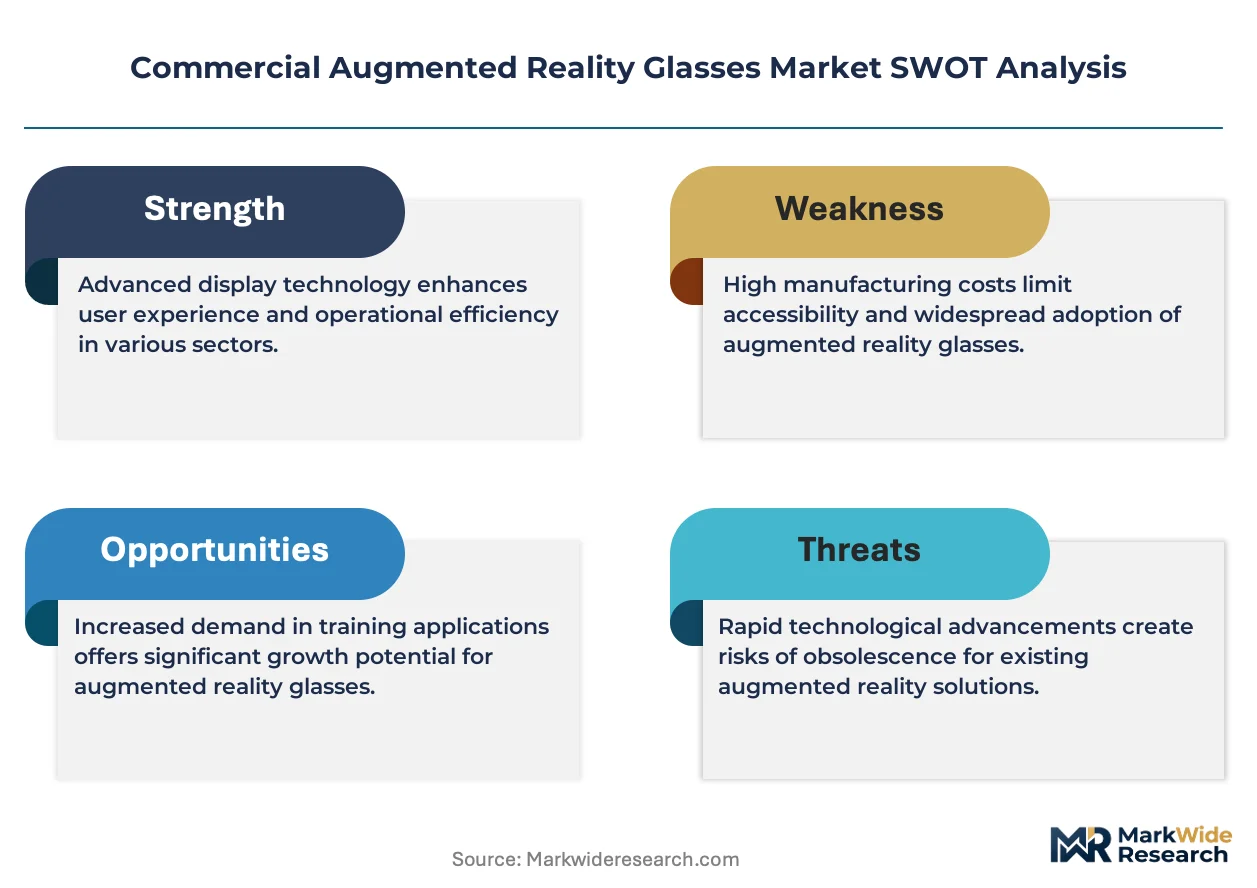
The EU Green Deal's digital-product-passport requirements is restructuring procurement criteria for enterprise wearables across European manufacturing chains. Microsoft Corporation leverages its HoloLens industrial installed base to sustain defense and healthcare contracts. Vuzix Corporation anchors North American supply through in-house waveguide manufacturing. XREAL, Inc. competes on consumer-to-commercial crossover optics at lower unit economics.
Commercial augmented reality glasses integrate micro-displays, waveguide combiners, and spatial computing processors into head-worn devices that overlay digital information onto physical environments for hands-free industrial task execution. Optical see-through systems using diffractive waveguides now achieve sub-ten-millimeter eye relief with forty-degree fields of view, enabling prolonged factory-floor use without operator fatigue. Head-mounted displays command the largest revenue pool in product type segmentation due to military and surgical training budgets, while mixed reality technology captures the fastest expansion as video passthrough quality approaches optical clarity. Smart glasses within retail applications concentrate margin pools through software subscription attach rates rather than hardware margins alone.
FCC equipment authorization rules govern radio-frequency emissions for AR glasses sold in the United States, while CE marking under the EU MDR and RoHS directives constrains optical component materials and electromagnetic compatibility for European commercial deployment. China's MIIT enforces GB standards on wireless transmission power that shape product localization strategies for manufacturers targeting industrial users in Shenzhen and Beijing. Buyers should monitor how FDA breakthrough device designation pathways for AR-guided surgery may reshape healthcare end-user certification requirements before committing to platform selections.
Market Dynamics
Waveguide optics thinning is compressing lens stack dimensions below ten millimeters while expanding field-of-view, forcing incumbent manufacturers to retool fabrication lines or cede industrial contracts to vertically integrated specialists.
Growth Catalysts
- EU Green Deal digital-product-passport mandates:Procurement criteria across European manufacturing chains now require traceable component sourcing, accelerating replacement cycles for legacy enterprise wearables.
- Surgical training budgets:Healthcare systems in Germany and Japan are deploying head-mounted displays for AR-guided procedures under stricter workplace safety protocols.
- Shenzhen-Shanghai industrial corridor concentration:China's MIIT GB standards enforcement on wireless transmission power is shaping localized product strategies for factory-floor deployment.
Market Restraints
- Waveguide substrate cost volatility:High-purity glass and photoresist inputs face supply concentration from Japanese and German specialty chemical suppliers.
- Optical see-through technical ceiling:Diffractive waveguides struggle with outdoor contrast ratios above ten thousand lux, limiting construction and field service applications.
- FCC equipment authorization friction:Radio-frequency emission testing timelines for AR glasses average fourteen months, delaying US commercial launches.
Strategic Opportunities
- FDA breakthrough device designation pathway:AR-guided surgery platforms accessing expedited review timelines can capture healthcare certification requirements before competitors.
- Video passthrough mixed reality convergence:Quality approaching optical clarity is opening surgical training and defense simulation applications previously reserved for optical see-through systems.
- Retail software subscription attach rates:Smart glasses vendors are unbundling hardware margins from recurring SaaS revenue in North American and European consumer-to-commercial crossover segments.
Industry Challenges
- Spatial computing processor integration complexity:Factory-floor IT departments lack personnel trained to synchronize AR glasses with legacy manufacturing execution systems.
- CE marking timeline under EU MDR:Electromagnetic compatibility and optical component material testing for RoHS compliance extends European market entry by eight to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Augmented Reality Glasses Market |
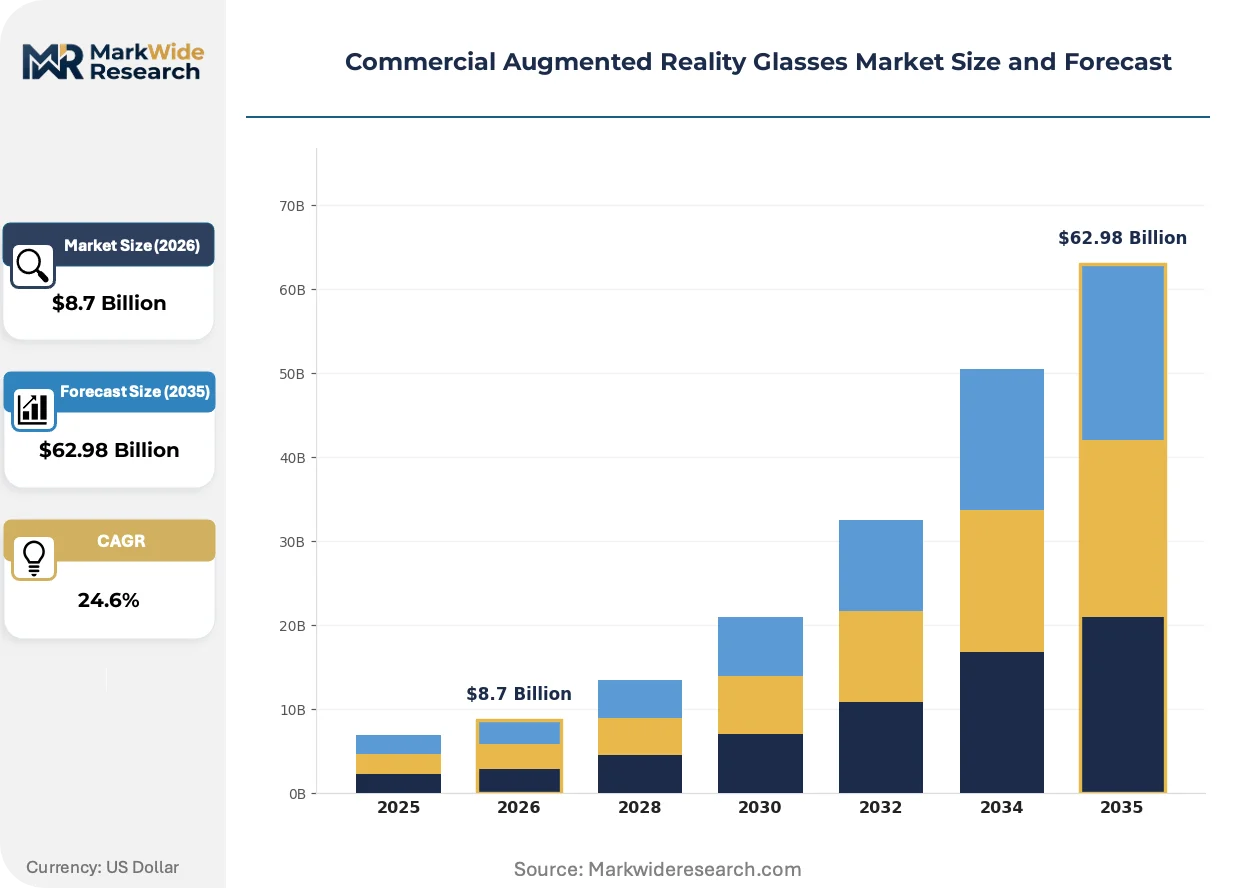
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Mounted Displays, Smart Glasses, Contact Lens Displays, Handheld Devices Application: Training & Simulation, Retail, Repair & Maintenance, Entertainment End User: Healthcare, Manufacturing, Education, Defense Technology: Optical See-Through, Video See-Through, Projection-Based, Mixed Reality |
| Companies Covered | Microsoft Corporation, XREAL, Inc., Magic Leap, Inc., Seiko Epson Corporation, Vuzix Corporation, RealWear Inc., Meta Platforms Inc., EssilorLuxottica, Rokid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Augmented Reality Glasses Market Trends and Innovations
Optical stack miniaturization, regulatory recalibration of medical device pathways, and procurement model fragmentation are simultaneously compressing hardware margins while expanding addressable software revenue pools.
Surface-relief grating waveguides is rewriting the competitive map for lens fabrication. German and Japanese manufacturing floors are adopting sub-millimeter eye-relief designs for eight-hour assembly shifts. This compression of optical module thickness is enabling form factors previously impossible without sacrificing field-of-view.
EU MDR and RoHS directive convergence is tightening material constraints on optical component supply chains. Electromagnetic compatibility testing now covers wireless transmission modules previously exempt under legacy medical device frameworks. Surgical training hardware vendors targeting European hospitals are requalifying suppliers to meet dual certification requirements.
Buyer preference is rotating toward outcome-verified deployment contracts rather than capital expenditure purchases. Industrial users in Shenzhen and Shanghai are demanding software performance guarantees tied to assembly error-rate reduction. This behavioral shift is visible most acutely in Chinese state-owned manufacturing enterprises consolidating vendor relationships under MIIT-mandated digital transformation budgets.
Commercial Augmented Reality Glasses Market Segmentation
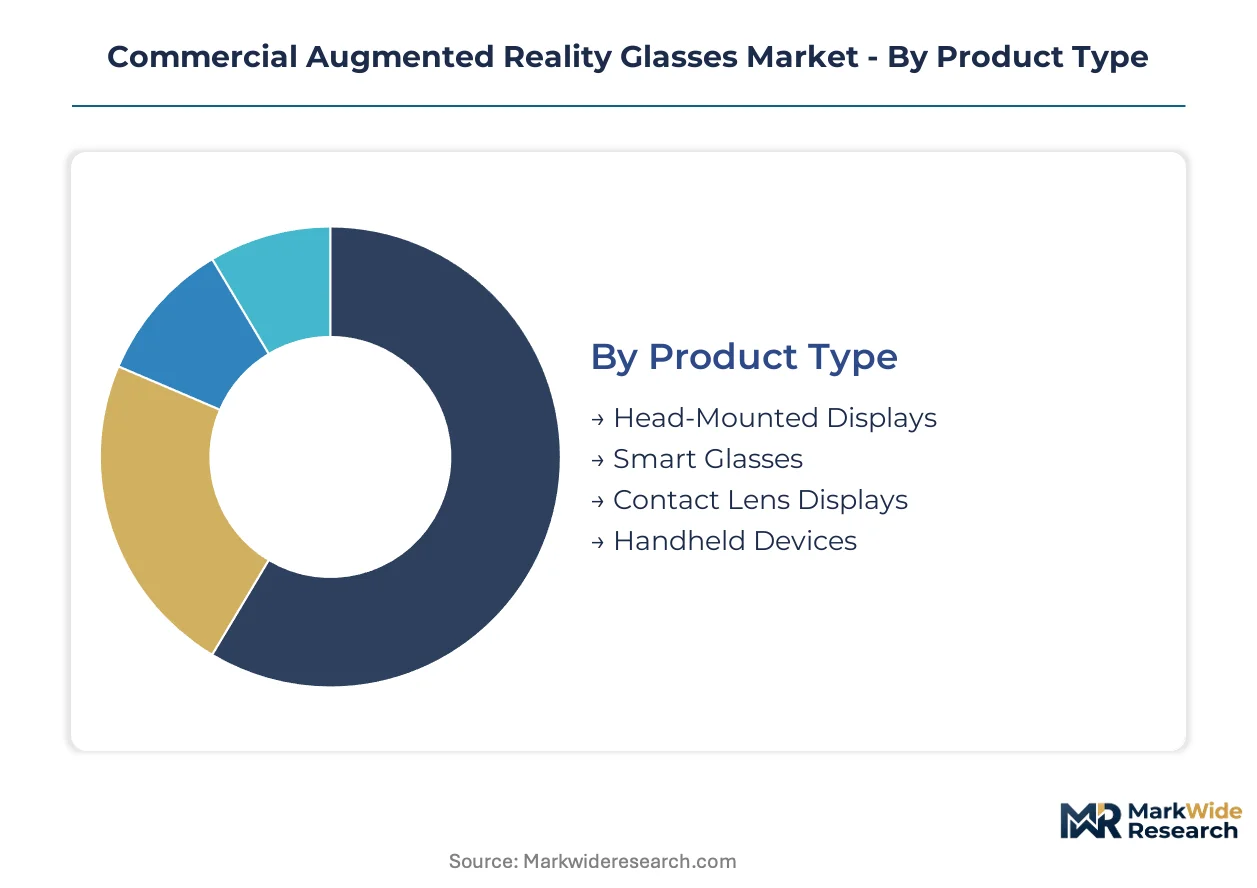
Segmentation in commercial AR glasses reveals divergent capital requirements across optical architectures and deployment contexts. Procurement committees weigh upfront hardware investment against software attach rates and integration complexity. Each dimension carries distinct margin profiles and certification pathways.
Product Type:
Head-mounted displays demand the heaviest capital commitment, with waveguide fabrication and spatial computing processors driving unit economics. Smart glasses achieve lower bill-of-materials through smartphone-tethered designs. Contact lens displays and handheld devices occupy opposite ends of the integration spectrum.
- Head-Mounted Displays:These systems integrate diffractive waveguides, micro-displays, and onboard spatial processors into sealed optical modules. Military training budgets in Germany and surgical simulation contracts in Japan concentrate demand here, though fourteen-month FCC equipment authorization timelines constrain US rollout velocity.
- Smart Glasses:Tethered architectures offload processing to paired smartphones, slashing per-unit hardware costs while preserving core overlay functionality. Retail software subscription attach rates in North America generate recurring revenue pools that offset thin device margins.
- Contact Lens Displays:Micro-LED arrays embedded in hydrogel substrates target ocular surface mounting with sub-millimeter optics.
- Handheld Devices:Tablet-based AR maintains relevance where head-worn deployment faces workplace safety restrictions or operator resistance.
Most installed capacity flows through Head-Mounted Displays. Expansion is steepest in Smart Glasses.
Application:
Volume concentrates in use cases where hands-free operation delivers measurable throughput gains. Repair scenarios command premium pricing for field service durability. Entertainment applications compete with consumer VR on unit economics.
- Training & Simulation:Surgical residency programs and defense simulation centers drive specification requirements. Germany's hospital procurement frameworks under EU MDR now mandate electromagnetic compatibility testing that extends vendor qualification cycles.
- Repair & Maintenance:Factory-floor IT departments in Shenzhen and Shanghai deploy these systems for assembly guidance under MIIT-mandated digital transformation budgets.
- Retail:Inventory management and clienteling applications generate software-as-a-service revenue through outcome-verified deployment contracts.
- Entertainment:Location-based experiences and theme park installations absorb hardware refresh cycles.
Training & Simulation captures the dominant revenue pool. Repair & Maintenance is climbing the fastest.
End User:
Defense and healthcare procurement operate on multi-year certification cycles that freeze vendor selection. Manufacturing buyers rotate faster, prioritizing integration with legacy manufacturing execution systems. Education budgets remain fragmented across institutional purchasers.
- Healthcare:AR-guided surgery platforms pursue FDA breakthrough device designation for expedited review timelines. EU MDR and RoHS directive convergence tightens material constraints on optical component supply chains entering European hospitals.
- Defense:Military contracts sustain waveguide optics innovation through multi-year development programs. German and Japanese manufacturing floors supply sub-millimeter eye-relief designs for eight-hour assembly shift compatibility.
- Manufacturing:China's industrial corridor around Shenzhen and Shanghai concentrates demand for factory-floor deployment.
- Education:Vocational training institutions and university research labs purchase on capital expenditure cycles.
Defense procurement anchors supplier viability. Healthcare is gaining share fastest.
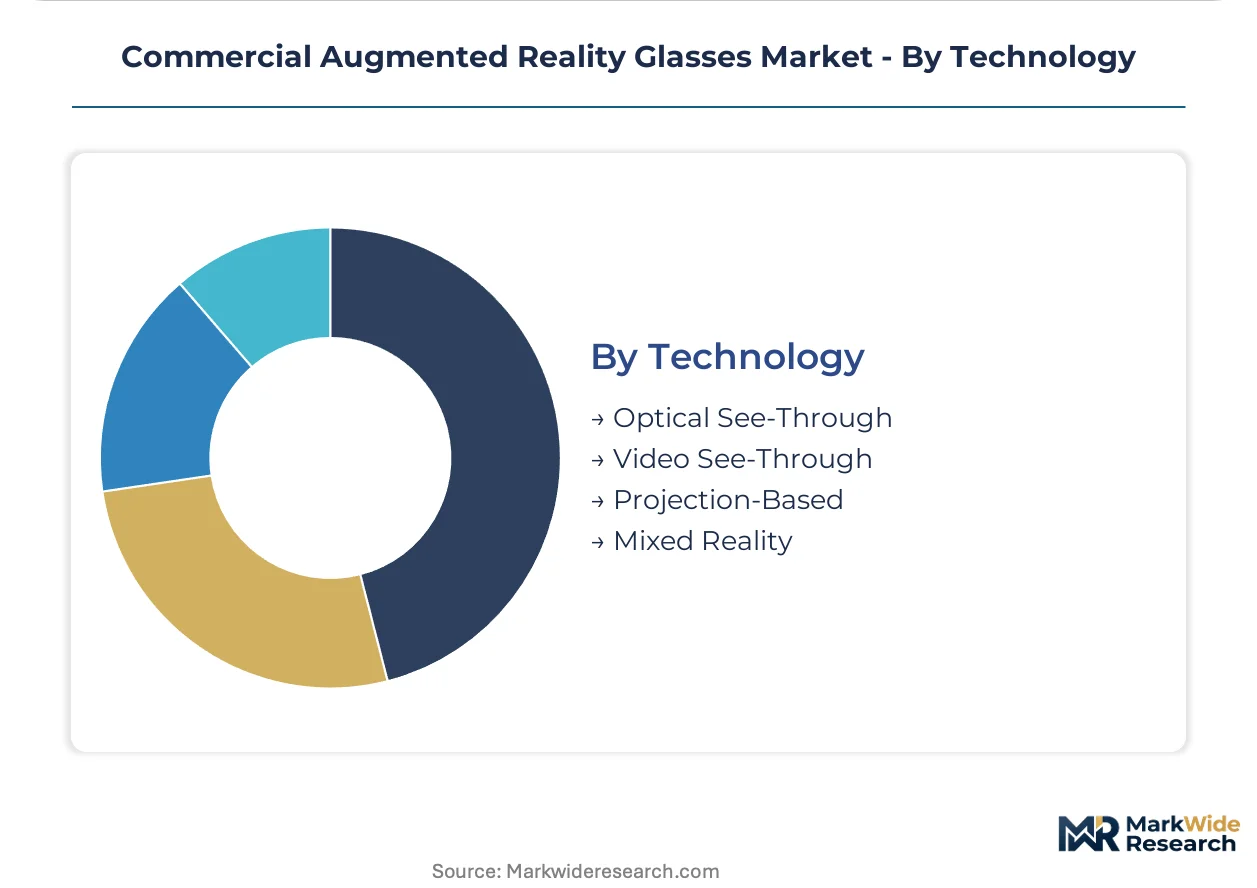
Technology:
Optical clarity and environmental robustness define competitive positioning. Video passthrough quality now approaches optical see-through fidelity in controlled lighting. Projection-based systems retreat to niche industrial settings.
- Optical See-Through:Diffractive waveguides achieve sub-ten-millimeter eye relief with forty-degree fields of view. Outdoor contrast ratios above ten thousand lux remain a technical ceiling limiting construction and field service applications.
- Mixed Reality:Video passthrough architectures merge real-time camera feeds with rendered overlays. Surgical training and defense simulation applications previously reserved for optical systems now open to this approach.
- Video See-Through:Camera-dependent systems sacrifice some spatial fidelity for manufacturing simplicity and cost reduction.
- Projection-Based:Retinal projection and spatial light modulators persist in specialized medical visualization contexts.
Optical See-Through retains the largest installed base. Mixed Reality shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial augmented reality glasses trace their industrial lineage to German precision optics and Japanese display manufacturing, with both nations establishing foundational waveguide fabrication capabilities during the 2010s before Chinese assembly integration scaled unit economics.
United States
Military training budgets and surgical simulation contracts drive procurement from defense contractors and academic medical centers. FCC equipment authorization rules govern fourteen-month radio-frequency testing timelines that constrain commercial rollout velocity. Boston and San Francisco Bay Area clusters concentrate venture-backed spatial computing startups alongside established enterprise software integrators.
Germany
Automotive assembly floors and hospital procurement frameworks sustain demand for sub-millimeter eye-relief optical designs. EU MDR and RoHS directive convergence tightens electromagnetic compatibility and material constraints on component supply chains. Stuttgart and Munich industrial corridors deploy AR-guided systems under stricter workplace safety protocols for eight-hour manufacturing shifts.
China
State-owned manufacturing enterprises consolidate vendor relationships under MIIT-mandated digital transformation budgets for factory-floor deployment. GB standards on wireless transmission power shape localized product strategies and certification pathways. Shenzhen and Shanghai industrial clusters concentrate demand for assembly guidance systems in electronics contract manufacturing.
Japan
Surgical residency programs and precision manufacturing sustain specification requirements for head-mounted display durability. METI industrial policy supports domestic waveguide substrate suppliers facing high-purity glass input cost volatility. Nagoya and Osaka production bases supply sub-millimeter optical modules for regional medical device OEMs.
United Kingdom
Defense simulation centers and vocational training institutions purchase on capital expenditure cycles with multi-year certification timelines. CE marking under EU MDR extends market entry procedures for optical component material compliance. London and Southeast England clusters house mixed reality software developers serving European healthcare procurement frameworks.
Commercial Augmented Reality Glasses Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across optical stack fabrication and spatial computing software integration. The vendor base separates into vertically integrated waveguide specialists, smartphone-tethered smart glasses assemblers, and defense-sustained head-mounted display manufacturers. Dominant competitive moves include backward integration into captive waveguide supply and outcome-verified deployment contracts replacing hardware-centric sales.
Within the vertically integrated tier, Vuzix Corporation anchors North American supply through in-house optical manufacturing capabilities. Microsoft Corporation occupies a position sustained by industrial installed base expansion into defense and healthcare certification pathways. XREAL, Inc. exemplifies the consumer-to-commercial crossover archetype competing on compressed unit economics for tethered smart glasses deployment.
| Leading Market Players |
|---|
| Microsoft Corporation |
| XREAL, Inc. |
| Magic Leap, Inc. |
| Seiko Epson Corporation |
| Vuzix Corporation |
| RealWear Inc. |
| Meta Platforms Inc. |
| EssilorLuxottica |
| Rokid |
| Others |
Pricing and Supply Chain Analysis
Captive waveguide manufacturing anchors both supply security and pricing power for AR glasses vendors, with in-house optical fabrication insulating against Japanese and German specialty chemical supplier concentration while enabling premium positioning in healthcare and defense procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated surgical platforms from CE-marked industrial systems and smartphone-tethered retail devices. Price differentiation hinges on certification grade and waveguide fabrication complexity. Cost compression in the economy tier is intensifying because Chinese OEMs are scaling smartphone-tethered architectures. Manufacturing buyers in Shenzhen and Shanghai exhibit the highest price sensitivity; defense contractors show the least.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Austin maintain hub-and-spoke patterns for optical module fulfillment. Manufacturing concentrates in Germany, Japan, and China. High-purity glass substrates and photoresist inputs draw from Japanese and German specialty chemical suppliers. Single-source vulnerability in waveguide substrate supply poses structural risk. Distribution runs through direct enterprise sales teams for healthcare and defense, with channel partners serving retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EU MDR and FDA breakthrough device pathways accelerating replacement cycles and freezing vendor selection for multi-year certification windows.
For Market Incumbents: To counter video passthrough mixed reality convergence threatening optical see-through dominance, incumbents should deepen captive waveguide supply and accelerate FDA breakthrough designation pursuit for surgical platforms. Backward integration into high-purity glass sourcing mitigates Japanese supplier concentration risk. For New Entrants and Emerging Players: System integrators in China's MIIT-mandated digital transformation programs represent the most penetrable channel. Target repair and maintenance applications in Shenzhen-Shanghai electronics contract manufacturing with outcome-verified deployment contracts replacing capital expenditure sales models. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated waveguide specialists because optical fabrication scarcity concentrates margin capture in healthcare and defense certification pathways. Five-to-ten-year viability favors vendors with in-house lens manufacturing and locked hospital procurement frameworks. Monitor FDA breakthrough device designation grants as inflection indicators for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waveguide Manufacturing | Captive optical fabrication insulates against Japanese photoresist supplier concentration and accelerates CE marking timelines. |
| FDA Breakthrough Device Designation Pursuit | Expedited review pathways lock healthcare procurement relationships before competitors complete fourteen-month FCC authorization cycles. |
| Outcome-Verified Deployment Contracts | Software performance guarantees tied to assembly error-rate reduction capture Chinese state-owned manufacturing digital transformation budgets. |
| Regional Distribution Center Expansion | Hub-and-spoke fulfillment in Stuttgart and Nagoya reduces lead times for German automotive and Japanese surgical training contracts. |
| Smartphone-Tethered Architecture Scaling | Offloaded processing slashes unit costs for retail SaaS attach-rate models in North American consumer-to-commercial crossover segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with optical engineers at waveguide fabrication facilities, procurement leads at German automotive OEMs, FDA regulatory affairs specialists, and hospital biomedical engineers with secondary validation against SEC filings from spatial computing vendors, EMA medical device registration databases, MIIT GB standards publications, and customs records for high-purity glass substrate trade flows. Bottom-up unit economics and top-down procurement budget triangulation anchored market sizing.
Segment-weighting applied differential growth assumptions across optical see-through, mixed reality, video see-through, and projection-based technology architectures, with product type splits between head-mounted displays and smart glasses, application segmentation across training and simulation, repair and maintenance, retail, and entertainment, and end-user categories spanning healthcare, defense, manufacturing, and education across the projection horizon. CAGRs derived from installed base replacement cycles, certification timeline constraints, and software attach-rate penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to waveguide substrate cost volatility, FCC equipment authorization timeline shifts, and EU MDR electromagnetic compatibility testing requirement changes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market