
 Asia-Pacific Intelligent Document Processing Market | 2026-2036
Asia-Pacific Intelligent Document Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Intelligent Document Processing Market Insights
Subscription-based cloud financing and pay-per-document pricing is reshaping competitive entry barriers across the Asia-Pacific Intelligent Document Processing landscape. UiPath leverages its robotic process automation heritage to anchor enterprise deployments in Japanese manufacturing conglomerates. ABBYY competes through specialized optical character recognition engines calibrated for complex script languages across South Asian markets. Automation Anywhere sustains channel control via partner networks penetrating mid-tier financial institutions in Singapore and Hong Kong.
Intelligent Document Processing combines machine learning, natural language processing, and computer vision to extract, classify, and validate unstructured data from scanned images, PDFs, and handwritten forms without manual transcription. The technology processes documents at throughput rates exceeding 10,000 pages per hour while maintaining field-level accuracy above ninety-five percent for structured templates. Cloud deployment configurations currently lead value generation as Australian healthcare providers and Indian government agencies prioritize scalable infrastructure with minimal capital expenditure. Workflow automation applications command premium pricing due to integration complexity with legacy core banking systems across regional financial institutions. Data extraction modules targeting invoice processing exhibit the steepest growth trajectory among product types, driven by GST compliance automation requirements in India and e-invoicing mandates in Japan.
India's BIS cloud security standards, Japan's METI data governance guidelines, and Australia's Privacy Act frameworks collectively shape product certification requirements and cross-border data handling protocols for vendors operating across the region. Japan's JIS standards for electronic document authenticity create additional compliance layers for solutions processing legal and contractual materials. Stakeholders must monitor evolving data localization statutes in Indonesia and Vietnam that threaten to fragment cloud architecture strategies currently optimized for regional scale.
Market Dynamics
India's PLI scheme for IT hardware procurement is compressing enterprise software deployment timelines, forcing vendors to reconfigure cloud delivery architectures for accelerated government and banking sector onboarding.
Growth Catalysts
- Japan's e-invoicing mandate:METI compliance requirements are forcing mid-tier manufacturers to automate document workflows, creating immediate demand for invoice processing modules.
- Healthcare digitization:Australian healthcare administration corridors are replacing paper-based patient records with automated classification systems to meet Privacy Act data handling protocols.
- GST automation:India's tax compliance infrastructure is driving banking hubs to deploy field-level validation engines for unstructured invoice data.
Market Restraints
- Data localization statutes:Indonesia and Vietnam's emerging data sovereignty rules threaten to fragment regional cloud architectures optimized for cross-border scale.
- Script complexity:South Asian language character sets require specialized OCR calibration, elevating implementation costs for vendors without pre-trained models.
- Legacy integration friction:Core banking system interdependencies in Southeast Asian financial institutions extend deployment cycles and compress vendor margins.
Strategic Opportunities
- Vietnam's underpenetrated SME segment:Manufacturing clusters outside Ho Chi Minh City lack document automation, presenting first-mover expansion potential for cloud-native entrants.
- Natural language processing convergence:Integration of transformer-based models with computer vision is enabling real-time contract analysis for Japanese legal departments.
- Subscription financing innovation:Pay-per-document pricing models are lowering adoption barriers for mid-tier financial institutions in Singapore and Hong Kong.
Industry Challenges
- Certification timeline compression:BIS cloud security standards and JIS electronic authenticity protocols require simultaneous compliance, straining vendor QA resources.
- Specialized talent scarcity:Shortage of machine learning engineers with regional language expertise constrains product localization velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Intelligent Document Processing Market |
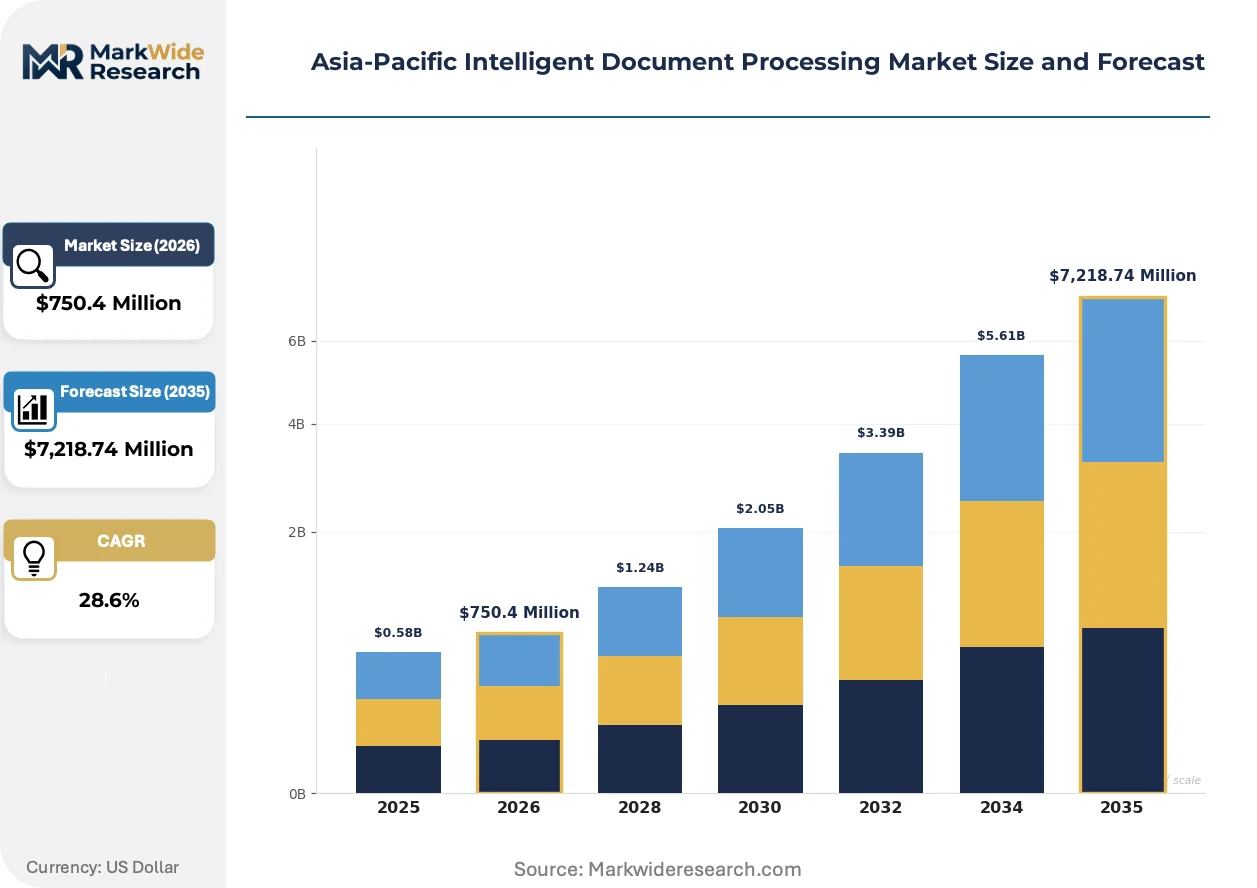
| Market Size in 2026 | $750.4 Million |
| Market Size in 2035 | $7,218.74 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OCR, Data Extraction, Classification, Workflow Automation Application: Invoice Processing, Legal Document Management, Healthcare Records, Contract Analysis End User: Financial Institutions, Government Agencies, Educational Institutions, Healthcare Providers Deployment: On-Premises, Cloud, Hybrid, Managed Services |
| Companies Covered | Automation Anywhere, ABBYY, UiPath, IBM Corporation, OpenText Corporation, Kofax, WorkFusion, Appian Corporation, HCL Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Intelligent Document Processing Market Trends and Innovations
Document processing architectures are pivoting toward modular, API-first designs that decouple extraction engines from workflow orchestration layers. This structural shift enables faster customization for sector-specific compliance requirements.
Transformer-based language models are migrating from English-centric training to multilingual fine-tuning for complex Indic and East Asian scripts. Japanese manufacturing conglomerates are adopting these engines for contractual document analysis. The technology is migrating from research environments to production deployments within eighteen-month cycles, compressing vendor R&D timelines.
Australia's Privacy Act frameworks are mandating enhanced audit trails for automated decision systems processing personal data. Healthcare providers must implement explainable extraction logic for patient records. Diagnostic imaging networks in Sydney and Melbourne are responding by demanding field-level confidence scoring from document classification vendors.
Mid-tier financial institutions are consolidating vendor relationships around integrated platform providers rather than point solutions. Singaporean banks are replacing standalone OCR tools with end-to-end automation suites. This concentration is most visible in Hong Kong's private banking sector, where procurement committees now prioritize workflow breadth over extraction accuracy metrics alone.
Asia-Pacific Intelligent Document Processing Market Segmentation
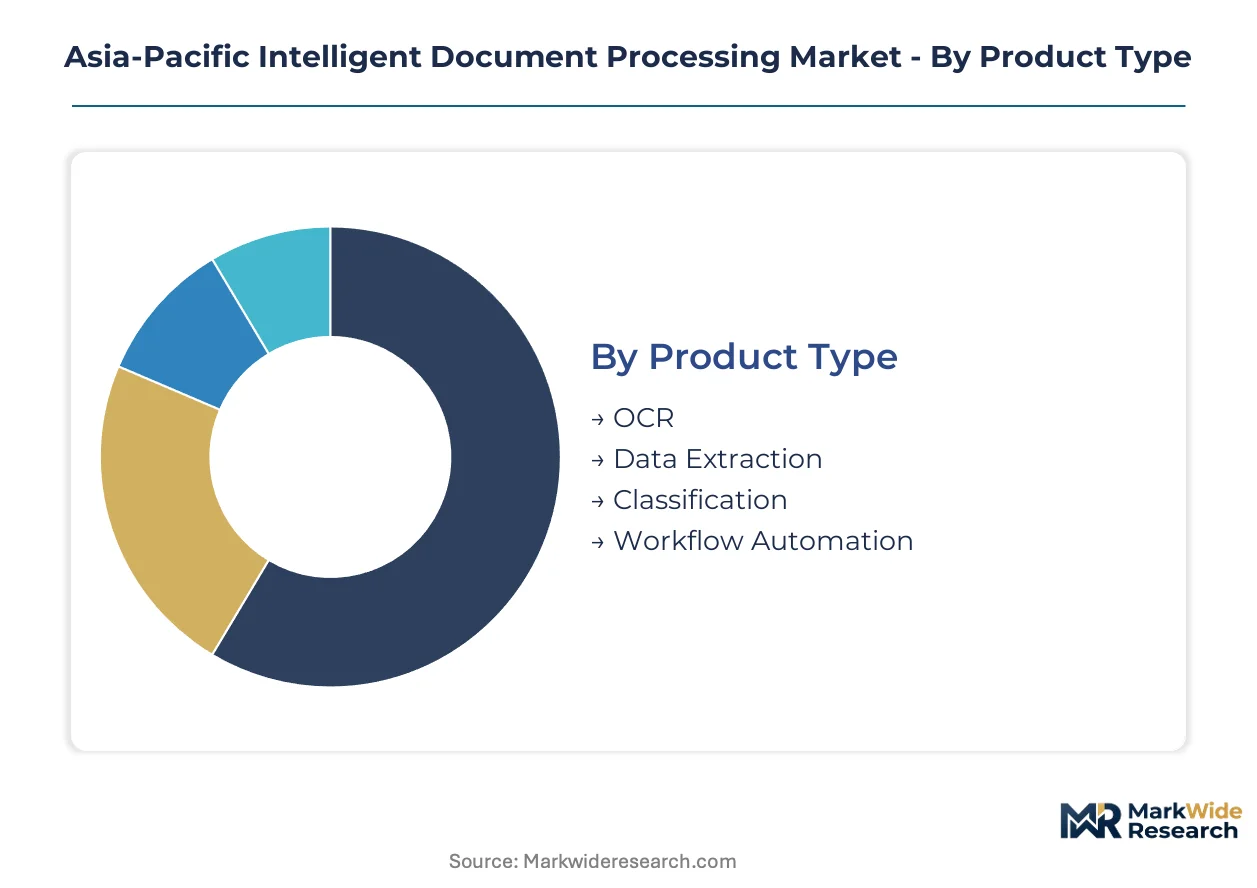
Segmentation in the Asia-Pacific Intelligent Document Processing market reveals how procurement priorities diverge across compliance environments and infrastructure maturity levels. Understanding these splits enables vendors to calibrate pricing architectures and localization investments for specific buyer profiles.
Product Type:
Cost tier separates basic optical recognition from premium workflow orchestration capabilities across the region's procurement committees.
- OCR:Optical character recognition engines convert scanned images and handwritten forms into machine-readable text through pattern-matching algorithms. Japanese manufacturers and Indian government agencies deploy these modules for high-volume invoice digitization under METI and GST compliance pressures.
- Data Extraction:Field-level parsing engines identify and validate specific data points within unstructured documents using machine learning classifiers. Banking hubs in Mumbai and Singapore's financial district prioritize these tools for automated loan documentation processing, driven by regulatory audit trail requirements.
- Classification:Document categorization systems apply taxonomy rules to route materials to appropriate downstream workflows.
- Workflow Automation:End-to-end orchestration layers integrate extraction outputs with enterprise systems and approval chains.
Workflow Automation holds installed capacity. Data Extraction is rotating up the share rankings.
Application:
Customer type dictates solution complexity, with tax compliance mandates creating distinct procurement urgency curves across use cases.
- Invoice Processing:Automated extraction and validation of line-item details from supplier invoices, purchase orders, and receipts. India's GST infrastructure and Japan's e-invoicing mandate are compressing deployment timelines for mid-tier manufacturers in both markets.
- Healthcare Records:Patient document classification and clinical data extraction with Privacy Act audit trail compliance. Australian providers in Sydney and Melbourne corridors demand explainable AI logic for automated decision systems processing personal health information.
- Legal Document Management:Contract repository organization and retrieval for law firms and corporate legal departments.
- Contract Analysis:Risk identification and obligation extraction from commercial agreements using natural language processing.
Invoice Processing holds installed capacity. Healthcare Records is climbing the fastest.
End User:
Geography correlates with infrastructure maturity, with banking hubs and government digitization programs concentrating demand in specific corridors.
- Financial Institutions:Banks, insurers, and capital markets firms deploying document automation for KYC, loan origination, and claims processing. Singapore and Hong Kong private banking sectors are consolidating vendor relationships around integrated platform providers rather than point solutions.
- Government Agencies:Public sector entities automating citizen service delivery and internal administrative workflows. India's PLI scheme for IT hardware procurement is accelerating enterprise software deployment timelines across central and state government bodies.
- Healthcare Providers:Hospitals, clinics, and diagnostic networks replacing paper-based patient records with automated classification systems.
- Educational Institutions:Universities and examination boards processing admissions documents and credential verification.
Financial Institutions hold installed capacity. Government Agencies are gaining share fastest.
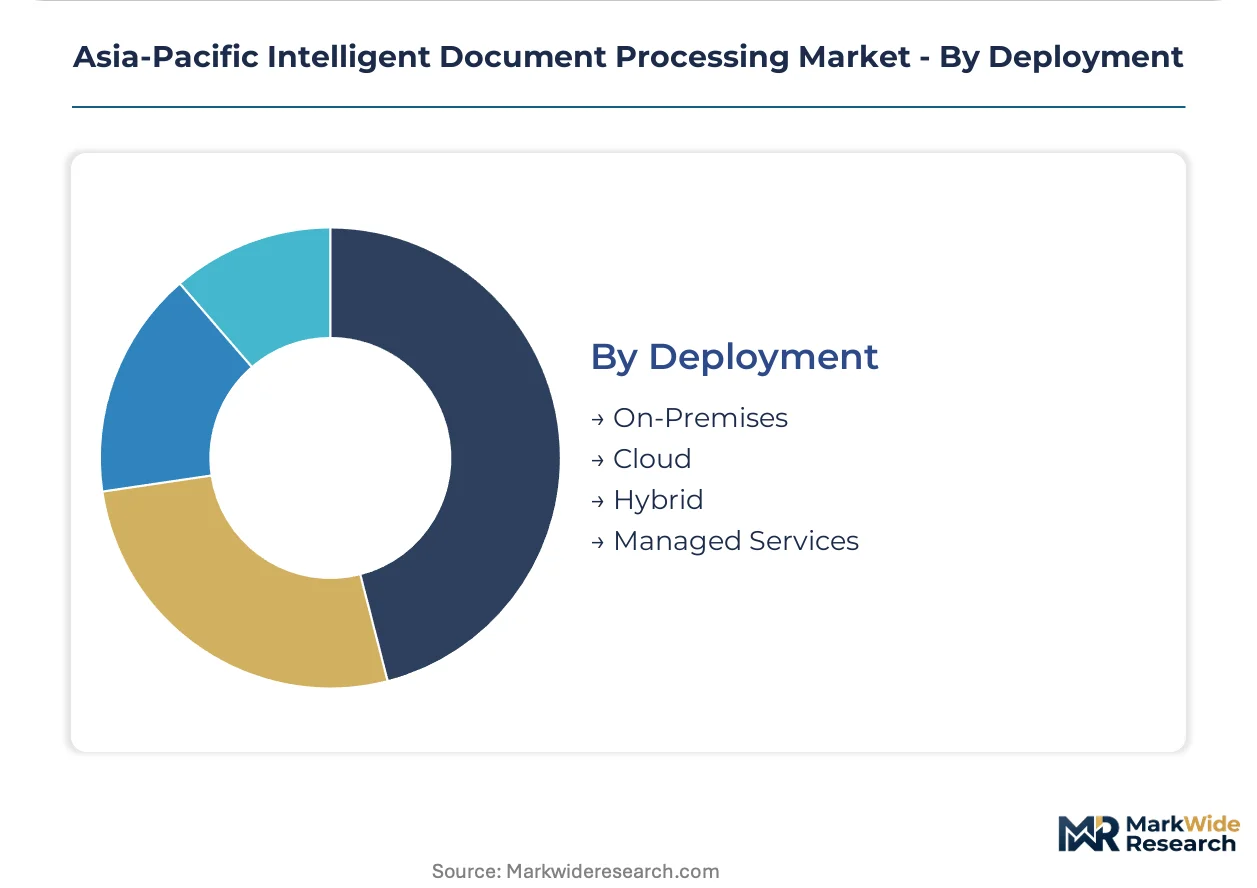
Deployment:
Supply concentration in cloud infrastructure is displacing on-premises architectures as data localization statutes reshape regional delivery models.
- Cloud:Multi-tenant SaaS delivery with elastic scaling and subscription-based pricing. Australian healthcare providers and Indian government agencies prioritize these configurations to minimize capital expenditure while meeting BIS cloud security standards.
- Hybrid:Mixed architectures combining on-premises processing for sensitive data with cloud-based analytics and storage. Japanese manufacturing conglomerates favor this model to satisfy JIS electronic document authenticity requirements while accessing scalable compute.
- On-Premises:Self-hosted installations within client data centers for maximum data sovereignty control.
- Managed Services:Outsourced document processing operations with vendor-managed infrastructure and staffing.
Cloud holds installed capacity. Hybrid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for IT hardware procurement is compressing enterprise software deployment timelines across the region. Government digitization programs and tax compliance mandates are concentrating demand in specific national corridors. Banking hubs and healthcare administration networks anchor procurement volume.
India
Mumbai and Bangalore banking hubs are deploying field-level validation engines for unstructured invoice data under GST automation pressure. BIS cloud security standards govern public sector procurement timelines. State government bodies in Maharashtra and Telangana are accelerating enterprise software onboarding.
Japan
METI's e-invoicing mandate is forcing mid-tier manufacturers in Nagoya and Osaka industrial belts to automate document workflows. JIS standards for electronic document authenticity create compliance layers for legal materials processing. Tokyo-headquartered manufacturing conglomerates are adopting contractual document analysis systems.
Australia
Sydney and Melbourne healthcare corridors are replacing paper-based patient records with automated classification systems. Privacy Act frameworks mandate explainable extraction logic for patient data handling. Diagnostic imaging networks demand field-level confidence scoring from classification vendors.
Singapore
Private banking sectors are consolidating vendor relationships around integrated platform providers rather than point solutions. The Monetary Authority of Singapore's digital banking framework accelerates automation procurement. Mid-tier financial institutions in the central business district are adopting pay-per-document pricing models.
Vietnam
Manufacturing clusters outside Ho Chi Minh City lack document automation infrastructure. Emerging data localization statutes threaten to fragment cloud architectures optimized for regional scale. Provincial industrial zones present first-mover expansion potential for cloud-native entrants targeting SME segments.
Asia-Pacific Intelligent Document Processing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately concentrated vendor base. RPA heritage firms leverage installed automation relationships to anchor enterprise deployments. OCR specialists compete through script-calibrated engines for complex language markets. Platform consolidators are absorbing point-solution vendors to expand workflow breadth. Strategic partnerships with systems integrators and cloud infrastructure providers dominate competitive moves.
Within the RPA-heritage tier, UiPath and Automation Anywhere occupy positions shaped by robotic process automation lineage. ABBYY exemplifies the optical character recognition specialist archetype. These three anchors represent distinct competitive vectors: workflow breadth, channel density, and script-language calibration.
| Leading Market Players |
|---|
| Automation Anywhere |
| ABBYY |
| UiPath |
| IBM Corporation |
| OpenText Corporation |
| Kofax |
| WorkFusion |
| Appian Corporation |
| HCL Technologies |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in GPU-accelerated compute infrastructure across Southeast Asian data centers is forcing vendors to prioritize enterprise clients with committed volume contracts, compressing margins for mid-tier deployments while elevating pricing power for cloud-native entrants with reserved capacity pipelines.
Pricing Analysis
Certification level creates the primary spread between deployment tiers, with BIS cloud security clearance and JIS electronic authenticity compliance commanding substantial premiums over uncertified alternatives. SaaS-tiered subscription models dominate procurement in Australian healthcare and Indian government sectors, while pay-per-document transactional pricing penetrates Singaporean mid-tier banking. Price differentiation stems from compliance overhead and integration complexity with legacy core systems. Cost compression in standard-tier offerings is intensifying because channel partners are absorbing implementation risk to secure recurring revenue streams. Government agencies exhibit highest price sensitivity due to fixed budget cycles, whereas Japanese manufacturing conglomerates prioritize workflow breadth over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced AI accelerators are fragmenting hardware procurement strategies across the region. Compute infrastructure concentrates in Singapore, Australia, and Japan, with Indian data centers rapidly expanding domestic GPU cluster capacity. Software supply chains draw from open-source machine learning frameworks, proprietary OCR engines, and transformer-based language models fine-tuned for regional scripts. Single-source vulnerability in cloud infrastructure provisioning threatens deployment timelines for vendors without multi-region failover architectures. Distribution runs through systems integrators and hyperscaler marketplaces, with channel partners managing localization and compliance layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
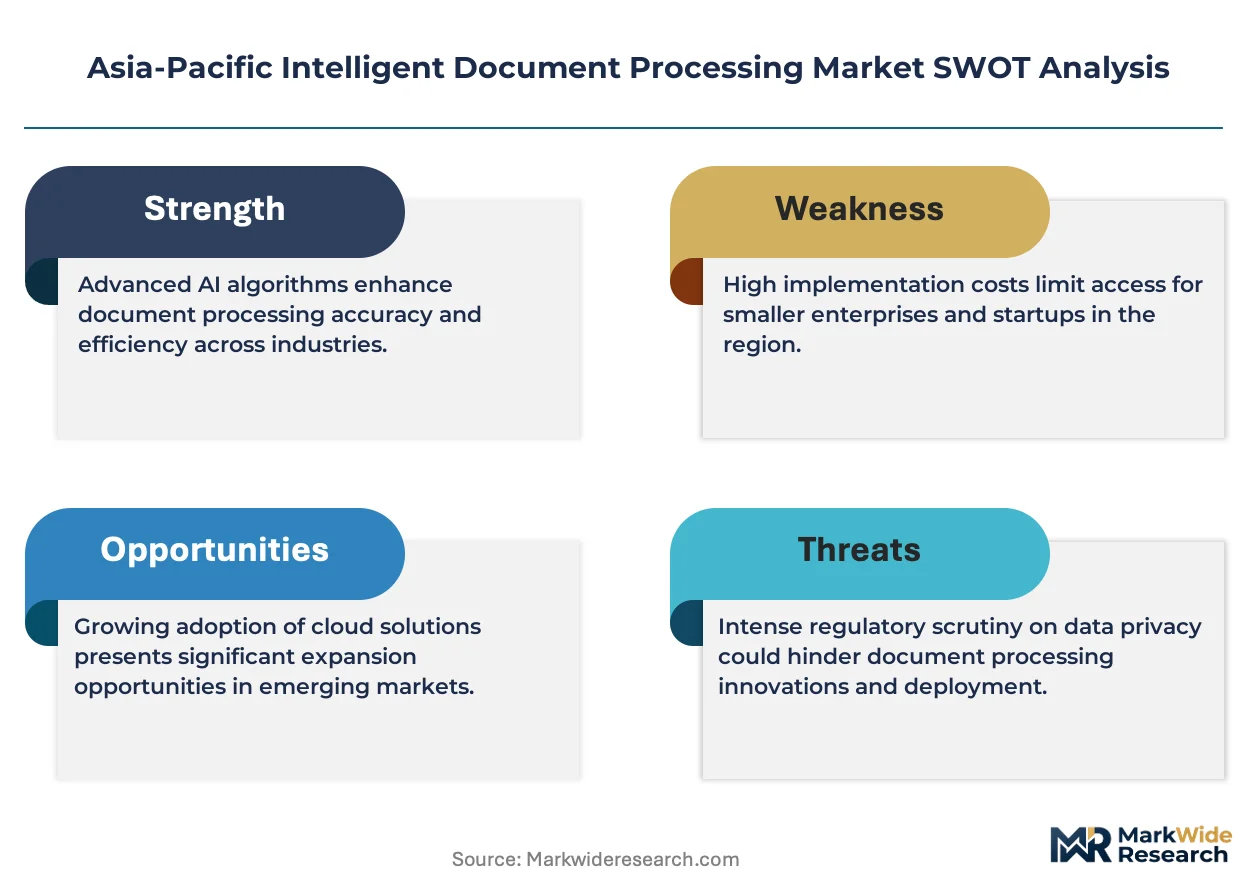
The Asia-Pacific Intelligent Document Processing market sits in early-cycle expansion, with e-invoicing mandates and GST automation creating immediate procurement urgency that outpaces vendor delivery capacity.
For Market Incumbents: Insulate enterprise relationships by embedding workflow automation deeper into core banking system architectures, creating switching costs that neutralize cloud-native challengers. Accelerate certification investment against BIS and JIS standards to maintain procurement eligibility in Indian government and Japanese legal segments. Channel control through exclusive systems integrator partnerships represents the critical defensive lever against platform consolidation trends in Singapore and Hong Kong private banking. For New Entrants and Emerging Players: Vietnam's manufacturing clusters outside Ho Chi Minh City represent the most penetrable entry point, with document automation penetration below regional benchmarks and emerging data localization statutes favoring localized cloud infrastructure. India's state government digitization programs under PLI acceleration offer second-mover capture potential for vendors with pre-certified cloud architectures. A direct-to-enterprise sales motion bypassing channel markups enables competitive pricing against incumbent platform providers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among workflow automation platform providers with embedded extraction engines, suggesting superior long-term viability across a five-to-ten-year holding horizon. Acquisition targets should prioritize vendors with pre-trained models for Indic and East Asian scripts, scarce technical capability that constrains competitor localization velocity. The signal to watch is consolidation velocity in Singaporean and Hong Kong financial institutions, where procurement committee shifts toward integrated suites indicate tipping point timing for platform rollups.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Fast-Track Investment | Parallel BIS and JIS compliance pipelines accelerate procurement eligibility in Indian government and Japanese manufacturing segments. |
| Regional Language Model Development | Pre-trained transformer architectures for complex Indic scripts create defensible moats against general-purpose OCR competitors. |
| Hybrid Deployment Architecture | Mixed cloud-on-premises configurations satisfy Vietnam and Indonesia data localization requirements without sacrificing regional scale economics. |
| Channel Partner Consolidation | Exclusive systems integrator relationships in Singapore and Hong Kong lock out competing platform vendors from private banking procurement cycles. |
| Pay-Per-Document Pricing Launch | Transactional revenue models lower adoption barriers for mid-tier financial institutions with constrained capital expenditure budgets. |
Research Methodology
A spread of perspectives from CTOs at regional banks, IT procurement officers in Australian healthcare networks, platform engineers at systems integrators, and regulatory compliance leads converged on the working assumptions driving segmentation splits. Primary interviews combined with secondary validation against SEC filings, hyperscaler capex disclosures, and government digitization program announcements anchored the demand-side assessment. Bottom-up deployment volume estimates triangulated against top-down IT spending forecasts across banking, healthcare, and government verticals.
Demand-supply balance modeling tracked cloud infrastructure capacity expansion against procurement pipeline compression from compliance mandates. Segmentation dimensions spanned deployment model, organization size, vertical industry, integration complexity with legacy systems, and regional adoption pattern. CAGRs derived from weighted scenario analysis across base, upside, and regulatory-delay cases. Forecast inputs incorporated BIS certification timeline data and METI e-invoicing implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in regional currency stability or cloud infrastructure investment cycles would shift the trajectory. Forecasts reflect documented assumptions about compliance deadline adherence and channel partner capacity expansion. Material shifts in data localization statute enforcement or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Community Engagement Software Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
North America API Management Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
Boat Navigation Software Market