
 China EDA Electronic Design Automation Market | 2026-2036
China EDA Electronic Design Automation Market Size, Share, and Industry Trends Forecast 2026-2036
China EDA Electronic Design Automation Market Insights
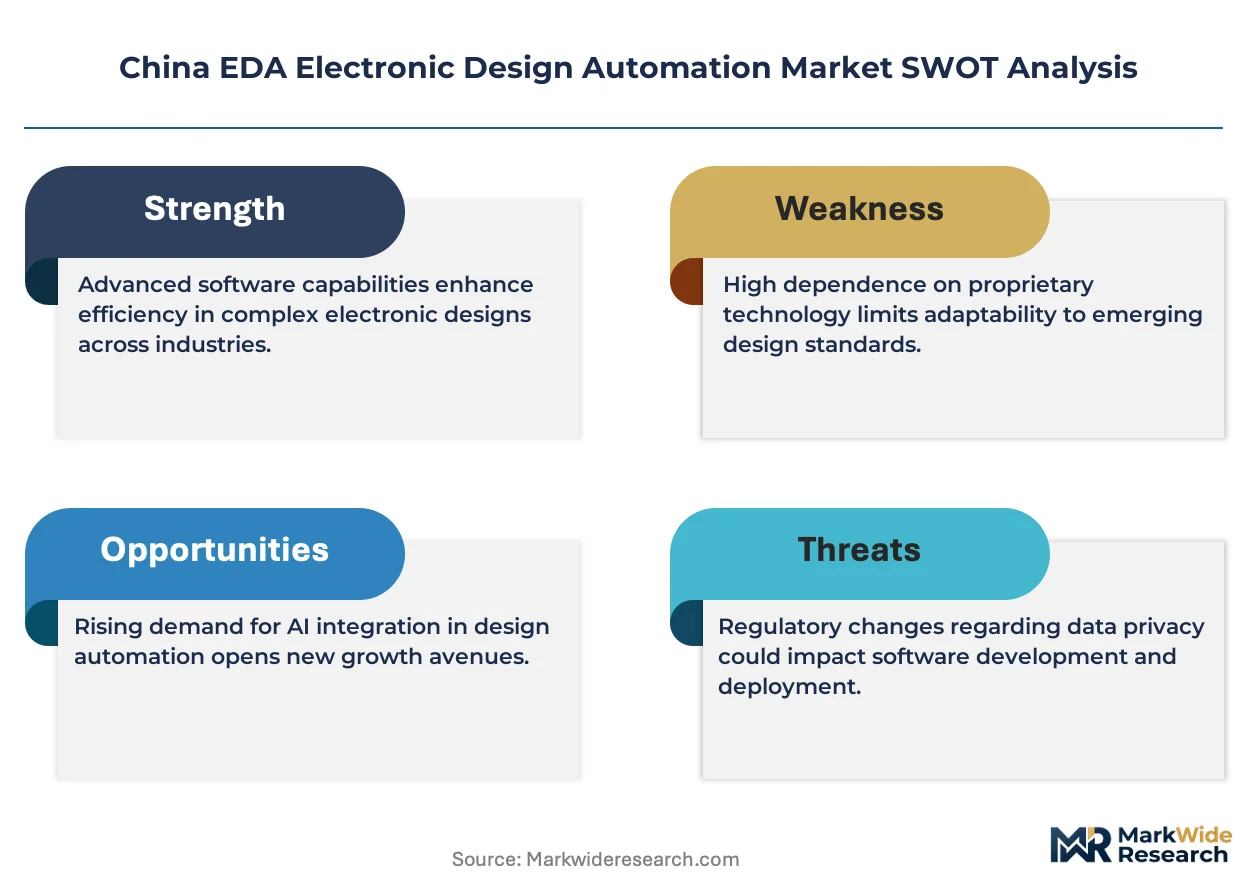
Domestic EDA toolchains are restructuring procurement economics for Chinese semiconductor firms. Empyrean Technology leverages native simulation suites to anchor government-backed substitution programs. Xpeedic Technology specializes in electromagnetic solver IP for 5G baseband and radar modules. Semitronix Corporation competes through yield analysis tools calibrated to domestic foundry processes.
Electronic design automation encompasses software algorithms, hardware description languages, and verification methodologies that enable integrated circuit and system-level design. Functional parameters include nanometer-scale place-and-route engines, parasitic extraction accuracy below one femtofarad, and multi-physics co-simulation convergence. IC Design Tools dominate procurement budgets as leading-edge node migration demands computational lithography and physical verification suites. Cloud-Based deployment is expanding fastest among fabless startups seeking elastic compute for sign-off regression cycles.
MIIT mandates and GB standards frameworks shape product qualification timelines for local EDA vendors. SAMR antitrust scrutiny on foreign software licensing terms is redirecting procurement toward domestic alternatives. Stakeholders must monitor foundry-design house co-development agreements as process technology roadmaps outpace standalone tool interoperability.
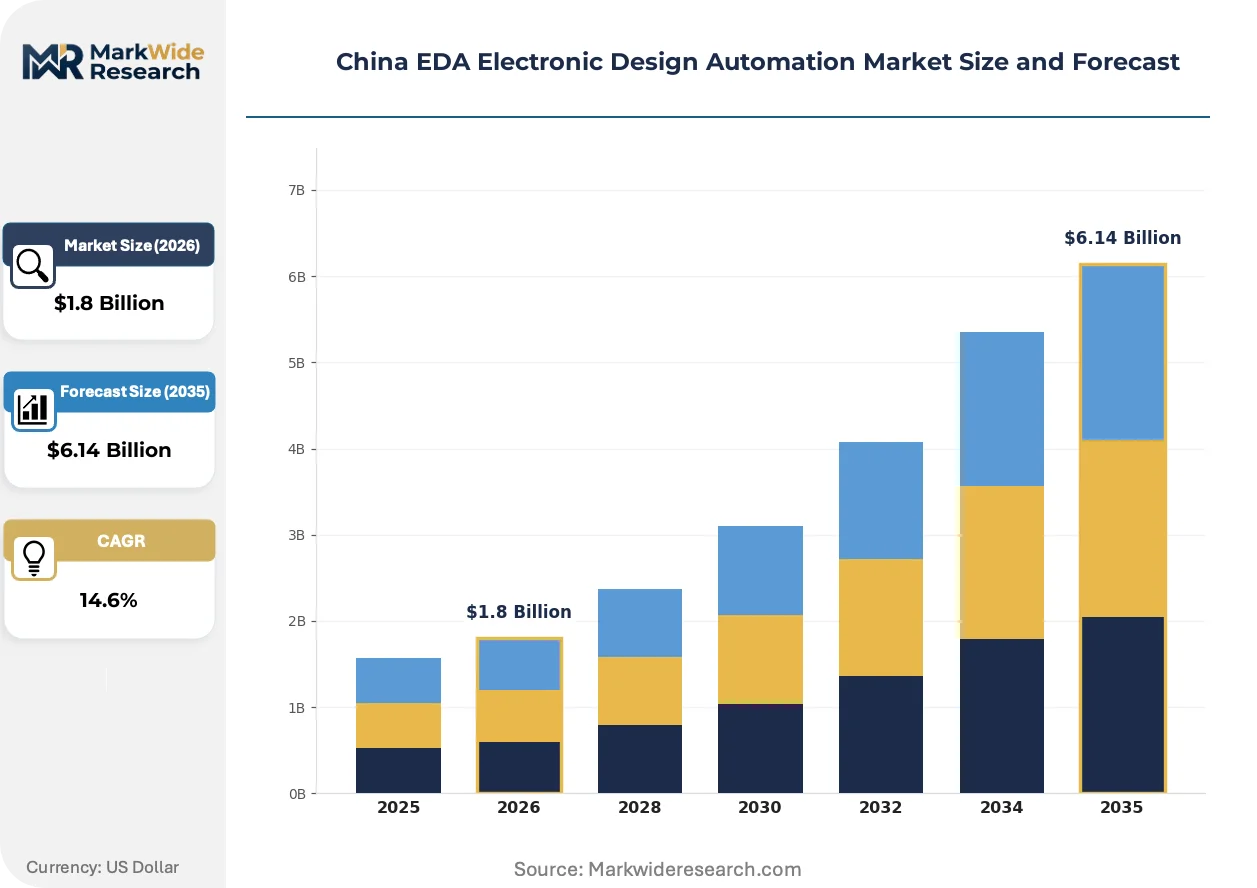
Market Dynamics
MIIT domestic software substitution mandates are restructuring procurement economics across Chinese semiconductor design houses, forcing immediate qualification timelines for native EDA toolchains while advanced node migration accelerates computational lithography spending.
Growth Catalysts
- Advanced Node Migration:Domestic foundries expanding 7nm and below process development require computational lithography and physical verification suites from qualified vendors.
- MIIT Substitution Mandates:Government procurement directives prioritize domestic EDA tools for state-backed IC design projects and defense-related semiconductor programs.
- Shenzhen Cluster Concentration:Fabless design house density in the Pearl River Delta generates concentrated demand for analog-mixed signal and RF design automation.
Market Restraints
- Foundry Process Access:Leading-edge PDK calibration requires multi-year co-development agreements with SMIC and Hua Hong that foreign vendors established decades earlier.
- IP Ecosystem Lock-in:Proprietary cell libraries and memory compilers from Cadence and Synopsys create switching costs exceeding two full tape-out cycles for mature design teams.
- Verification Compute Costs:Sign-off regression cycles for 5nm designs demand GPU-accelerated hardware emulation farms costing tens of millions in upfront capex.
Strategic Opportunities
- Cloud-Native Deployment:Fabless startups in Shanghai and Hangzhou are adopting elastic compute models for physical verification and parasitic extraction workloads.
- Automotive Functional Safety:ISO 26262 compliance requirements for ADAS chips create demand for fault simulation and safety verification tool suites.
- Chiplets and 3D Integration:Multi-die packaging standards are opening architecture planning and thermal-electrical co-simulation segments with limited incumbent presence.
Industry Challenges
- Cross-Domain Talent Scarcity:Engineers combining device physics expertise with machine learning algorithm development command premium compensation that strains domestic vendor R&D budgets.
- Interoperability Certification:GB standards compliance for data format exchange between point tools requires sustained investment in OpenAccess database adaptations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China EDA Electronic Design Automation Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IC Design Tools, PCB Design Software, FPGA Design Tools, Simulation Software End User: Semiconductor Companies, Automotive Manufacturers, Consumer Electronics, Telecom Providers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Application: Integrated Circuits, System on Chip, Embedded Systems, RF Design |
| Companies Covered | Empyrean Technology, Xpeedic Technology, Semitronix Corporation, Primarius Technologies, Huada Empyrean, EXCEEDA Technology, Gowin Semiconductor, Beijing Aerdai Information Technology, Faraday Dynamics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China EDA Electronic Design Automation Market Trends and Innovations
Computational methods and deployment architectures are fragmenting traditional EDA business models across Chinese design houses, creating openings for specialized vendors in electromagnetic simulation and yield analysis.
Machine learning-accelerated place-and-route is modularizing physical design workflows. Leading fabless houses in Beijing and Shanghai are adopting reinforcement learning-based congestion prediction for 5nm standard cell placement. This compression of iteration cycles is modularizing the traditional divide between front-end synthesis and back-end implementation teams.
MIIT cybersecurity review protocols for industrial software are tightening data localization requirements. SAMR scrutiny of foreign vendor licensing terms is redirecting procurement toward domestic alternatives with on-premise deployment options. State-backed design institutes are prioritizing tools with complete source code auditability for classified projects.
Subscription pricing for point tools is displacing perpetual license models among mid-size design houses. Cloud-based electromagnetic solvers from specialized vendors are capturing RF module design budgets previously allocated to comprehensive platform suites. This unbundling is most visible in 5G baseband and radar module development clusters around Chengdu and Xi'an.
China EDA Electronic Design Automation Market Segmentation
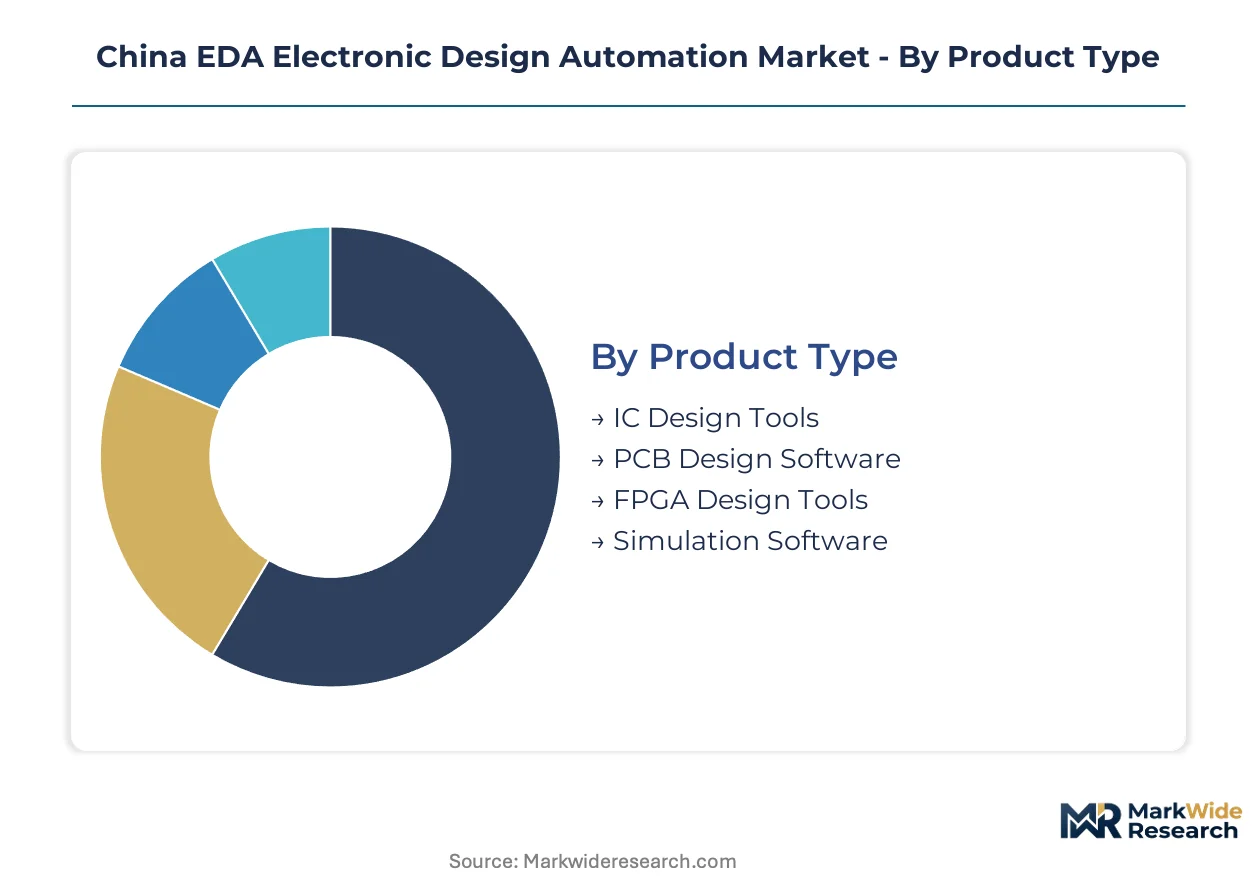
EDA procurement patterns in China diverge sharply across product architectures and deployment models. Domestic substitution mandates and foundry process roadmaps create distinct qualification requirements for each segment category.
Product Type:
Customization intensity varies from highly proprietary IC toolchains to standardized PCB suites, reshaping vendor competitive dynamics across the stack.
- IC Design Tools:Computational lithography and physical verification engines dominate procurement budgets for 7nm and below node development. Shenzhen fabless clusters drive concentrated demand for analog-mixed signal automation suites.
- PCB Design Software:Layout and routing tools for high-density interconnects serve consumer electronics manufacturing corridors in Dongguan and Suzhou. MIIT software substitution directives accelerate domestic vendor qualification for military-aerospace board designs.
- Simulation Software:Multi-physics co-simulation platforms address thermal-electrical coupling in advanced packaging applications.
- FPGA Design Tools:Synthesis and place-and-route suites target 5G baseband prototyping in Chengdu and Xi'an defense electronics clusters.
Most installed capacity flows through IC Design Tools. Expansion is steepest in Simulation Software.
End User:
Customer sophistication tiers separate defense-cleared design institutes from commercial fabless startups, creating diverging procurement workflows.
- Semiconductor Companies:Leading domestic foundries and fabless houses consume the majority of computational lithography and sign-off verification licenses. SMIC and Hua Hong co-development agreements gate PDK access for advanced node tool qualification.
- Automotive Manufacturers:ISO 26262 functional safety compliance drives fault simulation and safety verification procurement for ADAS chip development. BYD and NIO captive semiconductor units anchor demand in Shenzhen and Hefei.
- Consumer Electronics:Smartphone and IoT module vendors prioritize cost-optimized PCB and RF design automation.
- Telecom Providers:Huawei and ZTE internal IC design divisions source specialized electromagnetic solvers for 5G infrastructure ASICs.
Semiconductor Companies absorb the dominant share of license value. Automotive Manufacturers are climbing the fastest as electrification accelerates captive chip design.
Deployment:
Data sovereignty requirements and regression cycle economics split procurement between captive infrastructure and elastic cloud models.
- On-Premises:Perpetual license models with dedicated emulation farms remain standard for defense-classified projects and leading-edge foundry design enablement. Complete source code auditability satisfies MIIT cybersecurity review protocols.
- Cloud-Based:Elastic compute for physical verification and parasitic extraction gains traction among Shanghai and Hangzhou fabless startups. GPU-accelerated regression cycles reduce upfront capex for sign-off workloads.
- Hybrid:Mixed deployments separate sensitive front-end design from scalable back-end verification.
- SaaS:Subscription point tools capture mid-size design house budgets previously allocated to comprehensive platform suites.
On-Premises retains the largest installed base. Cloud-Based deployment is gaining share fastest among venture-backed startups.
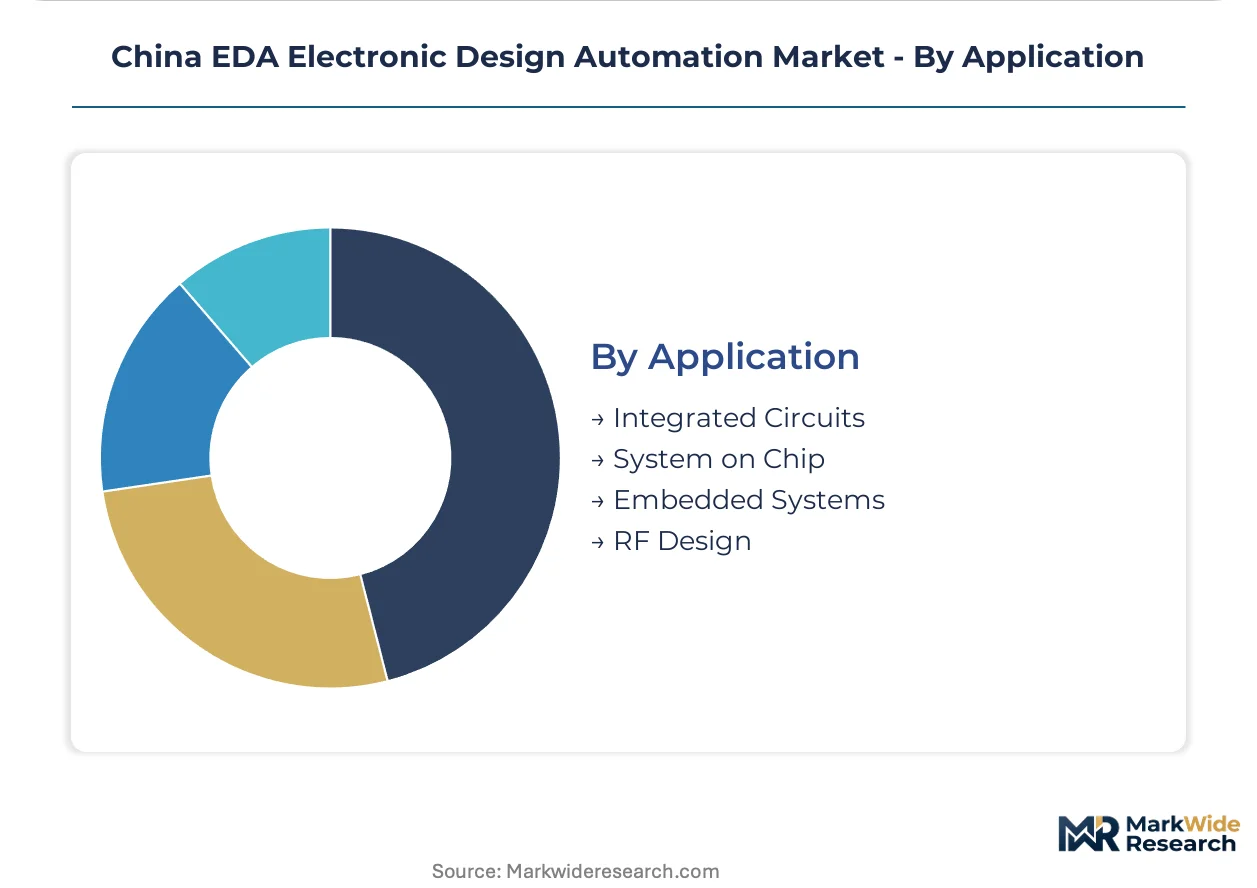
Application:
Design complexity gradients from planar ICs to multi-die chiplets fragment tool interoperability requirements.
- Integrated Circuits:Standard cell and memory design flows consume the bulk of place-and-route and timing analysis licenses. Domestic foundry migration to FinFET architectures intensifies computational lithography spending.
- System on Chip:Heterogeneous integration of CPU, GPU, and NPU blocks demands architecture exploration and power-performance-area optimization suites. Alibaba T-Head and Biren Technology anchor demand in Beijing and Shanghai.
- Embedded Systems:MCU and sensor fusion designs for automotive and industrial IoT prioritize low-power verification.
- RF Design:5G mmWave and radar module development drives electromagnetic solver procurement in Chengdu aerospace clusters.
Integrated Circuits command the deepest tool penetration. System on Chip shows the steepest expansion trajectory as AI accelerator designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors domestic EDA procurement as the Pearl River Delta's IC design cluster concentrates fabless demand for analog-mixed signal automation. MIIT software substitution directives and foundry process roadmaps reshape qualification timelines across provincial technology corridors.
Beijing-Tianjin-Hebei
State-backed semiconductor institutes and defense-cleared design houses drive demand for source-code-auditable EDA tools. MIIT cybersecurity review protocols prioritize on-premise deployment for classified projects. Zhongguancun technology corridor hosts architecture exploration teams for AI accelerator development.
Yangtze River Delta
Shanghai and Hangzhou fabless startups adopt cloud-based elastic compute for physical verification workloads. SAMR antitrust scrutiny on foreign licensing terms redirects procurement toward domestic alternatives. Zhangjiang Hi-Tech Park anchors computational lithography co-development with SMIC.
Pearl River Delta
Shenzhen's consumer electronics ecosystem generates concentrated RF and analog-mixed signal design automation demand. GB standards compliance for data format exchange shapes vendor qualification. Dongguan manufacturing corridors absorb PCB design software for high-density interconnect applications.
Sichuan-Chongqing
Chengdu aerospace and defense electronics clusters drive electromagnetic solver procurement for 5G radar modules. MIIT domestic substitution mandates accelerate local tool qualification for state-backed programs. Xi'an semiconductor research institutes anchor FPGA design tool adoption for baseband prototyping.
China EDA Electronic Design Automation Market Competitive Landscape
Strategic partnerships dominate the current landscape as domestic vendors secure foundry co-development agreements and government-backed qualification programs. The vendor base concentrates around native toolchains serving MIIT substitution mandates, with tiered specialization across simulation, physical verification, and yield analysis segments. Three archetypes define positioning: full-flow platform builders, point-tool specialists, and foundry-integrated enablers. Competitive moves center on PDK calibration partnerships and cloud-native deployment licensing.
Among Beijing-based platform builders, Empyrean Technology and Huada Empyrean occupy positions anchoring government-backed substitution programs. Xpeedic Technology exemplifies the point-tool specialist archetype, sitting within the electromagnetic simulation segment serving 5G infrastructure demand. Semitronix Corporation represents the foundry-integrated enabler model, with yield analysis tools calibrated to domestic process technology roadmaps.
| Leading Market Players |
|---|
| Empyrean Technology |
| Xpeedic Technology |
| Semitronix Corporation |
| Primarius Technologies |
| Huada Empyrean |
| EXCEEDA Technology |
| Gowin Semiconductor |
| Beijing Aerdai Information Technology |
| Faraday Dynamics |
| Others |
Pricing and Supply Chain Analysis
Computational lithography tool qualification for 7nm and below nodes simultaneously compresses development timelines and concentrates procurement leverage among domestic foundries. MIIT software substitution mandates accelerate this recalibration by redirecting state-backed design house budgets toward native EDA vendors with GB standards-compliant toolchains.
Pricing Analysis
GPU-accelerated emulation farm capex passes through to license pricing for leading-edge physical verification suites. Pricing stratifies across perpetual, subscription, and SaaS tiers, with customization level and foundry PDK certification status as primary differentiation drivers. Cost compression in cloud-based deployment models is intensifying because Shanghai and Hangzhou startups demand elastic compute without upfront infrastructure investment. Mid-size design houses exhibit highest price sensitivity, while defense-cleared institutes prioritize source-code auditability over cost.
Supply Chain Analysis
Freight and logistics costs for specialized hardware emulation equipment from the United States, Taiwan, and South Korea amplify total cost of ownership for on-premise deployments. EDA software distribution draws from concentrated semiconductor equipment manufacturing in these same jurisdictions, with lithography system components and GPU clusters as critical inputs. Single-source vulnerability in advanced node PDK calibration creates structural risk for domestic vendors lacking multi-year SMIC co-development agreements. Distribution runs through direct enterprise sales with foundry-integrated technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT domestic software substitution mandates compound procurement velocity for qualified native EDA toolchains, creating defensive moats for vendors with GB standards certification and state-backed design house relationships.
For Market Incumbents: Extend PDK calibration partnerships with SMIC and Hua Hong to anchor advanced node tool qualification timelines. Deepen backward integration into electromagnetic solver IP through targeted acquisition of Chengdu and Xi'an specialists. Certification investment in ISO 26262 functional safety compliance addresses automotive ADAS chip demand from BYD and NIO captive units.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in computational lithography suites creates white-space opportunity for point-tool specialists targeting parasitic extraction and thermal-electrical co-simulation. Cloud-native deployment models for physical verification workloads represent the most penetrable segment among Shanghai fabless startups. Go-to-market through foundry design enablement partnerships accelerates PDK integration without multi-year co-development overhead.
For Investors and Strategic Acquirers: Roll-up economics work for electromagnetic simulation specialists because 5G infrastructure and radar module demand fragments procurement across Chengdu, Xi'an, and Shenzhen clusters without dominant platform consolidation. Long-term viability centers on vendors with foundry-integrated yield analysis tools and MIIT qualification for defense programs. Watch SAMR antitrust enforcement intensity against foreign vendor licensing terms as inflection indicator for domestic substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Co-Development Agreement | PDK calibration with SMIC anchors 7nm tool qualification timelines for domestic vendors. |
| Cloud-Native Platform Launch | Elastic compute deployment captures Shanghai startup demand for GPU-accelerated regression cycles. |
| ISO 26262 Certification Investment | Functional safety compliance opens automotive ADAS verification budgets from BYD and NIO. |
| Electromagnetic Solver Acquisition | Specialist IP integration addresses 5G baseband and radar module design automation gaps. |
| GB Standards Compliance Program | OpenAccess database adaptation satisfies MIIT data format exchange requirements for state projects. |
Research Methodology
Multiple input streams — primary interviews with EDA vendor executives, foundry process engineers, and fabless design house CTOs; secondary validation through MIIT policy filings, SAMR antitrust records, and foundry capex disclosures; plus customs data on semiconductor equipment imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across deployment model, end-user sophistication tier, and application complexity dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level elasticity modeling against foundry node migration roadmaps and MIIT substitution mandate implementation pacing. Cloud adoption curves and automotive functional safety certification timelines served as industry-specific forecast inputs.
Caveats apply where SMIC process technology delays, SAMR enforcement intensity fluctuations, or cross-domain talent scarcity could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Global Product Lifecycle Management Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Australia ICT Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Global Product Design and Development Market