
 Global Interactive Whiteboard (IWB) Market | 2026-2036
Global Interactive Whiteboard (IWB) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interactive Whiteboard (IWB) Market Foresight
Leasing and subscription-based procurement is fragmenting the competitive landscape for interactive whiteboard deployment across institutional buyers. SMART Technologies leverages its captive software-hardware ecosystem to sustain recurring revenue streams in North American K-12 districts. Promethean Limited anchors its position through direct channel control over national education tenders in the United Kingdom and Australia. BenQ Corporation competes aggressively on price-performance ratios for laser projector-integrated systems in Asian commercial markets.
An interactive whiteboard is a large-format touch-sensitive display surface, typically exceeding 55 inches diagonally, that combines digital projection or direct-view LCD/OLED panels with infrared or capacitive sensing layers to capture stylus or finger input for real-time annotation and content manipulation. Its primary commercial purpose centers on collaborative visual communication in pedagogical and enterprise settings, replacing traditional whiteboards and analog projection systems. Touch screen products dominate volume shipments across higher education and corporate training applications, while infrared technology leads installed base due to lower manufacturing cost and proven durability in high-use environments. Portable configurations represent the fastest-growing hardware category as hybrid work models drive demand for reconfigurable meeting spaces in private enterprises and training centers.
The United States Environmental Protection Agency enforces ENERGY STAR certification thresholds that constrain standby power and luminous efficacy for displays deployed in federal agencies and public schools. The European Union's Ecodesign Directive and REACH chemical compliance framework shape material selection and end-of-life recycling obligations for manufacturers selling into European higher education and government sectors. China's Ministry of Education issues mandatory technical specifications for classroom digitization equipment that directly determine product eligibility in provincial procurement cycles. Stakeholders must monitor how evolving interoperability standards between interactive whiteboard operating systems and third-party collaboration platforms will reshape replacement cycles and vendor lock-in dynamics.
Market Dynamics
Leasing and subscription-based procurement is fragmenting the competitive landscape for interactive whiteboard deployment across institutional buyers, compressing traditional hardware-only sales cycles and forcing vendors to build recurring revenue architectures.
Growth Catalysts
- EU Ecodesign requirements:Tightening power-consumption thresholds for classroom and boardroom displays are accelerating replacement of legacy projection systems with energy-efficient direct-view panels in European higher education institutions.
- Corporate training budgets:Enterprise learning and development departments are redirecting capital toward interactive collaboration hardware that supports hybrid workforce engagement models.
- China's tier-one cities:Provincial procurement cycles under the Ministry of Education's mandatory classroom digitization specifications are concentrating demand in Beijing, Shanghai, Shenzhen, and Guangzhou metropolitan education corridors.
Market Restraints
- Semiconductor input volatility:Touch controller ICs and display driver shortages create production scheduling uncertainty for infrared and capacitive sensing layer manufacturers.
- Supply concentration in East Asian panel production:LCD and OLED substrate fabrication clusters in Taiwan and South Korea expose finished goods assembly to geographic risk concentration.
- Technical limitation of ambient light interference:Infrared-based touch systems suffer degraded performance in high-luminance environments, restricting deployment in windowed corporate training rooms without supplemental shading infrastructure.
Strategic Opportunities
- India's metropolitan education corridors:Underpenetrated state-level smart classroom initiatives in Maharashtra, Karnataka, and Tamil Nadu offer expansion pathways for hardware vendors with localized service networks.
- Technology convergence of AI-powered handwriting recognition:Integration of natural language processing with real-time annotation systems is digitizing meeting documentation workflows in enterprise settings.
- Regulatory tailwind from ENERGY STAR specifications:United States federal agency and public school procurement mandates are creating preference premiums for certified low-standby-power displays.
Industry Challenges
- Integration complexity with legacy AV infrastructure:Enterprise IT departments face interoperability testing burdens when connecting new interactive whiteboards to existing video conferencing and room control systems.
- Certification timeline compression:Multi-jurisdictional compliance with REACH chemical frameworks, CE marking, and China's GB standards extends product launch windows by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interactive Whiteboard (IWB) Market |
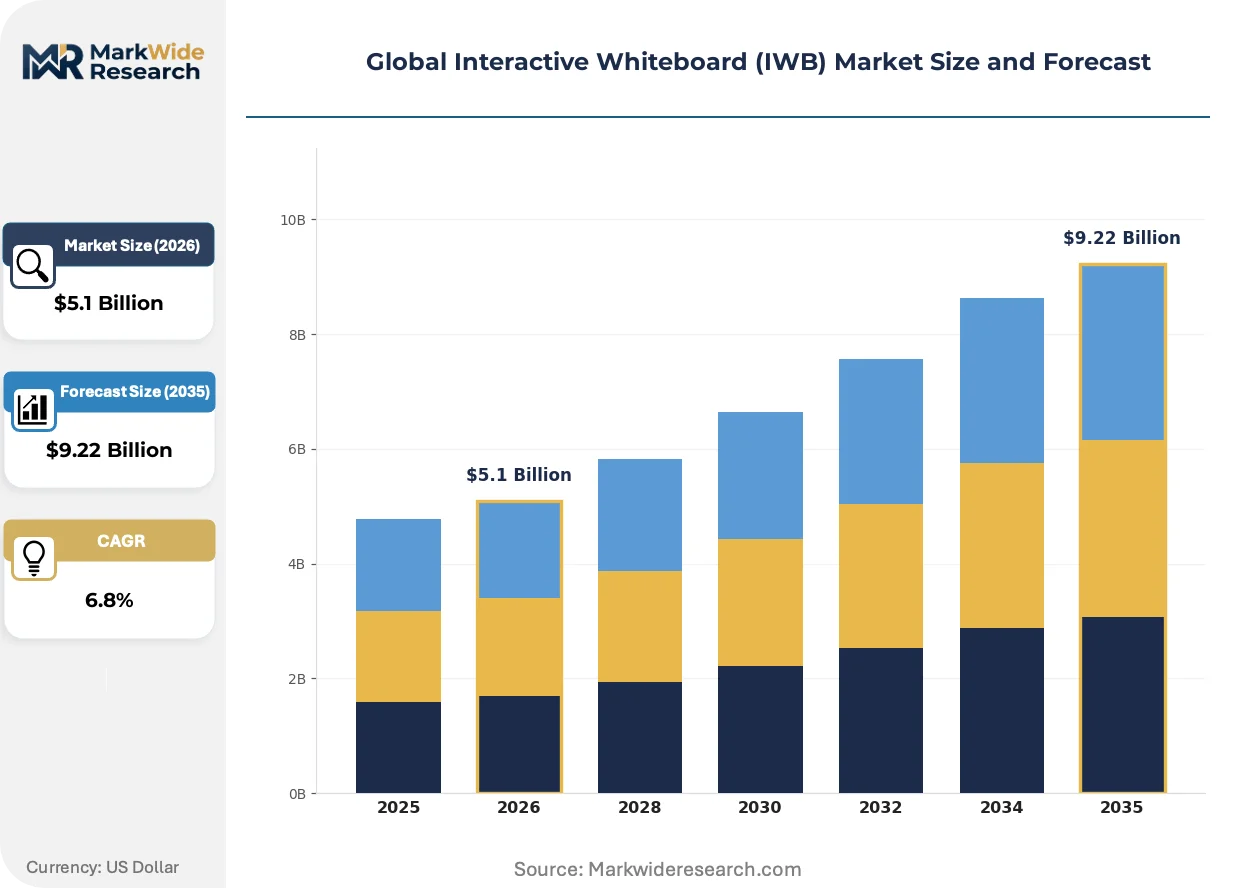
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $9.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touch Screen, Non-Touch Screen, Portable, Fixed, Laser Projector Technology: Infrared, Electromagnetic, Optical, Capacitive, Ultrasonic Application: Corporate Training, Higher Education, K-12 Education, Government, Military End User: Colleges, Training Centers, Defense Institutions, Public Agencies, Private Enterprises |
| Companies Covered | SMART Technologies, Promethean Limited, BenQ Corporation, ViewSonic Corporation, Panasonic Corporation, Hitachi Ltd., Samsung Electronics, Ricoh Company, Boxlight Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interactive Whiteboard (IWB) Market Shifts & Advancements
Three intersecting developments are restructuring how interactive whiteboard value is created and captured: touch sensing architecture evolution, regulatory compliance as product differentiation, and procurement model transformation toward operational expenditure frameworks.
Capacitive and infrared sensing technologies are digitizing annotation capture with sub-5 millisecond latency, enabling seamless multi-user collaboration. Higher education institutions and corporate training centers in North America and Western Europe are adopting these systems at replacement-cycle pace. The structural consequence is compression of single-user projection-centric meeting room designs toward multi-touch native architectures.
REACH chemical compliance and the EU's Ecodesign Directive are mandating material transparency and end-of-life recycling obligations for manufacturers selling into European government and education sectors. Industrial consequence includes reformulation of solder alloys and display coatings to eliminate restricted substances. Higher education procurement teams in Germany, France, and the Netherlands are now screening vendor submissions for circular economy documentation.
Subscription-based hardware-as-a-service contracts are displacing capital expenditure purchasing in North American K-12 districts and British academy trusts. The segment being disrupted is traditional distributor-led equipment sales; managed service providers with bundled software licensing are capturing procurement authority. This shift is most visible in United States federal Title I-funded districts and United Kingdom Department for Education national tender programs.
Global Interactive Whiteboard (IWB) Market Segmentation
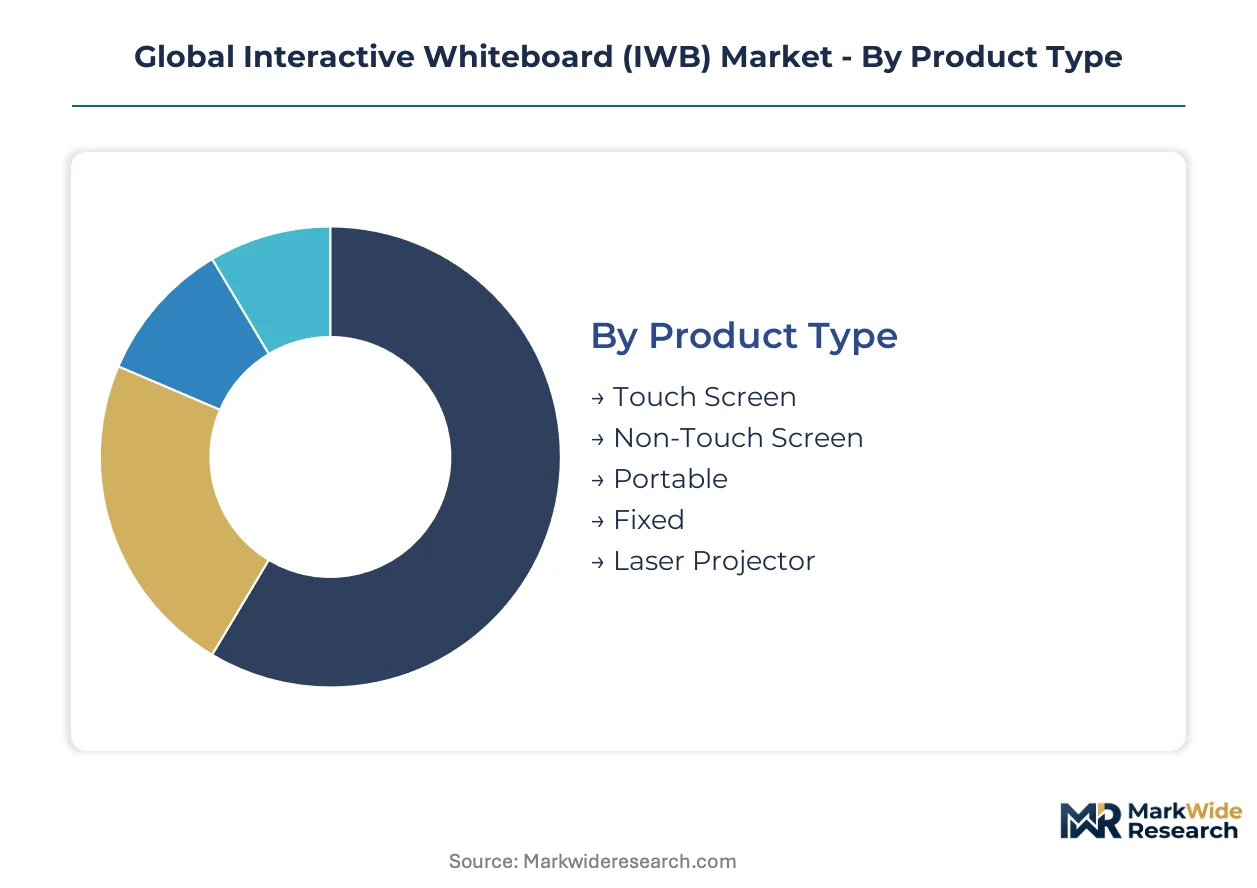
Interactive whiteboard procurement varies sharply across institutional contexts. Product specifications, sensing technologies, and deployment settings each create distinct commercial requirements that vendors must address through targeted portfolio architecture.
Product Type:
Use-case spectrum spans permanent classroom installations to reconfigurable enterprise meeting spaces, with touch sensitivity and mobility emerging as primary purchase criteria.
- Touch Screen:Direct-view LCD or OLED panels with embedded capacitive or infrared sensing layers enable multi-user annotation without peripheral projection. Higher education institutions in Germany and the United States favor these systems for collaborative seminar rooms where durability under continuous student use matters.
- Portable:Lightweight, wheeled or foldable units with integrated computing and wireless connectivity support hybrid workforce models. Training centers in India's Maharashtra and Karnataka states are acquiring these configurations to enable room reconfiguration across multiple corporate client sites.
- Non-Touch Screen:Projection-dependent systems requiring external input devices for annotation.
- Fixed:Wall-mounted permanent installations with hardwired AV infrastructure.
- Laser Projector:Solid-state illumination systems paired with sensing overlays for large-format display.
Established volume favors Touch Screen; emerging adoption favors Portable.
Technology:
Cost tier and performance durability divide procurement patterns across institutional buyers with varying maintenance capabilities and usage intensity.
- Infrared:LED emitter-receiver arrays frame the display perimeter to detect stylus or finger position through interrupted light beams. K-12 districts in the United States select this architecture for its proven 10-year operational lifespan in high-traffic elementary classrooms.
- Capacitive:Transparent conductive oxide layers laminated directly to display glass register touch through electrical field disruption. Corporate training centers in China's Shenzhen and Beijing metropolitan corridors specify these systems for sub-5 millisecond latency in multi-user collaboration scenarios.
- Electromagnetic:Resonant coil arrays embedded behind the surface detect proprietary stylus position and pressure.
- Optical:Camera-based triangulation of pointer position enables large-scale deployment at lower unit cost.
- Ultrasonic:Time-of-flight calculation between stylus emitters and surface microphones determines contact coordinates.
Installed base concentrates in Infrared; steepest expansion trajectory belongs to Capacitive.
Application:
Customer type determines feature prioritization, with pedagogical settings emphasizing durability and enterprise contexts demanding platform interoperability.
- Corporate Training:Enterprise learning and development departments require seamless integration with Microsoft Teams, Zoom, and proprietary LMS platforms. Private enterprises in the United Kingdom and Australia are replacing legacy projection systems with direct-view panels that support hybrid engagement models.
- Higher Education:Universities and colleges prioritize multi-user touch capacity for collaborative pedagogy. Institutions in France and the Netherlands screen vendor submissions for REACH compliance documentation and circular economy certification.
- K-12 Education:Primary and secondary schools mandate ruggedized construction for daily student contact.
- Government:Public sector procurement emphasizes ENERGY STAR certification and total cost of ownership metrics.
- Military:Defense institutions require secure, air-gapped systems with electromagnetic interference shielding.
Budget authority concentrates in Corporate Training; regulatory compliance complexity peaks in Government.
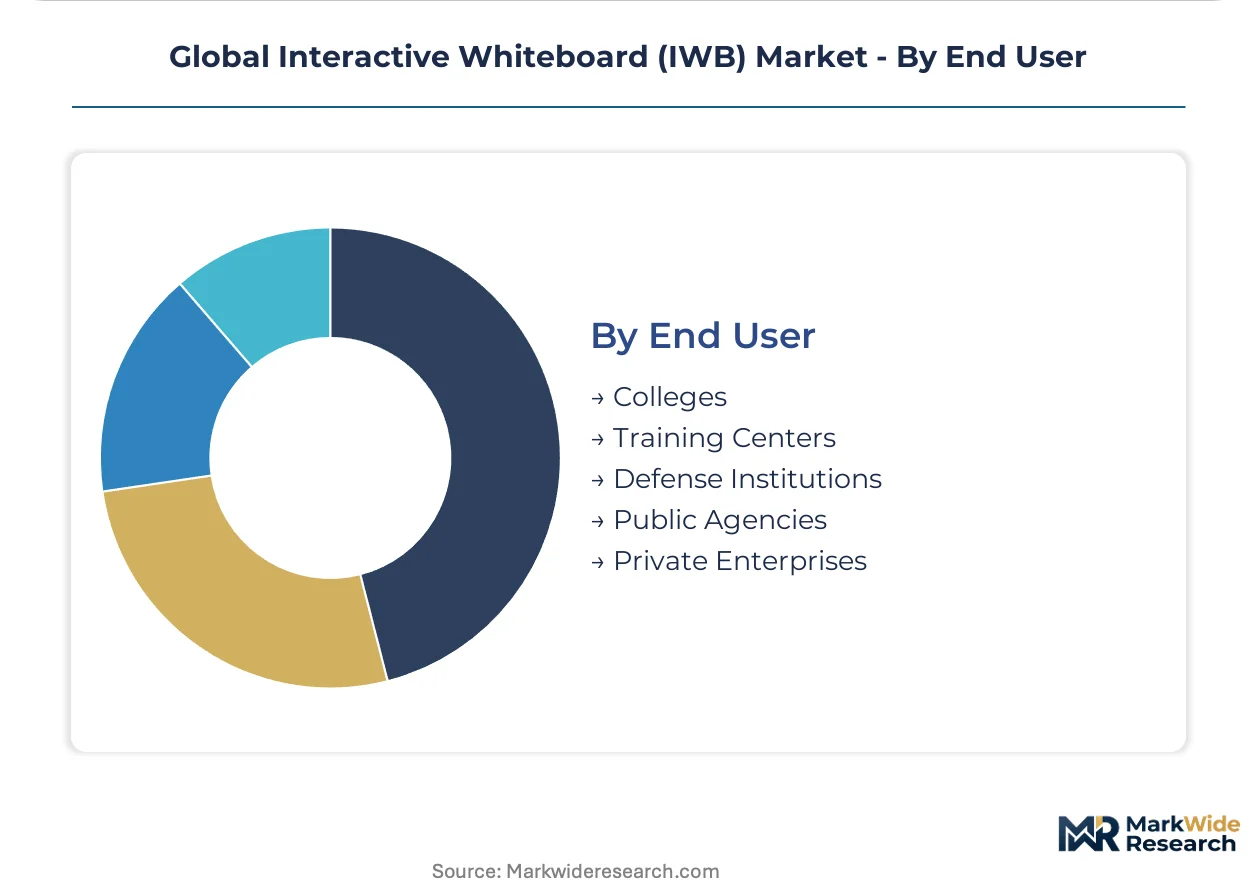
End User:
Volume scale and service network requirements fragment addressable market structure across institutional categories with diverging procurement cycles.
- Training Centers:Commercial learning facilities serving multiple corporate clients demand flexible leasing terms and rapid technical support response. Providers in India's Tamil Nadu corridor are expanding service networks to capture state-level smart classroom initiative tenders.
- Colleges:Post-secondary institutions balance capital expenditure constraints against 15-year facility lifecycle planning. Universities in China's Guangzhou education corridor specify equipment meeting Ministry of Education mandatory technical specifications for classroom digitization.
- Defense Institutions:Military academies and training commands impose security clearance and domestic content requirements.
- Public Agencies:Federal, state, and municipal departments follow competitive bidding rules with extended evaluation periods.
- Private Enterprises:Corporate headquarters and regional offices prioritize software ecosystem compatibility and managed service availability.
Replacement cycle visibility favors Colleges; subscription transition velocity peaks in Private Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in display panel components shape regional competitive positioning, with finished interactive whiteboard assembly gravitating toward markets with strong education procurement pipelines and established AV integration networks.
United States
Federal Title I funding streams and ENERGY STAR procurement mandates from the Environmental Protection Agency drive institutional purchasing in K-12 districts and government agencies. Corporate training departments in technology and financial services sectors are redirecting capital toward hybrid collaboration infrastructure. The Dallas-Fort Worth metroplex anchors a concentration of AV systems integrators serving central U.S. education markets.
Germany
Higher education institutions prioritize REACH-compliant equipment with circular economy documentation for classroom digitization tenders. The Ecodesign Directive enforces stringent standby power thresholds that filter non-compliant projection systems from public procurement. Industrial clusters in Bavaria and Baden-Württemberg host specialized manufacturers of capacitive sensing layers for premium direct-view panels.
China
Ministry of Education mandatory technical specifications determine product eligibility in provincial procurement cycles concentrated in Beijing, Shanghai, Shenzhen, and Guangzhou. Domestic panel fabrication capacity in the Yangtze River Delta reduces import dependency for LCD and OLED substrates. Corporate training centers in Shenzhen metropolitan corridor specify sub-5 millisecond latency systems for multi-user collaboration scenarios.
India
State-level smart classroom initiatives in Maharashtra, Karnataka, and Tamil Nadu create underpenetrated expansion pathways for hardware vendors with localized service networks. Commercial training facilities serving multiple corporate clients demand flexible leasing terms and rapid technical support response. Metropolitan education corridors in Mumbai, Bangalore, and Chennai concentrate procurement authority for both public and private institutional buyers.
United Kingdom
Department for Education national tender programs and British academy trust procurement frameworks accelerate subscription-based hardware-as-a-service adoption. Direct channel control over national education tenders anchors competitive positioning for established vendors. London and Southeast England host the densest concentration of corporate headquarters driving enterprise interactive collaboration demand.
Global Interactive Whiteboard (IWB) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensing layers, display drivers, and touch controller ICs to finished goods assemblers. The vendor base stratifies across three tiers: captive software-hardware ecosystems sustaining recurring revenue, price-performance competitors on laser projector-integrated systems, and managed service providers bundling equipment with software licensing. Two dominant competitive moves are reshaping positioning: direct channel control over national education tenders and geographic expansion of localized service networks to capture state-level procurement cycles.
Within the captive ecosystem tier, SMART Technologies and Promethean Limited exemplify platform-integrated positioning through software-hardware bundling architectures. BenQ Corporation anchors the price-performance vector for laser projector-integrated systems in Asian commercial markets. These three entities occupy distinct competitive spaces without direct overlap in procurement channel strategy or end-user segment focus.
| Leading Market Players |
|---|
| SMART Technologies |
| Promethean Limited |
| BenQ Corporation |
| ViewSonic Corporation |
| Panasonic Corporation |
| Hitachi Ltd. |
| Samsung Electronics |
| Ricoh Company |
| Boxlight Corporation |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta panel fabrication cluster governs substrate availability for direct-view interactive whiteboard systems, translating concentrated LCD and OLED capacity into asymmetric pricing power for finished goods assemblers sourcing from Chinese display manufacturers.
Pricing Analysis
Institutional buyers anchor a subscription-heavy pricing structure across North American K-12 districts and British academy trusts, with three-tier pricing stratification across premium capacitive systems, standard infrared configurations, and economy laser-projector bundles. Certification tiers—ENERGY STAR compliance for federal procurement and REACH documentation for European education tenders—create price premiums of fifteen to twenty percent above uncertified alternatives. Cost compression in entry-level infrared systems intensifies as Taiwanese touch controller IC suppliers expand wafer capacity. Corporate training centers exhibit lowest price sensitivity due to bundled software licensing requirements, while Indian state-level smart classroom initiatives demonstrate acute sensitivity to total cost of ownership metrics.
Supply Chain Analysis
Extended payment terms from sixty to ninety days have become standard practice among Taiwan and South Korean substrate suppliers, tightening working capital requirements for downstream sensing layer integrators. Finished interactive whiteboard assembly draws from concentrated input streams: touch controller ICs from Taiwanese semiconductor foundries, LCD and OLED panels from South Korean and Chinese display manufacturers, and capacitive sensing glass from Japanese specialty coating facilities. Single-source vulnerability in display driver integrated circuits creates exposure to foundry allocation shifts. Distribution runs through AV systems integrators in the Dallas-Fort Worth metroplex for North American education markets and direct channel relationships with national tender programs in the United Kingdom and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-as-a-service contracts for interactive whiteboard deployment are expanding at double the rate of transactional equipment sales, making software licensing attach and managed support services the primary value capture mechanism for vendors across institutional segments.
For Market Incumbents: Harden recurring revenue architectures by deepening captive software-hardware ecosystems against emerging cloud-native collaboration platforms threatening proprietary annotation stacks. Prioritize direct channel control over United Kingdom Department for Education national tenders and United States federal Title I-funded district procurement cycles. Invest in localized service network density across India's Maharashtra and Tamil Nadu corridors to defend against price-performance competitors. For New Entrants and Emerging Players: Portable interactive whiteboard configurations for hybrid corporate training rooms in Southeast Asian commercial hubs represent the most penetrable entry point, with underpenetrated demand in Vietnam and Indonesia's metropolitan education markets offering secondary expansion vectors. Target state-level smart classroom initiatives in Karnataka through flexible leasing terms and rapid technical support response capabilities unavailable from established hardware-only vendors. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant interactive display divisions lacking software ecosystem integration. Five-to-ten year viability hinges on subscription revenue transition velocity rather than hardware shipment volumes. Monitor procurement mandate shifts from China's Ministry of Education as inflection indicators for replacement cycle timing and vendor eligibility criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Revenue Transition | Hardware-as-a-service contracts displace capital expenditure purchasing in North American K-12 districts. |
| Regulatory Certification Investment | ENERGY STAR and REACH compliance creates procurement preference premiums in federal and European education tenders. |
| Localized Service Network Expansion | India's state-level smart classroom initiatives demand rapid technical support response unavailable from distant suppliers. |
| AI-Powered Handwriting Recognition Integration | Natural language processing layers digitize enterprise meeting documentation workflows beyond basic annotation capture. |
| Direct Channel Control | National education tender programs in the United Kingdom and Australia reward vendors with procurement authority capture. |
Research Methodology
Initial hypotheses were tested against primary input from AV systems integrators, K-12 district technology directors, corporate training procurement officers, and higher education facility planners, then refined through secondary validation against SEC filings from display panel manufacturers, United States Environmental Protection Agency ENERGY STAR certification databases, European Commission Ecodesign Directive implementation reports, and China's Ministry of Education classroom digitization procurement specifications. Bottom-up shipment estimates from sensing layer suppliers were triangulated against top-down education budget allocations across institutional buyer segments.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by touch sensitivity and mobility configuration, technology segmentation by infrared versus capacitive sensing architecture, application segmentation across corporate training and higher education contexts, and end user segmentation distinguishing training centers from colleges and private enterprises. CAGRs were derived from replacement cycle analysis calibrated to procurement mandate timelines and software ecosystem upgrade patterns. Forecast inputs included provincial procurement cycle schedules under China's mandatory technical specifications and United States federal funding authorization trajectories for Title I districts.
Macroeconomic conditions sit as an overlay; deviation in education budget appropriations, semiconductor foundry capacity allocation, or trade policy affecting display panel component tariffs would shift the trajectory. Forecasts incorporate documented assumptions regarding interoperability standard evolution and regulatory compliance timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Parking Management Systems Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Dating Services Market
Digital Solutions
Service Lifecycle Management Application Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
China EDA Electronic Design Automation Market
Digital Solutions
File Sharing Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Web Content Management Market