
 Europe Multichannel Order Management Market | 2026-2036
Europe Multichannel Order Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Multichannel Order Management Market Insights
Platform licensing revenue is narrowing relative to implementation services as vendors compete on recurring subscription models. SAP anchors European enterprise deployments through deep ERP integration capabilities. Oracle leverages its cloud infrastructure footprint to sustain competitive positioning in mid-market retail. Brightpearl specializes in native accounting-linkage for UK-based multichannel merchants.
Multichannel order management encompasses software systems that unify inventory visibility, order routing, and fulfillment orchestration across physical stores, online storefronts, and third-party marketplaces through real-time API connectivity and distributed order logic. These platforms process transaction data at sub-second latency to prevent stockouts and enable ship-from-store, curbside pickup, and drop-shipping workflows. Cloud-based deployment leads segment adoption as retailers prioritize elastic capacity for seasonal demand spikes, while API-based integration grows fastest as merchants dismantle monolithic legacy stacks. Services revenue occupies the deepest margin pool due to complex customization requirements for warehouse management system linkages.
The EU AI Act and GDPR impose algorithmic transparency and data residency mandates that shape vendor architecture decisions across France, Germany, and the Netherlands. ECHA chemical tracking obligations for textile and electronics retailers indirectly tighten supply chain traceability requirements that order management platforms must support. Stakeholders should monitor how the CSRD sustainability disclosure rules will force inventory-carbon accounting into core platform roadmaps.
Market Dynamics
Cloud-native API architectures are dismantling monolithic legacy stacks across European retail, as merchants prioritize elastic capacity for seasonal demand spikes and real-time inventory orchestration.
Growth Catalysts
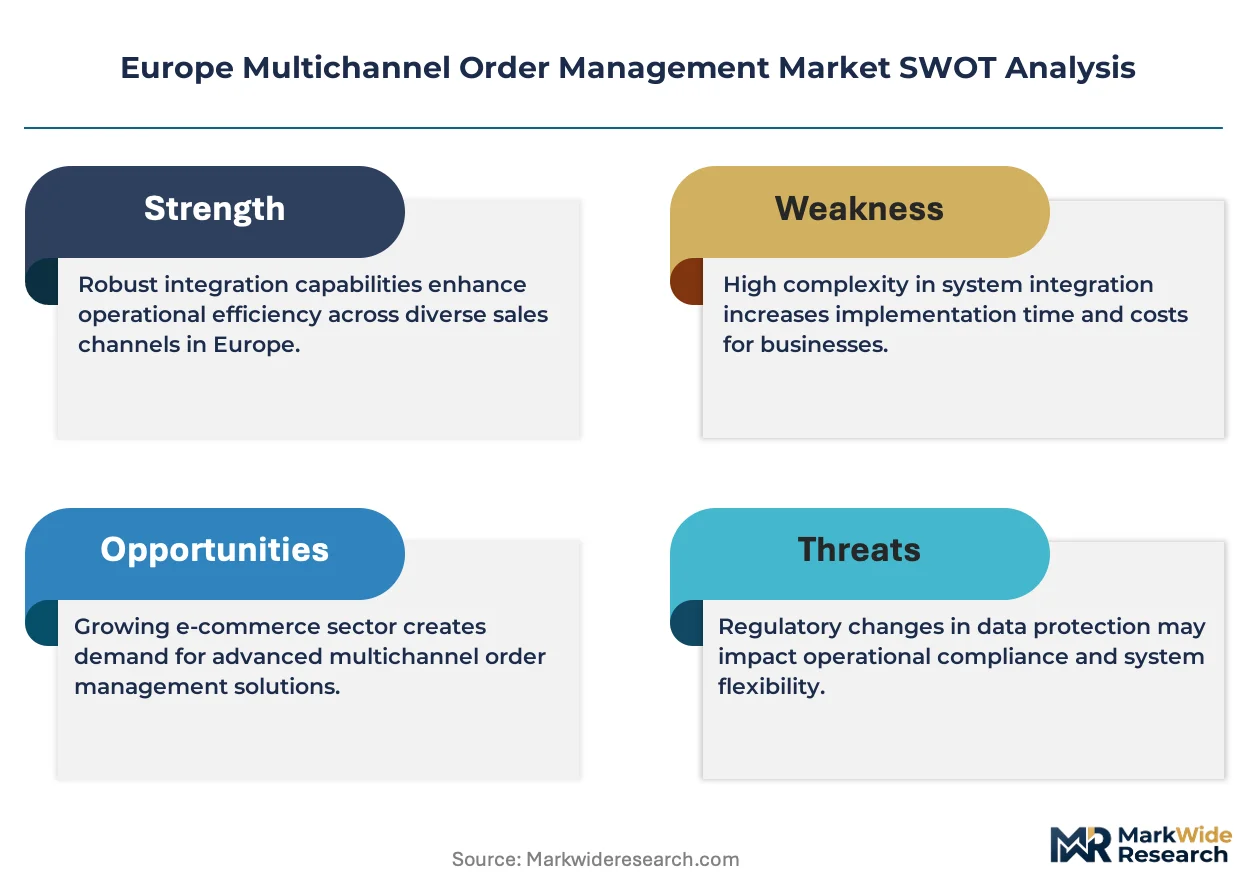
- EU AI Act compliance mandates:Algorithmic transparency requirements are accelerating migration toward auditable order routing engines in France and Germany.
- Fashion retail digitization:German and French apparel merchants are deploying distributed order logic to enable ship-from-store and curbside fulfillment workflows.
- GDPR data residency rules:Sovereign cloud requirements are pulling order management workloads toward EU-based infrastructure providers.
Market Restraints
- Warehouse management system integration costs:Complex customization for legacy WMS linkages consumes 40-60% of implementation budgets.
- Skills concentration in London and Berlin:Shortage of API architects and cloud-native developers limits deployment velocity outside these clusters.
- ECHA chemical tracking obligations:Textile and electronics retailers face indirect supply chain traceability mandates that extend platform scope.
Strategic Opportunities
- Netherlands fulfillment hub expansion:Rotterdam and Amsterdam logistics corridors offer underpenetrated mid-market retail segments.
- CSRD sustainability disclosure alignment:Inventory-carbon accounting requirements will embed emissions tracking into core platform roadmaps.
- Edge computing and 5G convergence:Sub-10ms latency at store-level nodes enables real-time stock rebalancing without central cloud dependency.
Industry Challenges
- Monolithic ERP decoupling complexity:SAP-dependent enterprises face multi-year migration timelines to API-first architectures.
- GDPR Article 30 record-keeping:Processing activity documentation for order data flows imposes ongoing operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Multichannel Order Management Market |
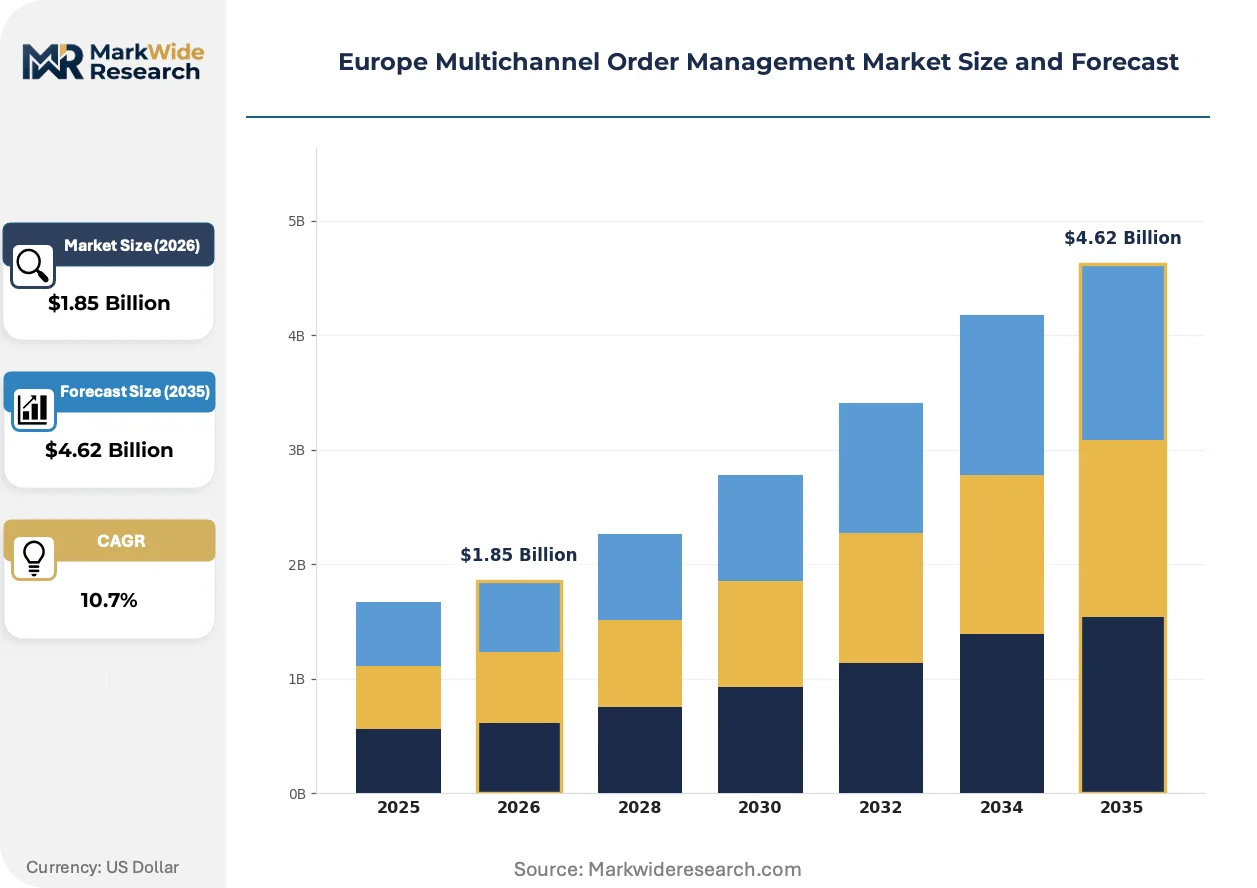
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.62 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
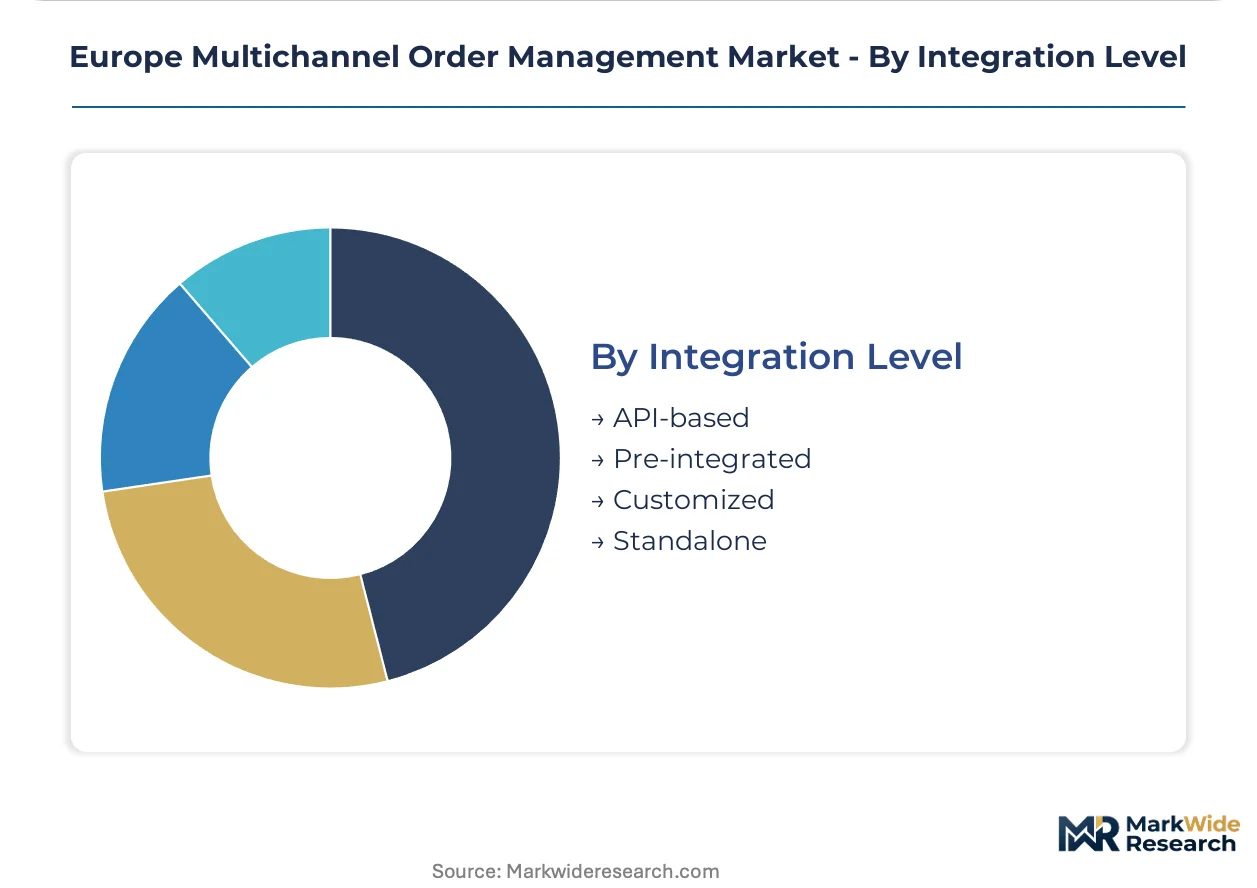
| Segmentation | Product Type: Software, Platform, Hardware, Services End User: Retailers, E-commerce Companies, Wholesalers, Distributors Deployment: Cloud-based, On-premises, Hybrid, Managed Services Integration Level: API-based, Pre-integrated, Customized, Standalone |
| Companies Covered | SAP, Brightpearl, Oracle, Salesforce, Shopify, IBM, Manhattan Associates, Blue Yonder, Zoho, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Multichannel Order Management Market Trends and Innovations
API-first composable commerce is replacing rigid suite architectures, enabling merchants to swap individual order management functions without platform lock-in.
Headless order orchestration engines are collapsing the traditional boundary between e-commerce platforms and warehouse management systems. Mid-market retailers in the United Kingdom are adopting microservices-based routing logic at twice the pace of continental peers. This architectural shift is collapsing vendor switching costs and compressing implementation cycles from 18 months to under 6 months.
The EU AI Act's risk classification framework is forcing algorithmic audit trails for automated order routing decisions. French regulators through CNIL are already inspecting retail AI systems for discriminatory geographic fulfillment patterns. High-volume fashion merchants serving multiple EU markets face the steepest compliance burdens and are pre-emptively deploying explainable AI modules.
Unified commerce procurement is consolidating vendor selection around platforms that natively span physical and digital channels. British multichannel merchants are rejecting point solutions in favor of end-to-end suites with embedded accounting linkages. This preference shift is most visible among UK-based mid-market apparel and homeware retailers with 20-100 store footprints.
Europe Multichannel Order Management Market Segmentation
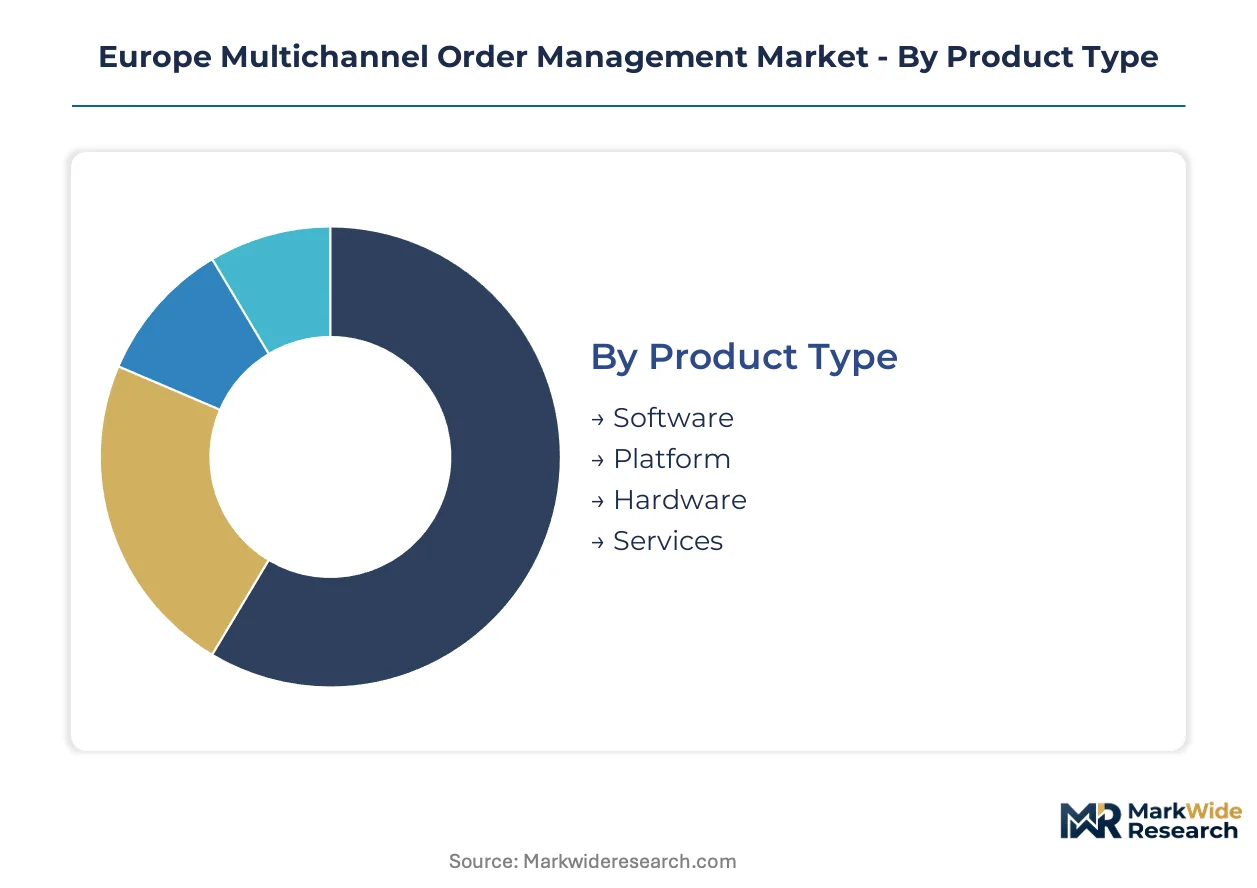
Order management complexity varies dramatically across deployment modes and integration architectures, driving divergent margin structures and vendor selection criteria. Retailers in Germany and France prioritize segments that minimize post-implementation service dependency while satisfying EU AI Act audit requirements.
Product Type:
After-sales service intensity distinguishes these segments, with implementation and ongoing support obligations consuming disproportionate vendor resources relative to license revenue.
- Software:Licensed order routing engines with embedded inventory allocation algorithms process transaction data at sub-second latency. German fashion retailers concentrate demand here as they dismantle monolithic ERP stacks for GDPR-compliant API architectures.
- Platform:Cloud-native orchestration layers unify storefront, marketplace, and fulfillment node visibility through distributed microservices. French apparel merchants deploy these to enable ship-from-store workflows while maintaining algorithmic audit trails under CNIL supervision.
- Hardware:Edge computing nodes and in-store fulfillment terminals with 5G connectivity.
- Services:Implementation consulting, WMS integration, and compliance documentation support.
By volume, Software leads. By growth pace, Platform is ahead.
End User:
Customer procurement sophistication determines solution complexity, with mid-market retailers demanding pre-configured templates while enterprise buyers insist on customization.
- Retailers:Brick-and-mortar chains with 20-100 store footprints require unified inventory visibility across physical and digital channels. UK-based mid-market apparel and homeware merchants drive adoption of end-to-end suites with embedded accounting linkages.
- E-commerce Companies:Pure-play digital merchants prioritize elastic capacity for seasonal demand spikes through cloud-native deployment. Dutch fulfillment hub operators in Rotterdam and Amsterdam corridors represent underpenetrated expansion targets.
- Wholesalers:B2B distributors managing bulk order flows with complex pricing tiers.
- Distributors:Multi-brand aggregators requiring cross-supplier inventory orchestration.
Retailers capture the deepest revenue pool. E-commerce Companies expand most quickly.
Deployment:
Infrastructure sovereignty requirements under GDPR Article 30 are reshaping hosting decisions, with data residency mandates favoring EU-based providers.
- Cloud-based:Elastic subscription models with sovereign EU data centers satisfy GDPR processing activity documentation requirements. German and French enterprises accelerate migration here to offload compliance overhead to vendors.
- On-premises:Legacy installations within retailer-owned facilities persist among SAP-dependent enterprises facing multi-year decoupling timelines.
- Hybrid:Split architectures retaining sensitive order data on-premises while routing fulfillment logic through cloud nodes.
- Managed Services:Fully outsourced operations with vendor assumption of CSRD sustainability disclosure alignment.
Cloud-based dominates current installations. Hybrid is gaining share fastest as transitional architecture.
Integration Level:
Technical architecture choices directly determine implementation duration and switching costs, with API-first approaches collapsing traditional 18-month deployment cycles.
- API-based:Composable microservices enabling modular function swaps without platform lock-in. UK mid-market retailers adopt these at twice continental European pace, compressing implementation to under six months.
- Pre-integrated:Vendor-curated connector libraries for common ERP and WMS combinations.
- Customized:Bespoke linkages consuming 40-60% of implementation budgets for legacy WMS integration.
- Standalone:Disconnected order management requiring manual data reconciliation between systems.
API-based leads technology roadmap investments. Pre-integrated solutions appeal to cost-constrained mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European markets. German buyers prioritize total cost of ownership over subscription rates. French and UK merchants accept premium pricing for compliance-ready platforms.
Germany
Enterprise fashion retailers and automotive parts distributors drive demand for algorithmic order routing with embedded audit trails. The EU AI Act's high-risk system classification pushes vendors toward explainable AI architectures. Berlin and Munich host the densest concentration of SAP-dependent enterprises undergoing multi-year decoupling toward API-first stacks.
United Kingdom
Mid-market apparel and homeware merchants with 20-100 store footprints demand end-to-end suites with native accounting linkages. GDPR Article 30 processing activity documentation shapes vendor selection toward sovereign cloud providers. London and Birmingham logistics corridors concentrate implementation expertise and cloud-native developer talent.
France
Luxury fashion houses and cosmetics brands require distributed order logic enabling ship-from-store and curbside fulfillment. CNIL inspections of retail AI systems for discriminatory geographic patterns accelerate explainable module deployment. The Île-de-France region anchors demand as Paris-based merchants expand unified commerce procurement.
Netherlands
Fulfillment hub operators in Rotterdam and Amsterdam corridors represent underpenetrated mid-market segments seeking elastic cloud capacity. ECHA chemical tracking obligations for textile and electronics retailers tighten supply chain traceability requirements. Dutch merchants prioritize platforms with embedded inventory-carbon accounting ahead of CSRD sustainability disclosure alignment.
Italy
Luxury leather goods and furniture manufacturers seek order orchestration bridging wholesale and direct-to-consumer channels. CE marking and product traceability mandates extend platform scope into supplier quality documentation. Milan and Turin industrial clusters concentrate demand for hybrid deployments retaining sensitive order data on-premises.
Europe Multichannel Order Management Market Competitive Landscape
Capability concentration sits with cloud-native specialists; scale advantage sits with ERP-anchored incumbents. The market exhibits tiered structure with enterprise suite vendors, vertical specialists, and emerging API-first platforms occupying distinct competitive positions. Three archetypes dominate: ERP-integrated incumbents leveraging existing customer relationships, vertical specialists targeting mid-market retail segments, and composable commerce platforms dismantling monolithic stacks. Dominant competitive moves include strategic partnerships with warehouse management system vendors and geographic expansion through EU sovereign cloud infrastructure.
Within the ERP-integrated tier, SAP and Oracle represent scale-driven positions anchored by deep enterprise penetration. Brightpearl exemplifies vertical specialization, occupying a position among UK-focused mid-market merchants requiring native accounting connectivity. These three names illustrate how competitive positioning fragments across capability vectors rather than consolidating around uniform platform architectures.
| Leading Market Players |
|---|
| SAP |
| Brightpearl |
| Oracle |
| Salesforce |
| Shopify |
| IBM |
| Manhattan Associates |
| Blue Yonder |
| Zoho |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure providers in Ireland and Germany anchor the upstream compute layer, concentrating margin capture in data residency-compliant hosting tiers while implementation services absorb downstream pricing pressure from WMS integration complexity.
Pricing Analysis
Implementation and ongoing support services drive lifetime value, with recurring subscription models displacing perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ERP integration depth and compliance module requirements. Pricing pressure stems from vendor competition on API-first architectures as cloud-native entrants compress margins. Mid-market retailers in the United Kingdom exhibit highest price sensitivity, while German enterprises prioritize total cost of ownership over subscription rates.
Supply Chain Analysis
Upstream software development talent concentrates in Germany, the United Kingdom, and the Netherlands, with API architects and cloud-native developers forming the critical input layer. Vendor ecosystems draw from hyperscaler infrastructure, open-source middleware, and specialized WMS connector libraries. Single-source vulnerability sits with SAP-dependent enterprises facing multi-year decoupling timelines. Distribution runs through direct vendor sales, systems integrator partnerships, and cloud marketplace procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-market retailers consolidating vendor selection around end-to-end suites, fragmenting procurement across accounting-linked platforms rather than point solutions.
For Market Incumbents: Build switching-cost moats through deep ERP integration and embedded compliance documentation. Defend against API-first challengers by accelerating sovereign cloud certification for GDPR Article 30 processing activity requirements. Prioritize vertical integration into WMS connector development to capture implementation margin pools. For New Entrants and Emerging Players: Mid-market apparel merchants in the Netherlands and Italy represent the most penetrable entry point, with underpenetrated fulfillment hub operators seeking elastic cloud capacity. Target explainable AI modules for French luxury houses facing CNIL inspection risk. Lead with six-month implementation guarantees against incumbent eighteen-month timelines. For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with native accounting linkages and API-first composable platforms dismantling monolithic stacks. Long-term viability favors vendors embedding CSRD sustainability disclosure alignment into core roadmaps. Watch for EU AI Act enforcement actions against high-risk order routing systems as inflection indicator for compliance-ready platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Migration | Enables modular function swaps for German fashion retailers dismantling SAP-dependent stacks. |
| Sovereign Cloud Certification | Satisfies GDPR data residency mandates pulling workloads toward EU-based infrastructure providers. |
| WMS Connector Development | Captures implementation margin pools consumed by complex legacy warehouse system linkages. |
| Explainable AI Module Deployment | Preempts CNIL inspection risk for French luxury houses under EU AI Act risk classification. |
| CSRD Alignment Investment | Embeds inventory-carbon accounting ahead of mandatory sustainability disclosure requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vendor financial disclosures, EU regulatory filings, and cloud infrastructure capex reports. Interviews with CTOs at German fashion retailers, integration specialists in London logistics corridors, and procurement officers at Dutch fulfillment hubs inform demand-side validation. Secondary sources include SEC filings of publicly traded software vendors, hyperscaler regional infrastructure announcements, and CNIL enforcement action records. Bottom-up sizing of deployment modes and integration architectures triangulates against top-down market aggregation.
Forecast inputs span cloud-based and hybrid deployment models, API-based versus pre-integrated architectures, and retailer versus e-commerce company end-use segments across the analysis window. CAGRs derive from segment-level growth rate application weighted by current revenue pool distribution. Industry-specific inputs include EU AI Act implementation timelines, GDPR Article 30 compliance cost estimates, and WMS integration project duration benchmarks.
Practitioners should monitor EU AI Act enforcement patterns and CSRD disclosure rule finalization for early signals of platform roadmap priority shifts. Cross-checking against hyperscaler European infrastructure expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Converter Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Virtual Desktop Infrastructure (VDI) Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Session Replay Software Market
Digital Solutions
File Sharing Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Cloud Service Assurance Market