
 Load Balancer Market | 2026-2036
Load Balancer Market Size, Share, and Industry Trends Forecast 2026-2036
Load Balancer Market Intelligence
Buyer consolidation among hyperscale cloud operators is repositioning procurement leverage toward volume-driven hardware and software load balancer contracts. Amazon Web Services leverages its captive infrastructure scale to negotiate custom silicon and software licensing terms. F5 sustains technology leadership in application delivery controllers through deep R&D investment in SSL/TLS offloading and DDoS mitigation. Cisco Systems anchors enterprise on-premises deployments with integrated networking and security portfolios.
A load balancer distributes incoming network traffic across multiple servers to prevent overload, optimize resource utilization, and ensure high availability through algorithms such as round-robin, least connections, and IP hash routing. Cloud-based load balancers now dominate new deployments as organizations migrate from hardware appliances to elastic, API-driven traffic management. The hybrid cloud deployment model represents the fastest-expanding segment as enterprises maintain sensitive workloads on-premises while bursting to public cloud during peak demand. IT services end users generate the largest revenue pool, though BFSI institutions command premium pricing for compliance-certified application delivery controllers.
FCC network reliability mandates and NIST cybersecurity frameworks shape product requirements for US-deployed load balancers, while GDPR and the EU AI Act drive European demand for traffic solutions with audit logging and data residency controls. ISO 27001 certification has become a baseline market access requirement for vendors serving regulated industries. Stakeholders must monitor how sovereign cloud regulations fragment procurement standards across national boundaries.
Market Dynamics
Hyperscale cloud consolidation is compressing procurement cycles and forcing load balancer vendors toward API-native, elastic licensing models that displace perpetual hardware appliance sales.
Growth Catalysts
- FCC network reliability mandates:US carriers must deploy redundant traffic management infrastructure, accelerating hardware refresh cycles among telecommunications operators.
- Hybrid cloud burst patterns:Enterprises maintain sensitive transaction processing on-premises while routing peak e-commerce traffic to AWS, Azure, and Google Cloud elastic load balancers.
- EU AI Act audit requirements:European financial institutions demand application delivery controllers with embedded packet inspection logging to demonstrate algorithmic decision transparency.
Market Restraints
- Custom silicon dependency:AWS Graviton and Google Axion processor development concentrates advanced load balancer chip sourcing within captive cloud provider supply chains.
- SSL/TLS certificate complexity:Shortened certificate lifespans under CA/Browser Forum mandates inflate operational overhead for enterprises managing thousands of endpoints.
- IPv6 migration friction:Legacy hardware appliances lack native dual-stack support, forcing costly forklift upgrades for federal contractors under OMB IPv6-only directives.
Strategic Opportunities
- India data center construction:MeitY data localization rules and PLI scheme incentives attract hyperscaler regions in Mumbai, Chennai, and Hyderabad.
- Edge computing convergence:5G MEC deployments integrate containerized load balancers with Kubernetes orchestration at cellular base stations.
- API gateway unification:Microservices architectures consolidate traffic management, authentication, and rate limiting into single control planes.
Industry Challenges
- Platform engineering talent scarcity:Site reliability engineers with Istio, Envoy, and NGINX configuration expertise command premium compensation.
- ISO 27001 certification timelines:Vendors serving BFSI and healthcare verticals face 12-18 month audit cycles before market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Load Balancer Market |
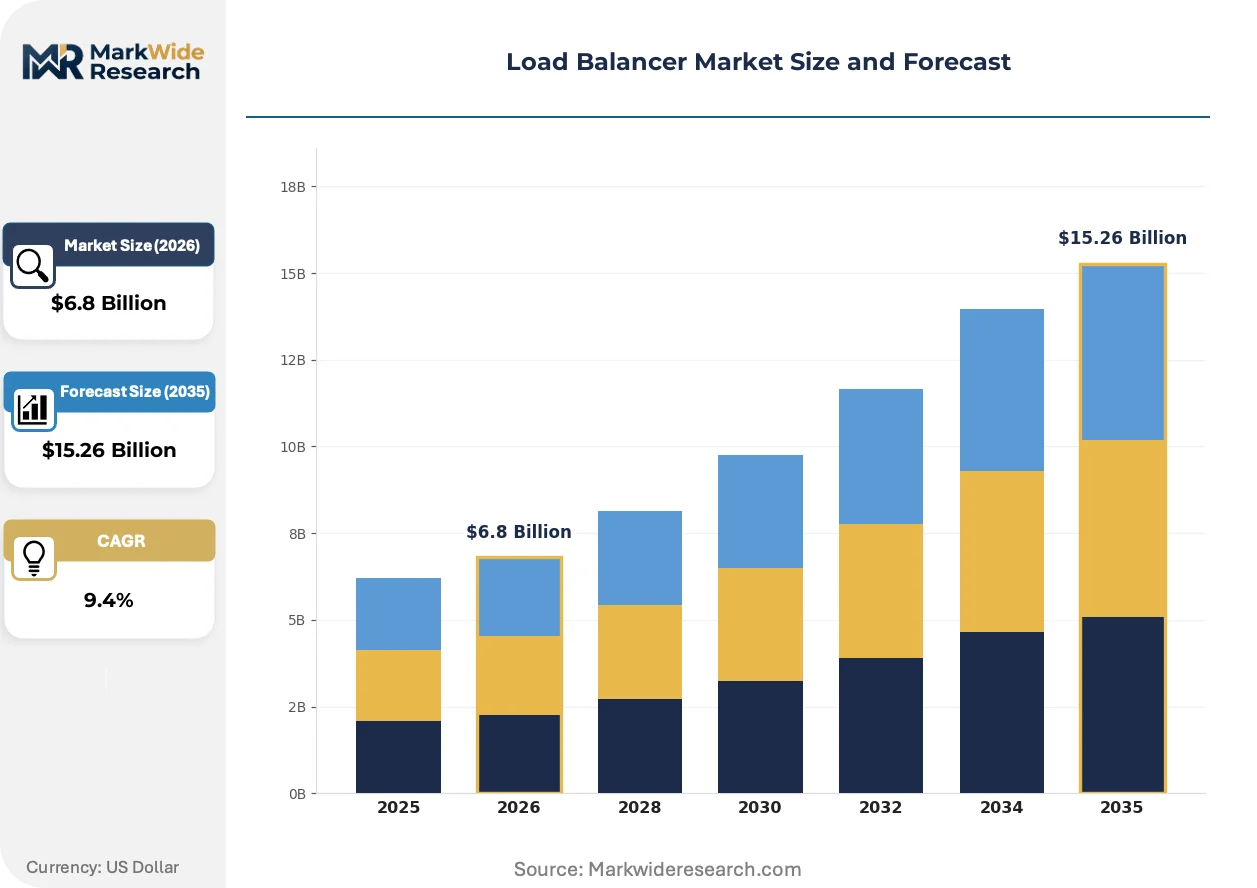
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Load Balancers, Software Load Balancers, Cloud-Based Load Balancers, Application Delivery Controllers Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud End User: IT Services, Telecommunications, BFSI, Retail Service Type: Managed Services, Professional Services, Consulting Services, Support Services |
| Companies Covered | Citrix Systems, Google Cloud, Amazon Web Services, Nginx, HAProxy Technologies, Cisco Systems, Microsoft Azure, A10 Networks, F5, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Load Balancer Market Strategic Shifts & Innovations
Software-defined traffic management is displacing hardware-centric deployment models, with Kubernetes-native service meshes and AI-driven autoscaling algorithms now defining competitive differentiation among infrastructure vendors.
Envoy proxy and Istio service mesh architectures are expanding into multi-cluster Kubernetes environments as the default east-west traffic control layer. Platform engineering teams at Fortune 500 retailers and SaaS providers adopt these technologies during cloud-native replatforming initiatives. This shift is expanding into adjacent observability and security budgets as service mesh vendors bundle distributed tracing and zero-trust mTLS capabilities.
GDPR Article 32 security requirements and the EU AI Act risk management framework mandate granular traffic logging for AI inference endpoints processing personal data. German automotive manufacturers and French banking consortia now require application delivery controllers with immutable audit trails and EU-sovereign data residency controls. Vendors are responding with region-locked software deployments and Bring Your Own Key encryption models.
Consumption-based licensing is replacing perpetual appliance purchases as cloud service providers and large enterprises negotiate elastic commit contracts tied to actual throughput metrics. Systems integrators and managed service providers capture margin by unbundling professional services from software licensing. This pattern is most pronounced in Germany and India, where IT outsourcing specialists package load balancer operations into broader infrastructure management agreements.
Load Balancer Market Segmentation
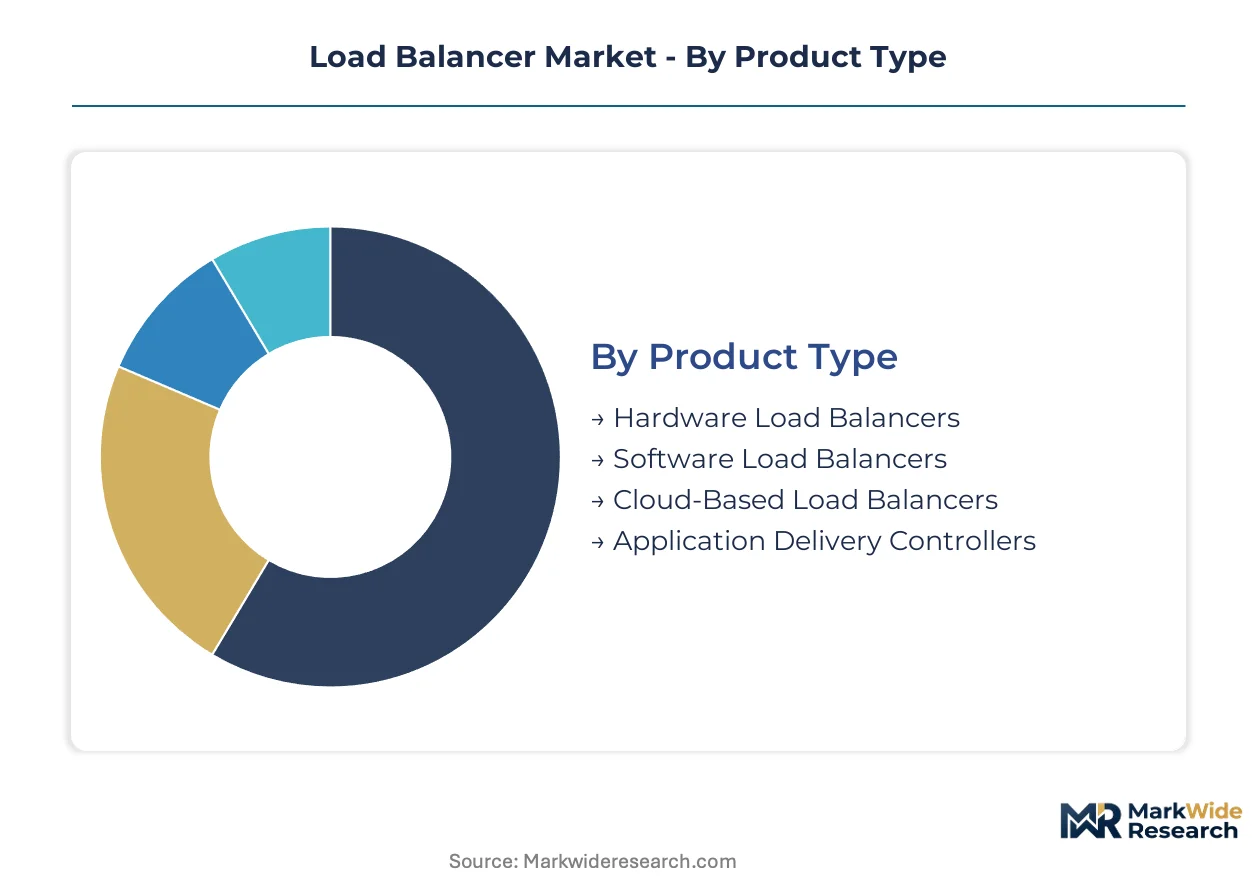
Load balancer procurement patterns diverge sharply by infrastructure maturity, compliance exposure, and cloud-native adoption velocity. Understanding these segment boundaries reveals where pricing power concentrates and which technology transitions threaten incumbent positions.
Product Type:
Hardware buyers prioritize deterministic latency and FIPS 140-2 certification; software purchasers optimize for DevOps velocity and API programmability.
- Hardware Load Balancers:Purpose-built appliances with dedicated SSL/TLS offload processors and redundant power supplies. Financial exchanges in Frankfurt and Chicago deploy these for sub-millisecond transaction consistency under MiFID II and SEC market access rules.
- Software Load Balancers:Deployed as virtual machines or bare-metal binaries on commodity x86 servers. Indian IT services exporters in Bangalore and Hyderabad favor these for data center consolidation under MeitY localization mandates.
- Cloud-Based Load Balancers:Consumed as metered infrastructure services with autoscaling integration.
- Application Delivery Controllers:Integrated platforms combining traffic management with web application firewalls and bot mitigation.
Hardware load balancers lead volumes today; cloud-based deployments are gaining share fastest.
Deployment Model:
Cost structure and data sovereignty requirements fragment deployment choices across regulated and unregulated workloads.
- On-Premises:Dedicated infrastructure within enterprise-owned facilities. German automotive manufacturers maintain on-premises application delivery controllers for CAD file repositories subject to ITAR and EU dual-use export controls.
- Hybrid Cloud:Orchestrated workloads spanning private infrastructure and burst capacity to public cloud. US retailers route Black Friday traffic to AWS Elastic Load Balancing while keeping payment card data in colocated private cages.
- Public Cloud:Fully managed services operated by hyperscale providers.
- Private Cloud:Single-tenant cloud infrastructure with dedicated hardware isolation.
On-premises deployments retain the largest installed base; hybrid cloud configurations are expanding most quickly.
End User:
Compliance certification requirements and traffic volatility patterns create distinct procurement behaviors across verticals.
- IT Services:Global system integrators and managed service providers delivering infrastructure operations to enterprise clients. Accenture and TCS operations in India consume elastic load balancer capacity for multi-tenant SaaS hosting platforms.
- BFSI:Banks, insurers, and capital markets firms with stringent audit and resilience mandates. French banking consortia now require application delivery controllers with immutable packet logs under GDPR Article 32 and EU AI Act algorithmic transparency rules.
- Telecommunications:Mobile and fixed-line carriers subject to network reliability regulations.
- Retail:Omnichannel merchants with extreme demand seasonality.
IT Services generates the largest revenue pool; BFSI commands the steepest pricing premiums.
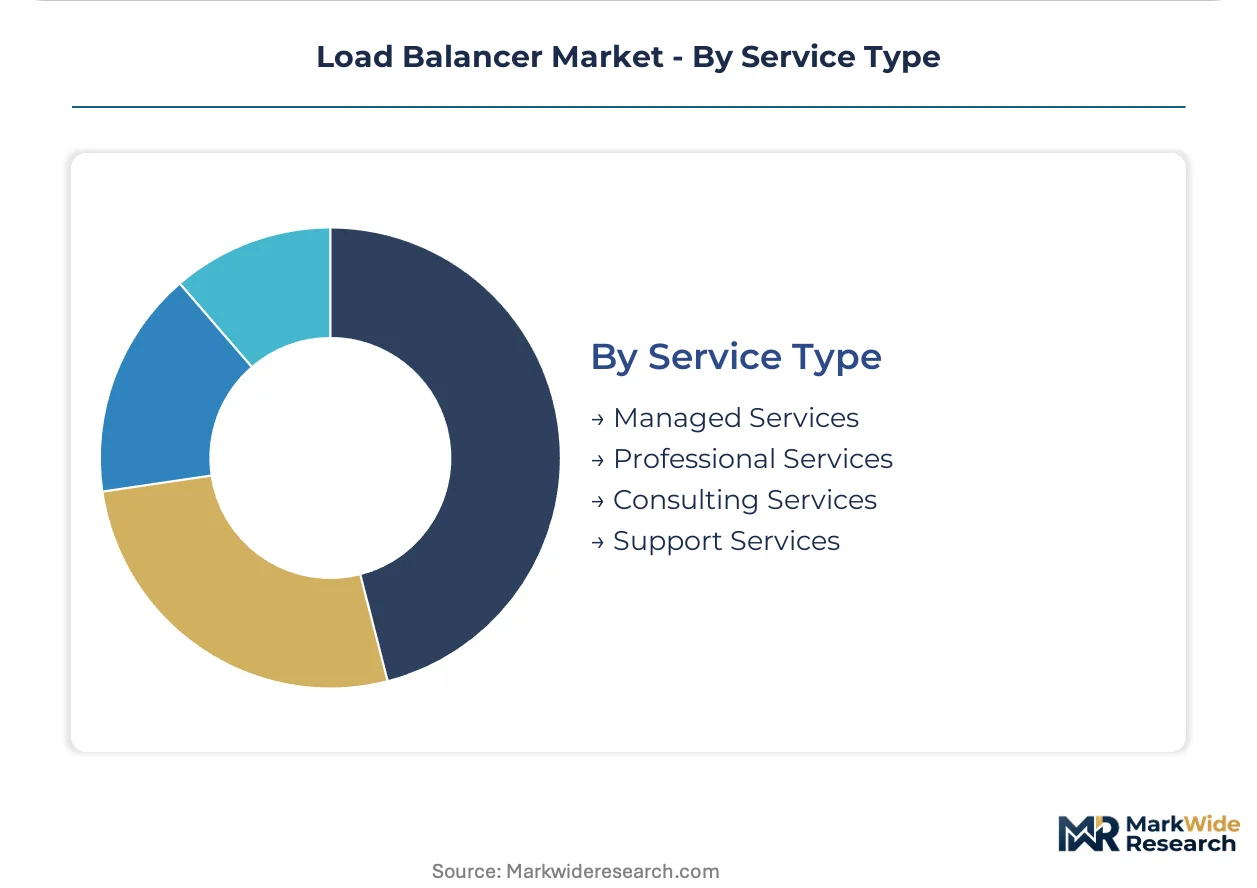
Service Type:
Margin capture shifts from perpetual licenses toward recurring operational support as cloud migration accelerates.
- Managed Services:Third-party operation of load balancer infrastructure including patching, certificate rotation, and capacity planning. German Mittelstand manufacturers outsource entire application delivery controller stacks to Frankfurt-based MSPs to address ISO 27001 certification gaps.
- Professional Services:Implementation, migration, and integration projects. Indian system integrators bundle professional services with software load balancer deployments for US-headquartered SaaS providers establishing Mumbai regions.
- Consulting Services:Architecture design and vendor selection advisory.
- Support Services:Break-fix maintenance and technical escalation.
Managed services dominate new contract value; professional services attach rates are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
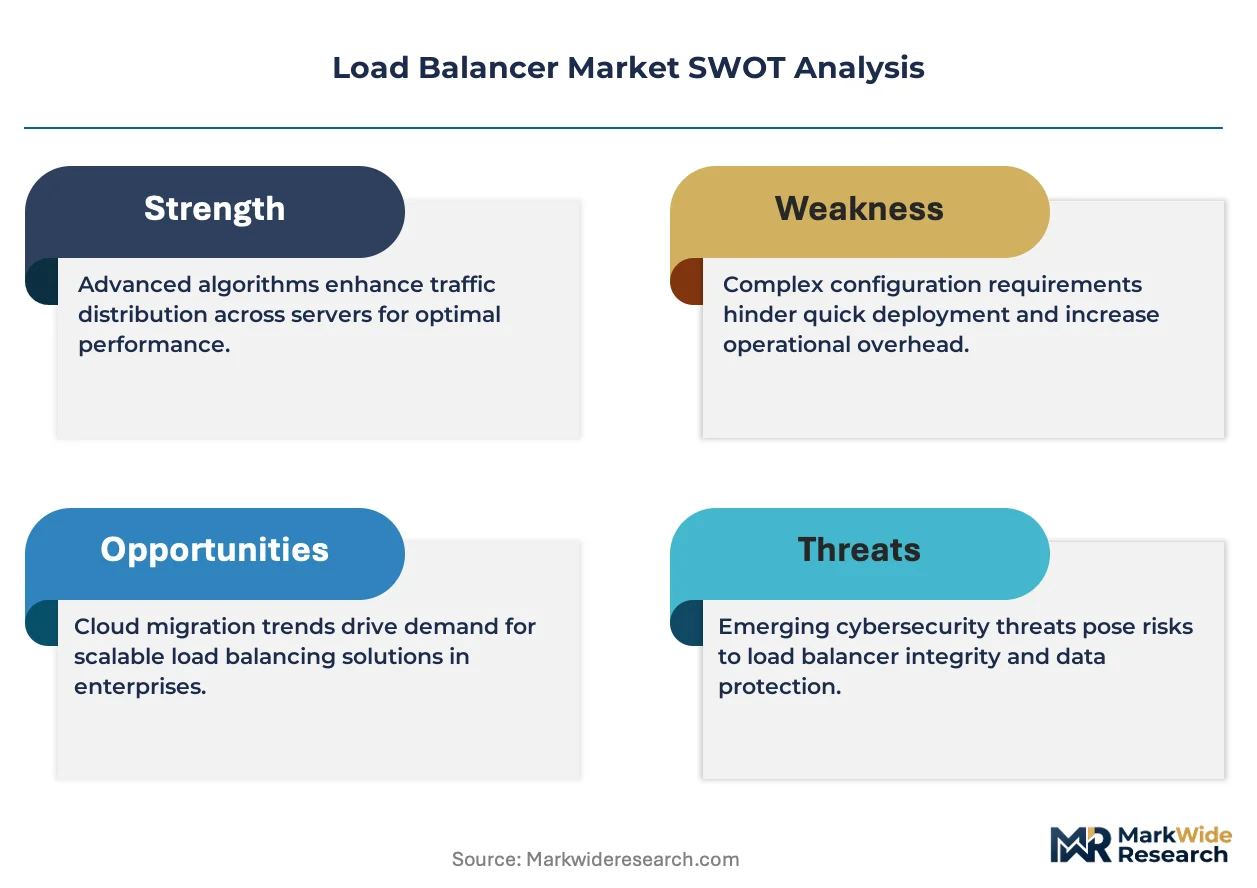
The United States generates premium pricing for compliance-certified hardware, while India captures volume growth through data center localization mandates. Germany anchors European demand with stringent regulatory frameworks. These three markets concentrate procurement leverage among distinct buyer archetypes.
United States
FCC network reliability mandates and NIST cybersecurity frameworks drive carrier infrastructure refresh cycles. Federal contractors face OMB IPv6-only directives that obsolete legacy hardware appliances. Hyperscale cloud regions in Northern Virginia, Oregon, and Ohio negotiate custom silicon sourcing terms with captive supply chains.
Germany
GDPR Article 32 security requirements and the EU AI Act risk management framework mandate immutable audit trails for financial institutions. German automotive manufacturers in Stuttgart and Munich maintain on-premises application delivery controllers for CAD repositories under ITAR and dual-use export controls. Frankfurt-based MSPs package managed load balancer operations for Mittelstand manufacturers.
India
MeitY data localization rules and PLI scheme incentives attract hyperscaler regions in Mumbai, Chennai, and Hyderabad. Indian IT services exporters in Bangalore favor software load balancers for multi-tenant SaaS hosting platforms. System integrators bundle professional services with deployments for US-headquartered providers establishing Mumbai regions.
United Kingdom
Financial services regulators in London require granular traffic logging for algorithmic trading infrastructure under MiFID II transparency rules. UK retailers route peak e-commerce traffic to elastic cloud load balancers while maintaining payment data in colocated private cages. The Thames Valley technology corridor concentrates managed service provider operations.
Japan
METI industrial digitization programs accelerate Kubernetes-native service mesh adoption among Tokyo-based platform engineering teams. Japanese telecommunications carriers deploy 5G MEC-integrated containerized load balancers at cellular base stations. Osaka and Nagoya manufacturing clusters demand sub-millisecond latency for precision automation systems.
Load Balancer Market Key Industry Players
United States producers anchor the premium-tier segment with integrated networking and security portfolios; European specialists hold compliance-certified positions in regulated verticals. The vendor base stratifies across three tiers: hyperscale cloud providers with captive infrastructure, established networking incumbents with enterprise relationships, and open-source-native challengers with DevOps velocity. Dominant competitive moves include API-native licensing transitions and managed service bundling to capture recurring revenue.
Within the cloud-provider tier, Amazon Web Services and Microsoft Azure exemplify scale-driven infrastructure control through custom silicon development and elastic consumption models. F5 occupies a position representing established application delivery controller incumbency with deep R&D investment in SSL/TLS offloading and DDoS mitigation. Among open-source-native specialists, Nginx and HAProxy Technologies sit within the DevOps-velocity archetype, anchoring Kubernetes service mesh deployments at Fortune 500 retailers and SaaS providers.
| Leading Market Players |
|---|
| Citrix Systems |
| Google Cloud |
| Amazon Web Services |
| Nginx |
| HAProxy Technologies |
| Cisco Systems |
| Microsoft Azure |
| A10 Networks |
| F5 |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud procurement consolidation in the United States and Germany is compressing vendor margins and forcing load balancer suppliers toward elastic consumption models that displace perpetual hardware sales. This buyer-driven shift concentrates pricing power among AWS, Azure, and Google Cloud while fragmenting margin capture across tier-two managed service providers.
Pricing Analysis
Capacity additions in India and Germany are reshaping price floors for software-defined load balancers as local system integrators absorb margin through bundled professional services. Three-tier pricing structure across premium compliance-certified, standard enterprise, and economy DevOps tiers dominates procurement, with FIPS 140-2 and ISO 27001 certifications commanding 40-60% premiums over uncertified alternatives. Pricing pressure stems from hyperscale captive silicon development that internalizes advanced SSL/TLS offload capabilities. Small and mid-sized enterprises exhibit highest price sensitivity, while BFSI institutions in France and Germany accept premium pricing for immutable audit trail features.
Supply Chain Analysis
ISO 27001 and FIPS 140-2 certification gating restricts qualified supplier pools to vendors with 12-18 month audit completion timelines, concentrating hardware appliance sourcing among established networking incumbents with established compliance infrastructure. Manufacturing concentrates in Taiwan for SSL/TLS offload processors, the United States for FIPS-certified appliance assembly, and India for software development talent. Component dependencies include specialized cryptographic processors, redundant power supply modules, and dual-stack IPv6-capable network interface cards. Single-source vulnerability in custom silicon supply chains operated by AWS Graviton and Google Axion creates procurement risk for enterprises seeking hardware independence. Distribution runs through direct hyperscale marketplaces, systems integrator channels in Frankfurt and Bangalore, and managed service provider aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The load balancer market functions as a stable compounder anchored by persistent infrastructure refresh cycles driven by regulatory compliance mandates across FCC, GDPR, and EU AI Act jurisdictions.
For Market Incumbents: Hedge against hyperscale silicon internalization by deepening R&D investment in Kubernetes-native service mesh orchestration and multi-cloud control plane unification. AWS Graviton and Google Axion processor development threatens to obsolete third-party hardware SSL/TLS offload appliances. Certification investment in EU AI Act audit logging and immutable packet inspection capabilities preserves pricing power in German and French banking verticals.
For New Entrants and Emerging Players: Managed service providers in Frankfurt and Mumbai represent the most penetrable channel archetype for containerized load balancer deployments targeting Mittelstand manufacturers and Indian IT services exporters. White-space concentration sits in edge computing convergence with 5G MEC deployments and API gateway consolidation for microservices architectures. Go-to-market positioning should emphasize DevOps velocity through Envoy proxy and Istio service mesh expertise rather than hardware appliance replacement.
For Investors and Strategic Acquirers: Asymmetric upside sits with open-source-native specialists possessing Kubernetes service mesh deployment velocity and platform engineering talent density. Long-term viability favors vendors with recurring managed services revenue exceeding 60% of contract value and established ISO 27001 certification pipelines. The signal to watch is hyperscaler custom silicon roadmap acceleration that would compress third-party hardware appliance addressable market.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Licensing Transition | Elastic consumption models align vendor economics with hyperscale procurement patterns at AWS and Azure. |
| Managed Service Bundling | Frankfurt-based MSPs capture recurring revenue from German Mittelstand manufacturers seeking ISO 27001 compliance. |
| Service Mesh Integration | Envoy proxy and Istio architectures penetrate Fortune 500 retailers undergoing cloud-native replatforming initiatives. |
| Compliance Certification Investment | EU AI Act audit logging capabilities unlock French banking consortium procurement under GDPR Article 32 mandates. |
| Edge Computing Convergence | Containerized load balancers integrate with 5G MEC deployments at Japanese cellular base stations per METI digitization programs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering leads at Fortune 500 retailers, infrastructure procurement officers at German automotive manufacturers, site reliability engineers at Indian IT services exporters, and compliance directors at French banking consortia with secondary validation against hyperscaler capex disclosures, FCC regulatory filings, EU AI Act implementation guidance, and NIST cybersecurity framework documentation. Bottom-up segment sizing and top-down macro anchoring were triangulated to constrain variance.
Comparable-period anchoring tied projection models to historical infrastructure spend patterns across telecommunications carrier refresh cycles, enterprise data center construction permits in Mumbai and Hyderabad, and cloud migration velocity indices. Segmentation dimensions modeled include deployment model, organization size, compliance exposure tier, cloud-native adoption velocity, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions across hardware appliance replacement, software license transitions, and cloud service consumption trajectories. Forecast inputs incorporated SSL/TLS certificate lifecycle compression effects and IPv6 migration mandate compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscale custom silicon roadmap acceleration, sovereign cloud regulation fragmentation, and platform engineering talent availability constraints. Deviation in EU AI Act enforcement stringency or FCC network reliability mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Virtual Desktop Infrastructure (VDI) Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Decision Support System Market
Digital Solutions
Czech Republic ICT Market