
 Europe Smart Card Market | 2026-2036
Europe Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Card Market Foresight
The gap between contact and contactless card architectures is narrowing as dual-interface technology becomes the default specification for European issuers. Thales Group S.A. leverages its semiconductor partnerships to dominate secure element supply for banking credentials. Giesecke & Devrient GmbH anchors German manufacturing capacity while Infineon Technologies specializes in chip-level security protocols for government ID programs.
A smart card is a pocket-sized plastic credential embedding an integrated circuit chip that stores, processes, and transmits data through physical contact or radio frequency interfaces, typically operating at 13.56 MHz for contactless protocols and manufactured via injection molding with embedded antenna lamination. Its primary purpose is to authenticate identity, execute secure transactions, or grant physical access in environments requiring tamper-resistant credential verification. Contactless cards lead product type demand as transit authorities across Europe mandate open-loop payment compatibility, while EMV cards retain mature volume in banking replacement cycles. Payment processing commands the largest application share, though identification applications for national eID schemes capture disproportionate margin pools due to certification complexity.
The European Banking Authority's strong customer authentication rules under PSD2 compel issuers to deploy cards meeting certified security thresholds, while GDPR constraints shape how transaction data flows through card ecosystems. ETSI technical standards for radio equipment ensure interoperability across member state transit networks. Stakeholders must weigh chip supply constraints against the acceleration of central bank digital currency pilots that could redirect credential demand toward hybrid physical-digital formats.
Market Dynamics
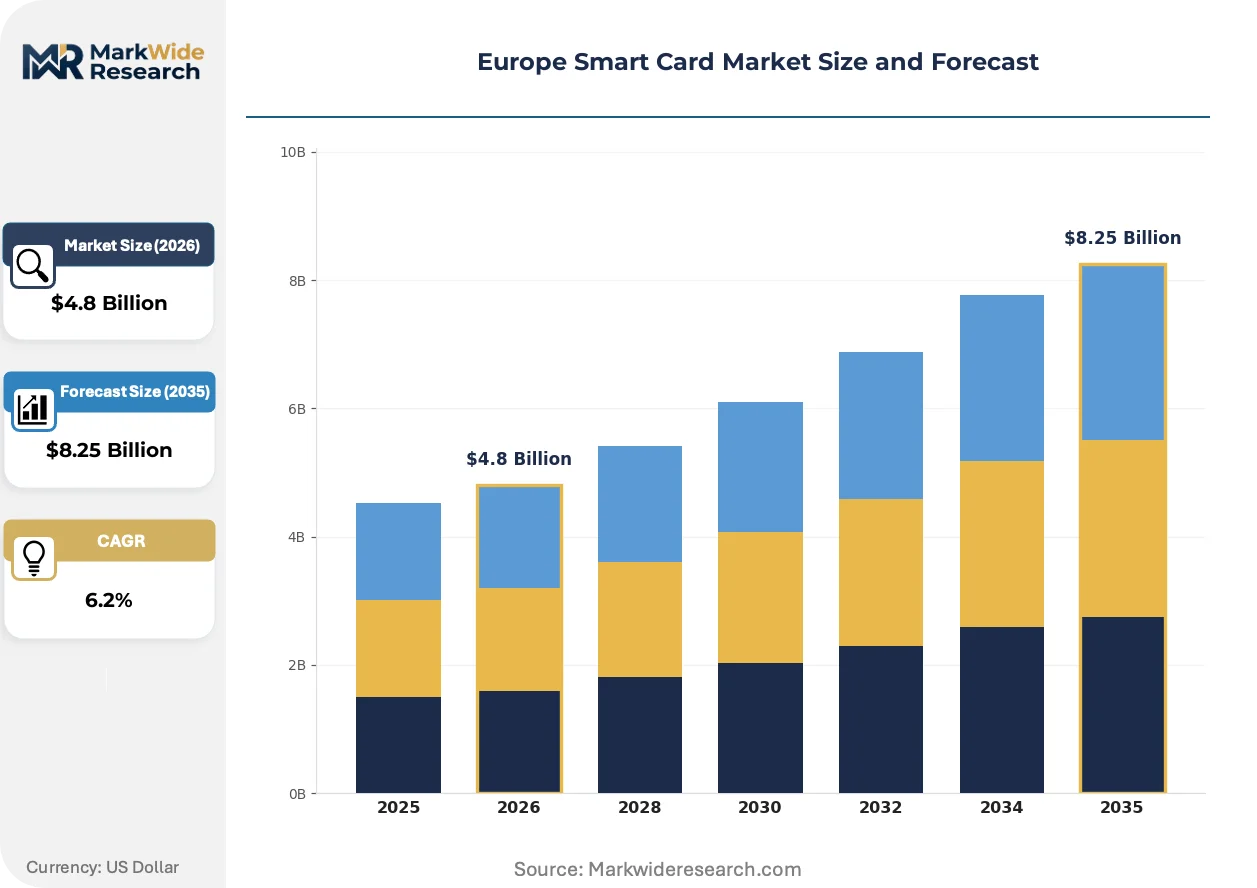
Dual-interface EMV migration is compressing replacement cycles across European banking sectors as issuers race to comply with authentication mandates before regulatory deadlines. This hardware refresh wave is redistributing contract volumes toward semiconductor suppliers with certified secure element capacity.
Growth Catalysts
- PSD2 Strong Customer Authentication:EBA rules compel card issuers to deploy cryptographic credentials meeting certified security thresholds, accelerating hardware refresh across continental banking networks.
- Transit open-loop mandates:Transport for London, Deutsche Bahn, and RATP are requiring contactless payment compatibility, forcing credential upgrades across urban mobility infrastructure.
- Silicon carbide substrate advances:Next-generation secure element manufacturing is yielding smaller die sizes with enhanced tamper resistance, enabling dual-interface cards at contact-only price points.
Market Restraints
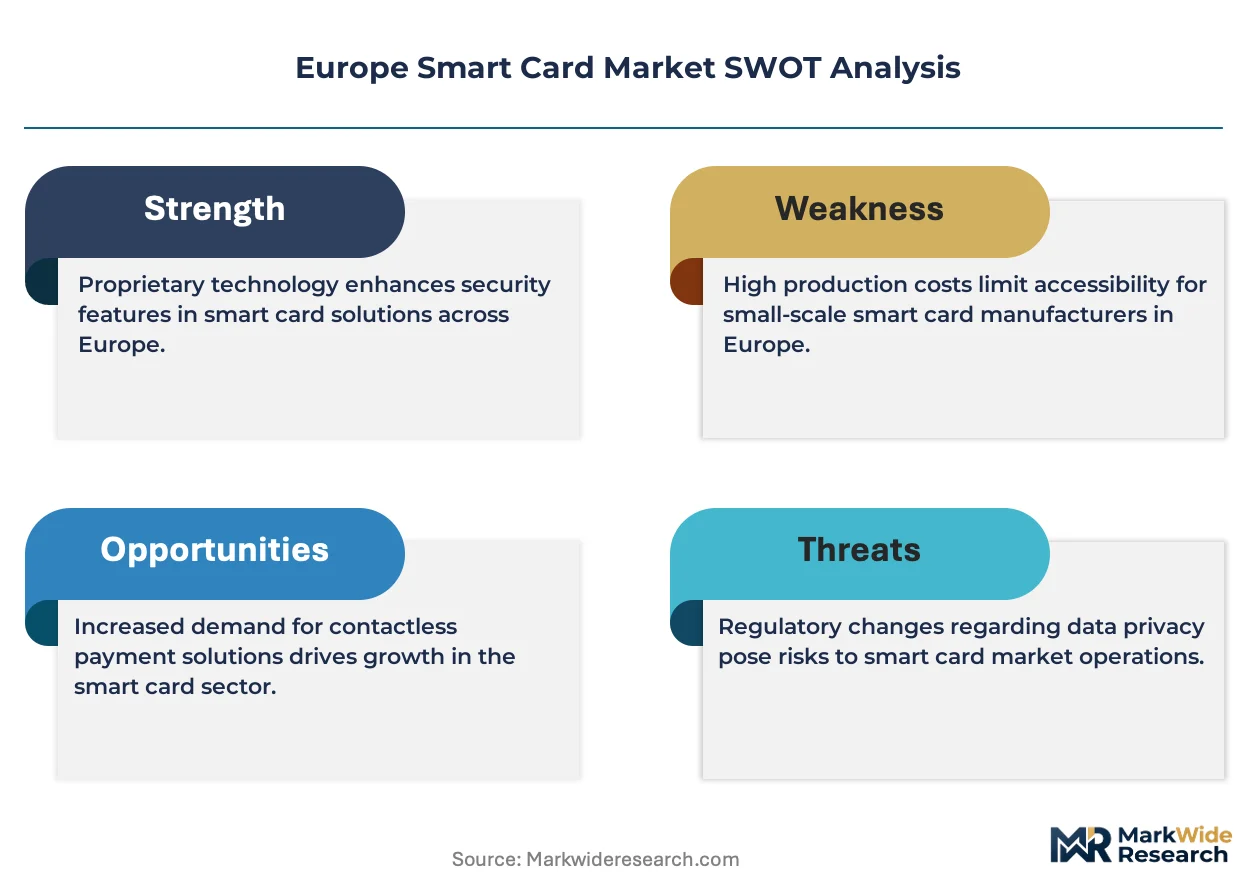
- Secure element supply concentration:Foundry capacity for certified smart card microcontrollers clusters at three European semiconductor fabs, creating allocation risk during demand surges.
- GDPR data flow constraints:Transaction telemetry restrictions complicate cloud-based credential provisioning and limit real-time fraud analytics deployment.
- Central bank digital currency pilots:European Central Bank experimentation with offline-capable CBDC wallets threatens to substitute physical card demand in retail payment use cases.
Strategic Opportunities
- Polish and Romanian eID schemes:National digital identity rollouts in Eastern European member states are creating first-mover advantage for credential providers with government security certifications.
- Biometric payment cards:Fingerprint-on-card technology convergence with EMV infrastructure is opening premium product tiers for high-value transaction segments.
- EU Digital Identity Wallet framework:The eIDAS 2.0 mandate for interoperable mobile credentials is generating hybrid physical-digital product specifications.
Industry Challenges
- Common Criteria certification timelines:EAL5+ security evaluations for banking credentials extend 12-18 months, compressing product launch windows against regulatory deadlines.
- Legacy contact-only terminal base:Merchant infrastructure heterogeneity forces issuers to maintain dual-interface compatibility, adding BOM complexity and antenna design constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Card Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Cards, Smart SIM Cards, EMV Cards, Dual Interface Cards End User: Banking, Transportation, Telecommunications, Healthcare Technology: RFID, NFC, Magnetic Stripe, Smart Chip Application: Payment Processing, Identification, Access Control, Loyalty Programs |
| Companies Covered | CPI Card Group, CardLogix Corporation, Thales Group S.A., Inteligensa, Watchdata Co., Ltd., Giesecke & Devrient GmbH, Assa Abloy AB, Infineon Technologies, IDEMIA SAS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Card Market Shifts & Advancements
Credential architecture is bifurcating between ultra-thin payment cards and multi-application government credentials, with antenna design and secure element partitioning becoming the primary technical battlegrounds. This divergence is forcing suppliers to maintain parallel R&D streams.
Polycarbonate substrate technology is rendering obsolete PVC as the default card body material for premium banking and government ID segments. Tier-one issuers in France and the Netherlands are specifying laser-engraved polycarbonate for 10-year credential lifespans. The structural consequence is rendering obsolete short-life PVC replacement cycles and compressing raw material supplier margins at the commodity end of the spectrum.
GDPR Article 32 security requirements are mandating encryption key rotation protocols that exceed legacy smart card OS capabilities. Issuers must now specify operating systems with post-issuance application management to maintain compliance. German banking networks are responding by consolidating procurement around suppliers with certified remote personalization infrastructure.
Transit authority procurement is consolidating around open-loop payment specifications that displace closed-loop proprietary cards. Transport operators in Barcelona, Milan, and Stockholm are unbundling fare collection from credential issuance, shifting revenue models toward transaction processing fees. This pattern is most visible in Southern European markets where public operator budgets constrain capital expenditure on dedicated infrastructure.
Europe Smart Card Market Segmentation
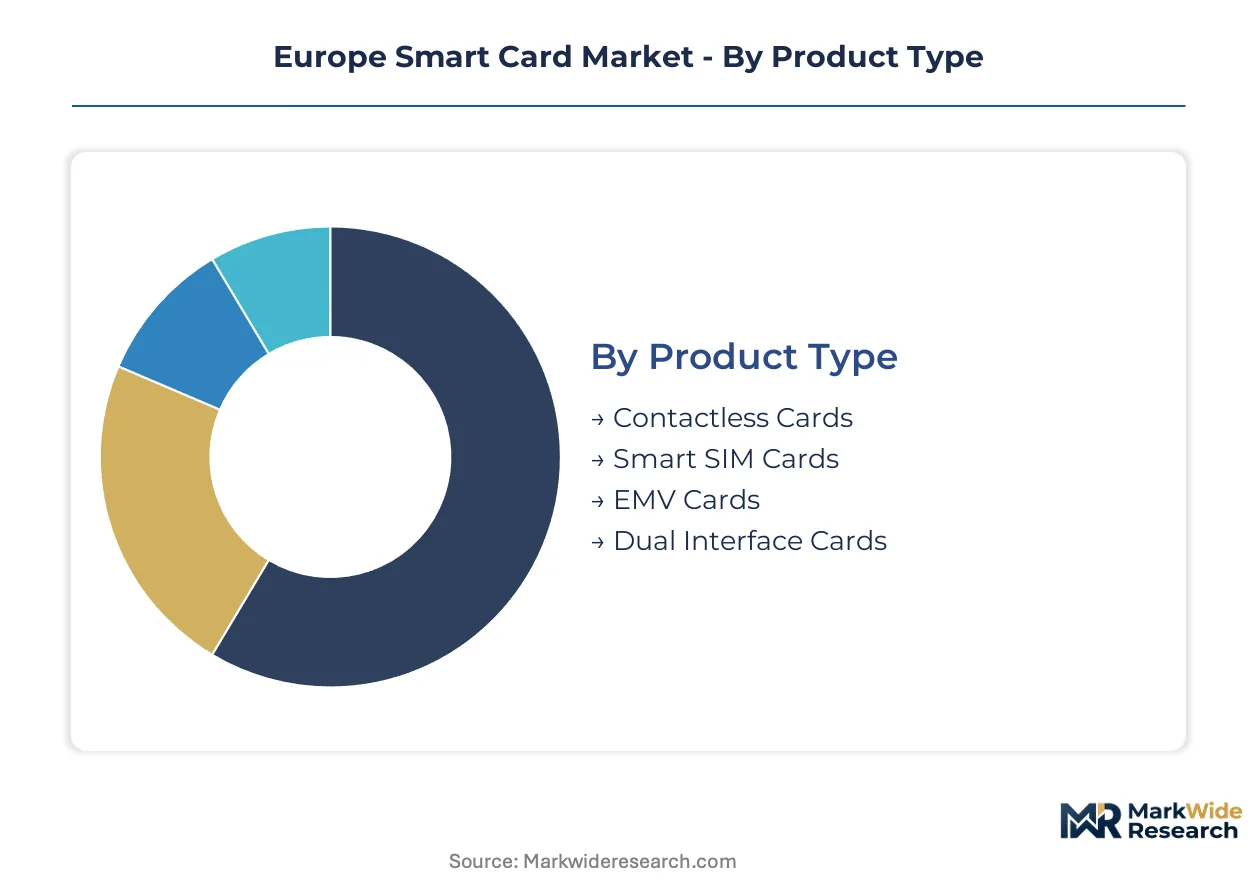
Smart card segmentation in Europe reflects divergent technical requirements across payment, identity, and transit ecosystems. Procurement patterns vary sharply between mature banking infrastructure and emerging government digital identity schemes.
Product Type:
Mature contact-based architectures coexist with emerging dual-interface platforms as issuers navigate terminal infrastructure heterogeneity.
- Contactless Cards:These credentials embed 13.56 MHz RFID antennas laminated between polycarbonate or PVC substrate layers for tap-to-pay functionality. Demand concentrates in Transport for London and Deutsche Bahn networks where open-loop mandates force credential upgrades. Transit authority procurement is displacing closed-loop proprietary systems across Barcelona, Milan, and Stockholm.
- Dual Interface Cards:Hybrid architectures combine ISO 7816 contact pads with ISO 14443 contactless coils, enabling fallback authentication at legacy terminals. German and French banking sectors lead deployment as EBA strong customer authentication deadlines compel hardware refresh cycles.
- EMV Cards:Europay-Mastercard-Visa chip specifications dominate banking replacement cycles with certified secure element protocols.
- Smart SIM Cards:Embedded UICC form factors serve telecommunications subscriber authentication with tamper-resistant key storage.
Contactless cards retain volume leadership; dual interface cards hold the steepest expansion curve.
End User:
Customer type segmentation tracks procurement sophistication from regulated financial services to budget-constrained public operators.
- Banking:Card issuers under EBA PSD2 mandates specify EAL5+ certified secure elements with post-issuance application management capabilities. GDPR Article 32 encryption key rotation requirements exceed legacy smart card OS capabilities, forcing German networks to consolidate procurement around remote personalization infrastructure.
- Transportation:Transit authorities mandate open-loop payment compatibility, unbundling fare collection from credential issuance. RATP and Deutsche Bahn procurement specifications are shifting revenue models toward transaction processing fees rather than capital-intensive dedicated infrastructure.
- Telecommunications:Mobile network operators specify UICC platforms for subscriber identity modules with over-the-air provisioning protocols.
- Healthcare:National health service credential schemes require extended lifespan polycarbonate substrates with laser-engraved personalization.
Banking retains procurement value leadership; transportation holds the most rapid specification evolution.
Technology:
Technology segmentation spans legacy magnetic architectures through radio frequency protocols with distinct interoperability requirements.
- RFID:Radio frequency identification at 13.56 MHz enables proximity coupling without physical contact, specified for transit open-loop mandates.
- NFC:Near field communication protocols support peer-to-peer modes and card emulation for mobile wallet integration.
- Smart Chip:Embedded microcontrollers with dedicated secure element partitions process cryptographic operations for authentication and transaction signing.
- Magnetic Stripe:Legacy back-up tracks persist on dual-interface cards for terminal infrastructure compatibility.
Smart chip technology anchors secure transaction volume; NFC gains share fastest through mobile convergence.
Application:
Application segmentation separates high-volume payment processing from certification-intensive identity credentials with divergent margin structures.
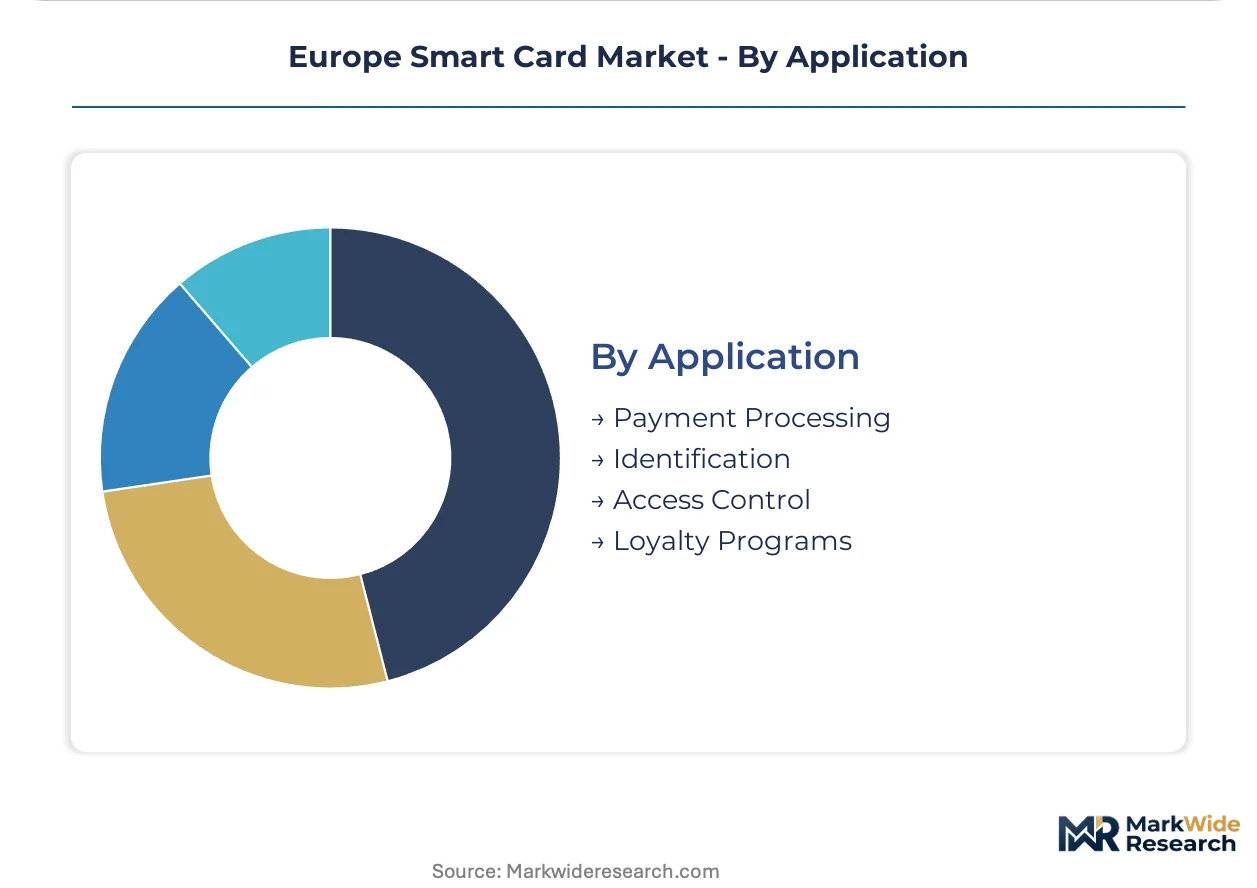
- Payment Processing:EMV and contactless card deployment for retail and transit transactions commands the largest volume share. EBA authentication mandates and transit open-loop requirements are compressing replacement cycles across European banking and urban mobility networks.
- Identification:National eID schemes capture disproportionate margin pools due to Common Criteria certification complexity and extended polycarbonate credential lifespans. Polish and Romanian government rollouts are creating first-mover advantage for providers with security certifications.
- Access Control:Physical and logical access credentials serve enterprise and government facility security with multi-application card capabilities.
- Loyalty Programs:Closed-loop stored value and points accumulation cards operate at lower security thresholds with commodity substrate specifications.
Payment processing retains transaction volume leadership; identification holds the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Banking consortiums and transit authorities in Germany, France, and the United Kingdom concentrate procurement volumes for dual-interface EMV credentials. Eastern European governments are accelerating national eID tenders, diverting contract flows toward certified secure element suppliers.
Germany
Deutsche Bahn and Verkehrsverbund Rhein-Ruhr mandate open-loop contactless compatibility across urban rail networks. The Federal Office for Information Security enforces Common Criteria EAL5+ certification for banking credentials under PSD2 implementation guidelines. Giesecke & Devrient anchors manufacturing capacity in Munich and Leinfelden-Echterdingen, supplying polycarbonate substrates for extended-lifecycle government ID programs.
France
RATP and SNCF procurement specifications require dual-interface EMV compliance for metropolitan transit corridors. The Commission Nationale de l'Informatique et des Libertés shapes GDPR Article 32 encryption protocols affecting credential personalization workflows. Thales Group concentrates secure element design activity in Toulouse and Paris, serving tier-one banking issuers with certified remote personalization infrastructure.
United Kingdom
Transport for London's open-loop mandate has displaced closed-loop Oyster card issuance across Greater London transit. The Financial Conduct Authority enforces EBA strong customer authentication timelines compelling hardware refresh cycles. CPI Card Group operates personalization centers serving UK banking networks with post-issuance application management capabilities.
Poland
The national eID rollout under the eIDAS framework creates first-mover contract opportunities for government security certification holders. The Ministry of Digital Affairs specifies polycarbonate substrate requirements with laser-engraved personalization for 10-year credential lifespans. Warsaw-based procurement clusters are consolidating around hybrid physical-digital wallet specifications under EU Digital Identity Wallet framework alignment.
Netherlands
ING and ABN AMRO banking networks specify remote personalization infrastructure for GDPR-compliant key rotation protocols. The Dutch Data Protection Authority enforces transaction telemetry restrictions affecting cloud-based credential provisioning. Randstad metropolitan transit authorities are unbundling fare collection from credential issuance, shifting revenue models toward transaction processing fees.
Europe Smart Card Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Semiconductor foundries with certified secure element capacity command allocation priority during demand surges. Card body fabricators, personalization service providers, and operating system licensors represent the three strategic archetypes. Consolidation through foundry partnerships and backward integration into substrate manufacturing constitute the dominant competitive moves reshaping supplier relationships.
Within the integrated-systems tier, Thales Group S.A. and Giesecke & Devrient GmbH exemplify full-stack credential providers spanning secure element supply through personalization services. Infineon Technologies occupies a specialized position in chip-level security protocols for government ID programs. IDEMIA SAS represents the personalization-scale archetype with distributed service center networks across continental banking markets.
| Leading Market Players |
|---|
| CPI Card Group |
| CardLogix Corporation |
| Thales Group S.A. |
| Inteligensa |
| Watchdata Co., Ltd. |
| Giesecke & Devrient GmbH |
| Assa Abloy AB |
| Infineon Technologies |
| IDEMIA SAS |
| Others |
Supply & Pricing Matrix
Foundry capacity for certified secure element microcontrollers clusters at three European semiconductor fabs, anchoring margin capture downstream with card issuers and government procurement offices. This concentration enables foundries to impose cost-plus contracts with silicon price indexation, while polycarbonate substrate suppliers compete on volume scale for commoditized PVC replacement cycles.
Pricing Analysis
Cost-plus contracts with quarterly silicon price indexation dominate procurement between semiconductor foundries and card manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects Common Criteria certification grade and polycarbonate substrate durability specifications. Cost compression in standard-tier EMV cards is intensifying because terminal infrastructure heterogeneity forces dual-interface compatibility at contact-only price points. Transportation authorities exhibit highest price sensitivity due to budget constraints, while national eID programs demonstrate lowest sensitivity given security certification requirements and extended credential lifespans.
Supply Chain Analysis
Export control regimes under EU dual-use technology regulations restrict flows of advanced secure element architectures to non-member states. Manufacturing concentrates in Germany, France, and the Netherlands for card body fabrication and personalization services, while silicon wafer supply rests on foundry partnerships in Taiwan and South Korea. Single-source vulnerability characterizes certified secure element allocation during demand surges for banking credential refreshes. Distribution runs through tier-one banking issuers and government procurement offices with direct foundry relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as transit authorities unbundle fare collection from credential issuance and Eastern European governments accelerate eID tenders. The divergence between ultra-thin payment cards and multi-application government credentials splits procurement specifications.
For Market Incumbents: Build certification moats through accelerated Common Criteria EAL5+ investment ahead of Polish and Romanian eID deadlines. Secure allocation agreements with foundries possessing certified secure element capacity. Counter central bank digital currency substitution risk by developing hybrid physical-digital wallet specifications under EU Digital Identity Wallet framework alignment. For New Entrants and Emerging Players: Pursue biometric payment card white-space in high-value transaction segments where fingerprint-on-card technology commands premium positioning. Target Romanian and Polish government security certification pathways for national eID first-mover advantage. Engage transport authorities in Southern European markets through open-loop payment compatibility specifications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed personalization service providers lacking upstream secure element supply control. Five-to-ten year viability hinges on credential demand persisting against CBDC substitution. Acquisition targets include mid-scale polycarbonate substrate fabricators with laser-engraving capabilities. Monitor European Central Bank offline-capable CBDC pilot announcements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Foundry Partnership | Guarantees allocation priority during EBA-mandated banking hardware refresh cycles. |
| Polycarbonate Substrate Backward Integration | Captures margin pools from tier-one issuers specifying 10-year credential lifespans. |
| Biometric Payment Card Launch | Opens premium tier for high-value transactions with fingerprint-on-card convergence. |
| Remote Personalization Infrastructure | Enables GDPR-compliant key rotation protocols for German banking network consolidation. |
| Eastern European eID Certification | Creates first-mover advantage in Polish and Romanian national digital identity rollouts. |
Research Methodology
The analysis maps contactless transit credentials, dual-interface banking cards, government eID programs, and biometric payment innovations, each validated through semiconductor procurement directors, card manufacturing executives, transit authority technology officers, and banking network security leads. Primary interview data triangulates against customs trade records for polycarbonate substrate flows, EBA regulatory filings on PSD2 implementation, and secure element foundry capacity disclosures. Bottom-up credential volume estimates reconcile with top-down banking replacement cycle projections across the analysis window.
Assumption sets held terminal infrastructure heterogeneity and EBA authentication deadlines fixed while varying central bank digital currency substitution scenarios and Eastern European eID tender timelines. Segmentation dimensions modeled include product architecture, end-user procurement sophistication, application security tier, and regional regulatory cluster. CAGRs derive from replacement cycle compression rates and open-loop transit mandate adoption curves, with silicon carbide substrate yield improvements and polycarbonate durability specifications as key forecast inputs.
Sensitivities concentrate around European Central Bank CBDC pilot acceleration and foundry allocation disruptions during demand surges. Forecasts reflect documented assumptions on regulatory deadline adherence and terminal infrastructure refresh rates. Material shifts in offline-capable digital currency technical specifications or secure element export control tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Anticipatory Commerce Infrastructure Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Global Network Engineering Service Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
India ICT Market