
 Asia-Pacific Synthetic Data Generation Market | 2026-2036
Asia-Pacific Synthetic Data Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Synthetic Data Generation Market Analytics
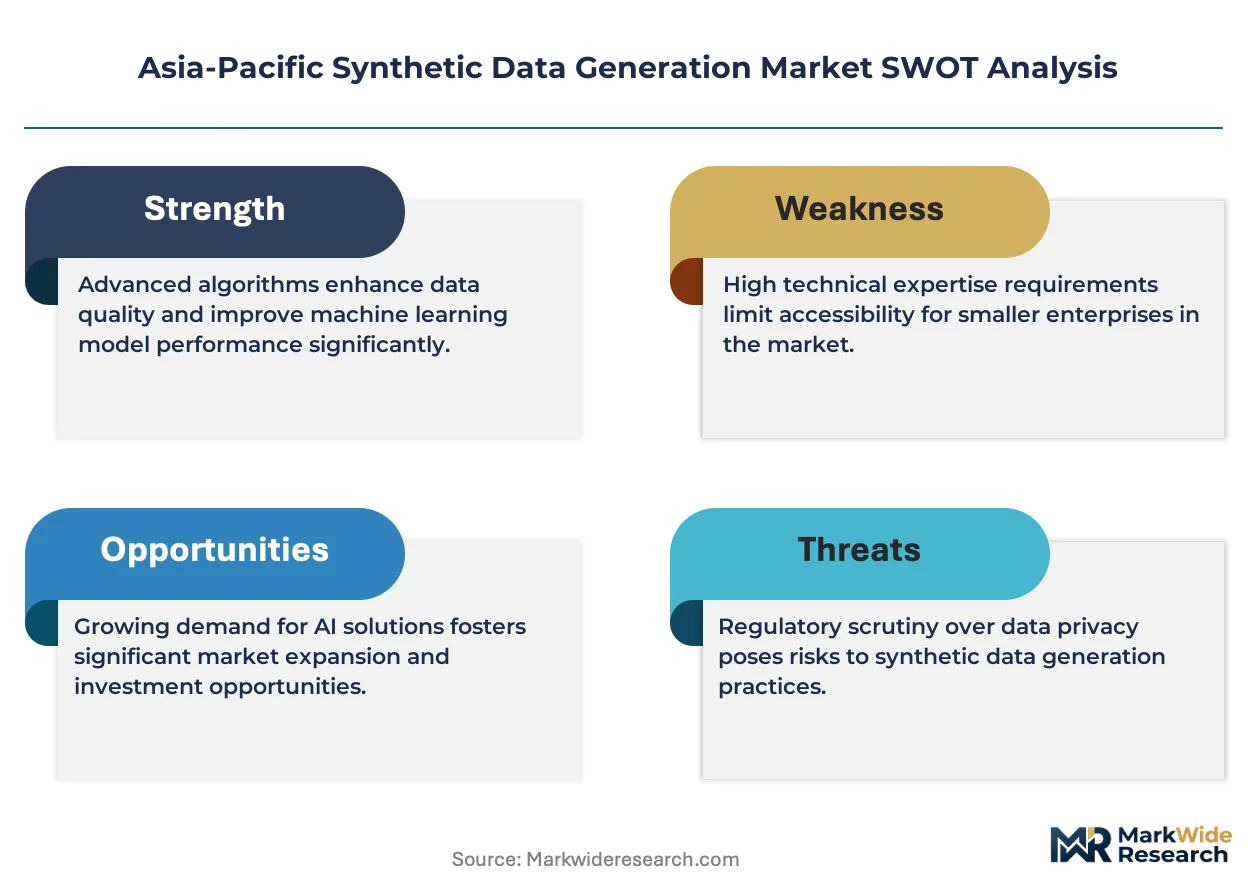
Platform licensing is rewriting margin distribution across the Asia-Pacific synthetic data generation landscape. NVIDIA Corporation leverages its GPU-native architecture to anchor high-performance training workloads for automotive and healthcare clients across Japan and South Korea. MOSTLY AI Solutions MP GmbH sustains European-origin privacy engineering while competing aggressively for APAC banking compliance contracts. Hazy Limited specializes in differential privacy implementations that occupy a defensible niche among Australian financial institutions navigating strict data-sovereignty requirements.
Synthetic data generation produces artificial datasets through algorithmic modeling of statistical distributions, neural network architectures, or agent-based simulations, preserving the analytical utility of source data while eliminating direct identifiability. Image and video synthesis commands the largest current revenue pool, driven by autonomous vehicle development in Japan and South Korea, while cloud deployment models capture the fastest expansion as Chinese and Indian enterprises prioritize scalable infrastructure over capital-intensive on-premises installations. Finance and healthcare end users generate disproportionate margin contribution due to regulatory complexity that elevates willingness-to-pay for privacy-preserving alternatives.
Japan's METI guides industrial AI standards that shape product certification requirements for synthetic training data in robotics and automotive applications. China's SAMR enforces algorithmic recommendation and data security provisions that constrain cross-border synthetic dataset flows while stimulating domestic platform development. India's TRAI and proposed Digital Personal Data Protection framework create compliance benchmarks that vendors must satisfy to access public-sector procurement channels. Stakeholders must monitor evolving interoperability standards between national regulatory regimes to anticipate where compliance costs will concentrate and which localization investments will prove strategically decisive.
Market Dynamics
Platform licensing models are concentrating margin capture among GPU-native vendors, while privacy-engineering specialists defend niche positions through differential-privacy implementations. This structural tension between scale economics and regulatory compliance is forcing mid-tier vendors to choose between vertical specialization and horizontal platform breadth.
Growth Catalysts
- India's PLI scheme for AI infrastructure:Direct procurement incentives channel public-sector demand toward domestic synthetic data providers, accelerating enterprise adoption timelines for healthcare and financial services applications.
- Autonomous vehicle perception training:Japanese automotive tier-one suppliers deploy synthetic video streams to replicate edge-case scenarios without exposing proprietary road-test footage, creating sustained demand for high-fidelity image synthesis pipelines.
- Healthcare AI model development:Cross-institutional research collaborations across South Korea and Australia require privacy-preserving patient record sharing, elevating synthetic tabular data to critical-path status for clinical trial simulation.
Market Restraints
- GPU supply concentration:Training workload dependency on NVIDIA's CUDA ecosystem creates vendor lock-in risk and inflates compute costs for mid-market enterprises lacking volume purchasing leverage.
- Cross-border data friction:China's SAMR algorithmic recommendation and data security provisions constrain synthetic dataset flows between multinational R&D centers and domestic operations, fragmenting training pipelines.
- Fidelity-validation overhead:Statistical distance metrics and downstream task performance audits add 15-25% implementation cost overhead versus raw data procurement, compressing budget elasticity for pilot programs.
Strategic Opportunities
- Indonesian financial inclusion:Underpenetrated digital banking infrastructure creates first-mover advantage for synthetic KYC and credit-scoring dataset providers serving neobank expansion.
- Convergence with federated learning:Edge-compute synthetic data generation combined with decentralized model training addresses data-sovereignty requirements for Australian and Japanese cross-border collaborations.
- TRAI compliance benchmarking:India's proposed Digital Personal Data Protection framework mandates privacy-by-design certifications, creating procurement preference for vendors with pre-validated synthetic data pipelines.
Industry Challenges
- Generative-AI talent scarcity:Shortage of engineers proficient in both differential privacy mechanisms and domain-specific data structures limits vendor scaling velocity and inflates compensation costs.
- Legacy system integration complexity:Enterprise data warehouses built on pre-GDPR architectures require expensive pipeline reengineering to feed synthetic generation workflows without exposing raw identifiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Synthetic Data Generation Market |
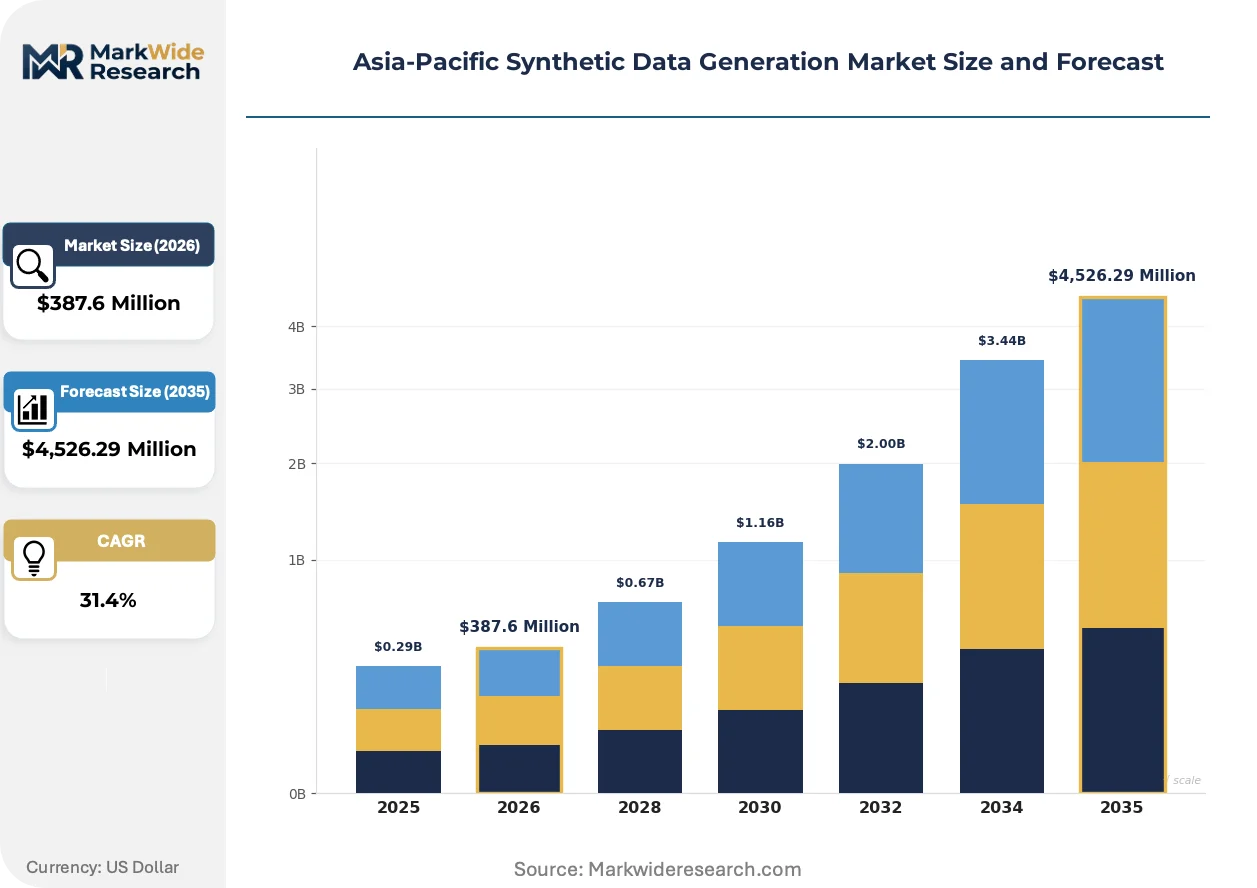
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $4,526.29 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text, Image, Video, Audio Deployment Model: Cloud, On-Premises, Hybrid, Edge End User: Retail, Healthcare, Automotive, Finance Use Case: Training, Testing, Simulation, Augmentation |
| Companies Covered | Synthesis AI, Inc., MOSTLY AI Solutions MP GmbH, Hazy Limited, YData, Statice GmbH, Kinetic Vision, Inc. (Deep Vision Data), NVIDIA Corporation, Google LLC, IBM Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Synthetic Data Generation Market Evolving Landscape
Neural rendering architectures are compressing the cost-quality frontier for perception-system training, while regulatory fragmentation across Asia-Pacific jurisdictions is forcing vendors to maintain parallel compliance stacks. These pressures are reshaping competitive positioning toward modular, jurisdiction-swappable platform designs.
Diffusion-based image synthesis is digitizing photorealistic scenario generation for autonomous vehicle development. Toyota and Hyundai Motor Group engineering teams in Japan and South Korea now source the majority of rare-weather training footage from algorithmic generators rather than physical fleet deployment. This shift is digitizing capital allocation away from road-test infrastructure toward compute clusters and synthetic scenario libraries.
Japan's METI industrial AI standards are mandating traceability documentation for synthetic training data used in robotics certification. Product safety audits now require provenance chains linking generated datasets to source statistical distributions, compelling vendors to implement immutable logging architectures. Automotive and industrial robotics segments are responding by pre-qualifying suppliers against METI's emerging certification benchmarks before procurement commitment.
Subscription-based platform access is displacing perpetual licensing among Chinese and Indian mid-market enterprises. Finance and healthcare buyers in Mumbai and Shenzhen now prioritize operational-expense predictability over capital-asset ownership, compressing vendor sales cycles from 12-18 months to 4-6 months. This pattern is most visible in cloud-native deployments where consumption-based pricing aligns directly with model development sprint timelines.
Asia-Pacific Synthetic Data Generation Market Segmentation
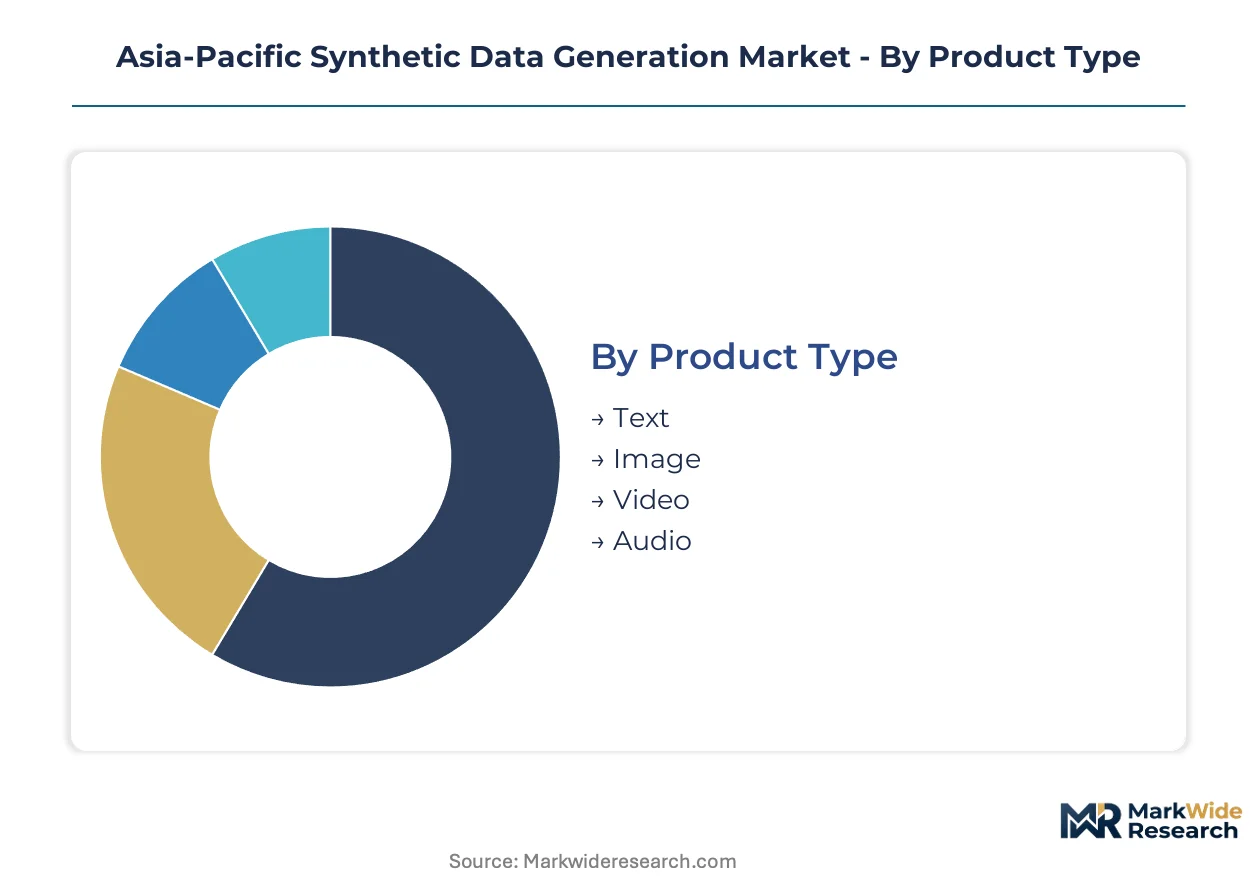
Segmentation in the Asia-Pacific synthetic data generation market reveals how deployment constraints and regulatory fragmentation shape procurement decisions. Vendors must align product architectures with jurisdiction-specific data sovereignty requirements while serving divergent computational intensity across automotive perception and healthcare AI workflows.
Product Type:
After-sales service intensity varies sharply across synthetic data modalities, with video and image pipelines demanding continuous fidelity calibration and scenario library updates that extend vendor-client relationships well beyond initial licensing.
- Image:Algorithmic generation of photorealistic visual datasets through neural rendering architectures preserves statistical distributions of source imagery while eliminating direct identifiability. Japanese automotive tier-one suppliers in Nagoya and Toyota City concentrate procurement for autonomous perception training, driven by METI certification requirements that mandate traceable provenance chains for robotics safety audits.
- Video:Temporal sequence synthesis replicates dynamic scenarios including rare-weather edge cases and adversarial traffic interactions without physical fleet deployment. South Korean automotive R&D clusters in Hwaseong and Seoul source the majority of training footage from synthetic generators, constrained by proprietary road-test footage protection and the capital efficiency of compute-cluster scaling versus physical infrastructure.
- Text:Natural language generation produces structured and unstructured synthetic corpora for conversational AI and document processing pipelines.
- Audio:Speech and acoustic environment synthesis supports voice biometric systems and natural language processing model development.
Image holds the largest share; momentum sits with video.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from consumption-scaled cloud alternatives, with hybrid architectures capturing mid-market buyers seeking workload-specific optimization.
- Cloud:Scalable infrastructure-as-a-service delivery eliminates upfront hardware procurement and aligns operational expenditure with model development sprint timelines. Chinese and Indian enterprises in Shenzhen, Mumbai, and Bangalore prioritize cloud-native deployments, driven by finance and healthcare buyers seeking predictable opex structures and rapid procurement cycles compressed to 4-6 months.
- Edge:Distributed compute nodes generate synthetic data at network peripheries, enabling federated learning workflows that satisfy data-sovereignty requirements for cross-border collaborations. Australian and Japanese healthcare consortia deploying edge-compute synthetic generation address strict localization mandates while preserving multi-institutional research participation.
- On-Premises:Dedicated hardware installations serve organizations with legacy security architectures and air-gapped operational requirements.
- Hybrid:Workload-optimized combinations of cloud burst capacity and on-premises baseline infrastructure balance cost efficiency with compliance constraints.
Cloud captures the dominant revenue position; edge deployment is climbing the fastest.
End User:
Application-specific regulatory complexity creates margin differentiation, with finance and healthcare end users commanding premium pricing for privacy-engineering capabilities that satisfy stringent compliance frameworks.
- Automotive:Synthetic perception data for autonomous vehicle development demands the highest fidelity standards and scenario diversity. Japanese and South Korean OEMs and tier-one suppliers anchor regional demand, compelled by METI industrial AI standards that shape product certification requirements for robotics and automotive applications.
- Healthcare:Synthetic patient records enable AI model development without exposing protected health information or violating cross-institutional data-sharing restrictions. South Korean and Australian clinical research networks drive adoption, constrained by differential privacy requirements and the critical-path status of synthetic tabular data for trial simulation.
- Finance:Privacy-preserving synthetic datasets support fraud detection, credit scoring, and algorithmic trading model development under strict data-sovereignty requirements.
- Retail:Customer behavior simulation and demand forecasting applications leverage synthetic transactional and demographic data.
Automotive holds the largest share; healthcare is gaining share fastest.
Use Case:
Customer-type differentiation separates research-phase buyers focused on model validation from production-phase deployments requiring continuous augmentation pipelines.
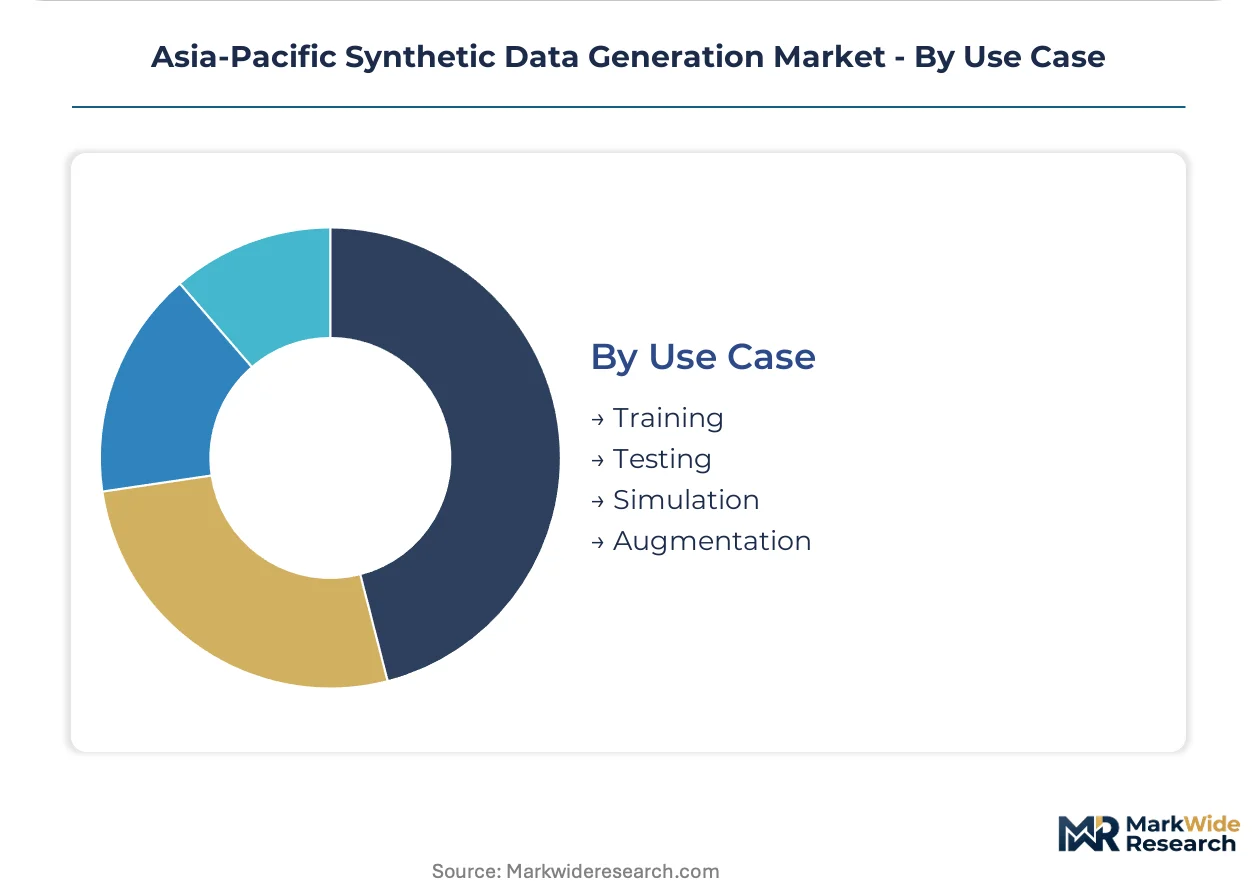
- Training:Primary synthetic data application supplies labeled datasets for machine learning model development across computer vision and natural language processing tasks. Regional concentration in Japanese automotive corridors and Indian healthcare AI startups reflects the scale of foundation-model development and the cost efficiency of synthetic versus annotated real-world data.
- Simulation:Scenario-based synthetic environments test model robustness against edge cases and adversarial conditions without operational risk. Australian mining automation and Japanese robotics manufacturers deploy simulation-heavy workflows, driven by safety-critical certification requirements that prohibit real-world testing of failure modes.
- Testing:Validation datasets assess model performance, bias, and generalization before production deployment.
- Augmentation:Synthetic sample injection expands limited real-world datasets to improve model performance on underrepresented classes and rare events.
Training holds the largest share; simulation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia-Pacific synthetic data generation landscape. Indian healthcare AI startups and Chinese mid-market fintechs compress procurement cycles to 4-6 months by prioritizing cloud-native opex models, while Japanese automotive OEMs absorb 15-25% fidelity-validation premiums for METI-compliant traceability documentation.
Japan
Autonomous vehicle perception training and industrial robotics certification anchor demand. METI industrial AI standards mandate immutable provenance chains linking synthetic datasets to source distributions, compelling tier-one suppliers in Nagoya and Toyota City to pre-qualify vendors against emerging benchmarks. Toyota and Hyundai engineering teams now source majority rare-weather training footage from algorithmic generators.
China
Scalable infrastructure-as-a-service delivery dominates as Shenzhen and Shanghai finance and healthcare buyers prioritize predictable operational expenditure. SAMR algorithmic recommendation and data security provisions constrain cross-border synthetic dataset flows between multinational R&D centers and domestic operations, fragmenting training pipelines while stimulating domestic platform development.
India
Healthcare providers accelerate synthetic patient record adoption for AI model development. The PLI scheme for artificial intelligence and data infrastructure creates direct procurement incentives channeling public-sector demand toward domestic providers. Mumbai and Bangalore enterprises compress vendor sales cycles through subscription-based platform access displacing perpetual licensing.
South Korea
Automotive R&D clusters in Hwaseong and Seoul source majority training footage from synthetic generators constrained by proprietary road-test footage protection. Cross-institutional clinical research networks across the nation elevate synthetic tabular data to critical-path status for trial simulation under differential privacy requirements.
Australia
Strict data-sovereignty requirements drive edge-compute synthetic data generation for healthcare consortia deploying federated learning workflows. Mining automation and robotics manufacturers deploy simulation-heavy workflows driven by safety-critical certification requirements that prohibit real-world testing of failure modes.
Asia-Pacific Synthetic Data Generation Market Competitive Landscape
GPU-native hyperscalers and privacy-engineering specialists split the market along a scale-versus-compliance axis. Vendor concentration remains moderate with clear tiering between infrastructure-anchored platforms and differential-privacy boutiques. Three archetypes dominate: CUDA-ecosystem incumbents leveraging hardware-software integration, European-origin privacy-engineering specialists competing on regulatory compliance, and cloud-native challengers attacking mid-market subscription economics. Dominant competitive moves include strategic partnerships with automotive OEMs for perception-training pipelines and vertical specialization into healthcare compliance workflows.
Within the privacy-engineering tier, MOSTLY AI Solutions MP GmbH and Hazy Limited exemplify European-origin specialists sustaining competitive position through regulatory compliance differentiation. MOSTLY AI competes aggressively for APAC banking contracts while Hazy occupies a defensible niche among Australian financial institutions navigating strict data-sovereignty mandates. NVIDIA Corporation anchors the GPU-native infrastructure tier, leveraging hardware-software integration to capture high-performance training workloads across Japanese automotive and South Korean healthcare verticals.
| Leading Market Players |
|---|
| Synthesis AI, Inc. |
| MOSTLY AI Solutions MP GmbH |
| Hazy Limited |
| YData |
| Statice GmbH |
| Kinetic Vision, Inc. (Deep Vision Data) |
| NVIDIA Corporation |
| Google LLC |
| IBM Corporation |
| Others |
Value Network & Pricing Analysis
Single-source GPU dependency concentrates pricing power among CUDA-ecosystem vendors while fragmenting procurement options for mid-market buyers, compressing margin elasticity across cloud-native deployments and forcing tiered service bundling as the primary differentiation mechanism.
Pricing Analysis
After-sales scenario library subscriptions and continuous fidelity calibration contracts drive lifetime value beyond initial platform licensing. Three-tier pricing structure across enterprise-grade METI-compliant bundles, standard cloud-native subscriptions, and entry-level developer tiers separates Japanese automotive OEMs from Indian healthcare startups. Pricing pressure stems from GPU compute cost inflation and mid-market buyer consolidation around consumption-based opex models. Indian fintechs and Chinese healthcare enterprises exhibit highest price sensitivity, while Japanese tier-one suppliers absorb premiums for immutable provenance documentation.
Supply Chain Analysis
Upstream feedstock concentration in NVIDIA's GPU architecture and Taiwan Semiconductor's advanced node production anchors compute infrastructure costs. The supply chain draws from US-designed silicon, Taiwanese foundry capacity, and South Korean memory fabrication, creating single-source vulnerability for training workload hardware. SAMR data localization mandates and METI certification documentation requirements introduce regulatory friction into cross-border component flows. Distribution runs through hyperscaler marketplaces and direct enterprise licensing channels, with cloud-native delivery displacing on-premises hardware procurement across Chinese and Indian mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic data generation represents a service-attach opportunity where scenario library subscriptions and compliance-certification renewals expand recurring revenue faster than core platform licensing, particularly among automotive and healthcare verticals requiring continuous fidelity updates.
For Market Incumbents: Pre-empt margin compression from open-source diffusion models by embedding differential-privacy tooling as standard features rather than premium add-ons. Anchor defensive positioning through METI pre-certification partnerships that lock in Japanese automotive procurement cycles. Deepen upstream control over GPU allocation agreements to secure volume pricing leverage against mid-market challengers. For New Entrants and Emerging Players: Indonesian neobank synthetic KYC datasets represent the most penetrable entry point, combining underpenetrated digital banking infrastructure with TRAI-aligned privacy-by-design procurement preferences. Australian healthcare edge-compute federated learning deployments offer second-mover advantage through data-sovereignty specialization. Attack through vertical-specific compliance pre-validation rather than horizontal platform breadth. For Investors and Strategic Acquirers: India's Digital Personal Data Protection framework implementation reshapes the acquisition landscape toward vendors with pre-validated synthetic pipelines and domestic PLI scheme alignment. Long-term viability favors specialists combining differential-privacy IP with jurisdictional certification depth over undifferentiated horizontal platforms. Monitor TRAI compliance benchmarking announcements as early signals of procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with GPU-Native Architecture | NVIDIA CUDA ecosystem anchoring secures high-performance training workload capture across Japanese automotive corridors. |
| Vertical Specialization into Healthcare Compliance | METI and TGA certification pathways create defensible moats among Australian and Japanese clinical research networks. |
| Geographic Expansion into Indonesian Financial Services | Neobank synthetic KYC demand outpaces domestic supply, enabling first-mover pricing power. |
| Strategic Partnership with Tier-One Automotive Suppliers | Toyota City and Hwaseong engineering clusters require rare-weather scenario libraries with immutable provenance chains. |
| Acquisition of Differential-Privacy Specialist Firm | Hazy Limited and Statice GmbH demonstrate regulatory compliance IP commands premium valuations in Australian banking. |
Research Methodology
Cross-validation between primary interviews with synthetic data platform engineers, automotive perception system architects, healthcare AI research directors, and regulatory compliance officers anchors the qualitative findings against secondary validation from SAMR algorithmic recommendation filings, METI industrial AI standard drafts, TRAI consultation papers, and hyperscaler capex disclosures. Bottom-up deployment model sizing triangulates against top-down end-use industry spending patterns.
Calibration against historical adoption curves in adjacent privacy-preserving technologies shapes the analytical framework across the projection horizon. Segmentation dimensions span synthetic data modality, deployment architecture, end-use vertical, and jurisdiction-specific compliance tier. CAGRs derive from fitted growth curves adjusted for GPU supply constraints and regulatory implementation timelines. Model inputs incorporate PLI scheme procurement acceleration and METI certification mandate effective dates.
Practitioners should monitor GPU supply allocation shifts and TRAI compliance benchmarking finalization for early signals of vendor consolidation or procurement preference disruption. Cross-checking against hyperscaler marketplace transaction velocity and automotive OEM synthetic data RFP volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
AI Recruitment Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Industrial AI Software Market