
 Car Wash Management System Market | 2026-2036
Car Wash Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Car Wash Management System Market Analytics
Market Context
ISO 14001 environmental management certification is unwinding competitive access for car wash technology vendors lacking documented sustainability protocols. DRB Systems leverages its vertical integration into payment processing and tunnel controls to sustain pricing power across North American installations. Istobal anchors European demand through specialized rollover and jet wash configurations designed for constrained urban footprints. Innovative Control Systems competes on software modularity, allowing independent owners to scale from single-bay POS to multi-site enterprise dashboards without hardware swaps.
Technical Definition and Segment Structure
A car wash management system integrates hardware controllers, payment gateways, chemical dosing units, and customer-facing interfaces into a unified operational platform that sequences wash cycles, tracks revenue, and monitors equipment health in real time. The system typically processes telemetry from conveyor sensors, water reclamation tanks, and vacuum stations to optimize throughput and flag maintenance events before failure. Cloud-based deployment leads the product type category because franchise operators require centralized visibility across dispersed locations without on-site server maintenance. IoT-enabled wash tunnels represent the fastest-growing technology segment as real-time water pressure and chemical concentration monitoring reduces waste and regulatory exposure. Subscription service models now dominate the service type dimension, converting capital expenditure into predictable operational budgets that align with fleet manager procurement frameworks.
Regulatory Frame and Outlook
EPA effluent guidelines and state-level water board regulations in California, Texas, and Florida mandate reclamation rates that force management system upgrades capable of metering and reporting water recovery percentages. OSHA workplace safety standards and local fire codes governing chemical storage further shape system design requirements for tunnel enclosures and employee access protocols. Stakeholders must monitor how municipal stormwater discharge permits evolve, as tightening local ordinances will determine which management platforms can demonstrate compliant closed-loop operations without manual intervention.
Market Dynamics
Franchise operators are consolidating purchasing power across multi-site networks, forcing management system vendors to standardize cloud-native architectures that eliminate on-premise server dependencies at each location.
Growth Catalysts
- EPA effluent guidelines:Federal water reclamation mandates compel tunnel operators to retrofit legacy equipment with metering-capable management systems that document recovery percentages for compliance audits.
- IoT sensor arrays:Real-time chemical concentration and pressure monitoring reduces per-wash resource waste, delivering measurable opex savings that accelerate payback periods for automation investments.
- Texas car wash density:Concentrated metro development in Dallas-Fort Worth and Houston creates cluster economies where shared service infrastructure justifies enterprise-grade management platform deployment.
Market Restraints
- Semiconductor input volatility:Controller board production depends on specialized industrial microcontrollers subject to foundry allocation swings that extend equipment lead times unpredictably.
- California water board enforcement:Retroactive permit modifications in Los Angeles and San Diego counties force operators into unplanned system upgrades without grandfathering provisions.
- Manual wash substitution:Low-touch self-service bays retain cost advantages in rural markets where labor arbitrage still undercuts automation economics.
Strategic Opportunities
- Florida stormwater ordinance evolution:Municipal discharge permit tightening in Miami-Dade and Orange counties creates first-mover advantage for vendors with pre-certified closed-loop documentation.
- Subscription billing convergence:Fleet manager procurement frameworks favor opex-aligned service contracts over capital purchases, opening recurring revenue streams for platform providers.
- 5G edge computing integration:Latency-sensitive tunnel controls combined with predictive maintenance algorithms enable new premium service tiers for high-throughput express locations.
Industry Challenges
- PLC programming specialization:Scarce technicians capable of troubleshooting legacy relay logic alongside modern IoT gateways extend mean-time-to-repair during hybrid system transitions.
- ISO 14001 certification timelines:Documentation gaps in chemical supply chain traceability delay vendor qualification for sustainability-mandated RFPs from major franchise chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Wash Management System Market |
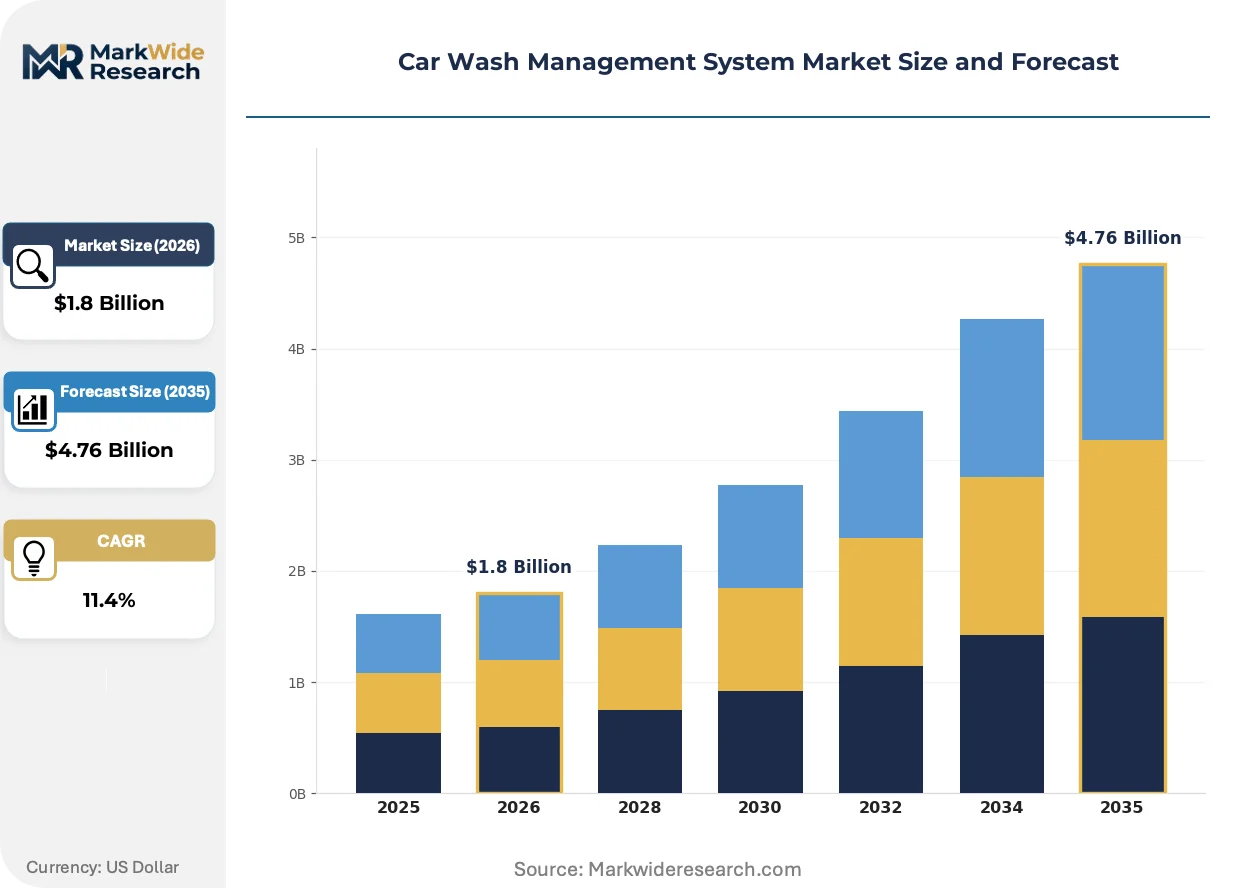
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile App End User: Franchise Operators, Independent Owners, Fleet Managers, Car Dealerships Technology: AI, IoT, SaaS, POS Integration Service Type: Subscription, One-Time Purchase, Maintenance, Training |
| Companies Covered | Istobal, Micrologic Associates, DRB Systems, Innovative Control Systems, SunrisePOS, Washify, ICS Systems, Rinsed, Sonny's The CarWash Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Wash Management System Market Evolving Landscape
Edge computing architectures are displacing centralized cloud dependency for latency-critical wash cycle controls, while regulatory telemetry requirements reshape how operators document environmental compliance.
Brushless motor controllers with integrated variable frequency drives are miniaturizing tunnel conveyor systems, enabling compact footprint designs for urban infill sites where real estate constraints previously blocked automation. Express exterior operators in California and Texas are adopting these units fastest, compressing equipment room requirements by 40 percent and unlocking retrofit opportunities in legacy gas station conversions.
OSHA workplace safety standards governing chemical storage and employee access protocols are tightening tunnel enclosure specifications, forcing management system redesigns that integrate automated lockout-tagout sequences with wash cycle logic. Tunnel operators in high-labor-cost jurisdictions face the steepest compliance burdens, with Florida and California installations prioritizing fully automated chemical delivery systems that eliminate manual handling exposure.
Fleet procurement officers now mandate outcome-based service level agreements that tie vendor payments to uptime percentages and water recovery targets rather than equipment delivery. This restructures competitive positioning around predictive maintenance capabilities and remote diagnostics infrastructure, with multi-site franchise buyers in Texas leading the contract innovation before the model spreads to California and Florida operators.
Car Wash Management System Market Segmentation
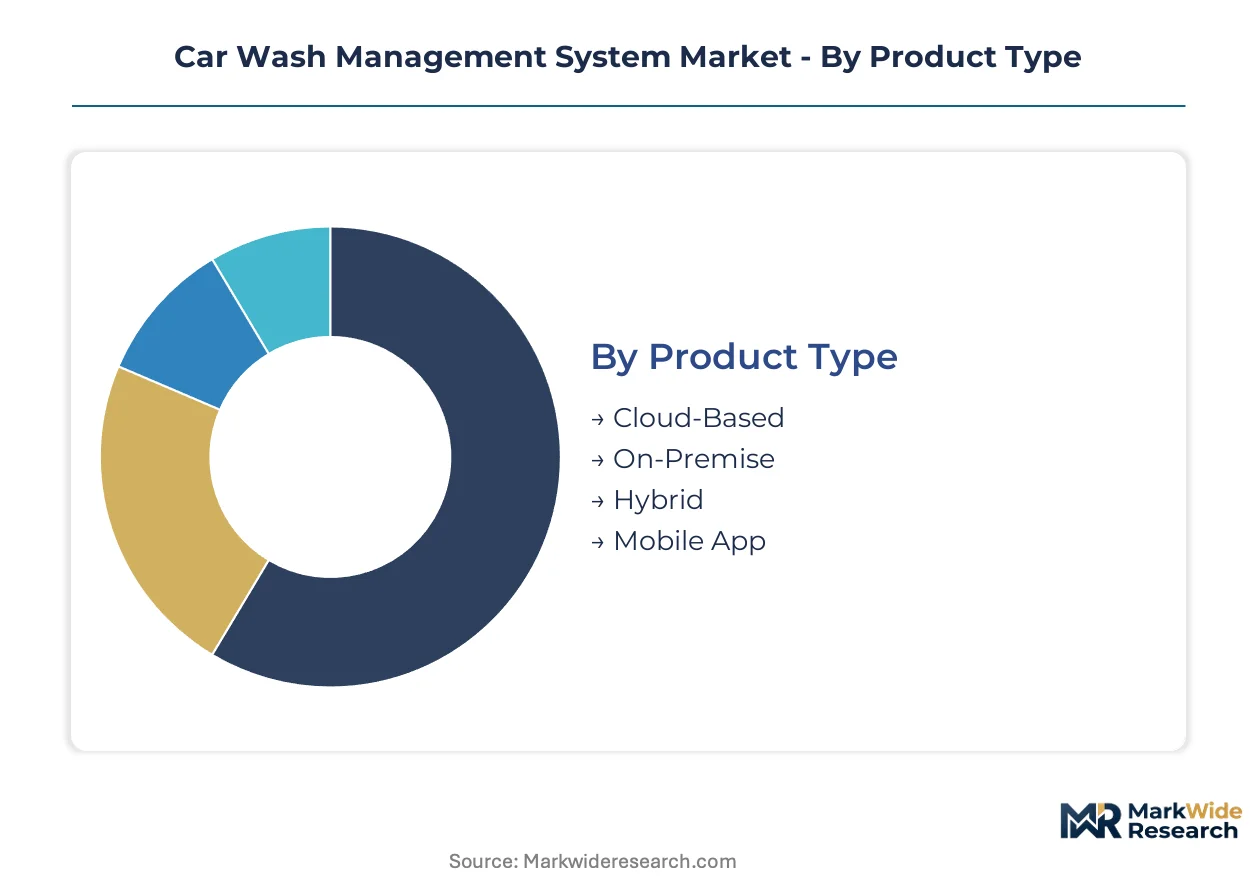
Segmentation in the car wash management system market reveals how deployment models, customer archetypes, and technology stacks fragment purchasing behavior. Franchise operators favor cloud-native platforms that centralize multi-site visibility, while independent owners prioritize capital-efficient on-premise alternatives that minimize recurring fees.
Product Type:
Cloud-based platforms dominate North American franchise deployments, whereas on-premise systems retain share in markets with unreliable connectivity infrastructure. Hybrid architectures bridge these extremes for operators transitioning from legacy installations.
- Cloud-Based:Centralized server architecture eliminates on-site hardware maintenance while enabling real-time telemetry aggregation across dispersed locations. Demand concentrates in Texas and California where multi-site chains standardize operations and EPA water reclamation reporting requirements favor centralized data repositories. The steepest expansion runs through this segment as subscription billing aligns with fleet procurement frameworks.
- On-Premise:Local server deployment retains full data sovereignty and eliminates recurring SaaS fees, appealing to single-bay operators with predictable throughput. Independent owners in rural Florida markets favor this model where internet redundancy concerns and low transaction volumes undermine cloud economics.
- Hybrid:Edge computing nodes process latency-critical wash cycle controls locally while batching compliance telemetry to cloud dashboards. This architecture serves California operators navigating municipal stormwater permit variations that demand both real-time responsiveness and centralized audit trails.
- Mobile App:Customer-facing interfaces handle payment, loyalty programs, and wash status notifications through smartphone integration. Express exterior operators deploy these fastest where queue management and prepaid subscription conversion drive revenue per bay.
Cloud-based systems command the established base. The steepest expansion runs through hybrid configurations as retrofit demand surges.
End User:
Customer type determines contract structure, with enterprise buyers mandating outcome-based SLAs and small operators prioritizing upfront capital control. Procurement sophistication varies sharply across these archetypes.
- Franchise Operators:Multi-site chains standardize management platforms across networks to enable centralized pricing, chemical procurement, and maintenance scheduling. Texas-based clusters in Dallas-Fort Worth and Houston drive volume concentration where shared infrastructure justifies enterprise-grade deployment.
- Independent Owners:Single or limited-site operators prioritize capital expenditure minimization and resist recurring subscription models. These buyers concentrate in secondary Florida metros where labor costs remain low enough to delay automation investments.
- Fleet Managers:Commercial vehicle operators demand outcome-based contracts tying vendor payments to uptime percentages and water recovery targets. California municipal fleets and Texas rental car operations lead this procurement innovation before the model spreads.
- Car Dealerships:Fixed-ops departments integrate wash management with service scheduling and customer relationship platforms. Volume concentrates in high-throughput metropolitan markets where detailing throughput supports dedicated tunnel investments.
Franchise operators anchor procurement volume. Fleet managers are gaining share fastest as outcome-based contracting restructures vendor relationships.
Technology:
Technology selection tracks regulatory exposure and labor cost intensity, with IoT sensor arrays penetrating fastest where water board enforcement is strictest. AI adoption lags in cost-sensitive segments.
- AI:Predictive maintenance algorithms analyze vibration and thermal patterns from conveyor motors and chemical pumps to flag failures before downtime. California operators facing steep labor costs and OSHA compliance burdens deploy these systems to reduce technician dispatch frequency.
- IoT:Real-time water pressure, chemical concentration, and flow rate monitoring enables automated dosing adjustments that reduce per-wash resource waste. Florida installations in Miami-Dade and Orange counties prioritize these capabilities where stormwater discharge permits tighten fastest.
- SaaS:Software-as-a-service delivery converts capital expenditure into predictable operational budgets with automatic feature updates. Franchise operators favor this model for multi-site standardization without on-site IT staffing.
- POS Integration:Unified payment processing, loyalty program management, and accounting system connectivity eliminates manual reconciliation. Independent owners in Texas adopt these most rapidly where cashless transaction mandates accelerate hardware refresh cycles.
IoT sensor platforms command the established base. AI-enabled predictive maintenance is climbing the fastest as labor scarcity intensifies technician optimization priorities.
Service Type:
Revenue model selection reflects buyer size and capital access, with subscription services displacing one-time purchases among credit-constrained operators. Maintenance contracts bundle critical for uptime-dependent express locations.
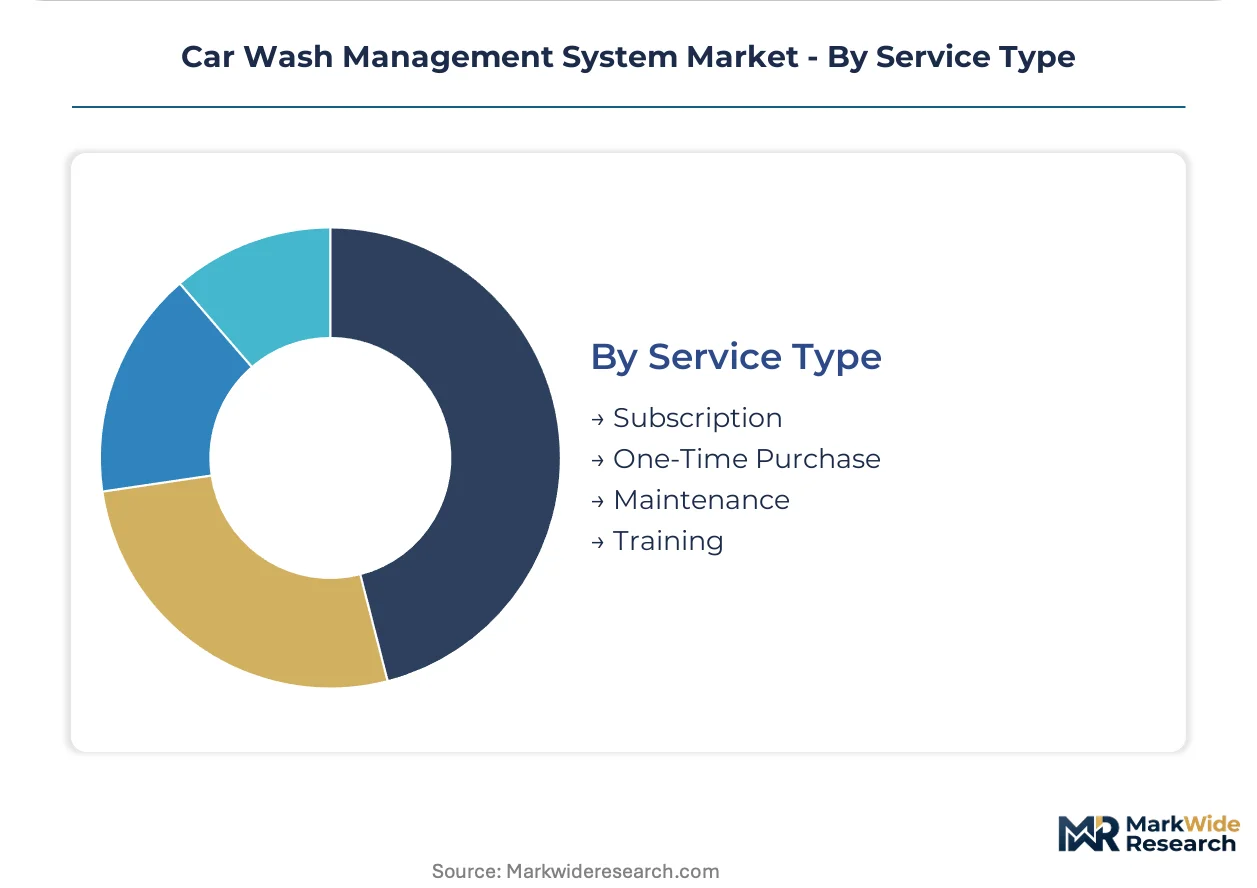
- Subscription:Recurring fee structures cover software licensing, cloud hosting, and feature updates without upfront capital deployment. Fleet managers and franchise operators favor this opex alignment for budget predictability and rapid scaling.
- One-Time Purchase:Perpetual license acquisition with optional annual support contracts appeals to independent owners with available capital and low technology refresh frequency. Rural Florida markets retain this preference where financing access is limited.
- Maintenance:Preventive and corrective service contracts ensure equipment uptime through scheduled inspections and priority technician dispatch. High-throughput Texas express operators mandate these for revenue protection against peak-hour downtime.
- Training:Operator certification and system administration education ensures effective platform utilization and regulatory compliance documentation. California water board audit requirements drive demand for reclamation system operation training.
Subscription billing commands the established base. Maintenance service bundling is expanding most quickly as uptime guarantees become standard contract terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent guidelines and state-level water board mandates are compressing upgrade timelines across major car wash markets, with compliance deadlines clustering in 2026-2028. Multi-site franchise operators concentrate purchasing power in metro corridors where labor costs and environmental enforcement intersect most aggressively.
United States
California, Texas, and Florida anchor North American demand through divergent regulatory pressures. EPA water reclamation mandates force tunnel operators to document recovery percentages through metered management systems. Dallas-Fort Worth and Houston cluster economies justify enterprise-grade platform deployment across shared service infrastructure.
Germany
REACH chemical registration requirements and EU Green Deal water efficiency targets reshape equipment specifications for tunnel operators. Industrial fabricators in Baden-Württemberg and North Rhine-Westphalia supply brushless motor controllers with integrated variable frequency drives. Munich and Stuttgart metro areas drive compact footprint adoption for urban infill retrofits.
United Kingdom
Environment Agency discharge permits and municipal stormwater ordinances in Greater London and Birmingham mandate closed-loop documentation capabilities. Independent operators in secondary metros retain on-premise deployment preferences where connectivity infrastructure remains uneven. Fleet manager procurement frameworks from rental car operations near Heathrow accelerate outcome-based contracting adoption.
Japan
METI energy efficiency standards and JIS certification requirements for industrial equipment filter vendor qualification. Tokyo-Osaka corridor operators prioritize predictive maintenance algorithms to offset technician scarcity and aging workforce demographics. Compact urban footprints in Nagoya and Fukuoka accelerate miniaturized tunnel conveyor system deployment.
Australia
State-level EPA variations across New South Wales, Victoria, and Queensland create patchwork compliance environments for multi-site operators. Sydney and Melbourne water restrictions tighten reclamation rate requirements fastest. Drought-driven municipal ordinances in Brisbane and Perth push automated dosing systems that reduce per-wash resource waste.
Car Wash Management System Market Competitive Landscape
Listed leaders compete with private specialists across payment processing and tunnel control integration. The vendor base stratifies into three tiers: vertically integrated platform providers, modular software specialists, and regional hardware fabricators. Dominant competitive moves include cloud-native architecture standardization and outcome-based service contract structuring.
Within the integrated platform tier, DRB Systems exemplifies vertical control spanning payment processing and tunnel controls, while Istobal anchors European demand through specialized rollover configurations. Innovative Control Systems occupies a position among modular software specialists competing on scalability from single-bay to multi-site deployments.
| Leading Market Players |
|---|
| Istobal |
| Micrologic Associates |
| DRB Systems |
| Innovative Control Systems |
| SunrisePOS |
| Washify |
| ICS Systems |
| Rinsed |
| Sonny's The CarWash Factory |
| Others |
Value Network & Pricing Analysis
Brushless motor controller substitution for legacy relay-based systems simultaneously shifts procurement geography toward German and Japanese fabricators while compressing hardware margins across mid-tier vendors. This displacement concentrates pricing power with suppliers offering integrated variable frequency drive architectures, forcing independent operators toward subscription models that bundle hardware depreciation into predictable operational expenditures.
Pricing Analysis
Certification level creates the primary spread between platform tiers, with ISO 14001-documented sustainability protocols commanding premium positioning against uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels aligns with deployment complexity, where cloud-native multi-site configurations sit at the top and single-bay on-premise licenses anchor the bottom. Pricing pressure stems from semiconductor input volatility extending controller board lead times unpredictably. Franchise operators demonstrate lowest price sensitivity due to procurement scale, while independent owners in rural Florida markets resist recurring SaaS fees most aggressively.
Supply Chain Analysis
Port congestion across Los Angeles-Long Beach and Houston trade lanes elevates inbound logistics costs for controller assemblies sourced from East Asian foundries. Manufacturing concentrates in China, Taiwan, and Germany, with industrial microcontroller fabrication drawing from specialized 28nm and 40nm process nodes. Supply chain risk centers on single-source vulnerability for chemical dosing pump motors where European suppliers dominate. Distribution runs through regional equipment distributors serving metro installation clusters, with Texas and California operators commanding priority allocation during capacity constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware sales as predictive maintenance contracts and water reclamation compliance monitoring convert capital expenditure into recurring revenue streams. Subscription billing for telemetry dashboards and automated chemical dosing optimization now outpaces equipment shipment growth across franchise operator networks.
For Market Incumbents: Consolidate cloud-native architecture standardization to defend against modular software specialists encroaching on multi-site deployments. Backward integration into payment processing sustains margin capture as transaction volume concentrates in Texas and California metro corridors. Prioritize ISO 14001 certification investment to disqualify sustainability-deficient competitors from franchise chain RFPs. For New Entrants and Emerging Players: Anchor in Florida stormwater ordinance evolution where municipal discharge permit tightening outpaces vendor certification capacity. Target independent operators in secondary Texas metros where shared service infrastructure remains underdeveloped. Deploy mobile-first customer interfaces as wedge offering, converting queue management software adoption into full platform expansion. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular software specialists lacking predictive maintenance capabilities. Five-to-ten year viability favors vendors with demonstrated closed-loop water reclamation documentation and established relationships with EPA-compliant franchise operators. Monitor California water board enforcement intensity as inflection signal for compliance-mandated upgrade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Standardization | Franchise operators in Texas demand centralized visibility without on-site server maintenance. |
| Predictive Maintenance Algorithm Development | California labor costs and OSHA burdens reduce technician dispatch frequency for AI-enabled vendors. |
| ISO 14001 Certification Investment | Sustainability-mandated RFPs from major chains disqualify documentation-deficient competitors. |
| 5G Edge Computing Integration | Latency-sensitive tunnel controls enable premium service tiers for high-throughput express locations. |
| Subscription Billing Convergence | Fleet manager procurement frameworks favor opex-aligned contracts over capital purchases. |
Research Methodology
The analysis maps cloud deployment models, IoT sensor configurations, and service type revenue structures, each validated through franchise operations directors, independent owner-operators, chemical supply procurement leads, and municipal fleet managers. Primary interview findings triangulate against EPA effluent guideline documentation, state water board permit filings, SEC 10-K equipment vendor disclosures, and trade association membership data. Bottom-up unit economics from installation clusters in California, Texas, and Florida reconcile with top-down market sizing across the analysis window.
Consistency checks validate volume and value outputs against hyperscaler capex disclosures for edge computing infrastructure and industrial automation trade flow data. Segmentation dimensions span product type, end user archetype, technology stack, and service model across the projection horizon. CAGRs derive from installed base growth rates, replacement cycle compression from regulatory deadlines, and penetration assumptions for subscription billing conversion. Forecast inputs incorporate water reclamation mandate enforcement timelines and semiconductor foundry capacity allocation patterns.
Underlying assumptions cover sustained EPA effluent guideline implementation, stable franchise operator consolidation velocity, and moderate semiconductor supply normalization, with deviation risk concentrated in retroactive permit modifications without grandfathering provisions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Service Mesh Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Desktop Virtualization in Manufacturing Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Warranty Management System Market
Digital Solutions
Global Recommendation Search Engine Market
Digital Solutions
Morocco ICT Market
Digital Solutions
Legal Technology Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Smart Card Reader Market