
 Customer Engagement Hub (CEH) Market | 2026-2036
Customer Engagement Hub (CEH) Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Engagement Hub (CEH) Market Outlook
India is reconfiguring its position as a critical delivery hub for CEH engineering talent and cloud infrastructure expansion. Braze leverages its real-time data streaming architecture to sustain product differentiation across high-velocity consumer brands. Klaviyo anchors its competitive position through deep e-commerce integration and first-party data specialization. Salesforce Marketing Cloud dominates enterprise accounts through extensive CRM connectivity and cross-channel orchestration capabilities.
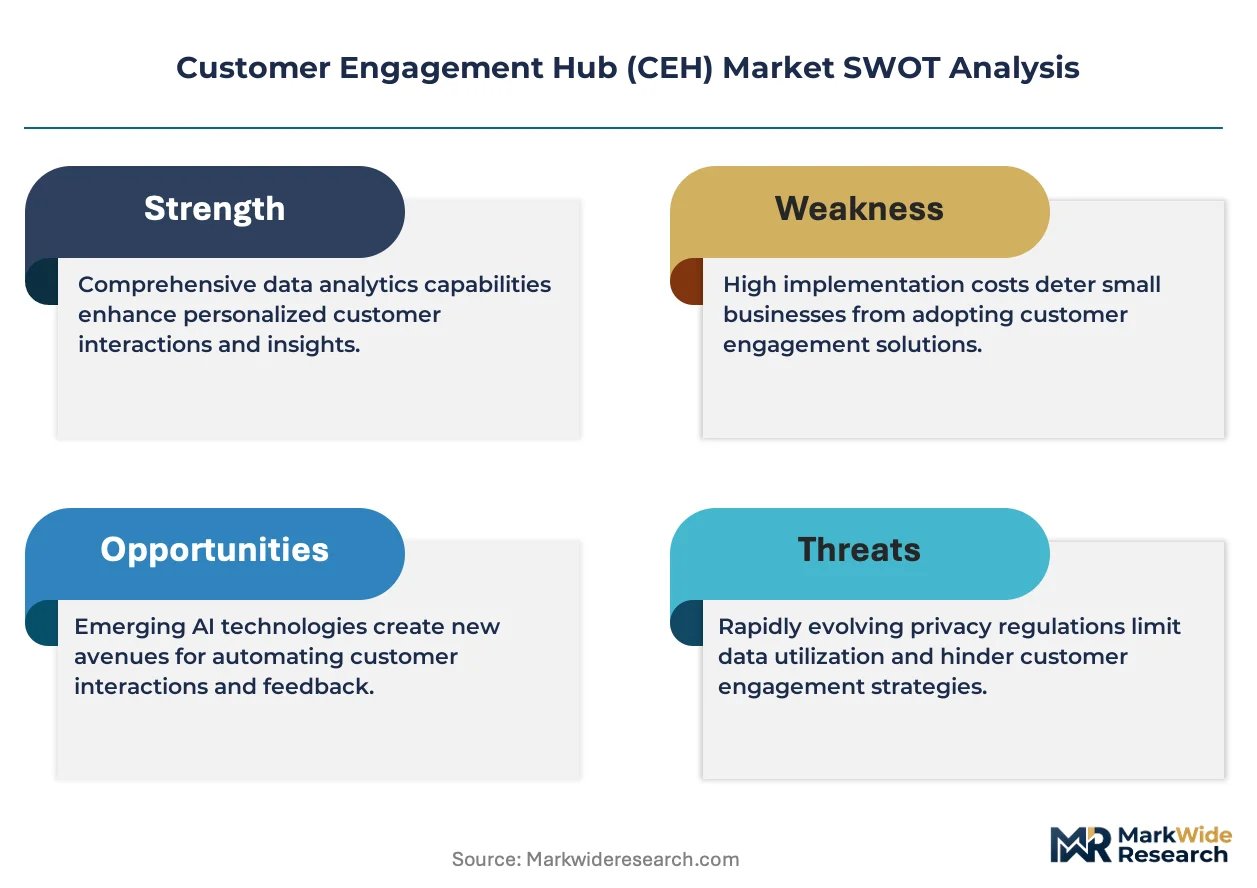
A customer engagement hub unifies consumer touchpoints across marketing, sales, and service channels into a single orchestration layer, typically processing behavioral signals through real-time decisioning engines with sub-100-millisecond latency thresholds to trigger personalized interventions. Its primary commercial purpose is to replace fragmented point solutions with coherent lifecycle management infrastructure. Cloud-based deployments now capture the dominant margin pool as enterprises abandon on-premises maintenance burdens for elastic consumption models. Email marketing functionality remains mature with compressed pricing, while AI-powered personalization within the feature set commands premium expansion rates due to measurable revenue attribution.
The EU AI Act and GDPR impose algorithmic transparency and data minimization requirements that reshape vendor development priorities across European deployments. In the United States, the FTC scrutinizes dark pattern design and deceptive automation disclosures, elevating compliance costs for engagement sequencing tools. Stakeholders must weigh regulatory fragmentation against platform consolidation bets, as jurisdictional divergence in AI governance threatens to splinter product roadmaps and inflate engineering overhead without clear standardization pathways.
Market Dynamics
Real-time decisioning latency requirements below 100 milliseconds are forcing infrastructure consolidation as enterprises abandon fragmented point solutions for unified orchestration layers that can process behavioral signals instantaneously.
Growth Catalysts
- EU AI Act:Mandates for explainable automation in European deployments accelerate vendor investment in transparent decisioning architectures that enterprises now demand worldwide.
- Retail banking modernization:Branch-digital integration initiatives across North American and Asian financial institutions drive substantial platform procurement for lifecycle management infrastructure.
- First-party data specialization:E-commerce operators invest heavily in owned data pipelines as third-party cookie deprecation renders external audience targeting economically unviable.
Market Restraints
- GDPR consent management complexity:Stringent data minimization requirements impose engineering overhead that slows deployment timelines and inflates implementation costs for European enterprises.
- Cloud infrastructure concentration:Dominant hyperscaler dependency creates single-point-of-failure risk for real-time streaming architectures that require sub-100-millisecond processing guarantees.
- Email pricing compression:Mature channel functionality faces commoditization pressure that constrains margin expansion despite overall platform value growth.
Strategic Opportunities
- India delivery hub expansion:Engineering talent concentration and cloud infrastructure investment position the country as a critical development and deployment center for CEH platforms.
- AI-powered personalization premium:Measurable revenue attribution capabilities command expansion rates well above baseline as enterprises prioritize intervention tools with direct ROI documentation.
- FTC dark pattern scrutiny:Elevated compliance requirements for engagement sequencing create competitive differentiation for vendors with embedded ethical design frameworks.
Industry Challenges
- Cross-functional talent scarcity:Shortage of engineers capable of bridging real-time data streaming, machine learning operations, and regulatory compliance slows product roadmap execution.
- Legacy CRM integration friction:Enterprises struggle to synchronize existing customer databases with modern decisioning engines without disrupting operational continuity.
- Jurisdictional AI governance divergence:Fragmented regulatory standards across the United States, European Union, and Asia-Pacific splinter engineering priorities and inflate roadmap complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Engagement Hub (CEH) Market |
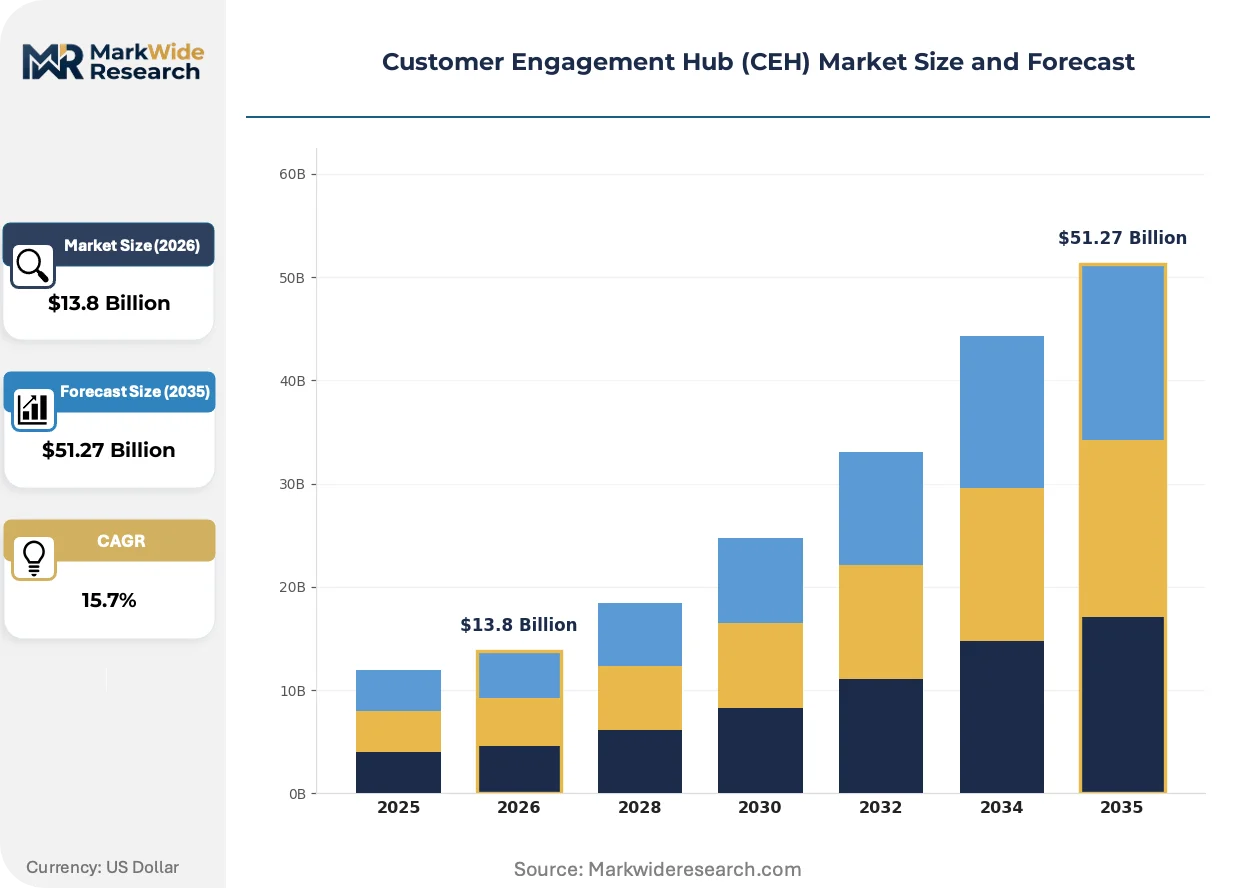
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $51.27 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: CRM, Chatbot, Social Media Management, Email Marketing Deployment Model: Cloud-based, On-premises, Hybrid, SaaS Customer Segment: Small Businesses, Enterprises, Non-profits, Government Agencies Feature Set: Personalization, Analytics, Automation, Integration |
| Companies Covered | Iterable, Klaviyo, Braze, CleverTap, Customer.io, HubSpot, MoEngage, Blueshift, Salesforce Marketing Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Engagement Hub (CEH) Market Strategic Shifts
Architectural shifts toward elastic cloud consumption and embedded algorithmic transparency are redefining competitive differentiation as buyers prioritize measurable attribution over feature breadth.
Real-time data streaming infrastructure is rendering obsolete batch-processed campaign management systems that cannot meet sub-100-millisecond latency thresholds for behavioral intervention. High-velocity consumer brands and financial services operators now mandate instantaneous decisioning as table stakes. Legacy campaign orchestration tools face accelerated displacement as buyers reject any architecture requiring hourly or daily data refreshes.
The EU AI Act's algorithmic transparency mandates compel vendors to embed explainable automation into core architectures rather than bolt-on compliance layers. European deployments now require documented decision trails for every automated customer intervention. Financial services and healthcare-adjacent verticals in Germany and France lead adoption of these transparent-by-design systems.
Enterprise buyers now unbundle point solutions in favor of coherent lifecycle management platforms that consolidate marketing, sales, and service touchpoints. Procurement committees prioritize vendors demonstrating cross-channel orchestration capabilities over specialized single-function tools. This consolidation preference is most visible in United States enterprise SaaS procurement, where AI governance investments accompany platform consolidation decisions.
Customer Engagement Hub (CEH) Market Segmentation
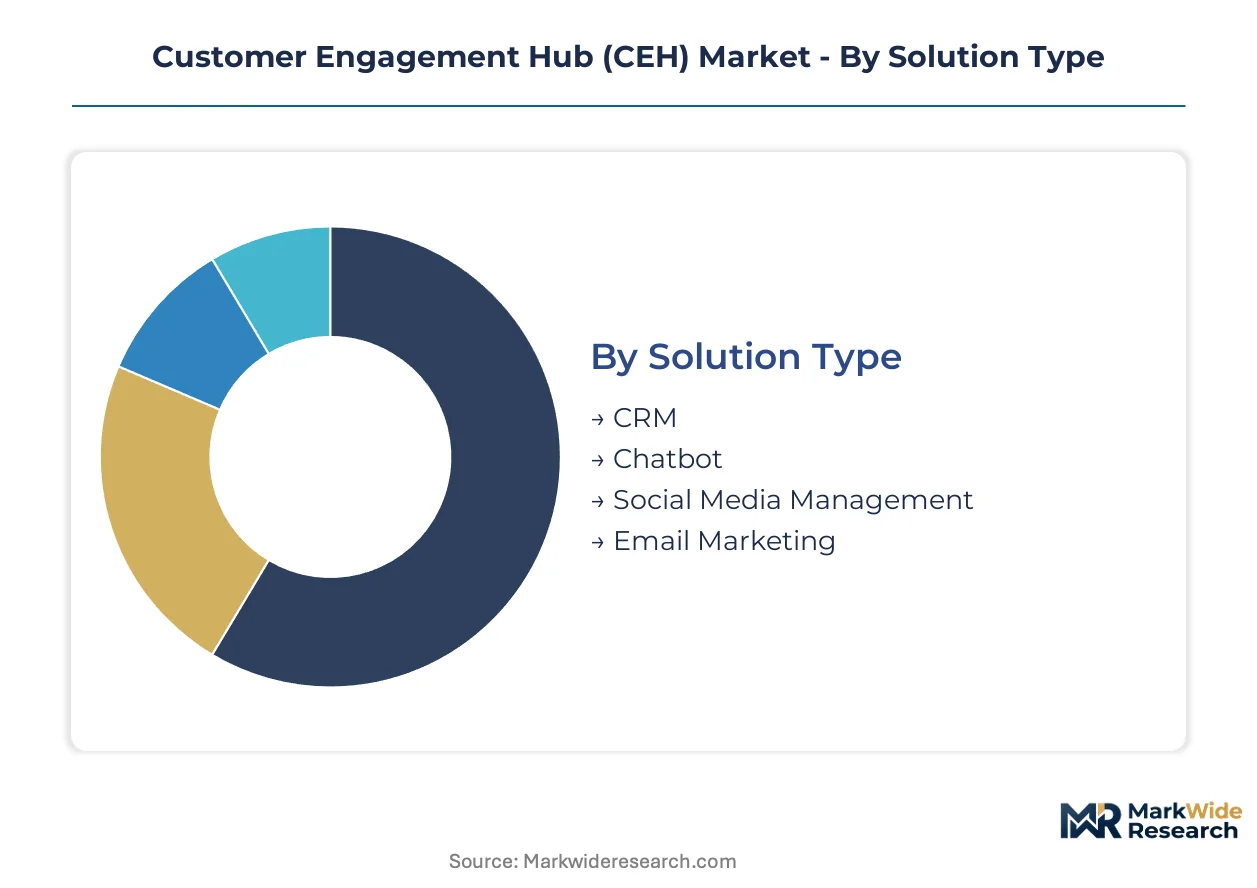
CEH procurement patterns diverge sharply across solution architectures and organizational scale. Deployment preferences and feature prioritization reflect fundamental trade-offs between operational control, regulatory exposure, and time-to-value expectations.
Solution Type:
Mature email marketing functionality now competes against emerging AI-native channels for platform investment priority.
- CRM:Core customer data infrastructure unifying transaction history, interaction logs, and lifecycle stage tracking into persistent identity graphs. Banking institutions in Germany and France drive procurement for branch-digital synchronization projects under ECB supervisory pressure.
- Chatbot:Conversational automation layer processing natural language queries through transformer-based models with escalating reasoning capabilities. Retail operators in the United States deploy these for 24/7 service coverage as labor costs compress margin structures.
- Social Media Management:Cross-platform publishing and listening tools aggregating public sentiment signals.
- Email Marketing:Mature broadcast and triggered messaging infrastructure with compressed pricing dynamics.
CRM retains volume leadership; chatbot holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure flexibility.
- Cloud-based:Elastic consumption architecture provisioning compute and storage through hyperscaler infrastructure. United States enterprise SaaS procurement concentrates here as IT organizations abandon datacenter maintenance obligations.
- SaaS:Fully managed software delivery with automatic updates and shared-tenant efficiency. Small and mid-market businesses in India select this tier for zero-infrastructure deployment velocity.
- On-premises:Self-managed installation requiring dedicated hardware and operational staffing.
- Hybrid:Partitioned architecture retaining sensitive data locally while bursting transactional workloads to cloud.
Cloud-based deployments dominate new procurement; SaaS climbs fastest among sub-$500M revenue enterprises.
Customer Segment:
Application intensity varies with organizational complexity and compliance surface area.
- Enterprises:Multi-divisional organizations requiring federated governance across dozens of national markets. Financial services conglomerates in the United States mandate these platforms for FTC-compliant engagement sequencing.
- Small Businesses:Owner-operated entities prioritizing rapid deployment over customization depth. E-commerce merchants in India adopt lightweight CEH tools as digital payment penetration accelerates.
- Non-profits:Donor-funded organizations with constrained technology budgets and volunteer-driven operations.
- Government Agencies:Public sector entities with stringent procurement protocols and sovereignty requirements.
Enterprises generate the majority of vendor revenue; small businesses are expanding most quickly.
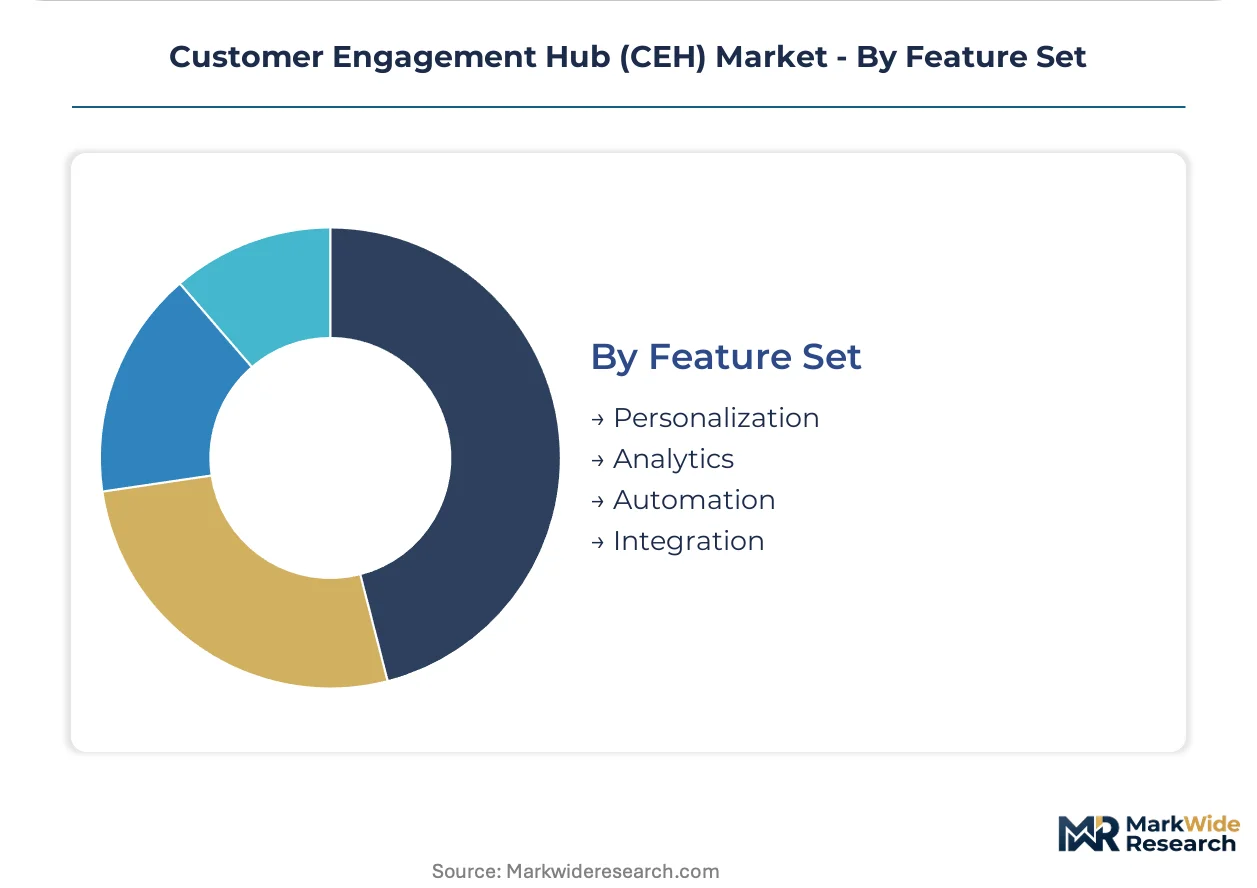
Feature Set:
Margin concentration follows measurable attribution capability rather than functional breadth.
- Personalization:Real-time decisioning engine selecting content variants based on behavioral propensity scoring. Consumer brands in the United States pay premium expansion rates for revenue-attributed intervention tools.
- Automation:Triggered workflow execution responding to customer journey events without manual intervention. GDPR-covered enterprises in France require documented decision trails for every automated touchpoint.
- Analytics:Dashboard and reporting infrastructure visualizing engagement performance metrics.
- Integration:API and connector ecosystem linking CEH to adjacent enterprise systems.
Personalization commands the highest pricing tier; automation gains share fastest among compliance-sensitive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEH procurement patterns diverge sharply across geographies. United States enterprises prioritize AI governance investments alongside platform consolidation. European buyers mandate explainable automation under regulatory pressure. India emerges as a delivery hub for engineering talent and cloud infrastructure expansion.
United States
Enterprise SaaS procurement and FTC-compliant engagement sequencing drive platform adoption. The FTC scrutinizes dark pattern design and deceptive automation disclosures, elevating compliance costs. Financial services conglomerates in New York and San Francisco mandate these platforms for lifecycle management infrastructure.
Germany
Retail banking modernization and branch-digital integration initiatives accelerate procurement. The EU AI Act mandates documented decision trails for every automated customer intervention. Frankfurt and Munich host financial services operators leading adoption of transparent-by-design systems.
France
GDPR-covered enterprises invest heavily in consent management and data minimization architectures. The CNIL enforces stringent data protection requirements that reshape vendor development priorities. Paris-based healthcare-adjacent operators drive demand for explainable automation.
India
Engineering talent concentration and cloud infrastructure investment position the country as a critical development center. The RBI supervises digital payment penetration that accelerates e-commerce merchant adoption. Bangalore and Hyderabad host delivery centers supporting global CEH platform engineering.
United Kingdom
Cross-channel orchestration capabilities and CRM connectivity drive enterprise procurement decisions. The Information Commissioner's Office enforces GDPR-aligned data protection standards. London's fintech cluster demands real-time decisioning infrastructure for high-velocity consumer engagement.
Customer Engagement Hub (CEH) Market Competitive Environment
Capability concentration sits with specialized real-time data streaming architects; scale advantage sits with established CRM incumbents. The vendor base organizes around three strategic archetypes: real-time streaming specialists, e-commerce-integrated platforms, and enterprise CRM extenders. Dominant competitive moves include strategic partnerships with hyperscaler infrastructure providers and portfolio diversification into adjacent marketing automation segments.
Within the real-time streaming tier, Braze and Iterable exemplify architectures designed for sub-100-millisecond behavioral intervention. Klaviyo occupies a position among e-commerce-integrated specialists with deep first-party data capabilities. Salesforce Marketing Cloud anchors the enterprise CRM extension archetype, leveraging extensive connectivity infrastructure.
| Leading Market Players |
|---|
| Iterable |
| Klaviyo |
| Braze |
| CleverTap |
| Customer.io |
| HubSpot |
| MoEngage |
| Blueshift |
| Salesforce Marketing Cloud |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific fiber-optic cable routes connecting Mumbai to Singapore and Los Angeles carry the bulk of real-time data streaming traffic for CEH platforms, with bandwidth cost differentials between these corridors directly shaping vendor margin structures and downstream pricing tiers for enterprise versus mid-market deployments.
Pricing Analysis
Geographic price spreads between United States enterprise deployments and Indian SaaS tiers exceed three-to-one ratios, reflecting hyperscaler infrastructure cost differentials and compliance overhead. The dominant pricing model follows subscription-based SaaS tiers scaled by message volume and data ingestion rates. Price differentiation rests on AI-powered personalization capabilities versus baseline automation, with GDPR-covered European buyers showing lowest price sensitivity due to mandated compliance investments. Pricing pressure intensifies in mature email marketing modules as vendors bundle these as loss-leaders to capture higher-margin real-time decisioning workloads.
Supply Chain Analysis
Extended payment terms from hyperscaler infrastructure providers now stretch to 90-120 days for established CEH vendors, compressing working capital cycles for emerging competitors. Geographic supply concentrates in the United States, India, and Ireland, where AWS, Azure, and GCP maintain primary compute regions. Raw material dependencies center on advanced GPUs for model training, high-throughput SSD storage arrays, and specialized network interface controllers. Single-source vulnerability in NVIDIA GPU supply creates bottleneck risk for AI-native personalization features. Distribution runs through direct enterprise sales teams for large accounts and self-serve digital channels for sub-$500M revenue segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CEH platforms represent a service-attach opportunity where ongoing model retraining and compliance audit subscriptions expand faster than core platform licensing, with managed service layers capturing recurring revenue multiples above pure software tiers.
For Market Incumbents: Harden real-time infrastructure resilience against hyperscaler concentration risk by diversifying across cloud regions and negotiating failover guarantees. Consolidate position through backward integration into proprietary data streaming layers that reduce third-party latency dependencies. Defensive priority centers on embedding EU AI Act-compliant explainability frameworks before regulatory deadlines tighten. For New Entrants and Emerging Players: Build out India-based engineering delivery capabilities to capture cost advantages in real-time decisioning development. White-space opportunity sits with mid-market e-commerce operators in Southeast Asia seeking first-party data specialization without enterprise complexity. Go-to-market angle emphasizes rapid time-to-value through pre-built vertical templates for retail banking and direct-to-consumer brands. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward vendors with embedded algorithmic transparency rather than bolt-on compliance modules. Long-term viability favors platforms demonstrating cross-channel orchestration depth with measurable revenue attribution. Acquisition target archetype: real-time streaming specialists with sub-100-millisecond latency architectures. Signal to watch: FTC consent decree patterns on dark pattern enforcement as predictor of compliance-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Infrastructure Expansion | Sub-100-millisecond latency guarantees displace batch-processed competitors in financial services procurement. |
| Explainable AI Architecture Investment | EU AI Act compliance embeds transparent decision trails that German banking regulators now mandate. |
| First-Party Data Pipeline Development | Owned data infrastructure insulates e-commerce operators from third-party cookie deprecation impacts. |
| Hyperscaler Partnership Deepening | Reserved capacity agreements with AWS and Azure secure processing guarantees for peak retail seasons. |
| Vertical Template Specialization | Pre-configured retail banking and healthcare workflows accelerate deployment velocity for compliance-sensitive buyers. |
Study Parameters
Cross-validation between primary interviews with CEH platform engineers and secondary analysis of hyperscaler capex disclosures anchors the qualitative findings. Stakeholder roles engaged include chief technology officers at consumer brands, IT procurement officers at retail banks, integration specialists at systems integrators, and data protection officers at GDPR-covered enterprises. Secondary sources span SEC filings from publicly traded vendors, EU AI Act implementation guidance from European Commission working groups, and RBI circulars on digital payment infrastructure. Bottom-up deployment estimates triangulate against top-down market sizing from cloud infrastructure spend allocations.
Calibration against historical adoption curves for marketing automation platforms informs the projection framework. Segmentation dimensions modeled span deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating price sensitivity differentials across buyer tiers. Industry-specific inputs include real-time latency requirement thresholds and EU AI Act compliance cost estimates.
Sensitivities concentrate around hyperscaler pricing changes, GDPR enforcement intensity variation, and FTC dark pattern ruling frequency. Forecasts assume continued third-party cookie deprecation and sustained retail banking modernization investment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Smart Signage Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Master Data Management Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Load Balancer Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Global Network Monitoring Software Market
Digital Solutions
Graph Technology Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Cloud Based Drug Discovery Platform Market