
 Asia-Pacific Computer Aided Engineering Market | 2026-2036
Asia-Pacific Computer Aided Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Computer Aided Engineering Market Insights
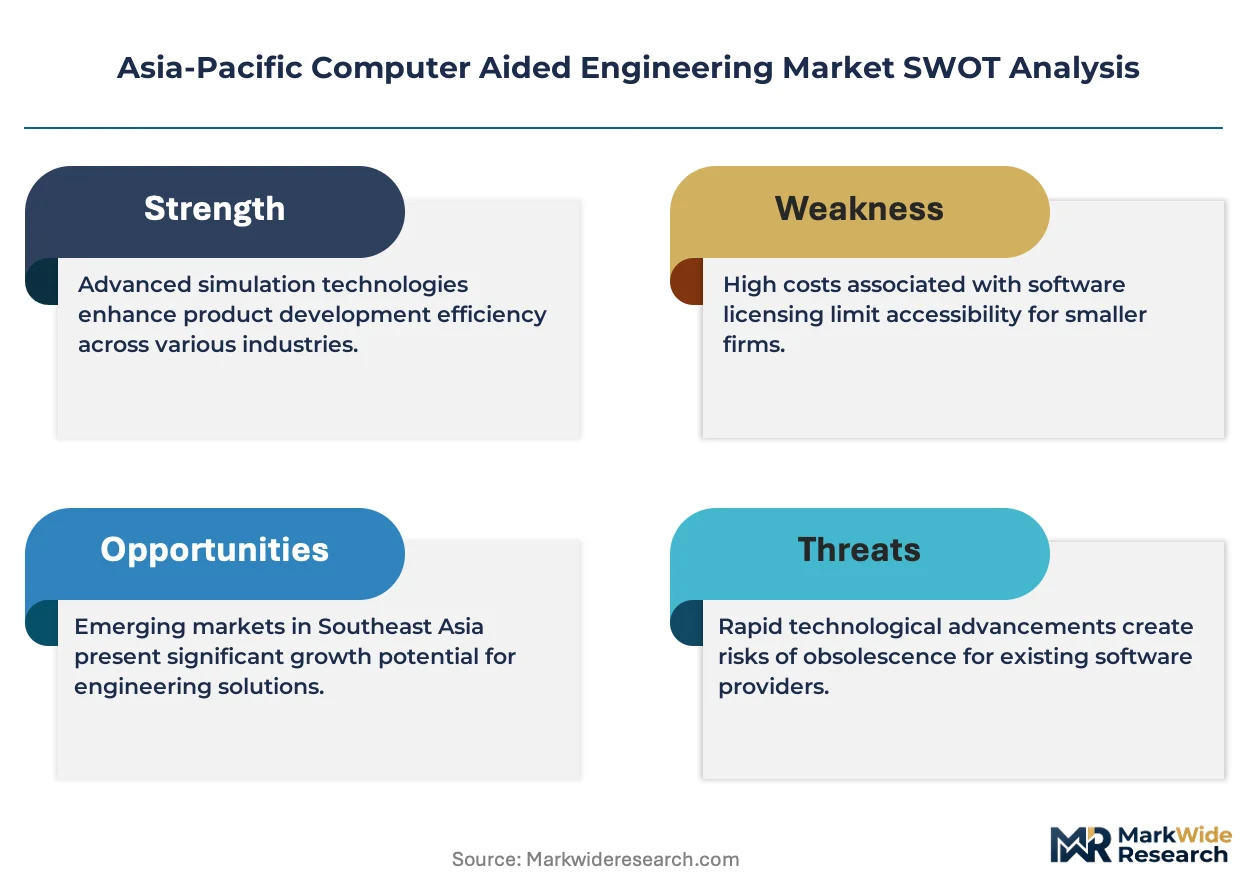
High-fidelity multiphysics simulation is reorganizing competitive dynamics across the Asia-Pacific Computer Aided Engineering Market. Siemens AG leverages deep vertical integration into industrial automation to anchor its position in automotive powertrain simulation. Dassault Systemes SE differentiates through product lifecycle management linkages that extend its reach beyond standalone analysis into integrated design environments. Altair Engineering Inc competes aggressively on solver speed and cloud accessibility, occupying a distinct tier for mid-market manufacturers seeking subscription flexibility.
Computer Aided Engineering encompasses finite element analysis, computational fluid dynamics, and multiphysics simulation tools that solve partial differential equations on discretized geometries to predict structural, thermal, and electromagnetic behavior before physical prototyping. These systems operate on mesh densities exceeding millions of elements for automotive crashworthiness validation and semiconductor thermal cycling prediction. Simulation software commands the deepest margin pools due to solver licensing premiums and specialized physics modules, while cloud-based deployment grows fastest as Japanese and South Korean manufacturers migrate HPC workloads away from capital-intensive on-premises clusters. Aerospace application demand lags automotive OEMs in absolute volume but sustains premium pricing through certification-grade accuracy requirements.
Japan's METI promotes digital twin standards through its Society 5.0 framework, while China's MIIT enforces smart manufacturing benchmarks that mandate CAE integration for advanced industrial bases. South Korea's MFDS and KATS align medical device and automotive safety regulations with simulation-validated design histories, tightening compliance documentation requirements. India's BIS progressively adopts ISO 10303 STEP standards for product data interoperability, easing cross-border engineering collaboration but raising software certification burdens. Stakeholders must weigh sovereign cloud mandates against solver performance trade-offs as data localization rules proliferate across the region.
Market Dynamics
Automotive OEMs in Japan and South Korea are compressing simulation cycles for electric vehicle thermal management, forcing software vendors to rearchitect solver licensing models around consumption-based metering rather than perpetual seats.
Growth Catalysts
- MIIT Smart Manufacturing Mandates:China's Ministry of Industry and Information Technology requires digital twin integration in advanced industrial bases, compelling state-owned enterprises to expand CAE procurement for factory simulation.
- EV Powertrain Simulation:Battery thermal runaway modeling now precedes every major platform launch in South Korea's automotive corridor, pulling high-fidelity electrochemistry solvers into standard design workflows.
- Semiconductor Packaging Stress Analysis:Advanced substrate warpage prediction for chiplet architectures drives solver demand in Taiwan's Hsinchu Science Park electronics cluster.
Market Restraints
- GPU Compute Cost Volatility:NVIDIA H100 cluster pricing fluctuations strain cloud-based simulation budgets for mid-tier Indian engineering services firms.
- Sovereign Data Localization:China's Cybersecurity Law and India's draft Data Protection Bill fragment solver deployment architectures, degrading cross-border collaboration efficiency.
- Open-Source Alternative Maturation:CalculiX and OpenFOAM community editions capture basic structural and CFD workloads from price-sensitive Tier-2 suppliers.
Strategic Opportunities
- Vietnam Electronics Manufacturing:Foxconn and Luxshare expansions in Bac Ninh Province create first-mover openings for mold flow and thermal simulation services.
- AI-Augmented Mesh Generation:Neural network-driven geometry discretization converges with traditional FEA workflows, collapsing preprocessing timelines for complex automotive assemblies.
- Indonesia Nickel Processing Simulation:Battery supply chain investments in Sulawesi require hydrometallurgical reactor modeling capabilities currently undersupplied in Southeast Asia.
Industry Challenges
- Multiphysics Talent Scarcity:Coupled thermal-structural-electromagnetic simulation expertise concentrates in Tokyo, Seoul, and Shanghai, leaving secondary cities dependent on remote consulting arrangements.
- Legacy CAD-CAE Integration Debt:Japanese automotive suppliers maintain decades-old geometry kernels that resist direct API linkage to modern cloud-native solvers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Computer Aided Engineering Market |
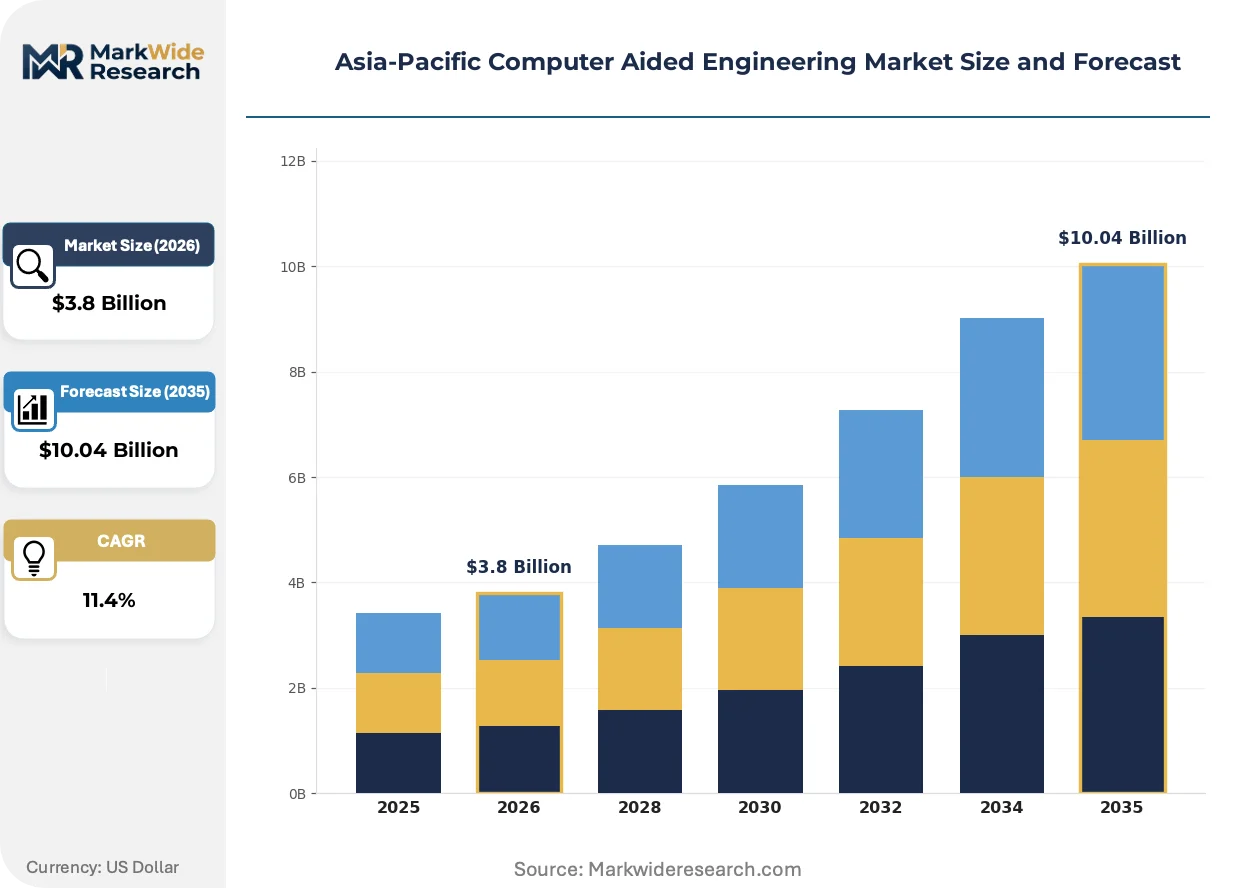
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Software, Design Software, Analysis Software, Testing Tools Application: Aerospace, Automotive OEMs, Consumer Electronics, Industrial Equipment End User: Manufacturers, Research Institutions, Engineering Firms, Educational Institutions Deployment: On-Premises, Cloud-Based, Hybrid, License-Based |
| Companies Covered | Bentley Systems Inc, Siemens AG, Ansys Inc, ESI Group, Hexagon AB, Altair Engineering Inc, Dassault Systemes SE, Aveva Group, Autodesk Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Computer Aided Engineering Market Trends and Innovations
Simulation fidelity requirements are splitting vendor strategies between GPU-accelerated cloud solvers and on-premises HPC clusters, with procurement patterns diverging sharply by buyer size and data sovereignty posture.
Physics-informed neural networks for surrogate modeling are bifurcating the traditional solver market. Automotive crash safety teams at Hyundai and Toyota deploy PINNs for early-stage design space exploration, compressing iteration cycles from weeks to hours. This bifurcation squeezes mid-range implicit solver vendors who lack either the cloud scale of hyperscaler partnerships or the academic credibility of open-source alternatives.
METI's Society 5.0 implementation roadmap mandates interoperable digital twin standards across Japanese manufacturing supply chains. The framework requires STEP AP242-compliant geometry exchange and standardized sensor telemetry formats, forcing CAE vendors to recertify import-export modules. Medical device manufacturers under PMDA jurisdiction face the tightest compliance timelines, with simulation validation documentation now required for Class III implantable submissions.
Subscription consumption models are displacing perpetual licensing across South Korean and Australian engineering consultancies. Mid-market buyers favor solver-hours metering over capital-intensive seat purchases, particularly for sporadic nonlinear dynamics workloads. This shift concentrates revenue predictability with vendors offering elastic cloud infrastructure, while penalizing traditional on-premises specialists dependent on maintenance renewal cycles.
Asia-Pacific Computer Aided Engineering Market Segmentation
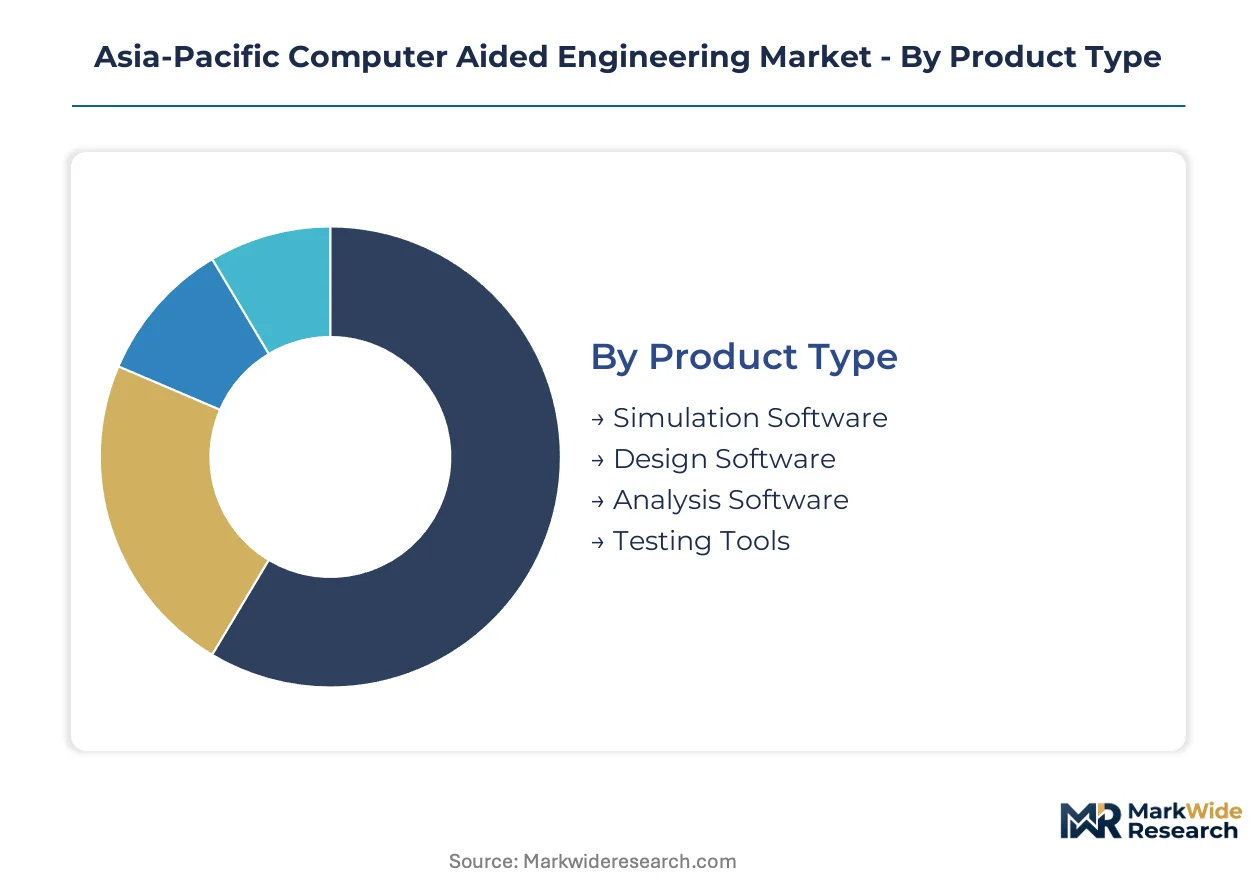
Segmentation in the Asia-Pacific Computer Aided Engineering Market reveals divergent channel economics. Software vendors route high-fidelity solvers through direct enterprise sales while pushing standardized modules via cloud marketplaces and regional distributors.
Product Type:
Channel mix varies sharply by product complexity, with perpetual-licensed simulation suites flowing through direct vendor relationships and lighter design tools penetrating via value-added resellers.
- Simulation Software:Finite element analysis and computational fluid dynamics solvers with electrochemistry modules for battery thermal runaway modeling. Japanese automotive OEMs in Toyota City and South Korean battery manufacturers in Gyeonggi Province drive procurement through multi-year enterprise agreements with solver-hour metering.
- Design Software:CAD-integrated geometry preparation and preprocessing environments that feed mesh data into downstream analysis workflows. China's Yangtze River Delta electronics cluster concentrates demand as MIIT-mandated digital twin standards force concurrent engineering adoption.
- Analysis Software:Post-processing visualization and results interpretation tools deployed by Indian engineering services firms in Bengaluru and Hyderabad.
- Testing Tools:Hardware-in-the-loop validation systems bridging virtual simulation with physical prototype verification.
By volume, Simulation Software leads. By growth pace, Cloud-integrated Design Software variants are expanding most quickly.
Application:
Cost tier stratification separates certification-grade aerospace deployments from high-volume automotive seats and entry-level electronics subscriptions.
- Automotive OEMs:Crashworthiness validation and electric powertrain thermal management dominate solver consumption. South Korean manufacturers under MFDS jurisdiction require simulation-validated design histories for every platform launch, compressing procurement cycles and favoring consumption-based licensing.
- Aerospace:Structural integrity and aerodynamic certification at precision thresholds exceeding automotive benchmarks. Premium pricing persists due to FAA-EASA aligned documentation requirements and extended validation timelines.
- Consumer Electronics:Semiconductor packaging stress analysis and thermal cycling prediction for advanced substrate architectures in Taiwan's Hsinchu Science Park.
- Industrial Equipment:Heavy machinery durability simulation with lower mesh density requirements and correspondingly reduced solver licensing premiums.
Automotive OEMs command the deepest revenue pools. Aerospace maintains the steepest margin structure per seat.
End User:
Customer type determines deployment architecture, with manufacturers favoring on-premises HPC clusters and engineering firms gravitating toward elastic cloud consumption.
- Manufacturers:Captive engineering teams at Japanese and South Korean automotive and electronics conglomerates operating dedicated solver farms for proprietary model security. Sovereign data localization mandates under China's Cybersecurity Law reinforce on-premises preferences despite higher capital intensity.
- Engineering Firms:Mid-tier consultancies in India and Australia purchasing solver-hours for sporadic nonlinear dynamics workloads without perpetual license overhead.
- Research Institutions:University laboratories and national research centers accessing academic licensing tiers with restricted commercial application rights.
- Educational Institutions:Training and curriculum deployment through vendor-sponsored campus programs building future practitioner familiarity.
Manufacturers generate the largest absolute procurement value. Engineering Firms are gaining share fastest as subscription flexibility displaces capital expenditure models.
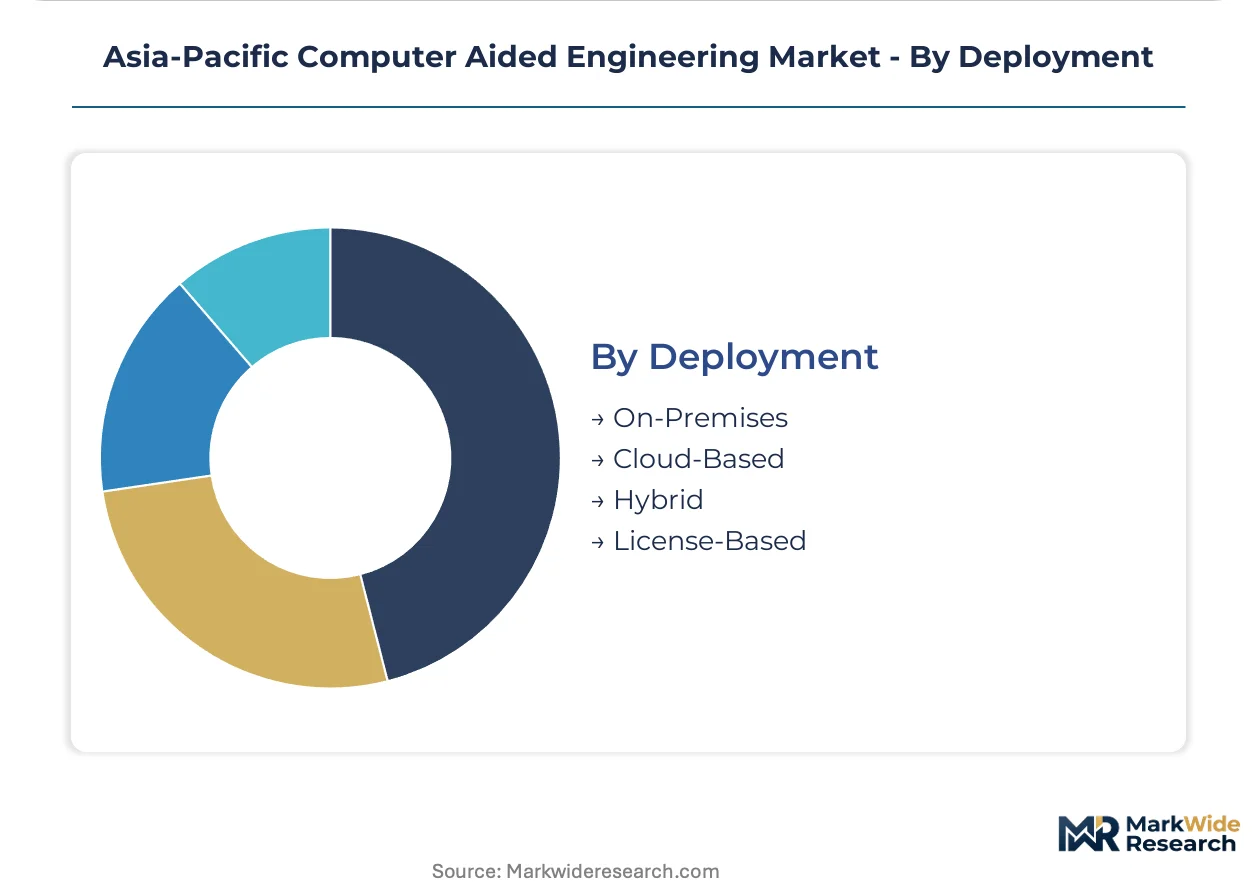
Deployment:
Maturity gradients separate established on-premises installations from emerging hybrid architectures navigating data sovereignty constraints.
- Cloud-Based:GPU-accelerated solver instances scaling elastically with project demand. Japanese manufacturers migrate HPC workloads to hyperscaler partnerships as METI's Society 5.0 framework clarifies interoperability standards, though India's draft Data Protection Bill creates deployment uncertainty.
- On-Premises:Traditional capital-intensive clusters retaining preference for classified defense and proprietary automotive programs where model confidentiality outweighs operational flexibility.
- Hybrid:Split architectures preprocessing sensitive geometries locally while offloading compute-intensive solves to sovereign cloud instances.
- License-Based:Perpetual seat purchases with maintenance renewals, increasingly restricted to aerospace certification workflows requiring version-locked solver validation.
On-Premises retains the installed base majority. Cloud-Based deployment is climbing the fastest as consumption metering aligns procurement with project cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solver licensing revenue concentrates in three national manufacturing corridors where automotive and electronics OEMs maintain captive engineering centers. Data localization mandates and sovereign cloud requirements are fragmenting deployment architectures across these markets.
China
MIIT smart manufacturing mandates compel state-owned enterprises to expand digital twin procurement for factory simulation. The Cybersecurity Law enforces data localization, degrading cross-border collaboration efficiency for multinational engineering teams. Yangtze River Delta electronics clusters drive electrochemistry solver demand for semiconductor packaging stress analysis.
Japan
METI's Society 5.0 framework mandates interoperable digital twin standards across manufacturing supply chains. PMDA jurisdiction tightens compliance timelines for medical device simulation validation documentation. Toyota City automotive OEMs compress crashworthiness simulation cycles through GPU-accelerated cloud solver migration.
South Korea
MFDS and KATS regulations align medical device and automotive safety standards with simulation-validated design histories. Battery thermal runaway modeling precedes every major EV platform launch in Gyeonggi Province. Hyundai and Samsung SDI procurement favors consumption-based solver licensing over perpetual seats.
India
BIS adoption of ISO 10303 STEP standards eases cross-border engineering collaboration while raising software certification burdens. Draft Data Protection Bill creates deployment uncertainty for cloud-based simulation architectures. Tamil Nadu automotive corridor and Bengaluru engineering services firms drive sporadic nonlinear dynamics solver-hour consumption.
Taiwan
Advanced substrate warpage prediction for chiplet architectures generates concentrated solver demand. Hsinchu Science Park electronics manufacturers require high-fidelity thermal cycling prediction for semiconductor packaging. Local foundries maintain on-premises HPC clusters for proprietary model confidentiality.
Asia-Pacific Computer Aided Engineering Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Computer Aided Engineering Market. The vendor base organizes into three tiers: integrated industrial automation conglomerates, specialized simulation software houses, and cloud-native platform providers. Two dominant competitive moves are reshaping positioning: hyperscaler partnerships for elastic GPU infrastructure and academic licensing programs building practitioner familiarity in university laboratories.
Within the integrated automation tier, Siemens AG and Dassault Systemes SE occupy positions where industrial software portfolios extend into captive manufacturing customer bases. Altair Engineering Inc exemplifies the cloud-native archetype competing on solver speed and subscription flexibility for mid-market manufacturers. These three anchors represent distinct strategic postures—vertical integration, product lifecycle management linkage, and consumption-based metering—without any single archetype commanding uniform preference across Japanese, South Korean, and Chinese procurement contexts.
| Leading Market Players |
|---|
| Bentley Systems Inc |
| Siemens AG |
| Ansys Inc |
| ESI Group |
| Hexagon AB |
| Altair Engineering Inc |
| Dassault Systemes SE |
| Aveva Group |
| Autodesk Inc |
| Others |
Pricing and Supply Chain Analysis
GPU-accelerated cloud solver instances displacing on-premises HPC clusters simultaneously redistributes procurement geography toward hyperscaler data centers and compresses pricing premiums for perpetual seat licenses. This substitution dynamic concentrates buyer leverage among Japanese and South Korean automotive OEMs while fragmenting revenue predictability for traditional on-premises vendors.
Pricing Analysis
METI's Society 5.0 framework dictates the pricing tier structure across Japanese manufacturing supply chains. Three-tier pricing structure across certification-grade, enterprise-standard, and academic-restricted levels separates aerospace validation workflows from mid-market automotive subscriptions. Cost compression in the academic tier intensifies because open-source CalculiX and OpenFOAM alternatives capture basic structural workloads. Engineering consultancies in India and Australia exhibit highest price sensitivity due to sporadic project demand, while Japanese automotive OEMs under PMDA jurisdiction show lowest sensitivity for certification-grade solver accuracy.
Supply Chain Analysis
Taiwan Strait cable systems and transpacific fiber routes constitute critical chokepoints for cloud-based solver delivery across the Asia-Pacific region. Software development concentrates in the United States, Germany, and France, while GPU hardware fabrication draws from Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for NVIDIA H100 clusters subject to export control fluctuations. Distribution runs through direct enterprise sales for high-fidelity perpetual licenses and hyperscaler marketplaces for consumption-metered cloud instances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Japanese and South Korean automotive OEMs as procurement consolidation around consumption-based metering displaces fragmented perpetual licensing decisions. This shift fragments vendor pricing power while elevating solver performance and data sovereignty as decisive selection criteria.
For Market Incumbents: Compound defensive positioning through backward integration into GPU infrastructure partnerships and captive certification investment for PMDA-aligned medical device validation workflows. Threat from cloud-native platform providers with elastic consumption models demands channel control reinforcement in South Korean battery manufacturing corridors. Priority lever rests on solver-hour metering architectures that match procurement flexibility expectations at Hyundai and Samsung SDI. For New Entrants and Emerging Players: Mid-tier Indian engineering services underpenetration by high-fidelity multiphysics specialists opens immediate service-layer opportunity. White-space targets include Tamil Nadu automotive corridor consulting arrangements and Bengaluru cloud-native solver deployment for sporadic nonlinear dynamics workloads. Most penetrable segment comprises price-sensitive Tier-2 suppliers migrating from open-source alternatives. Go-to-market angle emphasizes subscription flexibility without perpetual license overhead. For Investors and Strategic Acquirers: The market sits at a cloud-transition phase that favors platform-integrated specialists over standalone solver vendors. Long-term viability over the coming decade hinges on hyperscaler partnership depth and academic licensing program scale. Acquisition target archetype comprises regional engineering consultancies with captive customer relationships in Vietnam's emerging electronics manufacturing corridor. Signal to watch is MIIT enforcement intensity for digital twin standards across Chinese state-owned enterprises.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Partnership Formation | Elastic GPU infrastructure access secures consumption-metering revenue predictability for Japanese automotive OEM procurement. |
| Academic Licensing Program Expansion | University laboratory partnerships in Seoul and Tokyo build practitioner familiarity that converts to enterprise seat demand. |
| Certification Module Investment | PMDA-aligned validation documentation capabilities capture premium pricing from medical device manufacturers under tightened compliance timelines. |
| Regional Consulting Acquisition | Vietnam electronics manufacturing corridor presence delivers first-mover mold flow and thermal simulation service relationships. |
| Open-Source Integration Layer | API linkage to CalculiX and OpenFOAM community editions captures price-sensitive Tier-2 supplier migration without full solver redevelopment. |
Research Methodology
Initial hypotheses were tested against primary input from CAE software procurement directors, automotive platform engineering leads, semiconductor packaging simulation specialists, and cloud infrastructure architects at hyperscaler partnerships and refined through secondary validation. Primary fieldwork encompassed structured interviews across Toyota City, Gyeonggi Province, and the Yangtze River Delta electronics cluster. Secondary sources included MIIT smart manufacturing policy documents, METI Society 5.0 implementation roadmaps, SEC filings from listed simulation vendors, and hyperscaler capex disclosure statements. Bottom-up solver licensing revenue estimates triangulated against top-down manufacturing R&D expenditure allocations.
Variance decomposition across deployment model, end-user organization size, application vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed product type complexity tiers, certification-grade accuracy requirements, and sovereign data localization posture. CAGRs were derived from elasticity-adjusted adoption curves calibrated to MIIT mandate implementation schedules and METI standardization timelines. Industry-specific forecast inputs incorporated battery thermal runaway modeling penetration rates and chiplet architecture substrate warpage prediction solver demand from Taiwan's Hsinchu Science Park.
Forecasts assume regulatory continuity in MIIT smart manufacturing mandates, METI Society 5.0 interoperability requirements, and India's draft Data Protection Bill provisions; material policy shifts would require re-modeling cloud deployment architecture preferences and cross-border collaboration efficiency assumptions. Practitioners should keep alternative scenarios live as sovereign data localization enforcement intensity and GPU export control frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Recommendation Search Engine Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Online Dating Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Chile ICT Market