
 Microneedle Drug Delivery Systems Market | 2026-2036
Microneedle Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Microneedle Drug Delivery Systems Market Intelligence
The capability gap between precision-manufacturing scale and clinical-stage agility is rotating competitive capital allocation across the microneedle landscape. 3M Company leverages its materials science infrastructure to dominate industrial-scale polymer microneedle production. Zosano Pharma Corporation anchors its position through specialized transdermal patch-microneedle hybrid platforms for CNS indications. Vaxxas Pty Ltd. competes via high-density microarray technology optimized for vaccine thermostability in tropical distribution channels.
Microneedle drug delivery systems constitute minimally invasive devices incorporating arrays of sub-millimeter projections—typically 25–2000 micrometers in length—that breach the stratum corneum to enable transdermal administration of biologics, vaccines, and small molecules without reaching dermal nerve endings. Dissolvable microneedles fabricated from hyaluronic acid or polyvinylpyrrolidone matrices command expanding share in vaccination applications where cold-chain elimination drives value. Silicon-based solid microneedles retain dominance in cosmetic procedures and dermatological research where reusability and precise mechanical control justify higher per-unit economics.
FDA combination product regulations, EMA medical device directives under MDR frameworks, and ISO 10993 biocompatibility standards collectively govern market access timelines and clinical evidence requirements for microneedle platforms. The FDA's emerging guidance on closed-loop microneedle-based glucose monitoring is reshaping diabetes management product development priorities. Stakeholders must monitor evolving reimbursement classifications for home-care administration versus clinical settings as payors reassess value-based frameworks for transdermal biologic delivery.
Market Dynamics
The convergence of cold-chain elimination imperatives with precision polymer manufacturing is compressing development timelines for dissolvable microneedle platforms. Biopharmaceutical contract manufacturers are reallocating capital from traditional syringe filling lines toward micro-molding infrastructure capable of sub-100-micron feature resolution.
Growth Catalysts
- WHO prequalification pathways:Streamlined technical dossier requirements for thermostable vaccine formats are accelerating regulatory submissions from manufacturers in tropical distribution corridors.
- Hyaluronic acid matrix advances:Tunable degradation kinetics in biocompatible polymers now enable controlled release profiles previously achievable only through implantable depot systems.
- Japan's at-home administration infrastructure:Reimbursement codes for patient-administered transdermal biologics are expanding addressable markets beyond clinical settings.
Market Restraints
- Silicon wafer supply concentration:Solid microneedle fabrication depends on semiconductor-grade substrate availability concentrated in East Asian foundry networks.
- ISO 10993-10 sensitization testing costs:Extended dermal irritation protocols for novel polymer matrices add validation timelines incompatible with accelerated vaccine development cycles.
- Autoinjector format substitution:Pre-filled syringe systems with integrated needle safety mechanisms retain preference in institutional settings where sharps disposal infrastructure exists.
Strategic Opportunities
- India's CDMO expansion:Domestic polymer processing capabilities under PLI scheme incentives position the country for cost-optimized dissolvable microneedle export manufacturing.
- Continuous liquid interface production:Additive manufacturing convergence with photocurable resins enables patient-specific array geometries for personalized dosing regimens.
- Direct-to-pharmacy distribution:Bypassing wholesale channels for temperature-stable formats reduces handling complexity and margin leakage in last-mile vaccine delivery.
Industry Challenges
- Micro-molding tool steel expertise:Cavitation-resistant mold materials capable of maintaining 25-micron tolerances across millions of cycles command premium sourcing timelines from specialized European suppliers.
- Combination product quality agreement complexity:Alignment between device CMOs and drug substance manufacturers on batch release specifications requires novel contractual frameworks without established precedent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microneedle Drug Delivery Systems Market |
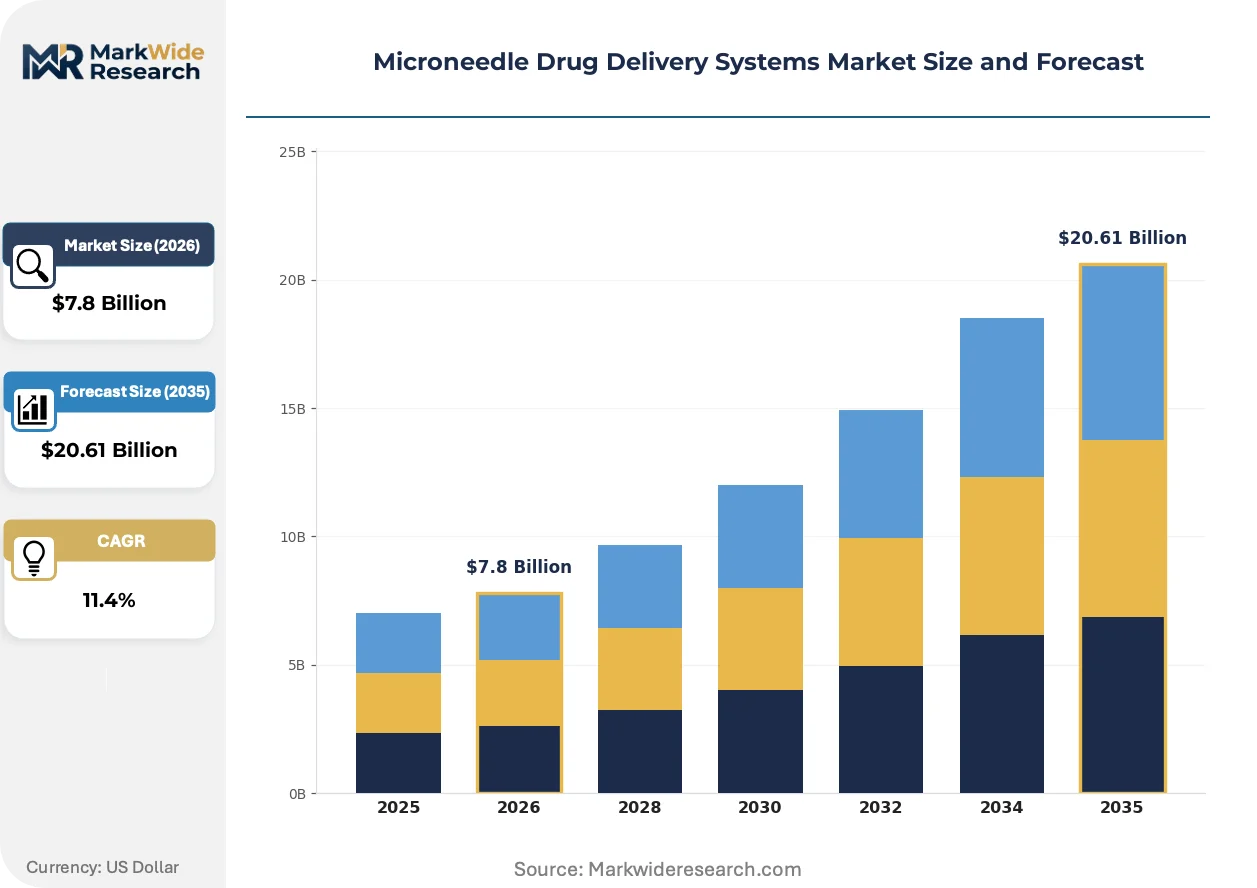
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Microneedles, Dissolvable Microneedles, Coated Microneedles, Biodegradable Microneedles Material: Silicon, Polymer, Metals, Glass End User: Hospitals, Clinics, Home Care Settings, Research Laboratories Application: Vaccination, Diabetes Management, Pain Management, Cosmetic Procedures |
| Companies Covered | Zosano Pharma Corporation, Vaxxas Pty Ltd., 3M Company, Terumo Corporation, Corium International Inc., Becton Dickinson and Company, Raphas Co. Ltd., LTS Lohmann Therapie-Systeme AG, NanoPass Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microneedle Drug Delivery Systems Market Strategic Shifts & Innovations
Materials science breakthroughs are collapsing the traditional boundary between device manufacturing and pharmaceutical formulation. The convergence of tunable polymer degradation with high-throughput micro-molding is enabling therapeutic categories previously excluded from transdermal delivery.
Photocurable thiol-ene resin systems are supplanting traditional thermoplastic micromolding for complex hierarchical geometries in dissolvable microneedle arrays. Vaccine developers at contract manufacturing organizations are adopting these resins for rapid prototyping cycles measured in days rather than months. The structural consequence is compression of IND-enabling timeline assumptions for novel biologic formats.
EMA's 2023 MDR guidance on borderline classification for drug-device integral products is clarifying technical documentation requirements for microneedle-patch combinations. The industrial consequence is reduced regulatory uncertainty for sponsors pursuing centralized marketing authorization procedures. Oncology supportive care applications in Germany and France are responding with expanded clinical trial investments in chemotherapy-induced nausea transdermal formulations.
Hospital procurement committees are consolidating supplier relationships around platform technologies capable of spanning multiple therapeutic indications. The group purchasing organization channel for transdermal delivery systems is displacing fragmented direct contracting between individual therapeutic area buyers and niche device specialists. This concentration is most visible in United States integrated delivery networks where formulary standardization incentives favor multi-indication platform vendors.
Microneedle Drug Delivery Systems Market Segmentation
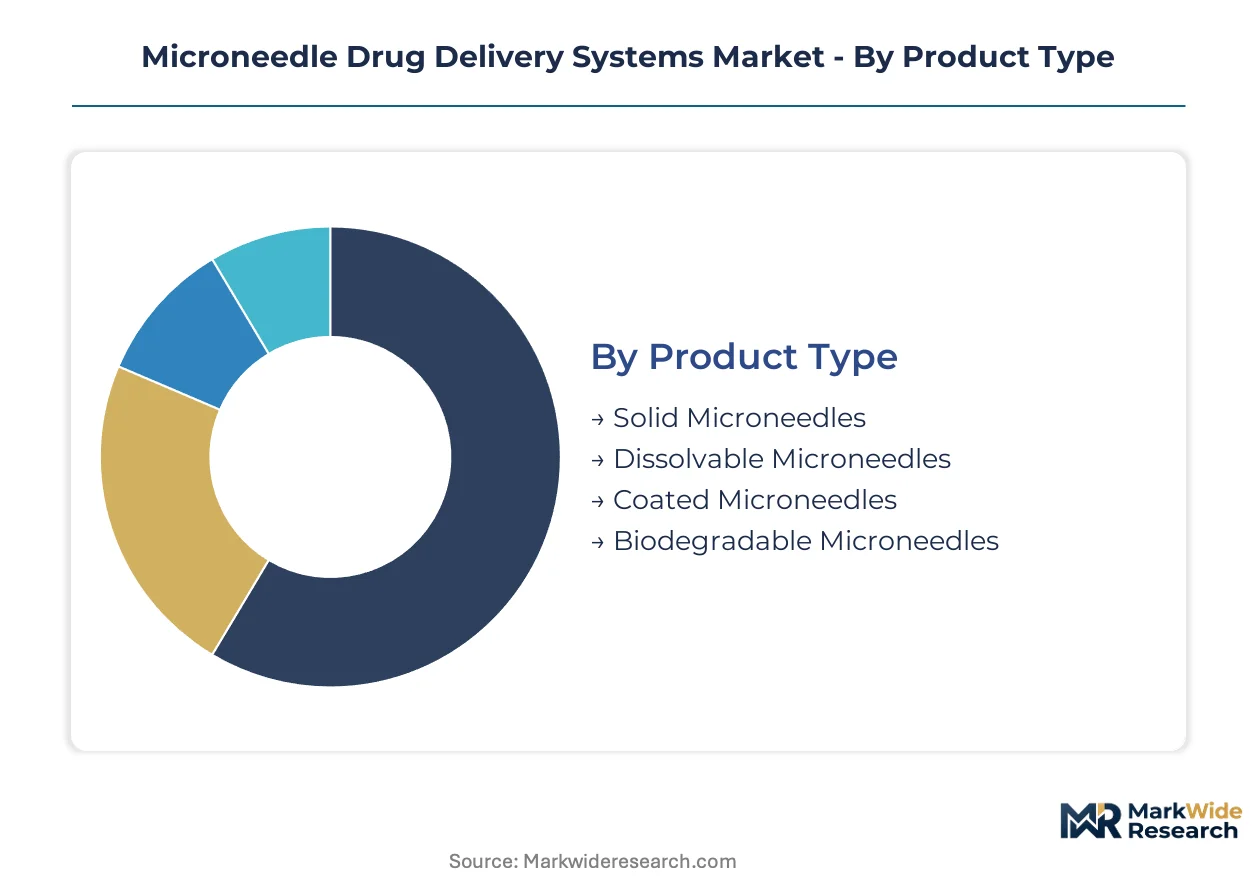
Microneedle platforms diverge sharply in regulatory classification, manufacturing complexity, and reimbursement pathways. Segment boundaries determine whether sponsors pursue FDA combination product review, EMA medical device certification, or streamlined WHO prequalification routes.
Product Type:
FDA and EMA classify microneedle arrays differently based on mechanical integrity post-insertion, altering clinical evidence requirements and commercial timelines.
- Dissolvable Microneedles:Hyaluronic acid and polyvinylpyrrolidone matrices degrade within minutes of skin insertion, eliminating sharps disposal requirements. Vaccination programs in tropical distribution corridors favor this format for thermostability advantages and cold-chain elimination.
- Solid Microneedles:Silicon or metal arrays maintain structural integrity for reusable applications. Dermatological research and cosmetic procedures in Germany and Japan concentrate demand here due to precise mechanical control and established reimbursement codes.
- Coated Microneedles:Drug-loaded surface coatings enable bolus delivery without matrix dissolution. Pain management applications in United States hospital systems drive procurement volumes.
- Biodegradable Microneedles:Polylactic acid and polycaprolactone constructs balance controlled degradation with mechanical robustness. Research laboratories in academic medical centers evaluate these for sustained-release oncology supportive care.
Solid microneedles handle the majority of throughput; dissolvable microneedles are expanding most quickly on share.
Material:
Raw material selection governs ISO 10993 biocompatibility testing scope, micro-molding process parameters, and end-use application eligibility.
- Silicon:Semiconductor-grade substrates enable sub-50-micron feature resolution through deep reactive ion etching. Foundry capacity constraints in East Asian supply networks limit expansion for solid microneedle manufacturers.
- Polymer:Hyaluronic acid, polyvinylpyrrolidone, and photocurable thiol-ene resins dominate dissolvable platform production. Tunable degradation kinetics now match implantable depot release profiles for biologic delivery.
- Metals:Titanium and stainless steel arrays serve reusable diagnostic and cosmetic applications where mechanical durability outweighs single-use convenience.
- Glass:Borosilicate formulations enable optical transparency for combined imaging-delivery platforms in research settings.
Polymer substrates command the steepest expansion trajectory; silicon retains the highest revenue concentration per unit.
End User:
Site-of-care determination shapes device design priorities, packaging requirements, and distribution channel economics.
- Home Care Settings:Patient-administered platforms require intuitive applicator mechanisms and minimal training. Japan's reimbursement infrastructure for at-home biologic administration accelerates format adoption.
- Hospitals:Integrated delivery networks in the United States consolidate procurement around multi-indication platform vendors capable of spanning vaccination, diabetes management, and pain protocols.
- Clinics:Outpatient facilities favor pre-filled, single-use formats with integrated safety mechanisms over reusable systems requiring sterilization infrastructure.
- Research Laboratories:Academic and contract research organizations drive demand for customizable array geometries and small-batch manufacturing flexibility.
Hospitals absorb the dominant procurement volume; home care settings are climbing the fastest on addressable market expansion.
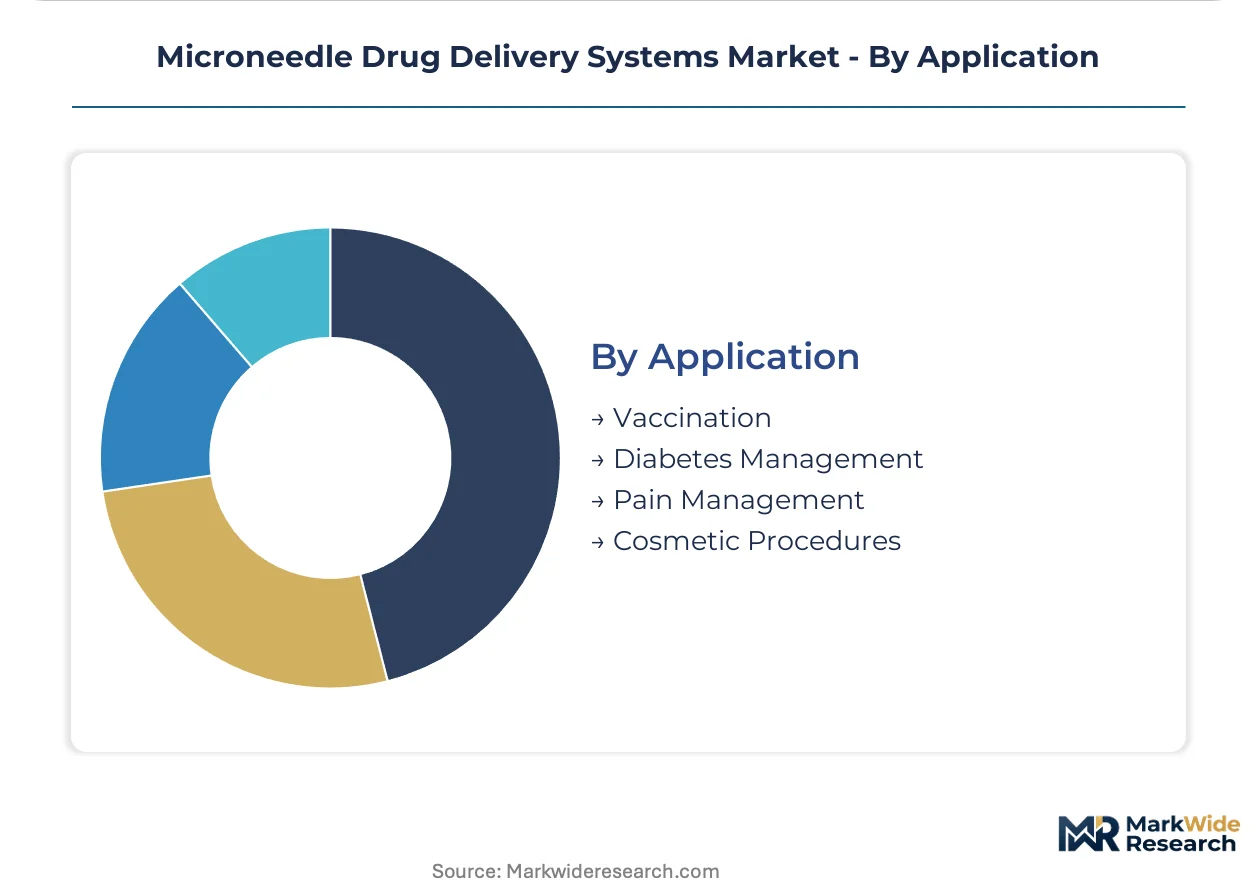
Application:
Therapeutic category determines payload compatibility, release kinetics requirements, and competitive substitution risk from alternative delivery modalities.
- Vaccination:Dissolvable microneedle arrays eliminate cold-chain dependency for thermostable formulations. WHO prequalification pathways for tropical distribution compress regulatory timelines for manufacturers targeting low-resource settings.
- Diabetes Management:Closed-loop glucose monitoring integration with hollow microneedle arrays reshapes product development priorities following FDA emerging guidance. Continuous monitoring applications concentrate in United States and German markets.
- Pain Management:Transdermal opioid and non-opioid delivery competes against autoinjector formats in institutional settings with established sharps disposal infrastructure.
- Cosmetic Procedures:Solid silicon arrays dominate dermatological aesthetics where precise depth control and reusability justify premium per-treatment economics.
Vaccination captures the largest development pipeline; diabetes management is gaining share fastest on monitoring integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese procurement channels where reimbursement codes for at-home biologic administration command premium margins, while Indian contract manufacturers compete on cost-optimized dissolvable microneedle export production under PLI scheme incentives.
United States
FDA combination product regulations and emerging guidance on closed-loop glucose monitoring reshape diabetes management development priorities. Integrated delivery networks consolidate procurement around multi-indication platform vendors spanning vaccination, pain management, and continuous monitoring protocols. Greater Boston and Research Triangle Park clusters host academic medical centers evaluating biodegradable microneedle arrays for oncology supportive care applications.
Germany
EMA medical device directives under MDR frameworks clarify technical documentation requirements for microneedle-patch combinations, reducing regulatory uncertainty for centralized marketing authorization. EMA's 2023 borderline classification guidance accelerates clinical trial investments in chemotherapy-induced nausea transdermal formulations. Baden-Württemberg's precision manufacturing corridor supplies cavitation-resistant mold materials maintaining 25-micron tolerances for micro-mooling infrastructure.
Japan
METI reimbursement infrastructure for patient-administered transdermal biologics expands addressable markets beyond clinical settings into home care environments. PMDA regulatory pathways streamline commercial entry timelines for combination product classifications. Kansai region polymer processing facilities develop tunable hyaluronic acid matrix degradation kinetics matching implantable depot release profiles.
India
CDSCO domestic polymer processing capabilities under PLI scheme incentives position the country for cost-optimized dissolvable microneedle export manufacturing. BIS standards alignment with ISO 10993 biocompatibility requirements accelerates validation timelines for novel polymer matrices. Maharashtra and Gujarat pharmaceutical corridors attract biopharmaceutical contract manufacturers reallocating capital from traditional syringe filling lines toward micro-molding infrastructure.
China
NMPA regulatory frameworks for drug-device integral products govern market access timelines for microneedle platforms targeting vaccination and cosmetic procedure applications. MIIT semiconductor-grade substrate availability constraints in East Asian foundry networks limit expansion for solid microneedle manufacturers. Yangtze River Delta medical device clusters concentrate silicon wafer supply relationships for reusable diagnostic array production.
Microneedle Drug Delivery Systems Market Key Industry Players
Concentration sits with diversified materials science conglomerates and specialized transdermal platform developers. The vendor base spans three tiers: industrial-scale polymer producers with captive micro-molding infrastructure, biopharmaceutical sponsors outsourcing device manufacturing to contract specialists, and regional fabricators serving research laboratory demand for customizable array geometries. Strategic moves center on capacity expansion in precision polymer manufacturing and technology licensing agreements bridging pharmaceutical formulation with device engineering capabilities.
Within the specialized platform tier, Zosano Pharma Corporation and Vaxxas Pty Ltd. occupy positions exemplifying hybrid patch-microneedle architectures and high-density microarray vaccine formats respectively. 3M Company anchors the materials science archetype through industrial-scale production infrastructure. These three entities represent divergent competitive vectors: CNS-focused transdermal delivery, tropical distribution thermostability optimization, and polymer manufacturing scale economies.
| Leading Market Players |
|---|
| Zosano Pharma Corporation |
| Vaxxas Pty Ltd. |
| 3M Company |
| Terumo Corporation |
| Corium International Inc. |
| Becton Dickinson and Company |
| Raphas Co. Ltd. |
| LTS Lohmann Therapie-Systeme AG |
| NanoPass Technologies |
| Others |
Cost & Logistics Intelligence
Photocurable thiol-ene resin systems replacing traditional thermoplastic micromolding are redrawing supply geography toward specialized polymer foundries while compressing configured-to-order premiums against standardized dissolvable array pricing. This substitution simultaneously elevates tooling costs for custom geometries and erodes margin buffers for commodity vaccination formats.
Pricing Analysis
The customization-premium spread between patient-specific array geometries and standard dissolvable vaccination formats spans three-to-fivefold differentials. Pricing stratifies across premium, standard, and economy tiers driven by ISO 10993-10 certification grade and micro-molding tolerance specifications. Cost compression in economy-tier dissolvable arrays is intensifying because Indian CDMOs under PLI scheme incentives are exporting at marginal cost structures. Research laboratories exhibit highest price sensitivity due to small-batch procurement volumes; hospital integrated delivery networks demonstrate lowest sensitivity given formulary standardization incentives.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for semiconductor-grade silicon wafers sourced from Taiwan, South Korea, and Japan. Solid microneedle fabrication draws from deep reactive ion etching equipment, cavitation-resistant mold steels, and photocurable resin precursors. Single-source vulnerability concentrates in Baden-Württemberg's specialized European suppliers for 25-micron tolerance tooling. Distribution runs through biopharmaceutical contract manufacturing organizations reallocating capital from syringe filling toward micro-molding infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as autoinjector formats with integrated needle safety mechanisms retain institutional preference where sharps disposal infrastructure exists.
For Market Incumbents: Shield market position through backward integration into hyaluronic acid matrix production and captive micro-molding infrastructure in Germany or Japan. Prioritize ISO 10993-10 certification investments to accelerate validation timelines against emerging polymer competitors. Channel control through integrated delivery network formulary standardization contracts provides defensive moats against autoinjector substitution threats.
For New Entrants and Emerging Players: Differentiate on tropical distribution thermostability optimization for WHO prequalification pathways. White-space opportunities concentrate in India's cost-optimized export manufacturing under PLI incentives and Japan's at-home reimbursement infrastructure expansion. Direct-to-pharmacy distribution models bypassing wholesale channels offer penetrable go-to-market angles for temperature-stable formats.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations holding micro-molding infrastructure but lacking pharmaceutical formulation capabilities. Long-term viability across the analysis window hinges on convergence between device engineering and biologic payload expertise. Monitor FDA emerging guidance on closed-loop glucose monitoring as inflection indicator for diabetes management platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Molding Infrastructure Expansion | Captures precision manufacturing capacity ahead of biopharmaceutical contract manufacturing demand concentration. |
| WHO Prequalification Pathway Investment | Unlocks tropical distribution corridors for thermostable vaccine formats through streamlined technical dossier requirements. |
| Hyaluronic Acid Matrix Backward Integration | Secures tunable degradation kinetics supply for controlled release profiles matching implantable depot systems. |
| Integrated Delivery Network Formulary Partnership | Consolidates procurement relationships across vaccination, pain management, and diabetes monitoring protocols. |
| Continuous Liquid Interface Production Adoption | Enables patient-specific array geometries through additive manufacturing convergence with photocurable resins. |
Research Approach
Cross-validation between primary interviews with regulatory affairs leads, hospital procurement managers, and contract manufacturing executives and secondary validation through FDA filings, EMA submissions, and ClinicalTrials.gov anchors the qualitative findings. Bottom-up triangulation incorporates formulary database analysis and ISO 10993 biocompatibility standard documentation. Top-down verification draws from biopharmaceutical capital expenditure disclosures and micro-molding equipment procurement records.
Sensitivity analysis across the modeling period evaluates product type, material substrate, end-user site-of-care, and therapeutic application segmentation dimensions. CAGRs derive from installed base expansion rates and per-procedure pricing trajectories without year-specific anchoring. Forecast inputs incorporate WHO prequalification pathway progression rates and reimbursement code expansion timelines for at-home administration.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EMA regulatory alignment or semiconductor-grade substrate availability would require recalibration. Forecasts reflect documented assumptions regarding polymer degradation kinetics standardization and cold-chain elimination adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Sustained Acoustic Medicine Market
Diagnostic and Therapeutic Devices
Therapeutic Apheresis Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market