
 Automated Immunoassay Analyzers Market | 2026-2036
Automated Immunoassay Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Immunoassay Analyzers Market Analysis
Modular chemiluminescence architectures with open-channel reagent flexibility is tilting procurement criteria away from closed-system lock-in. Roche Diagnostics AG leverages its installed base of cobas platforms to sustain recurring consumable revenue streams. Abbott Laboratories anchors its competitive stance through Alinity consolidation, spanning immunoassay, clinical chemistry, and molecular diagnostics on unified footprints. Siemens Healthineers competes via Atellica portfolio scale, targeting high-throughput hospital labs with magnetic cartridge transport and parallel processing.
Automated immunoassay analyzers are clinical diagnostic instruments that quantitatively or qualitatively detect analytes—antigens, antibodies, hormones, or therapeutic drugs—through antigen-antibody binding reactions with detection thresholds typically reaching picogram-per-milliliter sensitivity. These systems automate sample pipetting, incubation, washing, signal generation, and result calculation to deliver standardized throughput exceeding hundreds of tests per hour in centralized laboratory settings. Chemiluminescence immunoassay platforms command the dominant share of new instrument placements due to superior sensitivity and broad menu breadth across thyroid, cardiac, and infectious disease panels. Microfluidics technology represents the fastest-advancing segment, shrinking reaction volumes and enabling point-of-care deployment where near-patient turnaround overrides batch-efficiency economics.
FDA 510(k) clearance pathways and CLIA complexity categorization determine whether instruments deploy in moderately complex hospital labs or waived physician-office settings, directly constraining software design, operator training requirements, and quality control protocols. The European Union's In Vitro Diagnostic Regulation (IVDR) and MDR frameworks impose stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking for automated systems. Stakeholders must monitor how IVDR transition timelines and FDA's evolving predicate-device policies reshape competitive access for novel biomarker assays on open-platform architectures.
Market Dynamics
Modular chemiluminescence architectures with open-channel reagent flexibility are tilting procurement criteria away from closed-system lock-in, forcing manufacturers to decouple instrument hardware from consumable revenue streams.
Growth Catalysts
- CLIA waived complexity expansion:FDA pathway modifications enable decentralized deployment of compact analyzers into physician office laboratories, broadening addressable site volume.
- Cardiac biomarker protocol standardization:Troponin testing guidelines from cardiology societies accelerate high-sensitivity assay menu expansion across installed platforms.
- Thyroid panel demand:Population aging in Japan and Germany concentrates autoimmune and metabolic screening volumes in centralized hospital laboratories.
Market Restraints
- Reagent input concentration:Magnetic microparticle and acridinium ester chemistries depend on limited qualified suppliers in Switzerland and Japan.
- IVDR clinical evidence burden:European Union In Vitro Diagnostic Regulation imposes prospective performance studies for novel biomarker claims, extending time-to-market for assay developers.
- Point-of-care substitution threat:Lateral flow and microfluidic cartridge systems capture STAT testing volumes that previously flowed to core laboratory batch analyzers.
Strategic Opportunities
- India laboratory consolidation:Corporate hospital chains and diagnostic networks in Mumbai and Delhi standardize on automated platforms to replace manual ELISA workflows.
- Therapeutic drug monitoring convergence:Immunoassay and mass spectrometry hybrid architectures enable biologic drug quantification on unified footprints.
- US Medicare reimbursement stability:Clinical Laboratory Fee Schedule annual updates provide predictable revenue visibility for high-throughput hospital lab investments.
Industry Challenges
- Regulatory affairs specialization:IVDR technical documentation and FDA 510(k) predicate strategies require dedicated personnel that mid-tier manufacturers struggle to retain.
- Legacy LIS integration complexity:Hospital information system middleware and bidirectional interface certification consume implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Immunoassay Analyzers Market |
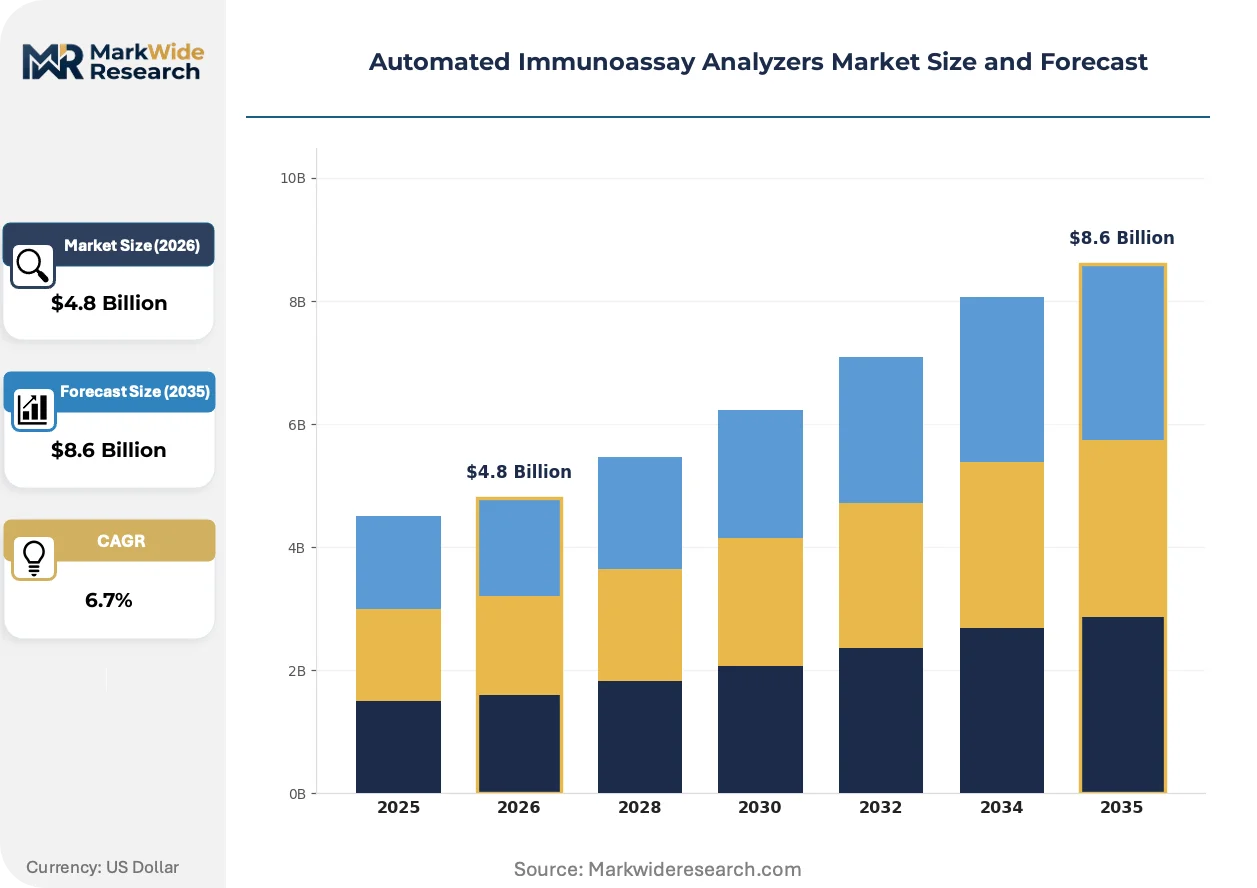
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemiluminescence, Enzyme-Linked Immunosorbent Assay (ELISA), Radioimmunoassay, Fluorescent Immunoassay End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinical Labs Technology: Microfluidics, Biosensors, Robotics, Automated Liquid Handling Application: Infectious Diseases, Hormonal Disorders, Oncology, Autoimmune Disorders |
| Companies Covered | Danaher Corporation, bioMérieux SA, Roche Diagnostics AG, Bio-Rad Laboratories Inc, QuidelOrtho Corporation, Abbott Laboratories, Becton Dickinson and Company, Tosoh Corporation, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Immunoassay Analyzers Market Emerging Trajectories
Cloud-connected quality control and predictive maintenance architectures are compressing instrument downtime economics while reshaping service contract structures across installed base management.
Digital twin simulation is digitizing pre-installation workflow optimization for high-throughput laboratories. Siemens Healthineers deploys virtual commissioning tools for Atellica configurations in US health systems. This capability compresses validation timelines and reduces physical space planning iterations.
FDA's evolving predicate device policy for 510(k) submissions is constraining novel biomarker assay approvals on open-platform architectures. Manufacturers must demonstrate substantial equivalence to established chemiluminescence methods. High-complexity hospital laboratories in the United States are delaying menu expansion commitments pending regulatory clarity.
Consolidated procurement through integrated delivery networks is compressing vendor switching cycles and unbundling after-sales service contracts. Multi-site health systems in Texas and California negotiate enterprise pricing spanning immunoassay, chemistry, and molecular platforms. This behavior concentrates purchasing leverage and pressures standalone instrument margins.
Automated Immunoassay Analyzers Market Segmentation
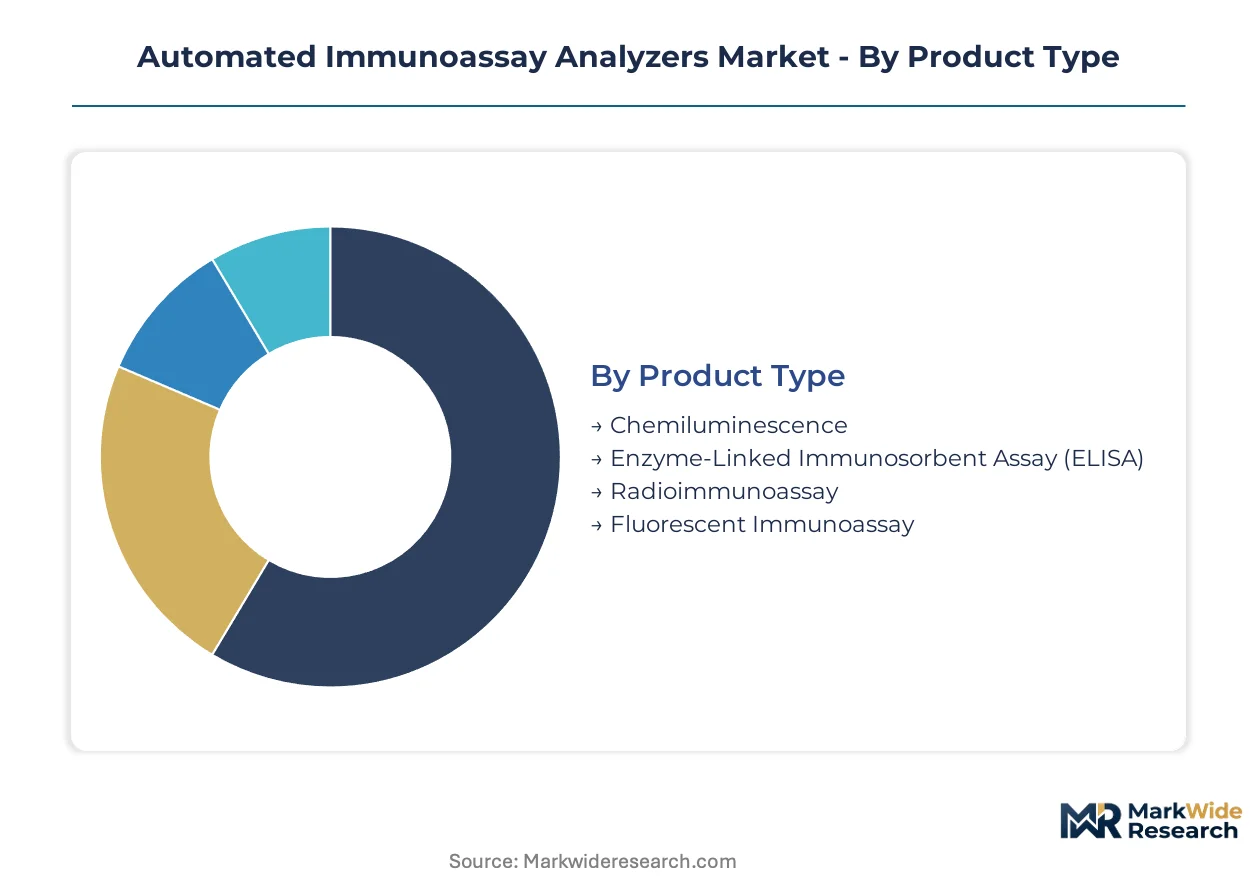
Segmentation in automated immunoassay analyzers reveals how procurement decisions diverge across testing environments. After-sales service intensity varies dramatically by product complexity and end-user technical sophistication, directly shaping vendor contract structures and margin retention.
Product Type:
Service contract attach rates and preventive maintenance schedules diverge sharply across detection chemistries, with consumable-dependent platforms commanding longer-term vendor commitments.
- Chemiluminescence:These platforms employ acridinium ester or alkaline phosphatase labels with picogram-per-milliliter detection thresholds. High-throughput hospital laboratories in the United States concentrate procurement here, driven by cardiac troponin and thyroid panel standardization requiring continuous reagent supply contracts.
- Enzyme-Linked Immunosorbent Assay (ELISA):Colorimetric detection with horseradish peroxidase or alkaline phosphatase conjugates dominates mid-volume clinical laboratories. Diagnostic networks in India favor these systems during manual-to-automated workflow transitions, constrained by initial capital budget limitations and technician training timelines.
- Radioimmunoassay:Gamma-counting detection using iodine-125 or tritium labels persists in specialized endocrinology reference laboratories requiring absolute quantification.
- Fluorescent Immunoassay:Europium chelate or quantum dot fluorophores enable multiplexed cytokine panels in research-intensive academic medical centers.
By volume, Chemiluminescence leads. By growth pace, Fluorescent Immunoassay is ahead.
End User:
Capital deployment cycles and reagent consumption patterns fragment sharply across institutional settings, with procurement authority increasingly centralizing at health system headquarters.
- Hospitals:Integrated delivery networks negotiate enterprise pricing spanning immunoassay, chemistry, and molecular platforms. Multi-site systems in Texas and California consolidate purchasing leverage, compressing standalone instrument margins while demanding unified informatics integration.
- Diagnostic Laboratories:Corporate chains in Mumbai and Delhi standardize on automated platforms to replace manual ELISA workflows, prioritizing throughput per square meter over menu breadth.
- Research Institutions:Academic medical centers with NIH funding streams invest in open-architecture systems supporting novel biomarker development.
- Clinical Labs:Physician office laboratories under CLIA waived complexity pursue compact footprint analyzers with minimal maintenance requirements.
Diagnostic Laboratories expand most quickly in absolute placements. Hospitals retain the highest revenue per installed base.
Technology:
Underlying automation architectures determine upgrade pathways and obsolescence risk, with modular liquid handling systems extending platform lifecycles through component replacement.
- Microfluidics:Sub-microliter reaction volumes enable point-of-care deployment where near-patient turnaround overrides batch-efficiency economics. Cardiac biomarker testing in emergency departments drives adoption.
- Biosensors:Electrochemical and optical transducers with surface plasmon resonance detection support continuous monitoring applications in therapeutic drug management.
- Robotics:Cartesian and SCARA arm configurations dominate high-throughput central laboratories with parallel sample processing architectures.
- Automated Liquid Handling:Displacement and air-displacement pipetting modules with capacitive level sensing reduce pre-analytical error rates in pre-analytical automation lines.
Microfluidics claims the steepest expansion trajectory. Automated Liquid Handling maintains the largest installed population.
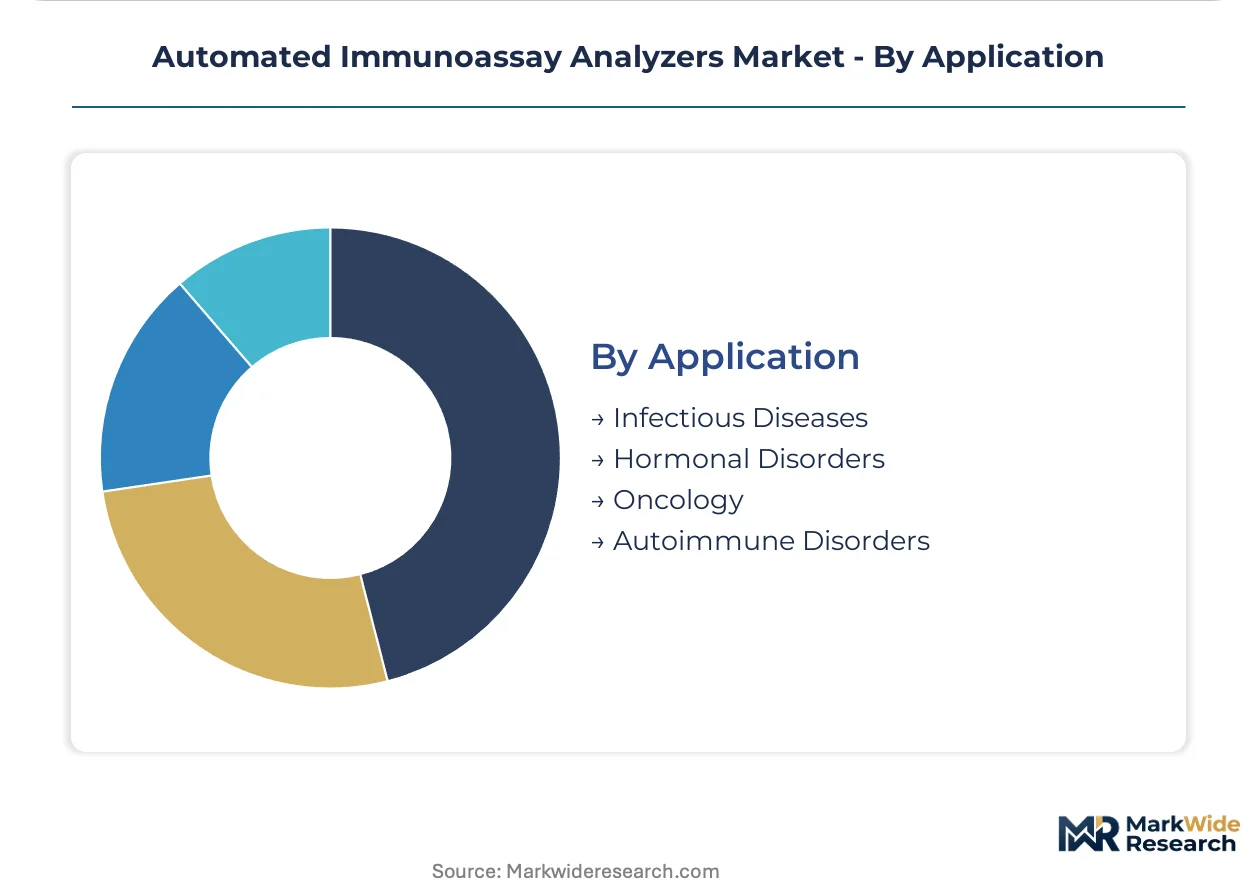
Application:
Test menu breadth requirements and reimbursement stability create distinct competitive moats across disease categories, with oncology panels demanding the most extensive validation documentation.
- Infectious Diseases:HIV, hepatitis, and respiratory pathogen panels require high sensitivity for screening applications. Public health laboratories in Germany and Japan concentrate procurement for population-level surveillance programs.
- Hormonal Disorders:Thyroid and reproductive endocrinology testing generates recurring revenue through monitoring protocols. Aging demographics in Japan accelerate autoimmune and metabolic screening volumes.
- Oncology:Tumor marker quantification for CA-125, PSA, and AFP supports treatment monitoring in comprehensive cancer centers with specialized immunoassay sections.
- Autoimmune Disorders:ANA and rheumatoid factor testing flows through hospital laboratories with integrated rheumatology services.
Infectious Diseases anchors current test volume. Oncology is climbing the fastest amid biomarker menu expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate purchasing authority for high-throughput immunoassay platforms, while diagnostic laboratory chains in India and corporate hospital networks in Germany drive replacement demand for automated workflows.
United States
Multi-site health systems in Texas and California negotiate enterprise pricing spanning immunoassay, chemistry, and molecular diagnostics on unified footprints. FDA 510(k) clearance pathways and CLIA complexity classifications determine instrument deployment in moderately complex hospital labs versus waived physician-office settings. The Southeast corridor from Florida to Georgia hosts consolidated procurement for academic medical centers with NIH funding streams.
Germany
Aging demographics concentrate autoimmune and metabolic screening volumes in centralized hospital laboratories across Bavaria and North Rhine-Westphalia. The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking for automated systems. Berlin-Brandenburg clusters public health laboratory procurement for population-level infectious disease surveillance programs.
Japan
Thyroid panel demand accelerates with population aging, driving high-sensitivity assay menu expansion across installed platforms in the Kanto and Kansai regions. PMDA regulatory frameworks align with international standards while maintaining distinct quality management system requirements. The Chubu region around Nagoya hosts diagnostic network consolidation for automated workflow transitions from manual ELISA systems.
India
Corporate hospital chains and diagnostic networks in Mumbai and Delhi standardize on automated platforms to replace manual ELISA workflows, prioritizing throughput per square meter over menu breadth. CDSCO regulatory pathways govern import licensing and local manufacturing requirements for in vitro diagnostic devices. Maharashtra and Karnataka concentrate private laboratory investment amid expanding health insurance penetration.
China
Domestic diagnostic manufacturers scale production of chemiluminescence platforms to capture mid-tier hospital laboratory demand in the Yangtze River Delta and Pearl River Delta. NMPA regulatory frameworks require clinical trial data for novel biomarker assay approvals on open-platform architectures. Beijing-Tianjin-Hebei clusters tertiary hospital procurement for comprehensive cancer center immunoassay sections.
Automated Immunoassay Analyzers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across instrument hardware, reagent consumables, and after-sales service contracts. The market structure tilts toward consolidated procurement leverage at integrated delivery networks, compressing standalone instrument margins while extending consumable lock-in durations. Three archetypes dominate: diversified conglomerates with cross-platform portfolios, pure-play diagnostics specialists with menu breadth concentration, and regional champions with localized regulatory navigation. Competitive moves center on modular open-channel architectures that decouple hardware from reagent revenue, alongside predictive maintenance service contracts that reshape installed base economics.
Within the diversified conglomerate tier, Danaher Corporation and Siemens Healthineers occupy positions that span life sciences tools through clinical diagnostics, exemplifying scale-driven channel control across multi-site health system procurement. Roche Diagnostics AG represents the pure-play diagnostics archetype with concentrated immunoassay expertise. These three entities anchor the competitive structure through recurring consumable revenue models and unified informatics integration demands from US-based integrated delivery networks.
| Leading Market Players |
|---|
| Danaher Corporation |
| bioMérieux SA |
| Roche Diagnostics AG |
| Bio-Rad Laboratories Inc |
| QuidelOrtho Corporation |
| Abbott Laboratories |
| Becton Dickinson and Company |
| Tosoh Corporation |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries magnetic microparticle reagents and acridinium ester chemistries from Swiss and Japanese suppliers, with freight cost volatility feeding directly into reagent contract indexation and widening price spreads between integrated delivery networks and standalone hospital laboratories.
Pricing Analysis
Cost-plus contracts with acridinium ester price indexation dominate high-throughput platform agreements. Three-tier pricing structure across premium, standard, and economy levels separates Roche Diagnostics AG's cobas consumable bundles from Abbott Laboratories' Alinity reagent rentals and mid-tier ELISA automation systems in India. Pricing pressure stems from integrated delivery network procurement consolidation across Texas and California, compressing standalone instrument margins. Physician office laboratories under CLIA waived complexity exhibit highest price sensitivity; academic medical centers with NIH funding streams show lowest.
Supply Chain Analysis
Export-control restrictions on high-purity magnetic microparticle production technologies limit flows from Switzerland and Japan to Chinese diagnostic manufacturers. Supply concentration centers on Swiss acridinium ester specialists, Japanese magnetic bead substrate producers, and German precision liquid handling component fabricators. Raw material dependencies include rare-earth magnetic particles, photomultiplier tubes, and specialized fluoropolymer tubing. Single-source vulnerability in acridinium ester qualified suppliers creates structural risk. Distribution runs through authorized distributor networks with direct service contracts for enterprise health system accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated immunoassay analyzers market sits in post-pandemic capital equipment replacement cyclicality, with hospital laboratory budget normalization and cardiac biomarker protocol standardization driving refresh demand.
For Market Incumbents: Pre-empt point-of-care substitution by embedding microfluidic modules within core laboratory platforms, defending against lateral flow and cartridge-based STAT testing capture. Secure backward integration into magnetic microparticle production to reduce Swiss and Japanese supplier concentration risk. Prioritize open-channel reagent flexibility in next-generation architectures to counter procurement consolidation leverage from integrated delivery networks. For New Entrants and Emerging Players: Pursue corporate diagnostic laboratory chains in Mumbai and Delhi during manual-to-automated workflow transitions, where capital budget constraints delay Roche Diagnostics AG and Abbott Laboratories penetration. Target mid-volume ELISA replacement demand with compact chemiluminescence footprints. Deploy throughput-per-square-meter value proposition through direct sales teams with local regulatory navigation expertise. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular open-architecture specialists with consumable-decoupled revenue models over closed-system incumbents. Long-term viability hinges on IVDR technical documentation capabilities and FDA 510(k) predicate strategy execution. Watch for CDSCO manufacturing localization mandates in India as inflection indicator for regional champion emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Channel Reagent Architecture | Decouples instrument hardware from consumable lock-in, responding to integrated delivery network unbundling demands. |
| Microfluidic Point-of-Care Integration | Captures emergency department STAT testing volumes threatened by lateral flow substitution. |
| IVDR Technical Documentation Investment | Accelerates CE marking timelines for novel biomarker assays under European Union regulatory frameworks. |
| India Manufacturing Localization | Aligns with CDSCO import licensing requirements while serving corporate hospital chain standardization demand. |
| Predictive Maintenance Service Contracts | Reshapes installed base economics through cloud-connected quality control and downtime compression. |
Methodological Framework
The analysis maps chemiluminescence platform configurations, ELISA automation transitions, microfluidic point-of-care deployments, and mass spectrometry hybrid architectures, each validated through hospital laboratory directors, diagnostic network procurement managers, biomedical engineers, and regulatory affairs specialists. Primary interview intelligence triangulates against FDA 510(k) clearance databases, IVDR technical documentation filings, hospital procurement contract records, and GPO pricing benchmarks. Bottom-up instrument placement counts reconcile with top-down consumable revenue estimates across the analysis window.
Assumptions held fixed include CLIA waived complexity expansion timelines, Medicare Clinical Laboratory Fee Schedule reimbursement stability, and cardiac troponin protocol standardization adoption curves. Variables tested encompass IVDR transition pace, integrated delivery network procurement consolidation rates, and point-of-care substitution penetration. Segmentation modeling spans detection chemistry, end-user setting, automation architecture, and disease application. CAGR derivation incorporates instrument replacement cycles, reagent consumption curves, and service contract attach rates.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure budgets, health insurance penetration in India, or yen-euro exchange rates affecting Japanese reagent import costs would shift the trajectory. Material shifts in FDA predicate device policy for novel biomarker assays or NMPA domestic manufacturing mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market