
 Hot and Cold Therapy Market | 2026-2036
Hot and Cold Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Hot and Cold Therapy Market Foresight
Subscription-based leasing for clinical thermal equipment is rewriting capital deployment across outpatient rehabilitation chains. DJO Global Inc. leverages direct-to-clinic service contracts to sustain placement density in sports medicine practices. Cardinal Health Inc. anchors hospital procurement through integrated distribution networks that bundle hot and cold therapy units with orthopedic consumables. Beurer GmbH differentiates via consumer-facing temperature precision controls that extend brand loyalty into homecare channels.
Hot and cold therapy encompasses thermoelectric and phase-change material systems engineered to maintain 40°C to 10°C surface temperatures for tissue modulation, using hydrogel matrices or circulating fluid reservoirs to deliver sustained thermal transfer for inflammation control and vasodilation. Heating pads and gel wraps occupy the largest revenue pool due to repeat purchase cycles in arthritic care, while wearable delivery modes represent the fastest structural expansion as Bluetooth-enabled temperature monitoring gains traction in physiotherapy centers. Reusable compresses concentrate margin capture through material durability standards that reduce per-treatment costs for clinics managing high patient throughput.
FDA 510(k) premarket notification requirements govern device classification for electrical heating pads in the United States, while the EU Medical Device Regulation mandates clinical evidence for wearable thermal systems sold in Europe. ISO 10993 biocompatibility testing shapes material selection for gel-based products that contact compromised skin during injury treatment. Stakeholders must monitor reimbursement code consolidation across Medicare and private payers, as coverage decisions for at-home thermal therapy will determine whether clinic-prescribed devices convert to direct consumer purchases.
Market Dynamics
Reimbursement code consolidation across Medicare and private payers is compressing clinic-prescribed thermal therapy margins while accelerating direct-to-consumer channel development for wearable devices.
Growth Catalysts
- FDA 510(k) Clearance Streamlining:The FDA's premarket notification pathway for electrical heating pads reduces time-to-market for wearable thermal devices in the United States, enabling faster commercial entry for thermoelectric systems.
- Germany's Statutory Health Insurance:Reimbursement for physiotherapy under German statutory health insurance sustains consistent outpatient purchasing of reusable gel wraps and compression systems.
- Phase-Change Materials:Advanced hydrogel matrices with enhanced thermal retention properties extend treatment duration per application, reducing per-session costs for high-throughput rehabilitation clinics.
Market Restraints
- Silicone Price Volatility:Hydrogel matrix production depends on medical-grade silicone supply chains concentrated in East Asian manufacturing clusters, exposing margin stability to petrochemical input fluctuations.
- EU MDR Clinical Evidence Requirements:The EU Medical Device Regulation mandates costly clinical trials for wearable thermal systems, creating regulatory friction for mid-cap manufacturers without established European notified body relationships.
- DIY Thermal Methods:Consumer substitution toward household ice packs and heated water bottles limits premium pricing power for basic compress products in price-sensitive homecare segments.
Strategic Opportunities
- Bluetooth-Enabled Temperature Monitoring:Wireless sensor integration with physiotherapy practice management software creates subscription revenue streams beyond hardware sales.
- Japan's Aging Demographics:METI-supported home healthcare infrastructure investments position wearable thermal devices for arthritis management in the world's oldest population.
- Amazon Pharmacy Integration:Direct-to-patient fulfillment partnerships with digital pharmacy platforms bypass traditional durable medical equipment distribution markups.
Industry Challenges
- ISO 10993 Biocompatibility Testing:Gel-based products contacting compromised skin require extended cytotoxicity and sensitization studies, stretching product development timelines by 8-14 months.
- Physiotherapist Training Gaps:Wearable thermoelectric systems with programmable temperature protocols demand clinical staff competency in digital interface operation, creating adoption friction in understaffed outpatient clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot and Cold Therapy Market |
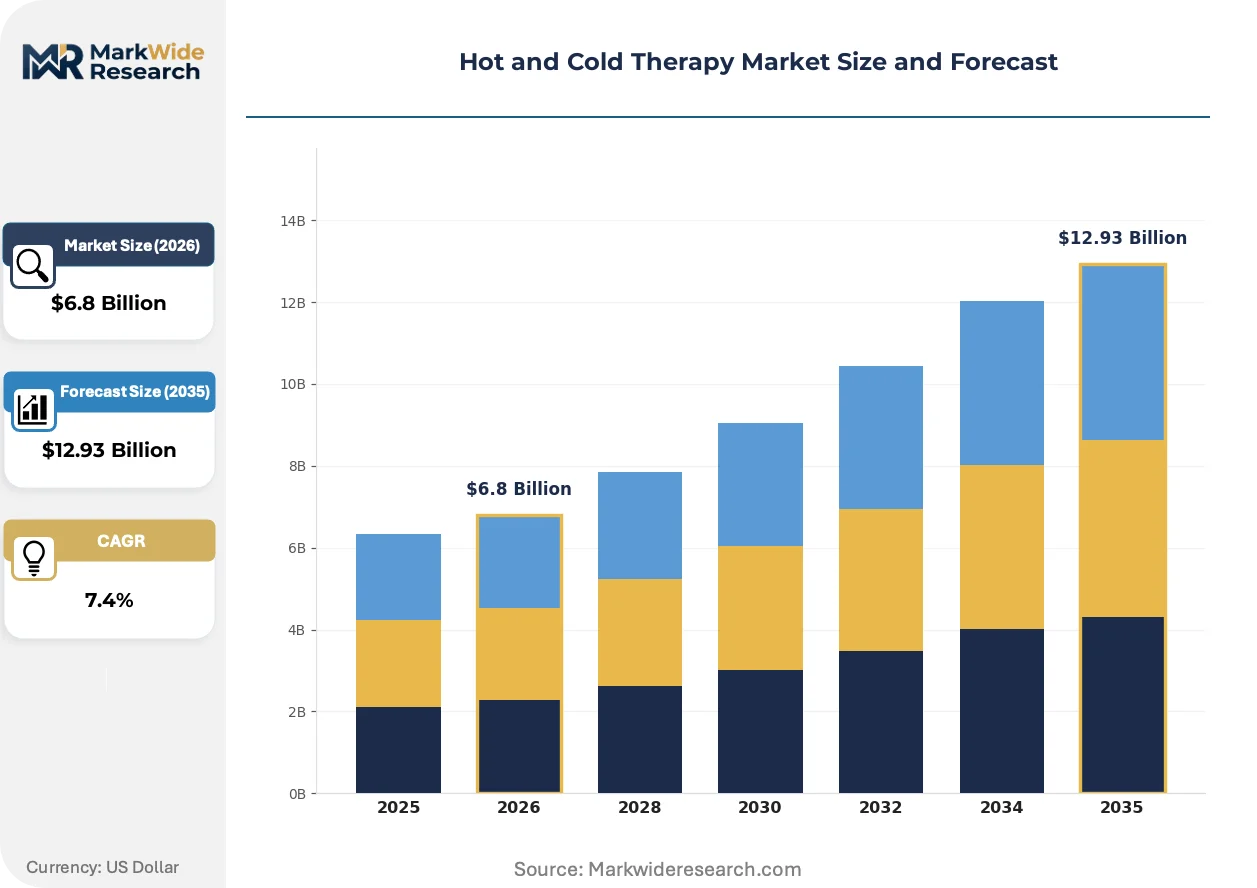
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Pads, Ice Packs, Gel Wraps, Compresses Delivery Mode: Topical, Wearable, Disposable, Reusable End User: Clinics, Physiotherapy Centers, Homecare, Sports Facilities Application: Pain Relief, Muscle Recovery, Injury Treatment, Arthritic Care |
| Companies Covered | Breg Inc., DJO Global Inc., Cardinal Health Inc., Bruder Healthcare Company, Beurer GmbH, 3M Company, Caldera International Inc., Therabody, Medline Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot and Cold Therapy Market Shifts & Advancements
Device intelligence and thermal material science are converging to transform passive compress products into connected therapeutic platforms that capture patient adherence data.
Thermoelectric cooling systems are migrating from industrial climate control applications into portable medical devices, enabling precise temperature modulation without ice or external heating elements. Sports medicine practices in the United States are piloting these systems for sideline injury management. This migration from passive to active thermal control compresses treatment setup time while expanding reimbursable procedure codes.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to implement real-world performance tracking for wearable thermal systems sold in Europe. Companies must now maintain clinical evidence registries documenting adverse events and effectiveness outcomes. German and French notified bodies are prioritizing MDR certification reviews for devices with built-in compliance data architectures.
Subscription leasing models are displacing capital equipment purchases across outpatient rehabilitation chains in the United States. DJO Global's direct-to-clinic service contracts bundle device maintenance, software updates, and consumable resupply into per-patient fees. This shift concentrates purchasing authority with procurement officers rather than clinical department heads, altering vendor sales motion requirements.
Hot and Cold Therapy Market Segmentation
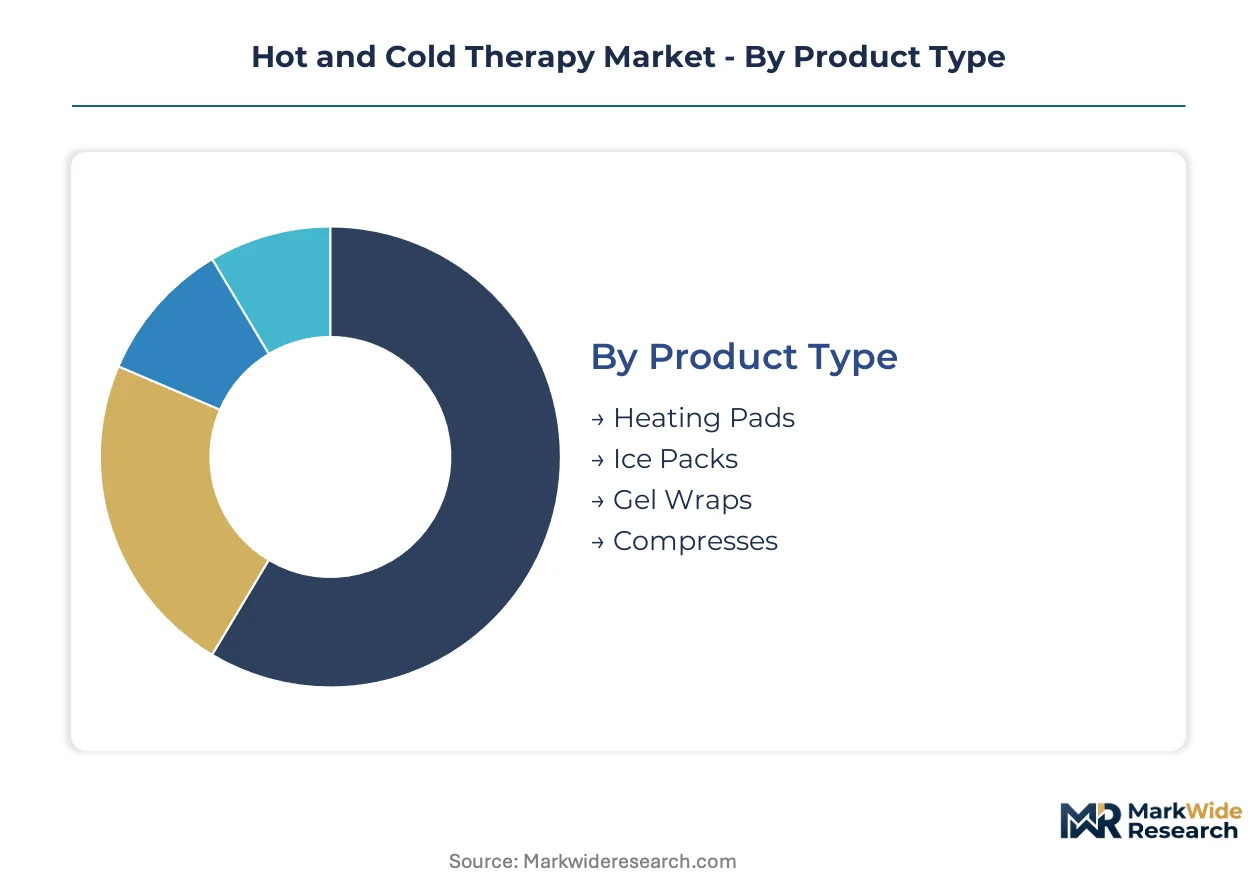
Segmentation in hot and cold therapy reveals divergent cash conversion cycles across product categories. Reusable compresses and gel wraps generate recurring revenue through repeat purchases, while wearable systems command extended replacement timelines tied to technology refresh rates.
Product Type:
Cycle times vary dramatically across this category, with single-use disposables turning inventory weekly while electric heating pads depreciate over multi-year horizons.
- Heating Pads:Electric and chemical variants utilize resistive wire elements or exothermic oxidation reactions to deliver sustained thermal transfer. Demand clusters in arthritic homecare segments across the United States and Germany, where Medicare supplemental policies and statutory insurance reimbursement reduce out-of-pocket friction for elderly patients.
- Ice Packs:Phase-change gel formulations and instant-chemical cold packs provide acute inflammation management through conductive cooling. Sports facilities in Australia and physiotherapy chains in Canada specify clinical-grade puncture resistance for high-frequency institutional use.
- Gel Wraps:Hydrogel matrices bonded to elastic compression fabrics enable conformal thermal contact with irregular anatomy. Reusable variants dominate German outpatient purchasing.
- Compresses:Passive thermal reservoirs rely on latent heat storage in paraffin or salt-hydrate media for extended treatment duration. Rural homecare markets in India favor low-cost compresses over powered alternatives.
Heating pads anchor the volume base while gel wraps gain share at the steepest rate.
Delivery Mode:
Cost stratification separates premium wearable electronics from commodity disposables, with reimbursement eligibility determining effective price tiers across patient populations.
- Topical:Creams, sprays, and patches deliver counterirritant or vasodilatory agents through dermal absorption rather than conductive thermal transfer. OTC pharmacy channels in Brazil and Mexico drive volume for menthol-based formulations.
- Wearable:Thermoelectric systems with programmable temperature protocols and Bluetooth telemetry integrate with physiotherapy practice management software. FDA 510(k) clearance pathways in the United States and EU MDR certification in Germany and France create regulatory segmentation between connected and passive devices.
- Disposable:Single-use chemical reaction packs eliminate sterilization overhead for infection-sensitive clinical environments. Emergency departments in the United Kingdom standardize on disposable cold packs for trauma triage.
- Reusable:Microwaveable gel packs and freezer-stored compresses minimize per-treatment costs for high-throughput rehabilitation clinics. Japanese homecare infrastructure investments under METI guidelines expand addressable demand for durable thermal devices.
Reusable systems dominate clinic procurement volumes while wearable configurations expand most quickly through subscription leasing models.
End User:
Customer concentration patterns split between institutional procurement officers negotiating service contracts and direct-to-consumer purchasers prioritizing convenience and price transparency.
- Clinics:Outpatient orthopedic and pain management practices specify ISO 10993 biocompatibility compliance for devices contacting compromised post-surgical tissue. Cardinal Health's bundled distribution contracts in the United States consolidate purchasing authority.
- Physiotherapy Centers:German statutory health insurance reimbursement sustains consistent gel wrap and compression system purchasing across independent practices.
- Homecare:Aging populations recovering from joint replacement procedures drive demand for intuitive temperature controls and extended battery life. Beurer GmbH's consumer-facing precision interfaces capture brand loyalty in European retail channels.
- Sports Facilities:Sideline injury management requires rapid-deployment thermal systems with minimal setup time. Thermoelectric cooling systems are piloting in United States sports medicine practices for acute trauma response.
Homecare channels represent the largest addressable population while physiotherapy centers maintain the most predictable replenishment cadence.
Application:
Maturity gradients separate established arthritic care protocols from emerging muscle recovery applications in athletic performance optimization.
- Pain Relief:Chronic nociceptive and neuropathic pain management utilizes thermal modulation to gate neural signaling and modulate inflammatory mediator release. Prescription-strength heating pads with temperature limiting circuits address liability concerns in United States litigation environments.
- Muscle Recovery:Contrast therapy protocols alternating vasoconstriction and vasodilation accelerate lactate clearance and reduce delayed-onset muscle soreness. Professional sports franchises in Spain and Italy contract for portable thermoelectric systems with programmable cycle timing.
- Injury Treatment:Acute soft-tissue trauma protocols specify cold application within 48 hours to limit edema and hematoma formation. Emergency medical services in South Korea deploy instant cold packs for field trauma stabilization.
- Arthritic Care:Osteoarthritis and rheumatoid arthritis patients utilize daily thermal therapy to maintain joint mobility and reduce stiffness. Repeat purchase cycles for heating pads concentrate margin capture in retail pharmacy networks.
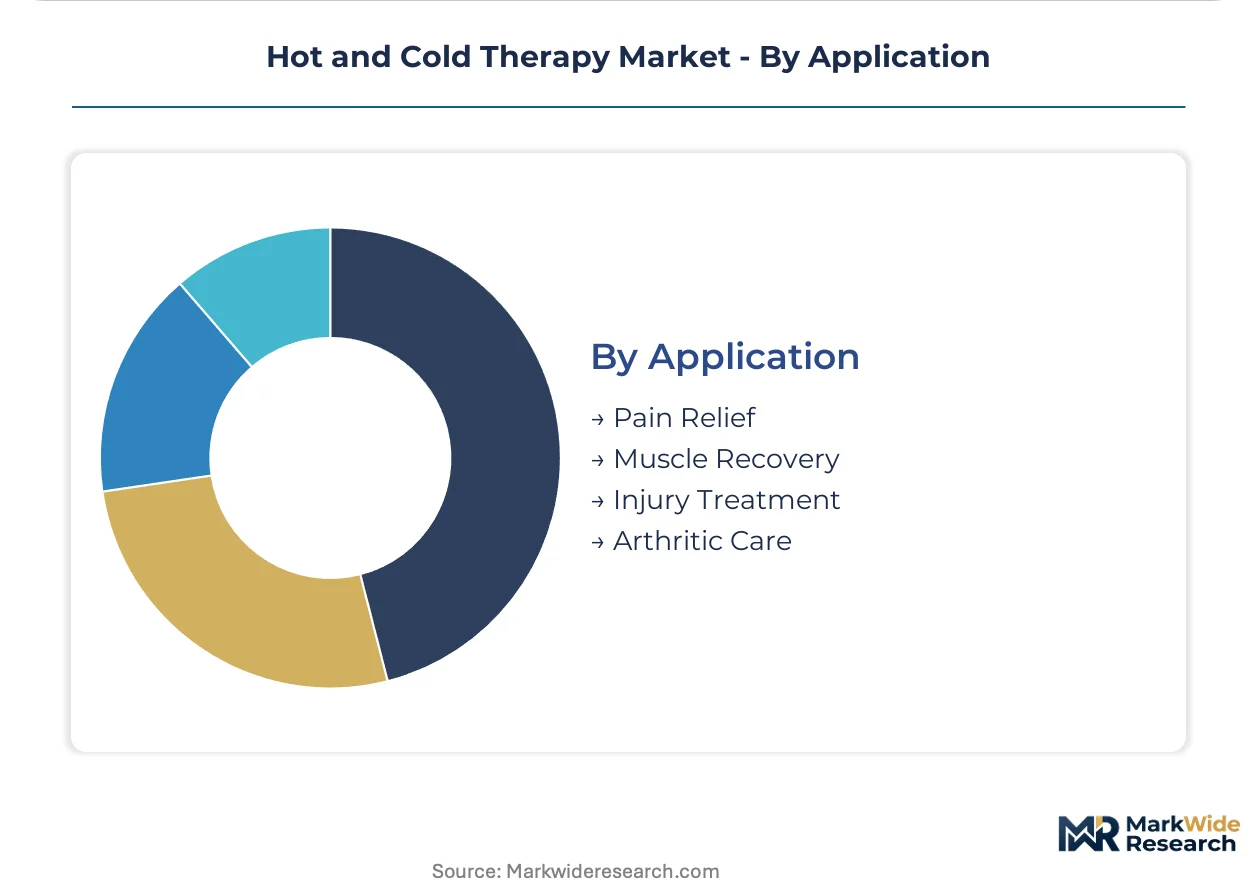
Arthritic care anchors the volume base while muscle recovery applications climb the fastest through sports medicine channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export volumes of thermoelectric cooling modules from East Asian manufacturing clusters exceed import demand in Western rehabilitation markets, creating trade imbalances that favor domestic gel-wrap production in Germany and the United States.
United States
FDA 510(k) clearance pathways accelerate commercial entry for wearable thermal devices targeting sports medicine practices. Medicare reimbursement code consolidation for at-home thermal therapy shifts procurement toward direct-to-consumer channels. The Minneapolis-Saint Paul medical device corridor hosts manufacturing operations for hydrogel matrix production serving North American distribution networks.
Germany
Statutory health insurance reimbursement for physiotherapy sustains consistent outpatient purchasing of reusable gel wraps and compression systems. EU MDR certification requirements mandate clinical evidence registries for wearable thermal systems sold in Europe. The Rhine-Ruhr industrial region concentrates production of medical-grade silicone components for hydrogel manufacturing.
Japan
METI-supported home healthcare infrastructure investments position wearable thermal devices for arthritis management in aging populations. PMDA regulatory frameworks govern thermoelectric medical device approvals with emphasis on biocompatibility documentation. The Kansai region around Osaka anchors domestic manufacturing of precision temperature control systems for rehabilitation equipment.
China
NMPA medical device registration drives localization requirements for thermoelectric systems entering hospital procurement channels. Domestic production of medical-grade silicone for hydrogel matrices reduces import dependency for gel-wrap manufacturers. The Yangtze River Delta cluster around Shanghai specializes in thermoelectric module fabrication for export to Western markets.
United Kingdom
NHS procurement frameworks standardize on disposable cold packs for emergency department trauma triage, compressing margins for reusable product categories. MHRA post-market surveillance aligns with EU MDR transitional arrangements for thermal medical devices. The East Midlands logistics corridor handles distribution of orthopedic consumables including thermal therapy products to European markets.
Hot and Cold Therapy Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: multinational distributors with bundled procurement contracts, specialized thermal device manufacturers with direct-to-clinic service models, and consumer-facing precision control specialists. Strategic archetypes include integrated orthopedic consumable bundlers, subscription-based equipment lessors, and retail-channel precision interface developers. Dominant competitive moves encompass M&A activity targeting physiotherapy software integration capabilities and backward integration into medical-grade silicone supply chains.
Within the integrated distribution tier, Cardinal Health Inc. and DJO Global Inc. exemplify divergent approaches to market access, with the former anchoring hospital procurement networks and the latter pioneering direct-to-clinic subscription contracts. Beurer GmbH occupies a distinct position as a consumer-facing precision control specialist, representing the retail-channel archetype that extends brand loyalty into homecare segments through intuitive temperature interfaces.
| Leading Market Players |
|---|
| Breg Inc. |
| DJO Global Inc. |
| Cardinal Health Inc. |
| Bruder Healthcare Company |
| Beurer GmbH |
| 3M Company |
| Caldera International Inc. |
| Therabody |
| Medline Industries Inc. |
| Others |
Supply & Pricing Matrix
The East Midlands logistics corridor channels orthopedic consumables through UK distribution hubs, where freight cost dynamics amplify supply concentration effects and force three-tier pricing stratification across premium gel-wrap, standard compress, and economy disposable tiers.
Pricing Analysis
Hospital procurement officers anchor contract-based long-term offtake pricing through Cardinal Health's bundled orthopedic consumable agreements. Price differentiation stems from ISO 10993 certification tier and after-sales service bundling. Cost compression in standard reusable compresses intensifies because DIY thermal substitution limits premium capture. Homecare elderly patients show highest price sensitivity; sports medicine practices demonstrate lowest sensitivity due to reimbursable procedure codes.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for thermoelectric module sourcing. Manufacturing concentrates in China, Germany, and the United States. Hydrogel matrix production draws from medical-grade silicone, thermoelectric semiconductors, and elastic compression fabrics. Single-source vulnerability persists in East Asian silicone supply clusters. Distribution runs through hospital GPO contracts, direct-to-clinic service agreements, and Amazon Pharmacy digital fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through outpatient rehabilitation chain consolidation, with procurement officers displacing clinical department heads as purchasing authority centralizes.
For Market Incumbents: Build regulatory data moats through EU MDR-compliant clinical evidence registries that emerging entrants cannot replicate. Deepen backward integration into medical-grade silicone supply chains to offset petrochemical input volatility. DJO Global's subscription leasing model threatens capital-equipment incumbents who lack service-contract capabilities. For New Entrants and Emerging Players: Build out Bluetooth-enabled temperature monitoring platforms for physiotherapy software integration, the most penetrable white-space segment. Target Japan's METI-supported homecare infrastructure investments for arthritis management devices. Pursue Amazon Pharmacy direct-to-patient fulfillment partnerships to bypass traditional durable medical equipment distribution markups. For Investors and Strategic Acquirers: Specialized thermal device manufacturers with direct-to-clinic service models and established European notified body relationships represent priority acquisition targets. Long-term viability favors platforms capturing recurring subscription revenue over transactional hardware sales. Watch FDA 510(k) clearance velocity for wearable thermoelectric systems as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Registry Development | Post-market surveillance compliance enables European market access for wearable thermal systems in Germany and France. |
| Backward Integration into Silicone Supply | In-house production of medical-grade hydrogel matrices insulates margin stability from petrochemical price swings. |
| Physiotherapy Software Platform Integration | Bluetooth telemetry connectivity with practice management systems creates subscription revenue beyond hardware sales. |
| Direct-to-Clinic Subscription Leasing | Per-patient service contracts concentrate purchasing authority with procurement officers rather than clinical heads. |
| Amazon Pharmacy Fulfillment Partnership | Digital pharmacy integration bypasses traditional durable medical equipment distributor markups for homecare channels. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, physiotherapy practice owners, biomedical engineers, and GPO contracts specialists and refined through secondary validation against FDA 510(k) filings, EU MDR notified body decisions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up demand modeling triangulated with top-down market sizing across product type, delivery mode, end user, and application dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling spanning product category, delivery technology tier, institutional versus homecare channel, and regional regulatory cluster. CAGRs derived from historical growth trajectory analysis adjusted for reimbursement policy shifts and technology adoption curves. Forecast inputs incorporated ISO 10993 biocompatibility testing timelines and EU MDR certification velocity variations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native thermal device entrants with direct-to-consumer capabilities would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market