
 Dermatology Diagnostic Equipment Market | 2026-2036
Dermatology Diagnostic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatology Diagnostic Equipment Market Outlook
Hospital procurement of dermatology diagnostic equipment is shifting toward outpatient and clinic-based models. Carl Zeiss Meditec leverages its optical engineering heritage to dominate high-resolution imaging segments. Koninklijke Philips competes across multimodal platforms that integrate dermatoscopy with digital records. DermaSensor specializes in handheld spectroscopic devices that reduce biopsy dependency for primary care physicians.
Dermatology diagnostic equipment encompasses instruments engineered to visualize, sample, or analyze skin tissue with resolution thresholds reaching cellular and subcellular levels, serving clinical screening and pathological confirmation purposes. Imaging systems incorporating optical coherence tomography achieve cross-sectional depth penetration of one to two millimeters, enabling non-invasive differentiation of benign from malignant lesions. AI-based solutions represent the fastest-expanding technology segment as machine learning classifiers demonstrate diagnostic parity with specialist consensus. Dermatoscopes retain the largest installed base but face margin compression from commoditization of basic handheld units.
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-as-medical-device classifications. The FDA's evolving guidance on AI-enabled diagnostic tools shapes development roadmaps for algorithm-dependent platforms. China's NMPA has accelerated review channels for innovative diagnostic equipment, altering market entry sequencing for multinational manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to optimize registration investments and avoid stranded development expenditures.
Market Dynamics
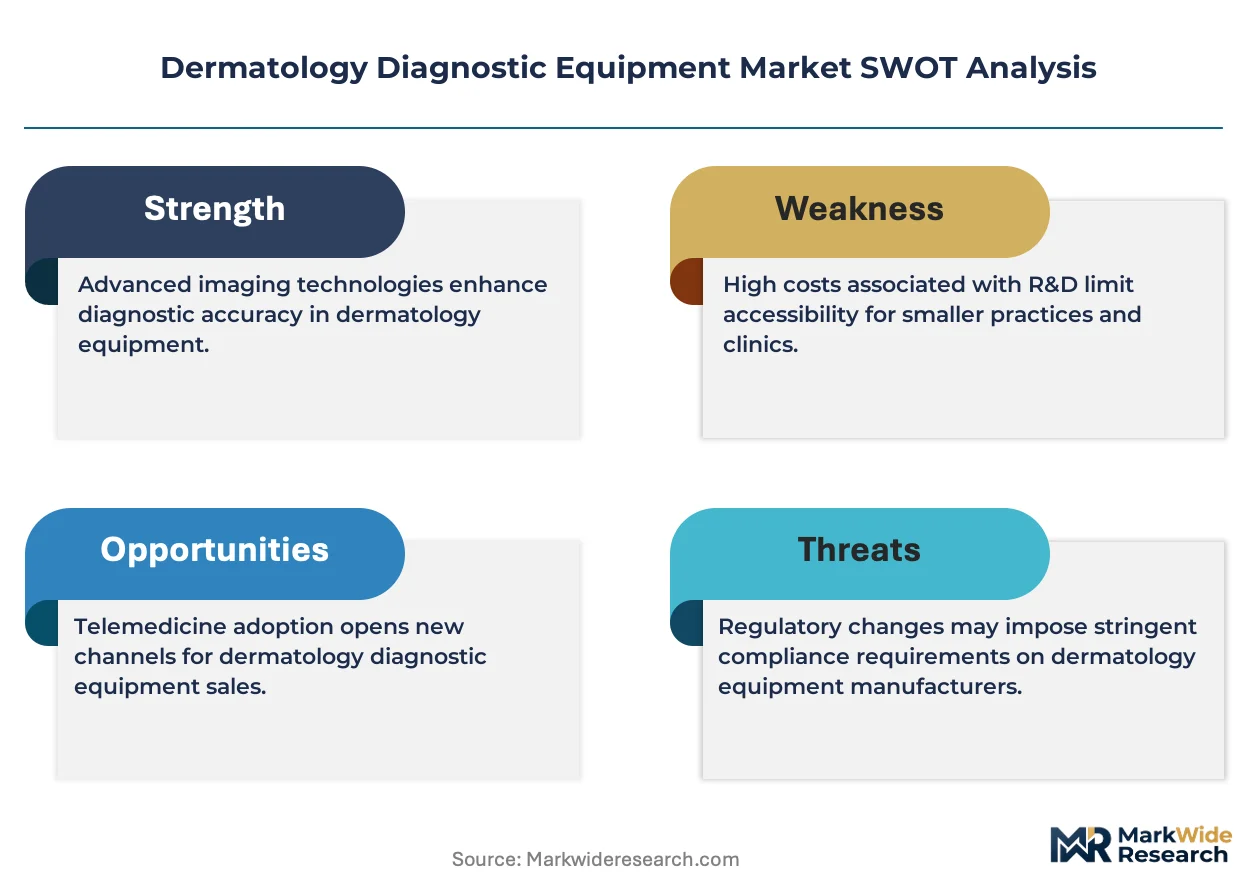
AI-enabled diagnostic algorithms are compressing the specialist referral pathway, forcing equipment manufacturers to embed machine learning classifiers directly into point-of-care devices or lose procurement contracts to integrated platform vendors.
Growth Catalysts
- FDA 510(k) De Novo Pathways:Accelerated clearance channels for AI-integrated dermatoscopes reduce time-to-market for algorithm-dependent devices, incentivizing R&D investment in automated lesion classification.
- Primary Care Integration:Family medicine clinics in the United States and Germany are adding dermatoscopy capabilities to reduce dermatologist referral backlogs, expanding the addressable installed base beyond specialist settings.
- Optical Coherence Tomography Depth Resolution:Sub-millimeter tissue penetration without biopsy enables screening workflows in outpatient settings previously limited to hospital-based pathology.
Market Restraints
- EU MDR Clinical Evidence Burden:Software-as-medical-device classifications now require prospective validation studies, extending registration timelines and straining development budgets for algorithm-based platforms.
- Detector Component Concentration:High-sensitivity CMOS sensors for multispectral imaging concentrate among East Asian semiconductor fabricators, creating supply vulnerability for European and North American device assemblers.
- Biopsy Pathology Substitution Ceiling:Definitive melanoma diagnosis still requires histopathological confirmation, limiting revenue capture from screening-only devices regardless of imaging accuracy.
Strategic Opportunities
- Telemedicine-Enabled Rural Penetration:Store-and-forward dermatoscopy protocols in Australia and Canada allow primary care networks to access specialist-grade screening without capital-intensive specialist deployment.
- China NMPA Innovation Fast Track:Priority review channels for breakthrough diagnostic devices reward early clinical validation in Chinese trial sites, altering market entry sequencing for multinational portfolios.
- Multimodal Platform Convergence:Integration of confocal microscopy with digital dermoscopy and electronic health records creates stickier hospital contracts and raises switching costs for incumbent vendors.
Industry Challenges
- Algorithm Validation Workforce Scarcity:Dermatopathologists capable of ground-truthing training datasets for machine learning classifiers command premium compensation, constraining development velocity for AI-dependent entrants.
- Legacy PACS Integration Friction:New imaging platforms face extended deployment timelines in hospital systems running decade-old picture archiving infrastructure, delaying revenue recognition and raising implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatology Diagnostic Equipment Market |
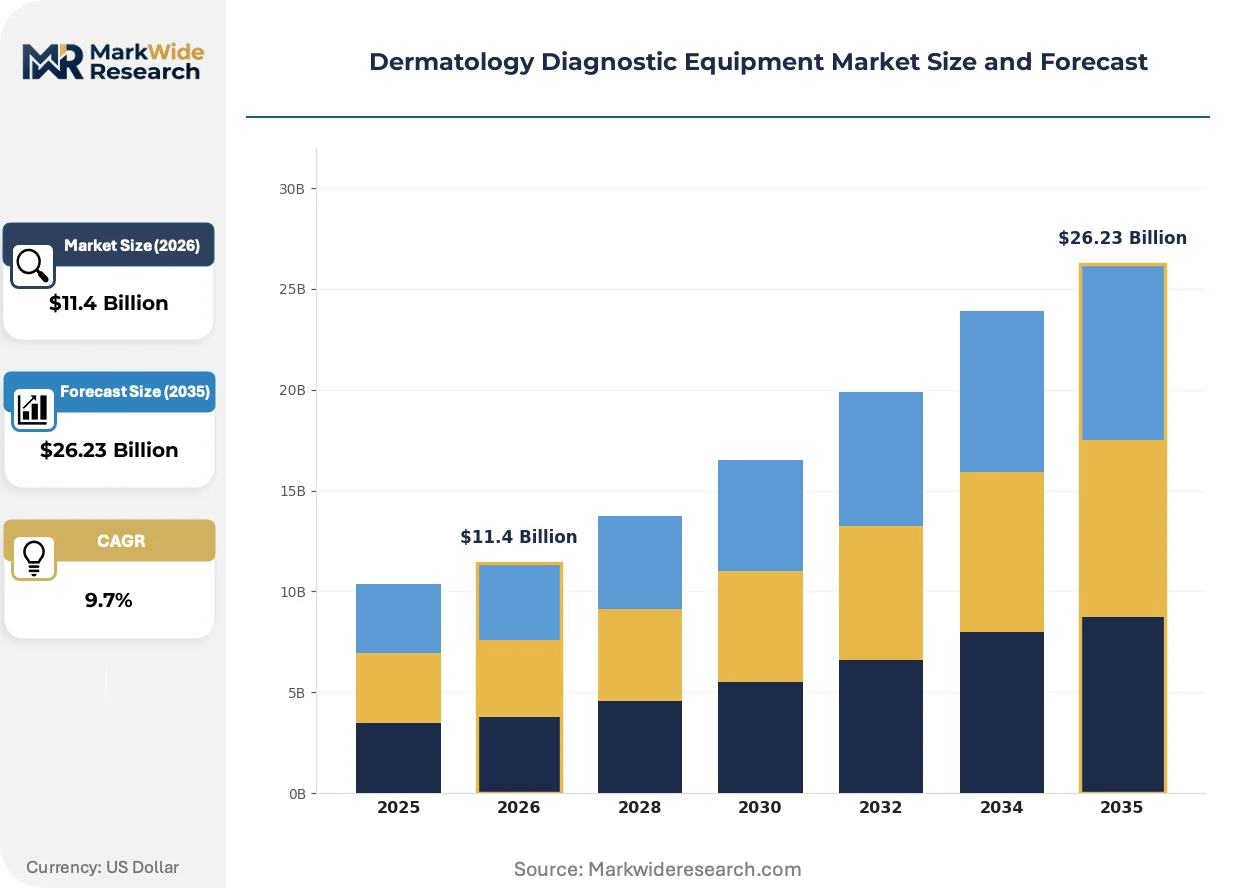
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.23 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dermatoscopes, Biopsy Devices, Imaging Systems, Analyzers Technology: Digital Imaging, Optical Coherence Tomography, Ultrasonography, AI-Based Solutions Application: Skin Cancer Diagnosis, Psoriasis Management, Eczema Assessment, Acne Treatment End User: Dermatology Clinics, Hospitals, Research Laboratories, Cosmetic Centers |
| Companies Covered | Canfield Scientific, Carl Zeiss Meditec, FotoFinder Systems, HEINE Optotechnik, Michelson Diagnostics, Caliber Imaging & Diagnostics, DermaSensor, Leica Microsystems, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatology Diagnostic Equipment Market Strategic Shifts
Computational pathology is collapsing the boundary between image acquisition and diagnostic interpretation, redefining equipment value propositions from hardware performance to algorithmic accuracy and workflow integration depth.
Multispectral imaging is consolidating diagnostic specificity previously distributed across sequential biopsy and histology workflows. Dermatology departments in academic medical centers are replacing discrete dermoscopy and reflectance confocal microscopy stations with unified spectral platforms. This consolidation compresses capital equipment footprints while elevating software licensing to the primary revenue determinant.
The EU Medical Device Regulation's software classification criteria are forcing algorithm developers to maintain prospective clinical registries. Manufacturers targeting European commercialization must now fund multi-site validation studies that were previously satisfied by retrospective image libraries. Dermatology AI platforms with pre-2021 CE marks face recertification cliffs that favor well-capitalized incumbents with dedicated regulatory affairs infrastructure.
Hospital purchasing committees are unbundling imaging hardware from maintenance contracts and algorithm subscriptions. Large health systems in Germany and the United States now negotiate three-year total cost of ownership agreements that separate device amortization from software access fees. This unbundling exposes pure-play hardware vendors to margin pressure while rewarding integrated platform providers with recurring revenue streams.
Dermatology Diagnostic Equipment Market Segmentation
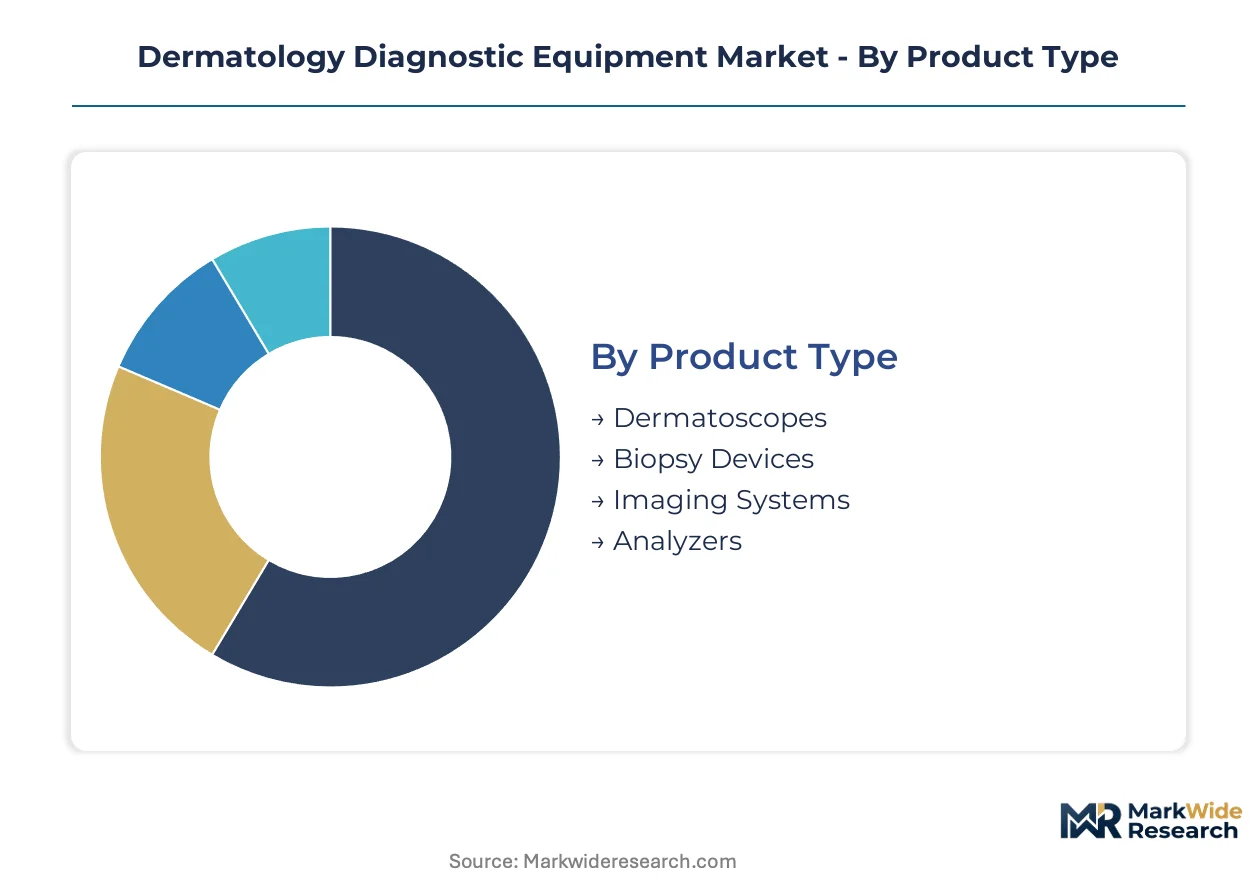
Dermatology diagnostic equipment procurement patterns diverge sharply across product architectures, imaging modalities, clinical applications, and care settings. Understanding these fault lines reveals where margin concentrates and where commodification threatens incumbent positions.
Product Type:
Supply concentration clusters around optical engineering capabilities, with German and Japanese precision manufacturers commanding premium segments while Chinese assemblers capture volume tiers.
- Dermatoscopes:Handheld and video-based devices utilizing polarized light to visualize subsurface skin structures. Demand concentrates in United States primary care networks seeking to reduce dermatologist referral bottlenecks, though margin compression from commoditized entry-level units constrains pure-play hardware vendors.
- Imaging Systems:Cross-sectional modalities including optical coherence tomography and confocal microscopy achieving cellular-level resolution without tissue excision. Academic medical centers in Germany and Japan drive procurement as these institutions replace discrete pathology workflows with unified spectral platforms.
- Biopsy Devices:Punch, shave, and excisional instruments for histopathological confirmation. Standardized manufacturing enables multi-source procurement strategies.
- Analyzers:Automated systems for molecular and cellular specimen processing. Laboratory consolidation in United States health systems favors integrated platform vendors over standalone device suppliers.
Today's leader: Imaging Systems. Tomorrow's challenger: AI-embedded Dermatoscopes.
Technology:
Cost tier stratification separates capital-intensive institutional platforms from deployable point-of-care solutions, with reimbursement pathways determining viable price ceilings.
- AI-Based Solutions:Machine learning classifiers trained on annotated lesion libraries to automate diagnostic scoring. United States FDA 510(k) De Novo pathways and China NMPA innovation fast tracks accelerate commercialization for algorithm-dependent entrants with prospective clinical validation.
- Digital Imaging:High-resolution capture systems with standardized output formats for telemedicine transmission. Rural health networks in Australia and Canada deploy store-and-forward protocols to access specialist-grade screening without capital-intensive specialist deployment.
- Optical Coherence Tomography:Interferometric depth profiling achieving one to two millimeter tissue penetration. Sub-millimeter resolution commands premium pricing in outpatient settings previously limited to hospital-based pathology.
- Ultrasonography:High-frequency transducers for dermal and subcutaneous tissue assessment. Dermatology clinics leverage lower capital requirements compared to optical modalities for preliminary lesion evaluation.
AI-Based Solutions climb the fastest, though Optical Coherence Tomography retains the steepest pricing power.
Application:
Volume distribution tracks disease prevalence and screening protocol intensity, with oncology applications commanding reimbursement premiums over chronic condition management.
- Skin Cancer Diagnosis:Melanoma and non-melanoma screening workflows incorporating dermoscopy, digital monitoring, and histopathological confirmation. Screening mandates in Germany and Australia's national health programs institutionalize procurement demand.
- Psoriasis Management:Severity scoring and treatment response monitoring through standardized imaging protocols. Biologic therapy expansion in United States and European markets sustains longitudinal assessment device demand.
- Eczema Assessment:Inflammation grading and barrier function evaluation. Pediatric dermatology clinics drive specialized imaging requirements.
- Acne Treatment:Lesion counting and sebaceous activity measurement for therapeutic monitoring. Cosmetic centers in South Korea and United States integrate assessment devices into treatment bundling.
Skin Cancer Diagnosis anchors current revenue. Psoriasis Management offers the most durable recurring utilization.
End User:
Customer type determines purchasing committee composition, contract structure, and switching cost architecture, with hospital systems demanding platform integration and clinics prioritizing workflow simplicity.
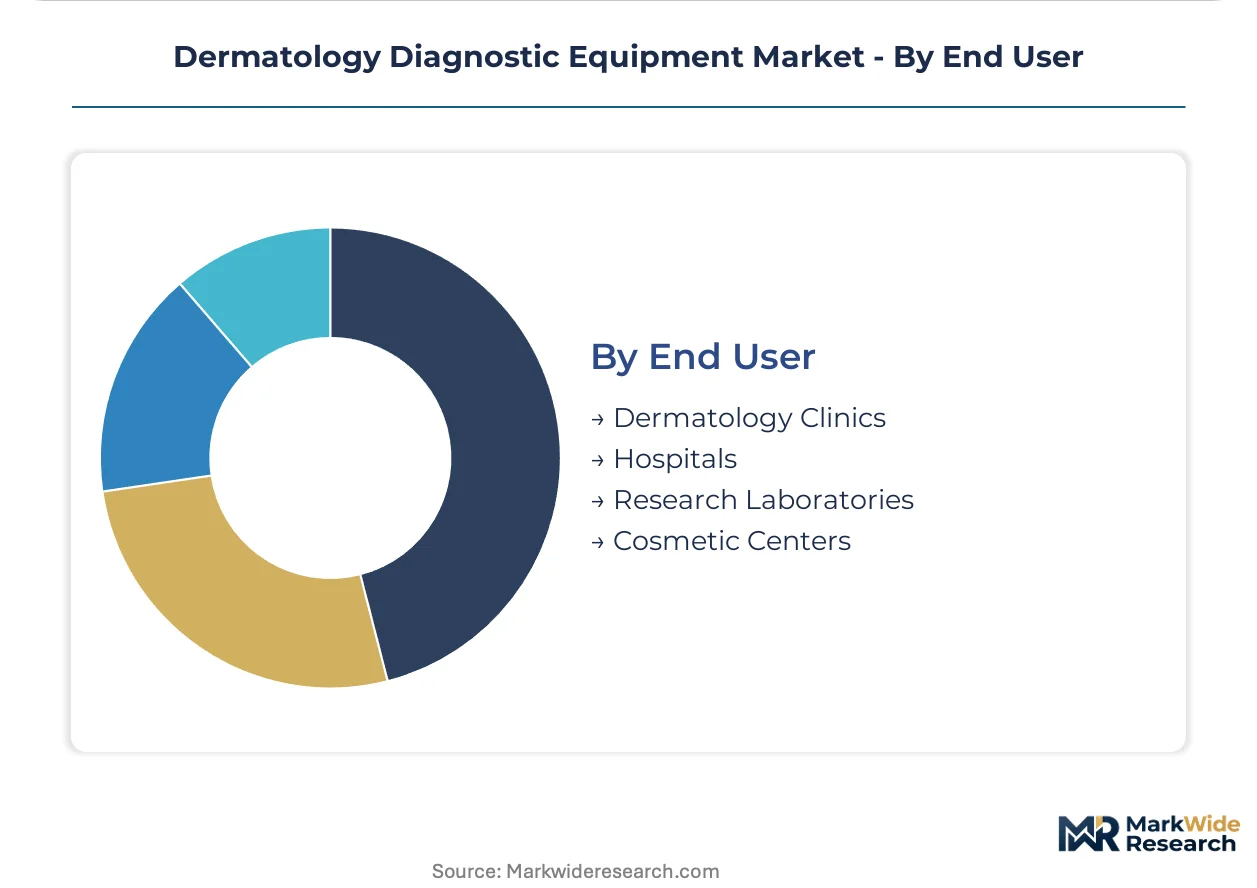
- Dermatology Clinics:Specialist practices with high lesion throughput and established referral relationships. United States and German clinic consolidation creates purchasing leverage for multi-site equipment standardization.
- Hospitals:Integrated delivery networks with legacy PACS infrastructure and enterprise EHR systems. Extended deployment timelines from decade-old picture archiving systems delay revenue recognition for new platform vendors.
- Research Laboratories:Academic and commercial sites conducting algorithm development and clinical validation. Dermatopathologist scarcity for ground-truthing training datasets constrains AI platform development velocity.
- Cosmetic Centers:Aesthetic practices incorporating diagnostic imaging into treatment consultation workflows. South Korean and United States markets show strongest device attachment rates.
Dermatology Clinics dominate installed base expansion. Hospitals control replacement cycle timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between FDA 510(k) pathways and EU MDR software classifications is creating compliance-cost arbitrage that redirects R&D investment and market entry sequencing. Manufacturers now sequence registrations to exploit faster clearance channels before tackling evidence-heavy jurisdictions.
United States
Primary care networks in Texas and Florida are deploying handheld dermatoscopes to reduce dermatologist referral backlogs. FDA 510(k) De Novo pathways accelerate commercialization for AI-integrated devices with prospective clinical validation. The Boston-Cambridge corridor anchors algorithm development clusters where dermatopathologists ground-truth training datasets for machine learning classifiers.
Germany
Academic medical centers in Munich and Heidelberg drive procurement of optical coherence tomography systems for outpatient screening workflows. EU MDR software-as-medical-device classifications impose prospective validation study requirements that strain development budgets. The Baden-Württemberg precision optics cluster supplies high-resolution imaging components to domestic device assemblers.
China
NMPA innovation fast-track channels reward early clinical validation in Shanghai and Beijing trial sites. Hospital procurement committees in Guangdong province prioritize multimodal platforms integrating confocal microscopy with electronic health records. Yangtze River Delta manufacturing hubs assemble CMOS sensors for multispectral imaging devices.
Japan
PMDA review timelines for AI-enabled diagnostic tools shape development roadmaps for algorithm-dependent platforms. Tokyo and Osaka dermatology clinics adopt store-and-forward telemedicine protocols to extend specialist-grade screening to rural prefectures. Kanto region precision manufacturers supply optical components for confocal microscopy systems.
Australia
National skin cancer screening mandates institutionalize procurement demand across Queensland and New South Wales. TGA regulatory alignment with FDA pathways enables faster market entry for devices with prior United States clearance. Store-and-forward dermatoscopy networks in Victoria and Western Australia allow primary care access to remote specialist interpretation.
Dermatology Diagnostic Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium imaging systems consolidating around optical engineering heritage while handheld devices fragment among price-competitive assemblers. The vendor base organizes into three tiers: precision optics conglomerates with medical device divisions, pure-play dermatology specialists, and emerging AI-native platform developers. Strategic moves concentrate on algorithm licensing partnerships and multimodal platform convergence rather than standalone hardware innovation.
Among precision optics conglomerates, Carl Zeiss Meditec and Leica Microsystems exemplify heritage-driven positioning in high-resolution imaging segments. Koninklijke Philips occupies a position spanning multimodal platform integration. Within the AI-native tier, DermaSensor represents point-of-care spectroscopic specialization. These archetypes illustrate how competitive advantage migrates from optical performance specifications to workflow integration depth and algorithmic diagnostic accuracy.
| Leading Market Players |
|---|
| Canfield Scientific |
| Carl Zeiss Meditec |
| FotoFinder Systems |
| HEINE Optotechnik |
| Michelson Diagnostics |
| Caliber Imaging & Diagnostics |
| DermaSensor |
| Leica Microsystems |
| Koninklijke Philips |
| Others |
Value Chain & Pricing Dynamics
CMOS sensor pricing indices from East Asian semiconductor markets cascade through dermatology device manufacturing, compressing margins on multispectral imaging systems while amplifying pricing power for vendors with captive optical component production.
Pricing Analysis
Distributor margins of 15-25 percent sit atop manufacturer pricing for handheld dermatoscopes sold through medical device distributors, while direct-to-hospital contracts for OCT systems bypass intermediary markups entirely. A three-tier pricing structure across premium, standard, and economy levels separates AI-embedded platforms from basic handheld units from disposable biopsy instruments. Cost compression in entry-level dermatoscopes is intensifying because Chinese assemblers flood primary care markets with polarized-light devices lacking algorithmic differentiation. Hospital systems demonstrate the least price sensitivity for multimodal platforms with EHR integration, while independent cosmetic centers in South Korea and the United States negotiate aggressively on capital equipment.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for high-sensitivity CMOS sensors used in multispectral imaging, forcing European and North American device assemblers to maintain 90-day inventory buffers against geopolitical disruption. Precision optical components draw from German Baden-Württemberg and Japanese Kanto manufacturing clusters, while CMOS sensor fabrication rests on East Asian semiconductor foundries. Tariff exposure on Chinese-assembled dermatoscopes entering United States markets threatens margin structures for price-competitive entrants. Distribution runs through specialized medical device distributors serving hospital purchasing committees and direct sales forces targeting academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dermatology diagnostic equipment functions as a stable compounder, with AI algorithm refresh cycles and screening protocol expansion in national health programs generating durable replacement demand.
For Market Incumbents: Hedge against margin erosion in handheld dermatoscopes by deepening software licensing revenue through algorithm subscription tiers, while securing backward integration into precision optical component supply through partnerships with Baden-Württemberg and Kanto region manufacturers. FDA 510(k) clearance backlogs for AI-native entrants create a temporary defensive moat if incumbents accelerate De Novo pathway submissions for integrated diagnostic platforms.
For New Entrants and Emerging Players: Telemedicine-enabled store-and-forward protocols offer the lowest customer acquisition cost route into rural primary care networks in Australia, Canada, and United States Medicaid expansion states where dermatologist density falls below screening mandate requirements. Target psoriasis management monitoring devices for biologic therapy clinics, where longitudinal utilization creates recurring revenue streams absent from one-time skin cancer screening purchases.
For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native platform developers possessing prospective clinical validation datasets and NMPA innovation fast-track positioning, given the regulatory recertification cliff facing pre-2021 CE-marked algorithms under EU MDR software classifications. Watch NMPA priority review channel announcements as the signal indicating which algorithm-dependent platforms will capture first-mover advantage in Chinese hospital procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) De Novo Submission | Accelerated clearance for AI-integrated dermatoscopes reduces competitive entry timelines against algorithm-dependent entrants. |
| CE Marking Pathway Investment | EU MDR software-as-medical-device compliance demands prospective validation studies that strain development budgets for algorithm platforms. |
| Hospital System Partnership | Integrated delivery network contracts with EHR embedding create switching costs and recurring software licensing revenue streams. |
| Software Companion Development | Algorithm subscriptions unbundled from hardware sales transform capital equipment vendors into recurring revenue platform providers. |
| Reimbursement Strategy Execution | CPT code establishment for AI-assisted dermatoscopy determines viable price ceilings for primary care deployment models. |
Study Parameters
Bottom-up dermatology clinic and hospital procurement modeling reconciled against top-down device manufacturer shipment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee chairs, biomedical engineers, dermatopathologists, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, NMPA registration databases, EU MDR notified body certificates, and hospital procurement system records. Triangulation across these sources isolates installed base estimates from replacement cycle timing and new deployment velocities.
Input-output matrices map imaging modality adoption rates against screening protocol expansion in national health programs, dermatologist supply constraints, and AI algorithm validation milestones across the projection horizon. Segmentation dimensions include product architecture, imaging technology, clinical application, and care setting, with CAGRs derived from elasticity modeling of equipment replacement cycles and software licensing attach rates. Forecast inputs incorporate NMPA innovation fast-track approval velocities and EU MDR recertification timelines for algorithm-dependent platforms.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled diagnostic algorithms achieving dermatopathologist consensus parity would alter the outlook. Forecasts reflect assumptions regarding regulatory clearance timelines, reimbursement code establishment, and semiconductor supply continuity that could revise projections if disrupted. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market