
 Drug-Loaded Oral Thin Films Market | 2026-2036
Drug-Loaded Oral Thin Films Market Size, Share, and Industry Trends Forecast 2026-2036
Drug-Loaded Oral Thin Films Market Analytics
Pullulan and hydroxypropyl methylcellulose is restructuring cost structures across the Drug-Loaded Oral Thin Films sector as manufacturers displace gelatin substrates to improve moisture stability and dissolution profiles. Aquestive Therapeutics, Inc. leverages its PharmFilm platform to dominate prescription thin film manufacturing for CNS and antiemetic therapies. IntelGenx Corp. anchors the generic thin film segment through vertically integrated formulation development and partnered commercialization models. ZIM Laboratories Limited specializes in complex generic thin films targeting emerging market access through technology licensing arrangements.
Drug-loaded oral thin films constitute polymeric matrix systems typically 50-500 microns in thickness, engineered for rapid buccal or sublingual disintegration within seconds to minutes without water co-administration. These systems incorporate active pharmaceutical ingredients into hydrophilic, hydrophobic, bioadhesive, or mucoadhesive polymer bases to achieve enhanced bioavailability and dose precision for patients with dysphagia or compliance limitations. Buprenorphine and ondansetron films command established revenue pools through addiction management and chemotherapy-induced nausea applications, while fentanyl thin films face structural headwinds amid intensified DEA scheduling and diversion controls. The homecare end user segment generates the fastest growth trajectory as post-acute care models shift administration away from institutional settings toward supervised outpatient protocols.
FDA bioequivalence requirements under 21 CFR 320, EMA quality guidelines for oromucosal preparations, and USP dissolution standards collectively govern product development timelines and commercialization barriers for thin film developers. The FDA's 505(b)(2) regulatory pathway enables reduced clinical burden for reformulated products, though the agency demands rigorous in vitro-in vivo correlation data for polymer matrix substitutions. Stakeholders must monitor evolving pharmacovigilance obligations for abuse-deterrent labeling and real-world evidence requirements as payers tighten reimbursement criteria for differentiated delivery formats.
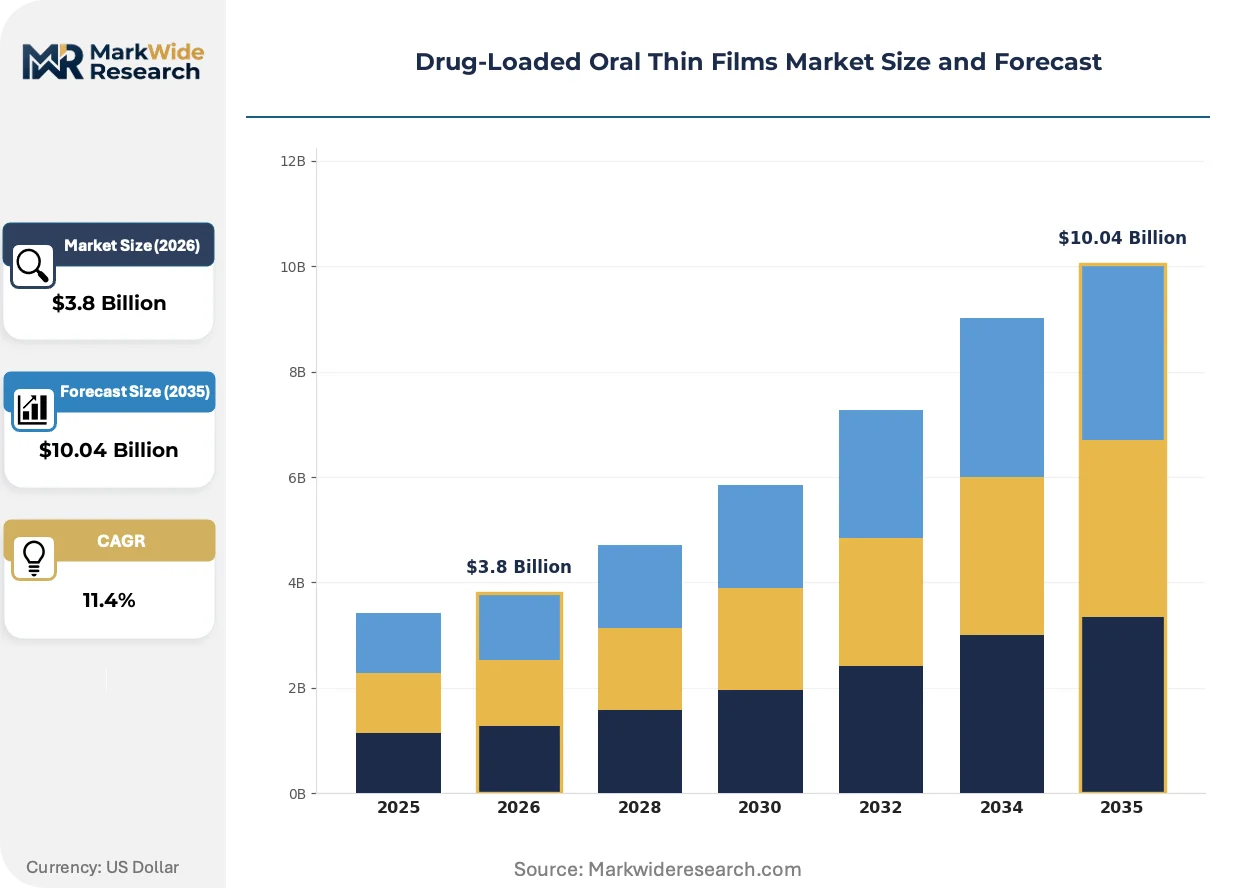
Market Dynamics
Pullulan-based polymer matrices are displacing gelatin substrates across formulation development, compressing moisture stability failure rates and accelerating dissolution profile standardization for manufacturers targeting FDA 505(b)(2) submissions.
Growth Catalysts
- EMA Accelerated Assessment:The European Medicines Agency's priority review pathway for improved formulations reduces regulatory timelines for thin film developers seeking oromucosal drug delivery approvals.
- Pediatric Dysphagia Prevalence:Hospital and homecare settings report rising demand for water-independent dosage forms among pediatric patients with swallowing disorders.
- Polymer Matrix Innovation:Hydroxypropyl methylcellulose substrates enable faster buccal disintegration and enhanced bioavailability compared to conventional tablet formulations.
Market Restraints
- DEA Scheduling Controls:Fentanyl thin films face intensified Drug Enforcement Administration diversion monitoring and distribution restrictions that limit prescriber access.
- Specialized Manufacturing Concentration:Commercial-scale PharmFilm production capacity concentrates among limited contract development and manufacturing organizations.
- In Vitro-In Vivo Correlation Burden:FDA demands extensive IVIVC data for polymer substitutions, extending development timelines for reformulated products.
Strategic Opportunities
- Generic Thin Film White Space:Complex generic formulations targeting emerging markets through technology licensing arrangements bypass originator patent thickets.
- Homecare Administration Shift:Post-acute care models create demand for supervised outpatient protocols using sublingual antiemetic and CNS therapies.
- Abuse-Deterrent Labeling Premium:Payer reimbursement criteria increasingly favor differentiated delivery formats with real-world evidence supporting diversion resistance.
Industry Challenges
- Formulation Scientist Scarcity:Mucoadhesive polymer expertise and buccal absorption modeling capabilities remain concentrated among specialized contract research organizations.
- USP Dissolution Standard Harmonization:Divergent dissolution testing protocols across FDA, EMA, and USP guidelines create compliance complexity for multi-jurisdictional filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug-Loaded Oral Thin Films Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buprenorphine, Ketorolac, Ondansetron, Fentanyl End User: Pharmacies, Hospitals, Clinics, Homecare Formulation: Hydrophilic, Hydrophobic, Bioadhesive, Mucoadhesive Distribution Channel: Online, Offline, Wholesalers, Distributors |
| Companies Covered | Aquestive Therapeutics, Inc., IntelGenx Corp., ZIM Laboratories Limited, C.L.Pharm, CURE Pharmaceutical, LTS Lohmann Therapie-Systeme AG, NAL Pharma, Indivior Plc, MonoSol Rx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug-Loaded Oral Thin Films Market Evolving Landscape
Multilayer thin film architectures are converging with precision dosing requirements, enabling simultaneous release of incompatible APIs and reshaping competitive differentiation in addiction management and antiemetic categories.
Nanocrystal incorporation into hydrophilic polymer bases is converging with bioavailability enhancement objectives for poorly soluble compounds. Oncology and CNS therapeutic developers adopt these architectures to achieve therapeutic equivalence with reduced dose volumes. This convergence is compressing clinical development timelines for reformulated products by improving pharmacokinetic predictability in early-phase studies.
FDA's evolving pharmacovigilance framework for oromucosal preparations mandates real-world evidence collection for abuse-deterrent claims. Manufacturers must establish post-market surveillance infrastructure to maintain 505(b)(2) labeling advantages. Addiction management and pain therapeutic categories face the steepest compliance burden as DEA scheduling reviews intensify.
Hospital procurement committees now require water-independent administration protocols for dysphagia-capable patient populations. This specification displaces conventional tablet and liquid formulations in chemotherapy and post-surgical nausea protocols. United States and German acute care networks lead this specification shift, with Japan's geriatric care facilities following comparable adoption curves.
Drug-Loaded Oral Thin Films Market Segmentation
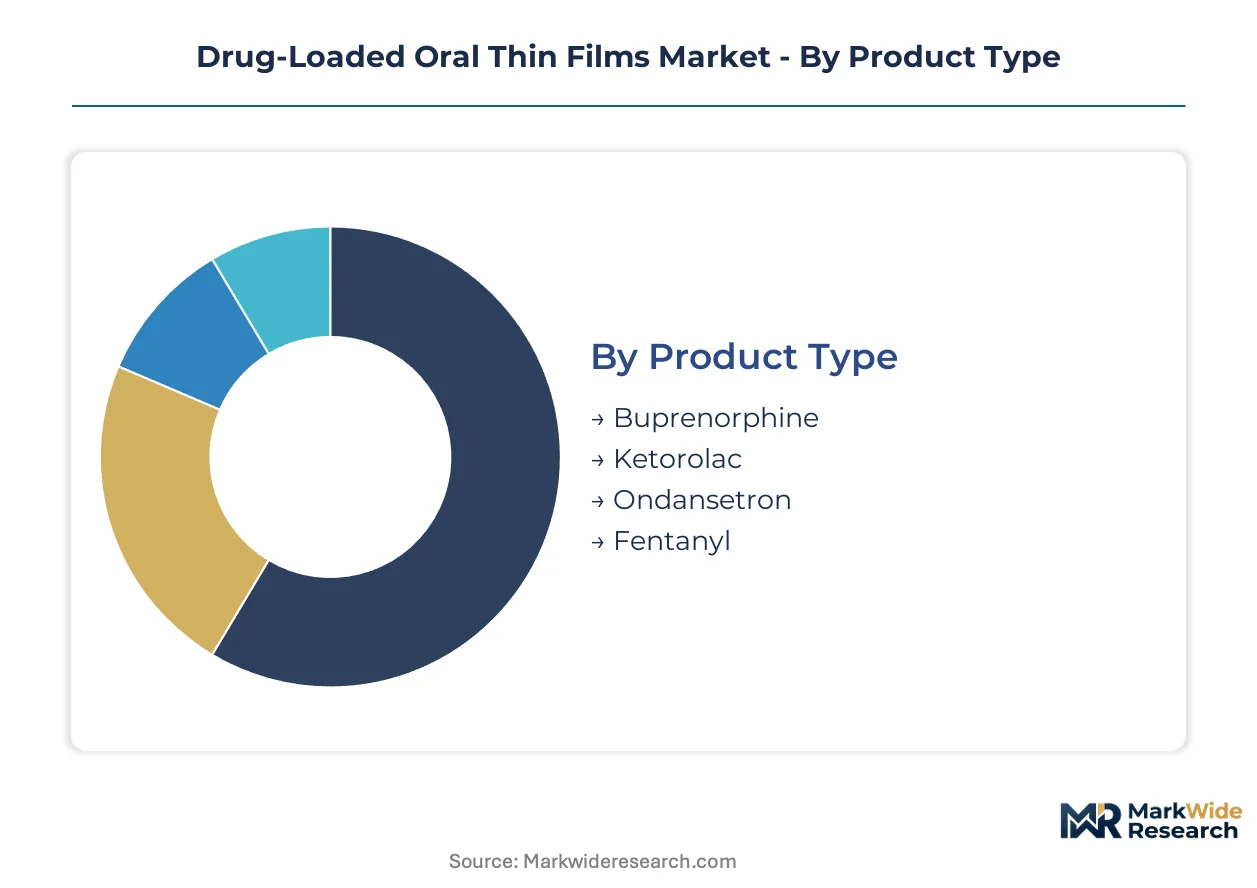
Drug-loaded oral thin films fragment across therapeutic molecule, care setting, polymer chemistry, and route-to-patient dimensions. Each axis carries distinct margin profiles, regulatory burdens, and manufacturing scale requirements that reshape competitive positioning.
Product Type:
Buprenorphine and ondansetron concentrate revenue at premium price points, while ketorolac and fentanyl occupy structurally different commercial niches shaped by scheduling and generic competition.
- Buprenorphine:Polymer matrix formulations for opioid use disorder achieve rapid sublingual absorption with abuse-deterrent properties. Hospital and homecare addiction protocols in the United States drive procurement concentration amid DEA distribution quotas.
- Ondansetron:Antiemetic thin films disintegrate within seconds for chemotherapy-induced nausea management. Pediatric oncology units and post-surgical wards specify water-independent administration, compressing tablet substitution rates.
- Ketorolac:Non-opioid analgesic films target acute pain episodes with buccal delivery bypassing first-pass metabolism. Generic manufacturers exploit patent-expired formulations for emerging market access.
- Fentanyl:Transmucosal delivery faces intensified diversion monitoring and prescriber registration requirements. DEA scheduling constraints limit distribution to certified addiction specialists and palliative care networks.
Today's leader: Buprenorphine. Tomorrow's challenger: Ondansetron.
End User:
Institutional procurement specifications diverge sharply from direct-to-patient channels on formulation complexity, reimbursement coding, and compliance documentation requirements.
- Pharmacies:Retail dispensaries stock sublingual films for chronic therapy refills with standardized counseling protocols. United States chain pharmacies deploy specialized cold-chain handling for temperature-sensitive polymer matrices.
- Hospitals:Acute care networks mandate water-independent dosage forms for dysphagia-capable populations in chemotherapy and surgical recovery units. German and Japanese hospital formularies lead specification adoption for rapid-disintegration requirements.
- Clinics:Outpatient specialty practices favor single-unit packaging for controlled substance accountability. Addiction medicine clinics in the United States prefer buprenorphine films with tamper-evident dispensing.
- Homecare:Supervised outpatient protocols create demand for patient-administered sublingual therapies with remote monitoring integration. Post-acute care models shifting from institutional settings drive the steepest volume expansion trajectory.
Institutional buyers dominate current procurement volumes; homecare channels are expanding most quickly as reimbursement shifts toward outpatient administration.
Formulation:
Polymer base selection determines moisture stability, dissolution kinetics, and manufacturing yield—variables that concentrate expertise among specialized contract development organizations.
- Hydrophilic:Pullulan and hydroxypropyl methylcellulose matrices achieve sub-60-second buccal disintegration for rapid onset therapies. FDA 505(b)(2) submissions favor these substrates for bioequivalence predictability.
- Mucoadhesive:Carbomer and polycarbophil bases extend residence time for sustained API release across buccal membranes. Chronic pain and addiction management applications specify these formulations for prolonged therapeutic windows.
- Hydrophobic:Ethyl cellulose and lipid-based matrices protect moisture-sensitive APIs from environmental degradation. Tropical climate distribution requirements in emerging markets drive adoption.
- Bioadhesive:Chitosan and alginate composites combine mucoadhesion with permeation enhancement for poorly soluble compounds. Oncology developers specify these for bioavailability-challenged chemotherapeutics.
Hydrophilic platforms anchor current manufacturing capacity; mucoadhesive systems are gaining share fastest as extended-release applications multiply.
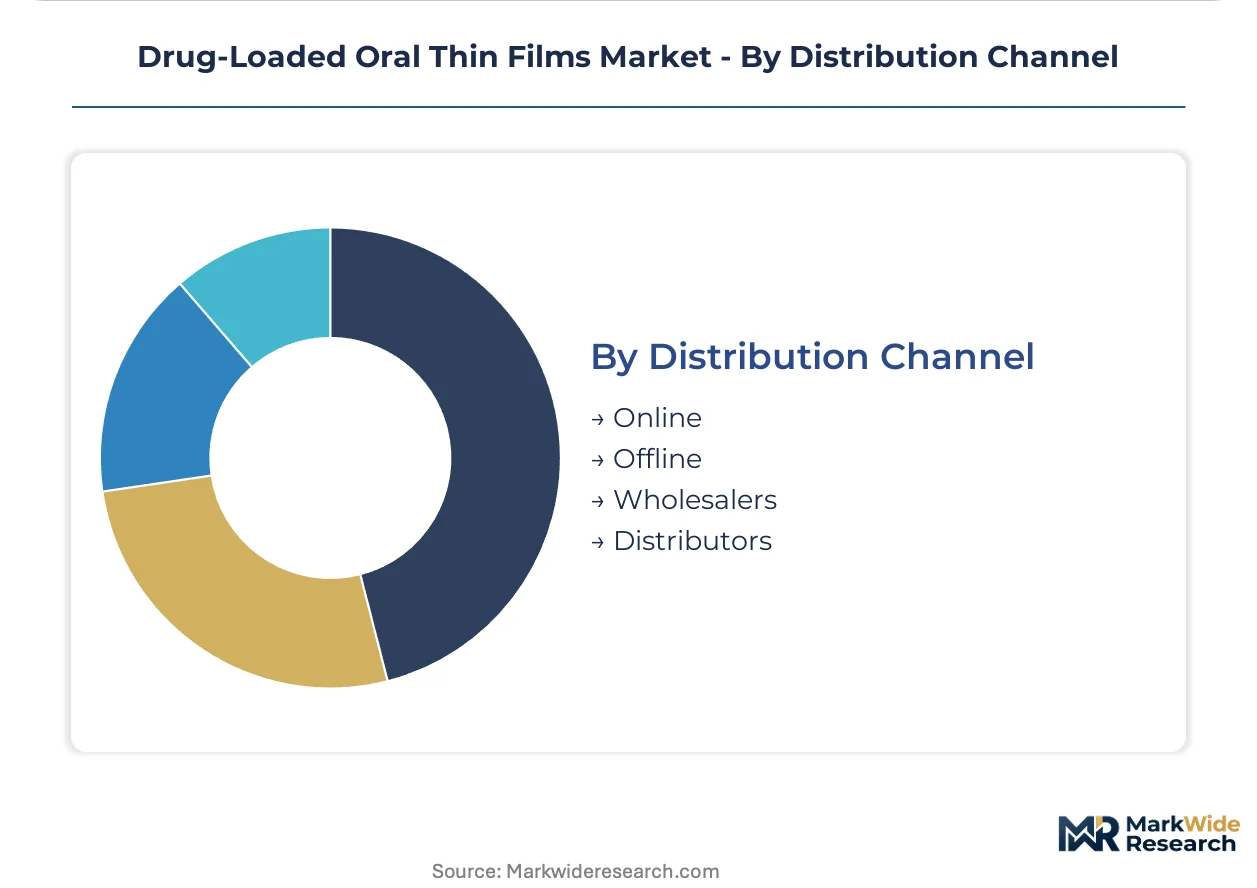
Distribution Channel:
Channel selection reflects controlled substance scheduling, cold-chain requirements, and patient education burdens that fragment logistics strategies across therapeutic categories.
- Offline:Brick-and-mortar pharmacies and hospital dispensaries handle DEA-regulated films with physical custody documentation. United States wholesale distributors maintain specialized vault infrastructure for Schedule III-V thin films.
- Online:Telehealth-integrated pharmacies ship non-controlled sublingual therapies with temperature-monitoring logistics. Direct-to-patient models expand for ondansetron and over-the-counter equivalent formulations.
- Wholesalers:National distributors aggregate demand across retail chains with inventory management systems tracking lot-level traceability. McKesson and Cardinal Health networks dominate United States controlled substance distribution.
- Distributors:Regional specialists service independent pharmacies and long-term care facilities with customized unit-dose packaging. Emerging market access relies on these intermediaries for regulatory compliance navigation.
Offline channels retain controlled substance dominance; online infrastructure is climbing the fastest as telehealth prescribing normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical thin film manufacturing clusters in the United States, Germany, and Japan concentrate formulation expertise and regulatory infrastructure for rapid-disintegration drug delivery systems.
United States
Pediatric oncology units and addiction medicine clinics drive procurement of sublingual buprenorphine and ondansetron films. FDA's 505(b)(2) pathway accelerates approval timelines for reformulated products with established bioequivalence. New Jersey and North Carolina host contract manufacturing organizations specializing in PharmFilm production for CNS therapeutics.
Germany
Hospital formularies specify water-independent dosage forms for dysphagia-capable populations in chemotherapy and surgical recovery settings. EMA accelerated assessment programs prioritize oromucosal preparations with improved patient compliance. The Rhine-Ruhr metropolitan region anchors European thin film manufacturing capacity for mucoadhesive polymer matrices.
Japan
Geriatric care facilities adopt rapid-disintegration films for patients with swallowing disorders in post-acute care protocols. PMDA guidelines for oromucosal drug delivery align with international dissolution standards while maintaining distinct stability testing requirements. The Kansai region around Osaka concentrates formulation development expertise for bioadhesive polymer systems.
India
Generic manufacturers target emerging market access through technology licensing arrangements for complex thin film formulations. CDSCO approval pathways for improved formulations streamline entry for reformulated products with enhanced bioavailability. Hyderabad and Ahmedabad host contract research organizations specializing in buccal absorption modeling and polymer matrix optimization.
Switzerland
Specialty pharmaceutical developers leverage precision dosing capabilities for oncology and CNS therapeutic categories. Swissmedic maintains harmonized standards with EMA quality guidelines while offering expedited review for pediatric formulations. The Basel pharmaceutical cluster integrates nanocrystal incorporation expertise with polymer science capabilities for poorly soluble compounds.
Drug-Loaded Oral Thin Films Market Competitive Landscape
Global majors compete with regional champions across polymer matrix innovation and regulatory pathway expertise, creating a tiered structure where specialized contract development organizations command premium positioning. The vendor base separates into three strategic archetypes: vertically integrated platform developers, generic-focused technology licensors, and specialized manufacturing contractors. Capacity expansion and strategic technology licensing agreements constitute the dominant competitive moves as participants seek to secure 505(b)(2) submission capabilities.
Within the platform technology tier, Aquestive Therapeutics, Inc. and IntelGenx Corp. occupy positions as North American anchors for prescription and generic thin film development respectively. ZIM Laboratories Limited exemplifies the emerging market-focused archetype through its technology licensing model. LTS Lohmann Therapie-Systeme AG represents European manufacturing concentration for transdermal and oromucosal delivery systems.
| Leading Market Players |
|---|
| Aquestive Therapeutics, Inc. |
| IntelGenx Corp. |
| ZIM Laboratories Limited |
| C.L.Pharm |
| CURE Pharmaceutical |
| LTS Lohmann Therapie-Systeme AG |
| NAL Pharma |
| Indivior Plc |
| MonoSol Rx |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA-validated 505(b)(2) submissions and emerging-market CDSCO filings splits pricing power across supply chain configurations. Premium polymer matrix formulations command three-to-five-fold markups over commodity gelatin substrates, with validated cold-chain logistics and DEA-compliant distribution infrastructure concentrating procurement leverage among United States and German hospital networks.
Pricing Analysis
Input-cost pass-through from pullulan and hydroxypropyl methylcellulose substrate suppliers compresses margins for generic thin film manufacturers while insulating premium platform developers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence validation, polymer innovation premiums, and volume scale. Pricing pressure stems from Indian generic manufacturers licensing technology into emerging markets with reduced regulatory burden. Hospital procurement committees exhibit lowest price sensitivity; retail pharmacy chains show highest elasticity.
Supply Chain Analysis
Warehouse-distribution layer concentration in New Jersey, North Carolina, and the Rhine-Ruhr metropolitan region creates hub-and-spoke patterns for temperature-sensitive polymer matrices. Raw material supply draws from United States hydroxypropyl methylcellulose producers, Indian pullulan extractors, and German carbomer specialists. Single-source vulnerability concentrates in PharmFilm manufacturing capacity held by limited contract development organizations. Distribution runs through McKesson and Cardinal Health networks for DEA-scheduled films, with regional specialists handling emerging market compliance navigation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Drug-Loaded Oral Thin Films Market functions as a stable compounder, with pediatric dysphagia prevalence and geriatric care protocol standardization generating predictable volume expansion across hospital and homecare channels.
For Market Incumbents: Deploy polymer matrix IP licensing to extend platform revenue beyond direct manufacturing. Secure backward integration into pullulan supply to offset raw material cost volatility from Indian extractors. Defend against generic erosion by accelerating FDA 505(b)(2) submissions for multilayer architectures with abuse-deterrent claims.
For New Entrants and Emerging Players: The price-point gap between premium Aquestive-platform CNS films and economy-grade ketorolac generics creates entry space for mid-tier mucoadhesive specialists. Target German hospital formularies with EMA-validated extended-release formulations. Pursue technology licensing arrangements with Indian CDSCO-registered manufacturers for emerging market access.
For Investors and Strategic Acquirers: Consolidation pressure builds where contract manufacturing capacity scarcity intersects with 505(b)(2) submission expertise concentration. Five-to-ten-year viability favors vertically integrated platform developers with captive polymer science capabilities. Acquisition target archetype: specialized buccal absorption modeling firms with FDA-established IVIVC databases. Watch DEA scheduling review outcomes for fentanyl films as regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Matrix IP Licensing | Enables revenue extraction from generic manufacturers without capital-intensive capacity expansion. |
| FDA 505(b)(2) Submission Acceleration | Compresses approval timelines for reformulated products with established bioequivalence pathways. |
| Backward Integration into Pullulan Supply | Reduces moisture stability failure rates and insulates margins from Indian extractor pricing volatility. |
| EMA Accelerated Assessment Pursuit | Prioritizes oromucosal preparations for German hospital formulary adoption and European market access. |
| Homecare Distribution Partnership | Captures fastest-growing end-user segment through supervised outpatient protocol integration. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement records, polymer supply chain documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and contract manufacturing officers supplied qualitative validation. Secondary sources included FDA 505(b)(2) submissions, EMA accelerated assessment decisions, CDSCO approval records, USP dissolution standards, and hospital GPO contract databases.
Data-stream reconciliation across the analysis window employed segmentation modeling by therapeutic molecule, care setting, polymer chemistry, and route-to-patient dimensions. CAGRs were derived from volume-weighted projections incorporating pediatric dysphagia prevalence trajectories, DEA scheduling enforcement intensity, and polymer substrate cost curves. Forecast inputs included EMA priority review pathway utilization rates and homecare reimbursement policy shifts.
The model assumes a particular technology adoption path; alternative pathways for nanocrystal-incorporated bioadhesive matrices would alter the outlook for bioavailability-challenged compounds. Forecasts reflect stated assumptions regarding FDA pharmacovigilance evolution and DEA diversion control tightening. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Encephalitis Vaccine Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Gabapentin Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market