
 Nanobiosensors in Healthcare Market | 2026-2036
Nanobiosensors in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Nanobiosensors in Healthcare Market Outlook
Hospital procurement channels for nanobiosensor platforms is fragmenting as point-of-care testing decentralizes beyond centralized laboratories. Abbott anchors its position through vertical integration across glucose monitoring and cardiac biomarker detection. Dexcom competes through sustained R&D intensity in continuous glucose monitoring wearables. Roche differentiates via its established diagnostics distribution network spanning research labs and clinical settings.
Nanobiosensors in healthcare integrate nanomaterials—typically gold nanoparticles, carbon nanotubes, or quantum dots—with biological recognition elements to detect analytes at picomolar concentrations, serving precision diagnostics and real-time physiological monitoring. Wearable sensors and point-of-care devices command the dominant revenue share as chronic disease management shifts from episodic clinic visits to ambulatory data collection. Electrochemical technology leads in commercial deployment due to lower manufacturing complexity and established readout electronics, while optical platforms capture premium positioning in multiplexed assay applications.
The FDA regulates nanobiosensors as Class II or Class III medical devices depending on intended use, with the 21st Century Cures Act streamlining breakthrough designation pathways. ISO 13485 quality management standards govern manufacturing consistency for devices entering European and North American markets. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payors recalibrate coverage for decentralized diagnostic outputs.
Market Dynamics
Decentralization of diagnostic workflows is fragmenting procurement channels as hospital systems shift from centralized laboratories to distributed point-of-care testing nodes. This structural reconfiguration compresses traditional distribution hierarchies and forces manufacturers to reconfigure go-to-market architectures around ambulatory care networks.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated approval pathways compress time-to-market for novel sensing platforms, enabling faster commercialization of electrochemical and optical nanobiosensor systems.
- Chronic Disease Surveillance:Diabetes and cardiovascular monitoring programs in the United States drive sustained demand for continuous glucose monitoring and cardiac biomarker detection devices.
- Gold Nanoparticle Conjugation:Advances in surface chemistry enable picomolar sensitivity thresholds, expanding detectable analyte ranges for infectious disease and oncology applications.
Market Restraints
- Platinum Group Metal Volatility:Electrode fabrication depends on palladium and ruthenium thin-film deposition, exposing manufacturers to raw material price swings from South African and Russian supply corridors.
- Cleanroom Manufacturing Intensity:ISO 14644 Class 7-8 environments for nanomaterial synthesis require capital outlays exceeding conventional diagnostic device production by threefold.
- Reimbursement Code Lag:CMS and private payors maintain limited coverage categories for remote patient monitoring outputs, constraining provider willingness to adopt decentralized diagnostic infrastructure.
Strategic Opportunities
- Quantum Dot Multiplexing:Simultaneous detection of five-plus analytes from single-sample inputs creates premium positioning in emergency department triage and sepsis screening protocols.
- India PLI Scheme:Production-linked incentives for medical device manufacturing attract contract development partners seeking cost-competitive nanofabrication capacity outside established North American and European bases.
- Carbon Nanotube Wearables:Flexible substrate integration enables sweat-based metabolite monitoring for athletic performance and occupational health verticals currently underserved by invasive sampling methods.
Industry Challenges
- Biofouling Mitigation Expertise:Surface engineering talent capable of designing antifouling coatings for implantable sensors remains concentrated within academic research institutions, creating recruitment bottlenecks for commercial scale-up.
- ISO 13485 Certification Timelines:Quality management system audits for nanomaterial-containing devices extend eighteen to twenty-four months, delaying European market entry relative to conventional Class II diagnostics.
- Interoperability Architecture:Legacy electronic health record systems lack standardized APIs for real-time biosensor data ingestion, forcing point-of-care device manufacturers to maintain multiple integration workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanobiosensors in Healthcare Market |
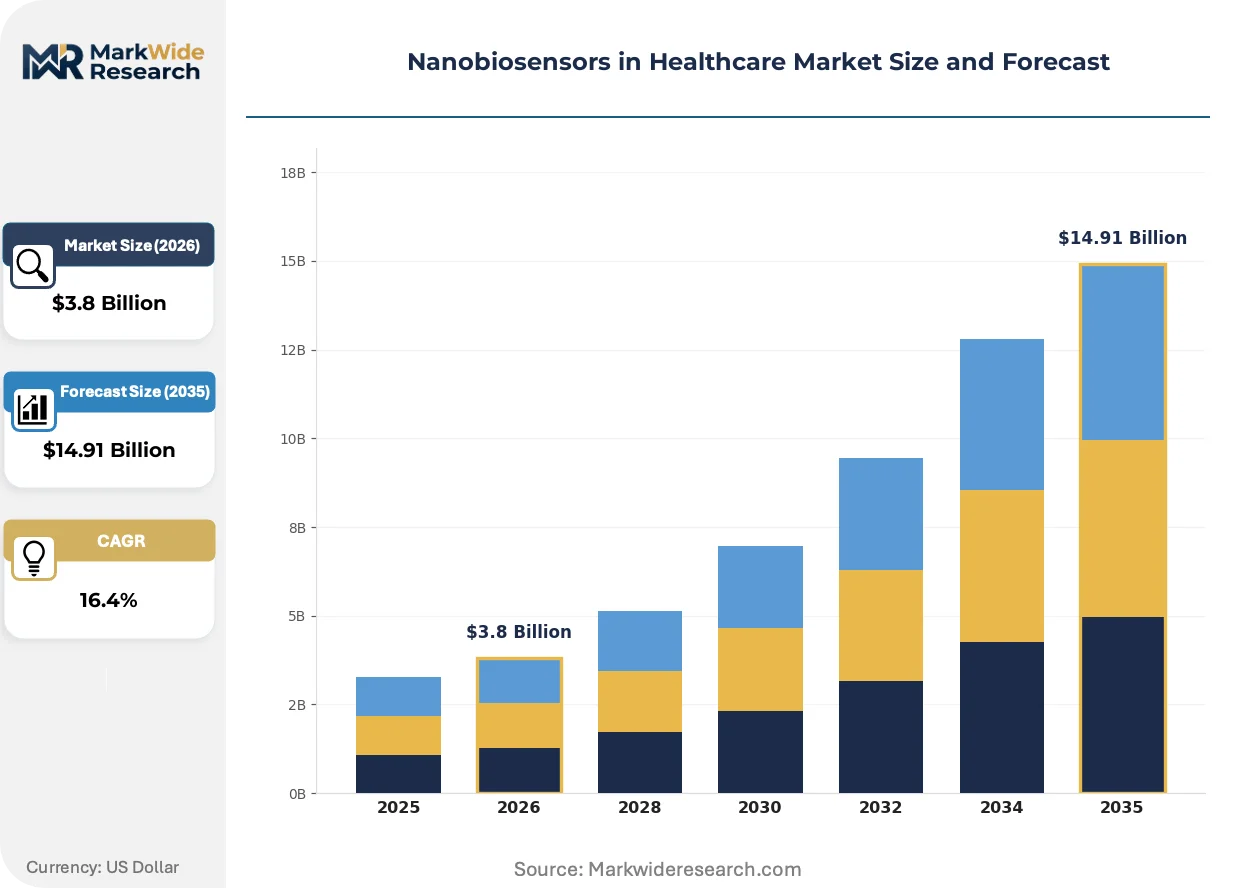
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Sensors, Point-of-Care Devices, Lab-On-A-Chip Technology: Electrochemical, Optical, Magnetic, Piezoelectric Application: Diagnostics, Drug Delivery, Monitoring, Therapeutics End User: Hospitals, Research Labs, Diagnostic Centers, Clinics |
| Companies Covered | Bio-Rad Laboratories, Dexcom, Abbott, Universal Biosensors, Biosensors International Group, Roche, DuPont, ACON Laboratories, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanobiosensors in Healthcare Market Strategic Shifts
Convergence of nanomaterial synthesis with semiconductor manufacturing methods is compressing sensor form factors while expanding functional density. These developments are reconfiguring competitive advantage around fabrication scale rather than biological recognition chemistry alone.
Silicon photonics is virtualizing optical detection platforms by replacing bulk optical components with integrated waveguide structures. Cardiology departments in German university hospitals are piloting these systems for troponin quantification at fifteen-minute turnaround times. The technology is virtualizing the economics of multiplexed assay deployment, collapsing the cost differential between single-analyte and multi-panel testing.
EMA's In Vitro Diagnostic Medical Devices Regulation (IVDR) reclassification requirements are forcing manufacturers to generate clinical evidence for legacy nanobiosensor products previously grandfathered under the IVDD framework. This regulatory compression is advantaging firms with established notified body relationships and documented post-market surveillance databases. Smaller developers without Class D device experience are exiting the European market or seeking acquisition by established diagnostics conglomerates.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts that bundle devices, consumables, and data analytics subscriptions. This purchasing concentration displaces standalone sensor suppliers unable to demonstrate longitudinal patient management value. The shift is most pronounced in United States integrated delivery networks managing risk-based contracts for Medicare Advantage populations.
Nanobiosensors in Healthcare Market Segmentation
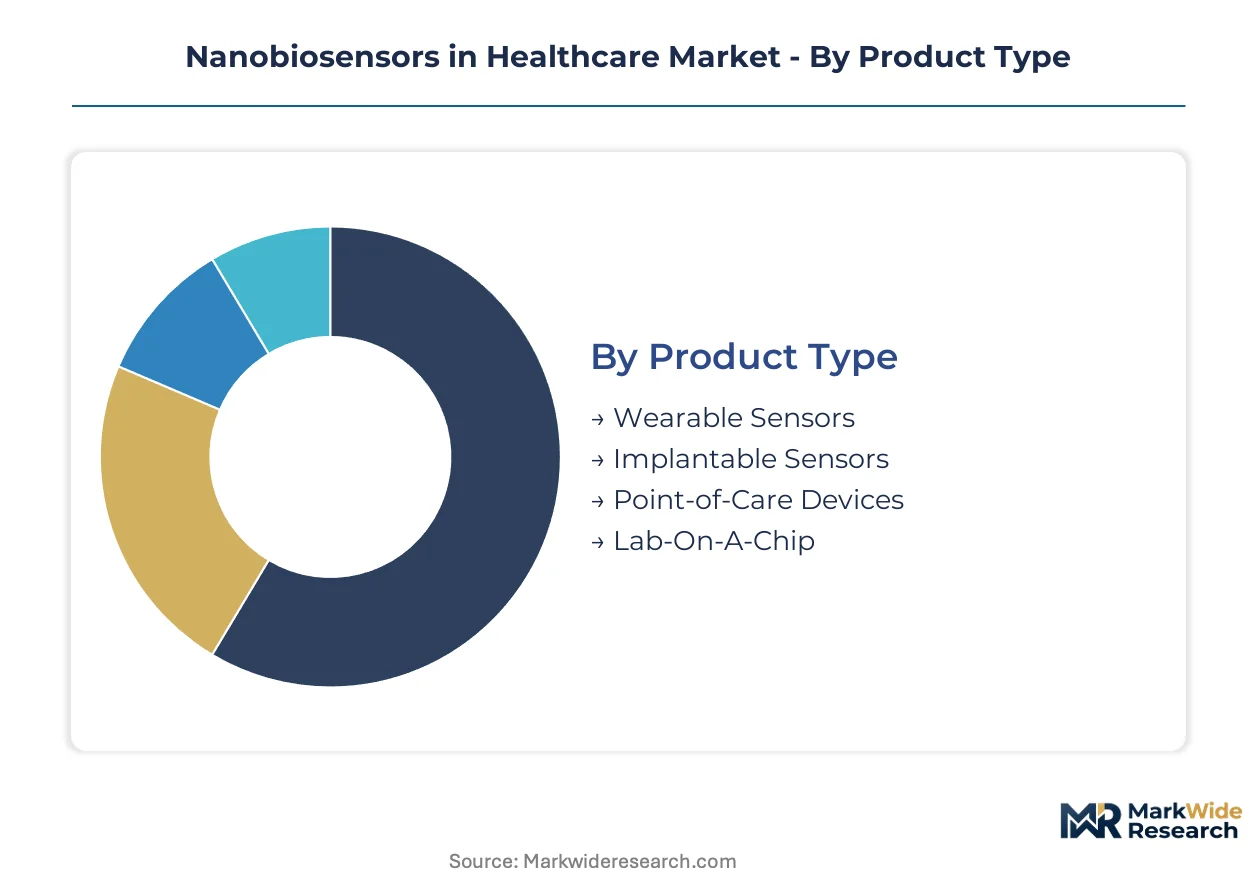
Nanobiosensor architectures diverge sharply across clinical workflows, with form factor and readout technology determining reimbursement eligibility and procurement channel access. Manufacturers must align product portfolios against specific end-user infrastructure constraints rather than pursuing undifferentiated platform strategies.
Product Type:
Mature wearable formats coexist with emerging implantable systems at vastly different regulatory maturity levels.
- Wearable Sensors:Continuous glucose monitors and cardiac patch electrodes dominate ambulatory revenue streams. United States Medicare Advantage contracts now bundle these devices with remote patient monitoring codes, accelerating hospital system procurement.
- Point-of-Care Devices:Handheld electrochemical readers deliver troponin and infectious disease results at fifteen-minute turnaround times. German university hospitals are piloting silicon photonics integration to collapse multiplexed assay costs.
- Implantable Sensors:Subcutaneous glucose monitors and intracardial pressure transducers face extended FDA Class III approval timelines. Biofouling mitigation expertise remains concentrated in academic institutions, constraining commercial scale-up.
- Lab-On-A-Chip:Microfluidic cartridges for sepsis screening and pharmacokinetic monitoring require ISO 14644 cleanroom fabrication. India's PLI scheme is attracting contract manufacturing partners seeking cost-competitive nanofabrication capacity.
Wearable sensors retain volume leadership; implantable systems hold the steepest expansion curve pending breakthrough device designations.
Technology:
Cost tiers separate established electrochemical platforms from premium optical multiplexing architectures.
- Electrochemical:Amperometric and potentiometric transducers using gold nanoparticle-modified electrodes achieve picomolar sensitivity at manufacturing complexity below optical alternatives. Abbott and Roche have anchored commercial positions through vertical integration across electrode fabrication and readout electronics.
- Optical:Surface plasmon resonance and fluorescence resonance energy transfer enable simultaneous five-plus analyte detection from single-sample inputs. Silicon photonics integration is virtualizing bulk optical components into waveguide structures at German cardiology departments.
- Magnetic:Giant magnetoresistance sensors detect biomagnetic signals for neural and cardiac applications. Superparamagnetic nanoparticle functionalization requires specialized surface chemistry expertise currently scarce outside academic research institutions.
- Piezoelectric:Quartz crystal microbalance transducers measure mass changes from biomolecular binding events. These platforms occupy niche positions in research laboratory settings where real-time kinetic analysis commands premium pricing.
Electrochemical formats dominate unit economics; optical platforms are climbing the fastest as silicon photonics compresses multiplexed deployment costs.
Application:
Customer workflows stratify across episodic diagnostic testing and continuous physiological surveillance.
- Diagnostics:Acute infectious disease and oncology biomarker detection command highest reimbursement rates in United States hospital outpatient settings. FDA breakthrough device pathways are compressing time-to-market for novel sensing platforms in this category.
- Monitoring:Chronic disease surveillance for diabetes and cardiovascular conditions drives sustained demand for continuous data streams. Dexcom competes through sustained R&D intensity in wearable glucose monitoring form factors.
- Drug Delivery:Closed-loop insulin pumps and responsive chemotherapy release systems integrate biosensor feedback with therapeutic actuation. Regulatory complexity spans both device and pharmaceutical approval frameworks.
- Therapeutics:Photothermal and photodynamic therapy guidance using nanobiosensor-localized drug activation remains predominantly preclinical. Clinical evidence requirements under EMA IVDR reclassification are forcing smaller developers toward acquisition or market exit.
Diagnostics captures current revenue concentration; monitoring applications are gaining share fastest as risk-based contracts shift care toward ambulatory settings.
End User:
Procurement authority is fragmenting as testing decentralizes from centralized laboratories toward distributed clinical nodes.
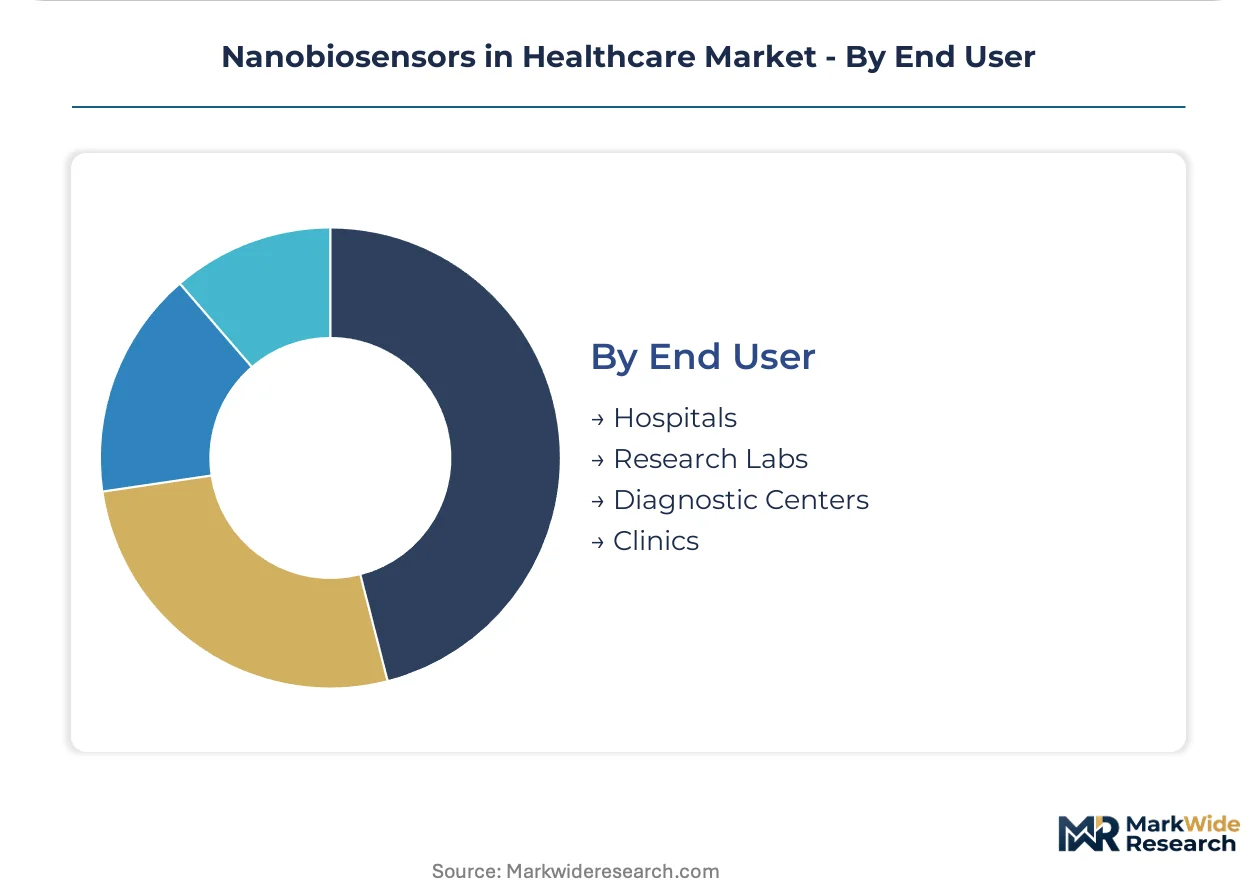
- Hospitals:Integrated delivery networks in the United States are consolidating vendor relationships around platform contracts bundling devices, consumables, and analytics subscriptions. This purchasing concentration displaces standalone sensor suppliers.
- Diagnostic Centers:Independent reference laboratories seek high-throughput multiplexed systems for esoteric testing panels. ISO 13485 certification timelines extending eighteen to twenty-four months delay European market entry for nanomaterial-containing devices.
- Clinics:Federally qualified health centers and urgent care chains drive point-of-care device adoption where reimbursement codes support decentralized diagnostic infrastructure. CMS coverage limitations constrain provider willingness in certain service categories.
- Research Labs:Academic medical centers and contract research organizations pilot emerging nanomaterial architectures before clinical translation. Biofouling mitigation and surface engineering talent recruitment bottlenecks impede technology transfer to commercial manufacturing.
Hospitals retain procurement volume leadership; clinics are expanding most quickly as point-of-care testing nodes proliferate in ambulatory networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while procurement cost sensitivity defines Indian hospital adoption curves. German university hospitals pilot premium optical platforms, whereas Chinese manufacturers compete on electrochemical unit economics.
United States
Medicare Advantage risk-based contracts drive hospital system procurement of continuous glucose monitors and cardiac patch electrodes. FDA breakthrough device designations compress approval timelines for novel sensing platforms. The Boston-Cambridge corridor anchors glucose monitoring R&D concentration alongside Minnesota's cardiac device cluster.
Germany
University hospital cardiology departments pilot silicon photonics integration for fifteen-minute troponin quantification. EMA IVDR reclassification forces clinical evidence generation for legacy nanobiosensor products. The Baden-Württemberg precision engineering belt concentrates cleanroom nanofabrication capacity for diagnostic device production.
China
NMPA streamlined approval pathways accelerate domestic electrochemical sensor commercialization for diabetes management. Dual carbon goals pressure manufacturers toward green nanomaterial synthesis methods. The Yangtze River Delta hosts contract manufacturing clusters serving export markets with cost-competitive electrode fabrication.
India
Production-linked incentive schemes attract medical device manufacturing seeking alternatives to North American and European production bases. CDSCO regulatory harmonization efforts align with ISO 13485 quality standards for export market access. Gujarat and Maharashtra industrial corridors concentrate cleanroom infrastructure investments for lab-on-a-chip fabrication.
Japan
PMDA's structured consultation pathways support novel nanomaterial safety assessments for implantable sensor applications. METI funding programs target carbon nanotube wearable development for aging population health monitoring. The Kansai region's chemical industry cluster supplies surface chemistry expertise for antifouling coating development.
Nanobiosensors in Healthcare Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying electrode materials and biological recognition elements. Market structure tilts toward consolidation as hospital procurement committees bundle devices, consumables, and analytics subscriptions into integrated contracts. Three archetypes dominate: diversified diagnostics conglomerates with captive distribution networks, pure-play wearable sensor developers with sustained R&D intensity, and contract manufacturers leveraging India's PLI scheme for cost-competitive nanofabrication. Competitive moves center on M&A to acquire surface engineering talent and strategic partnerships to secure platinum group metal supply corridors.
Within the diversified diagnostics tier, Abbott and Roche exemplify platform integrators with vertical control over electrode fabrication and readout electronics distribution. Dexcom occupies a position as the pure-play wearable specialist, representing sustained R&D intensity in continuous glucose monitoring form factors. Among contract development partners, Universal Biosensors anchors the outsourced nanofabrication archetype, sitting within supply chains seeking cost-competitive production outside established North American and European bases.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Dexcom |
| Abbott |
| Universal Biosensors |
| Biosensors International Group |
| Roche |
| DuPont |
| ACON Laboratories |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Freight corridors connecting South African platinum group metal mines to East Asian electrode fabrication hubs transmit raw material volatility directly into nanobiosensor cost structures. This logistics architecture concentrates pricing power with thin-film deposition specialists while forcing device manufacturers to absorb margin compression or pass through to hospital procurement committees.
Pricing Analysis
The customization-premium spread separates ISO 13485-certified electrochemical platforms from standard glucose monitoring strips by threefold at the hospital procurement tier. Pricing stratifies across premium optical multiplexing, standard electrochemical wearables, and economy-grade point-of-care readers. Cost compression in the economy tier is intensifying as Indian contract manufacturers exploit PLI scheme subsidies. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks managing Medicare Advantage risk contracts show lowest sensitivity due to bundled reimbursement structures.
Supply Chain Analysis
Upstream feedstock for gold nanoparticle synthesis draws from Australian mining operations and Chinese refining complexes before reaching electrode fabrication facilities. Palladium and ruthenium thin-film deposition rests on South African and Russian supply corridors. Single-source vulnerability in superparamagnetic nanoparticle functionalization creates bottlenecks for neural and cardiac magnetic sensor applications. Distribution runs through diversified diagnostics conglomerates with captive logistics networks serving hospital systems and research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nanobiosensor healthcare applications sit in early-cycle expansion as FDA breakthrough device designations compress commercialization timelines for novel sensing platforms. Chronic disease surveillance tailwinds in diabetes and cardiovascular monitoring sustain penetration growth across ambulatory care networks.
For Market Incumbents: Insulate electrode fabrication margins through backward integration into gold nanoparticle synthesis or captive palladium supply agreements. Secure surface engineering talent from academic institutions before competitors exhaust the limited pool of biofouling mitigation specialists. Prioritize ISO 13485 certification maintenance to defend European market position against IVDR reclassification pressures. For New Entrants and Emerging Players: Indian hospital procurement channels present the most penetrable geography for cost-competitive lab-on-a-chip manufacturing under PLI scheme coverage. Carbon nanotube wearables for occupational health monitoring offer white-space positioning currently underserved by invasive sampling incumbents. Target German university hospital pilot programs as reference customers for silicon photonics integration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract development partners with established cleanroom nanofabrication capacity and CDSCO regulatory alignment for export market access. Surface chemistry expertise concentrated in Japanese Kansi region chemical clusters represents acquisition target archetype with defensible IP moats. Watch FDA breakthrough device designation velocity as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated approval compresses time-to-market for picomolar-sensitivity electrochemical platforms. |
| CE Marking Pathway under IVDR | EMA reclassification demands clinical evidence generation for legacy nanobiosensor product retention. |
| Hospital System Partnership | Integrated delivery networks bundle devices with remote patient monitoring codes for Medicare Advantage. |
| Software Companion Development | Real-time biosensor data ingestion requires API standardization for legacy electronic health record systems. |
| Reimbursement Strategy | CMS coverage expansion for decentralized diagnostic outputs determines provider adoption willingness. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and nanomaterial synthesis specialists and refined through secondary validation against FDA 510(k) filings, EMA IVDR submission databases, CMS reimbursement code updates, and hospital procurement contract records. Bottom-up unit economics modeling triangulated with top-down market sizing across electrochemical and optical technology platforms.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product architecture, technology readout mechanism, clinical application workflow, and end-user procurement authority. CAGRs derived from patent filing velocity, regulatory approval throughput, and hospital capital expenditure tracking for point-of-care infrastructure. Nanomaterial cost curves and cleanroom capacity utilization fed supply-side constraints.
Practitioners should monitor platinum group metal price corridors and FDA breakthrough device designation grant rates for early signals of margin pressure and competitive entry timing. Forecasts reflect assumptions about reimbursement code expansion and IVDR audit timeline stability. Cross-checking against hospital procurement database benchmarks and GPO contract win rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market