
 Germany Diabetes Drugs Market | 2026-2036
Germany Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Diabetes Drugs Market Foresight
Specialized diabetes centers are redrawing prescribing patterns across Germany's fragmented outpatient landscape. Novo Nordisk leverages its integrated insulin and GLP-1 portfolio to anchor hospital formulary decisions in Bavaria and Baden-Württemberg. Sanofi competes through sustained manufacturing scale in recombinant insulin analogs, while Eli Lilly and Company differentiates via concentrated R&D investment in oral peptide delivery platforms.
Germany diabetes drugs comprise pharmaceutical agents engineered to regulate blood glucose through hormonal modulation, enzymatic inhibition, or renal glucose excretion, with molecular specifications ranging from recombinant human insulin to small-molecule SGLT-2 inhibitors formulated for bioavailability thresholds above 70 percent. These therapeutics serve to prevent microvascular and macrovascular complications in chronic metabolic disease management. GLP-1 agonists and SGLT-2 inhibitors now command the fastest expansion in drug class dynamics, displacing older oral agents as first-line combination therapy in type 2 diabetes protocols. Subcutaneous administration retains dominant volume share, though oral GLP-1 formulations are eroding injection burden in patient demographic segments prioritizing adherence convenience.
The Federal Joint Committee (G-BA) and the European Medicines Agency (EMA) jointly determine market access timelines through parallel health technology assessment and centralized marketing authorization, with Germany's AMNOG process capping launch prices for novel agents during the first year of reimbursement. The Medical Device Regulation (MDR) and In-Vitro Diagnostic Regulation (IVDR) increasingly govern companion diagnostics bundled with precision diabetes therapies, tightening conformity requirements for glucose monitoring integration. Stakeholders must monitor how the EU pharmaceutical legislation revision reshapes data exclusivity periods and whether Germany's regional sickness funds accelerate outcomes-based contracting for drug-device combinations.
Market Dynamics
Germany's Statutory Health Insurance reform is compressing reimbursement timelines for digital therapeutics paired with pharmacotherapy, forcing drug manufacturers to restructure launch sequences around AMNOG price caps and integrated care network procurement bundles.
Growth Catalysts
- AMNOG Fast-Track Pathways:The Federal Joint Committee's accelerated assessment procedures for combination therapies are shortening market access delays for GLP-1 agonists paired with continuous glucose monitoring systems.
- North Rhine-Westphalia Care Networks:Integrated diabetes management contracts in this region bundle drug provision with monitoring services, creating captive demand channels for formulary inclusion.
- SGLT-2 Inhibitor Protocol Expansion:Cardiovascular outcome data are elevating this drug class to first-line combination status in type 2 diabetes treatment algorithms across German hospital outpatient clinics.
Market Restraints
- Reference Pricing Compression:Germany's AMNOG process caps launch prices for novel agents during their first reimbursement year, constraining margin recovery for R&D-intensive portfolios.
- Recombinant Insulin Supply Concentration:Manufacturing scale advantages for established analog producers create barriers to entry for biosimilar challengers seeking hospital formulary slots.
- EMA-G-BA Parallel Assessment Friction:Divergent evidentiary requirements between centralized marketing authorization and national health technology assessment extend time-to-market for precision diabetes therapies.
Strategic Opportunities
- Baden-Württemberg Digital Health Corridors:Regional sickness funds in this state are piloting outcomes-based contracting models for drug-device combinations, creating testbeds for value-based pricing.
- Oral Peptide Delivery Platforms:Concentrated R&D investment in non-injectable GLP-1 formulations addresses adherence barriers in patient segments prioritizing convenience over injection efficacy.
- MDR Companion Diagnostic Bundling:The Medical Device Regulation's tightened conformity requirements for glucose monitoring integration create first-mover advantages for manufacturers with unified drug-sensor regulatory dossiers.
Industry Challenges
- AMNOG Evidence Generation Timelines:The twelve-month price negotiation window demands parallel real-world evidence collection, straining clinical operations teams.
- Legacy Hospital IT Integration:Continuous glucose monitoring data streams require interoperability with existing electronic health record architectures in Bavaria's specialized diabetes centers.
- Multistate Sickness Fund Variability:Divergent formulary preferences across Germany's regional insurance pools fragment commercialization strategies and field force deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Diabetes Drugs Market |
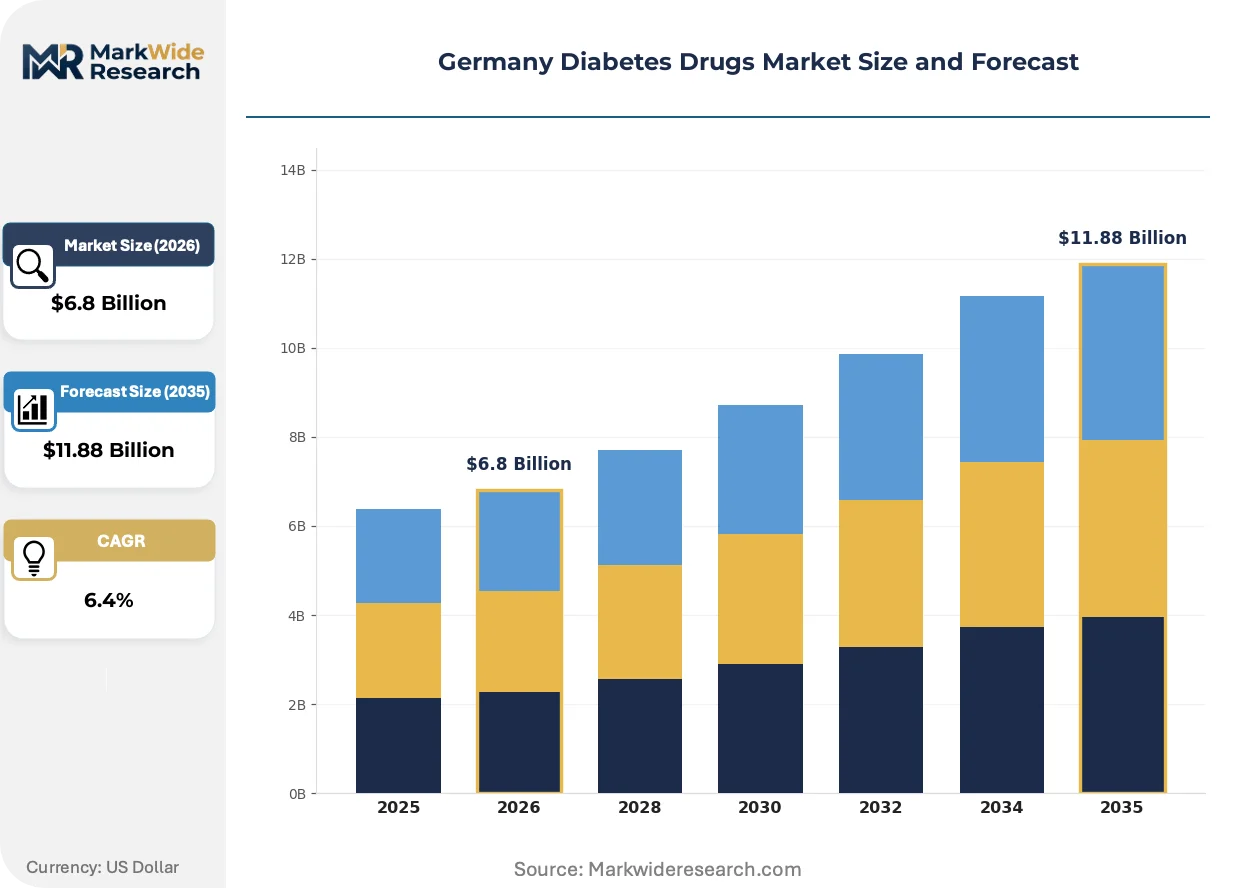
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT-2 Inhibitors Administration Route: Subcutaneous, Oral, Intravenous, Inhalation Treatment Stage: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pre-diabetes Patient Demographics: Adults, Adolescents, Elderly, Pediatric |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, AstraZeneca, Merck, Boehringer Ingelheim, Takeda, Pfizer, Janssen Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Diabetes Drugs Market Shifts & Advancements
Drug delivery modality innovation and regulatory bundling requirements are restructuring competitive advantage in Germany's diabetes therapeutics sector. Manufacturers must now synchronize molecular development with device conformity timelines.
Oral peptide delivery platforms are bifurcating the GLP-1 agonist market between injection-dependent and tablet-dependent patient pathways. Endocrinology practices in urban centers are adopting oral formulations at three times the rate of rural clinics. This modality split is compressing injection-volume forecasts while expanding total addressable patient populations previously excluded by needle aversion.
The EU Medical Device Regulation's 2021 enforcement is tightening glucose monitoring integration standards for precision diabetes therapies. Manufacturers now face synchronized EMA marketing authorization and notified body conformity assessment timelines. Bavarian hospital procurement offices are prioritizing bundled drug-sensor tenders that satisfy MDR technical documentation requirements in single-source awards.
Integrated care networks in North Rhine-Westphalia are unbundling traditional pharmacy dispensing from continuous monitoring service contracts. Regional sickness funds now contract separately with device suppliers and drug manufacturers, then reconcile outcomes data across both spend categories. This procurement fragmentation is most visible in the AOK Rhineland/Hamburg network's 2024 diabetes management tender structure.
Germany Diabetes Drugs Market Segmentation
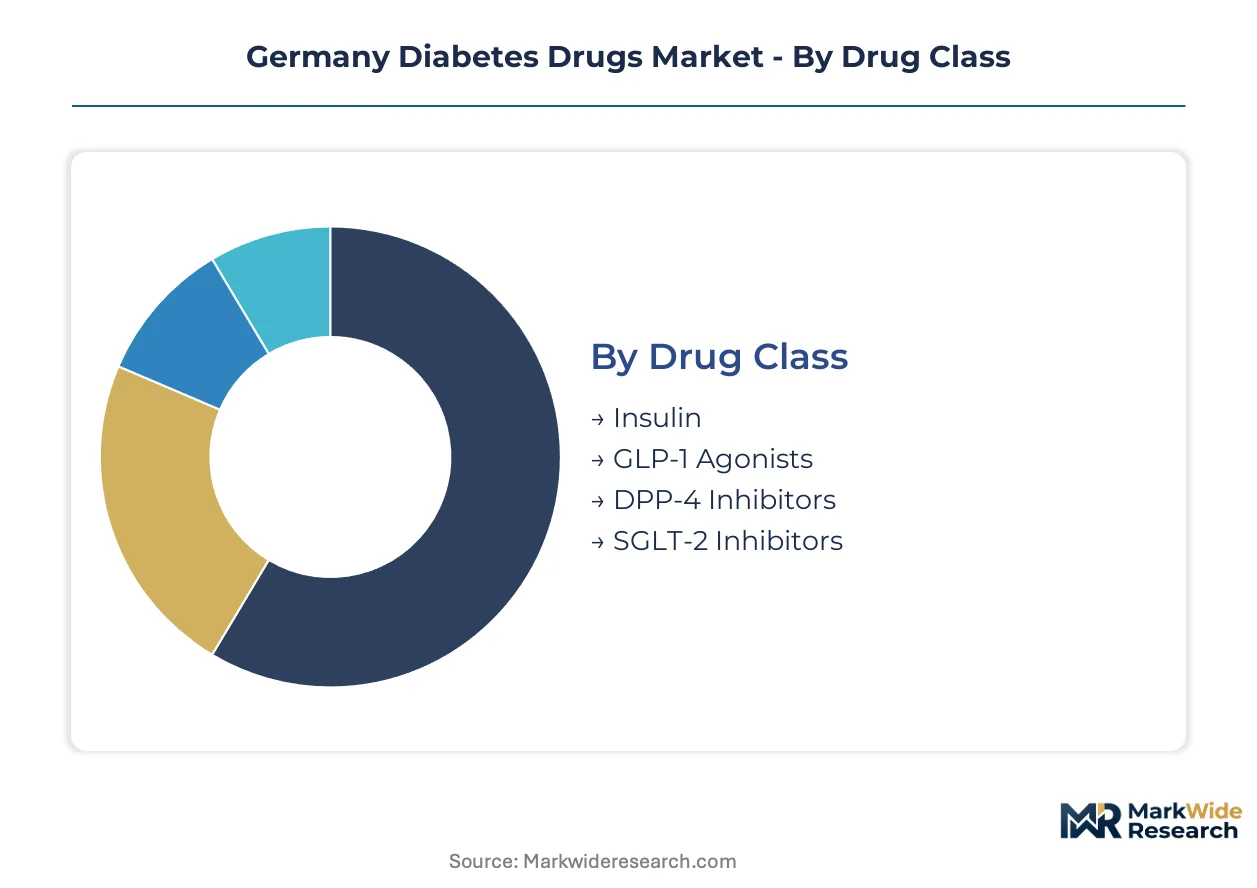
Segmentation in Germany's diabetes therapeutics market reveals distinct margin architectures across molecular classes and delivery modalities. Prescribing patterns diverge sharply between statutory health insurance reimbursement tiers and private insurance formulary access, reshaping commercial prioritization for manufacturers.
Drug Class:
Margin pools concentrate in incretin-based therapies and renal glucose excretion inhibitors, where cardiovascular outcome data command premium positioning in hospital outpatient protocols.
- Insulin:Recombinant human insulin and analog formulations retain foundational volume across Bavaria's specialized diabetes centers. Manufacturing scale advantages at established producers limit biosimilar penetration in hospital formulary slots, though North Rhine-Westphalia's integrated care networks are testing unbranded analog substitution in management contracts.
- GLP-1 Agonists:Subcutaneous and emerging oral peptide formulations drive the steepest expansion trajectory in German prescribing. Endocrinology practices in urban Baden-Württemberg are adopting oral pathways at triple the rate of rural clinics, compressing injection-volume forecasts while expanding addressable populations previously excluded by needle aversion.
- DPP-4 Inhibitors:These gliptin compounds maintain steady reimbursement status as second-line combination therapy, particularly where GLP-1 agonist tolerability issues arise in elderly patient cohorts.
- SGLT-2 Inhibitors:Renal glucose excretion inhibitors have ascended to first-line combination status following cardiovascular and renal outcome data integration into German treatment algorithms.
The dominant share belongs to Insulin, while GLP-1 Agonists are closing the gap fastest.
Administration Route:
Cost tier stratification separates injection-dependent premium therapies from oral convenience formulations targeting adherence-sensitive patient segments.
- Subcutaneous:Injection delivery dominates current volume through pen devices and pump-compatible formulations. Hospital outpatient clinics in North Rhine-Westphalia specify interoperable device standards in procurement bundles, tightening technical documentation requirements under MDR conformity assessment.
- Oral:Tablet formulations are eroding injection burden in demographic segments prioritizing convenience, with peptide bioavailability engineering now achieving thresholds above 70 percent for GLP-1 agonist absorption.
- Intravenous:Hospital-administered insulin infusions concentrate in acute hyperglycemic crisis management and perioperative glycemic control protocols.
- Inhalation:Pulmonary insulin delivery maintains niche positioning limited by dosing precision constraints and lung function screening requirements in German reimbursement guidelines.
Subcutaneous administration retains volume leadership, though Oral delivery is gaining share fastest among newly diagnosed type 2 diabetes patients.
Treatment Stage:
Application focus determines pricing architecture, with chronic disease management contracts bundling monitoring services alongside pharmacotherapy in integrated care networks.
- Type 1 Diabetes:Absolute insulin deficiency mandates lifelong hormonal replacement, with pump therapy and continuous glucose monitoring integration dominating pediatric and adolescent protocols in German specialized centers.
- Type 2 Diabetes:Progressive beta-cell dysfunction drives combination therapy sequencing, where SGLT-2 inhibitors and GLP-1 agonists now displace sulfonylureas in first-line escalation pathways per G-BA treatment guidelines.
- Gestational Diabetes:Pregnancy-specific glycemic targets prioritize insulin safety profiles over oral agents, with tight obstetric monitoring requirements in German maternity care standards.
- Pre-diabetes:Impaired glucose tolerance interventions concentrate on lifestyle modification with metformin prophylaxis in high-risk metabolic syndrome patients, representing an emerging preventive pharmacotherapy segment.
Type 2 Diabetes commands the dominant patient volume, while Pre-diabetes represents the steepest expansion trajectory as screening protocols intensify.
Patient Demographics:
Customer type segmentation aligns formulary decisions with age-specific complication risk profiles and adherence support requirements.
- Adults:Working-age patients aged 18-64 drive combination therapy complexity, with occupational flexibility influencing preference for oral over injectable regimens in German sickness fund populations.
- Adolescents:Transitional care protocols between pediatric and adult endocrinology services create specialized coordination requirements, particularly for type 1 diabetes pump management.
- Elderly:Patients over 65 with multimorbidity and hypoglycemia vulnerability prioritize simplified regimens with low glycemic variability, driving DPP-4 inhibitor retention where GLP-1 agonist gastrointestinal tolerability limits use.
- Pediatric:Childhood-onset type 1 diabetes concentrates in specialized academic medical centers with multidisciplinary care teams, where parental injection training and school-based glucose monitoring integration shape device selection.
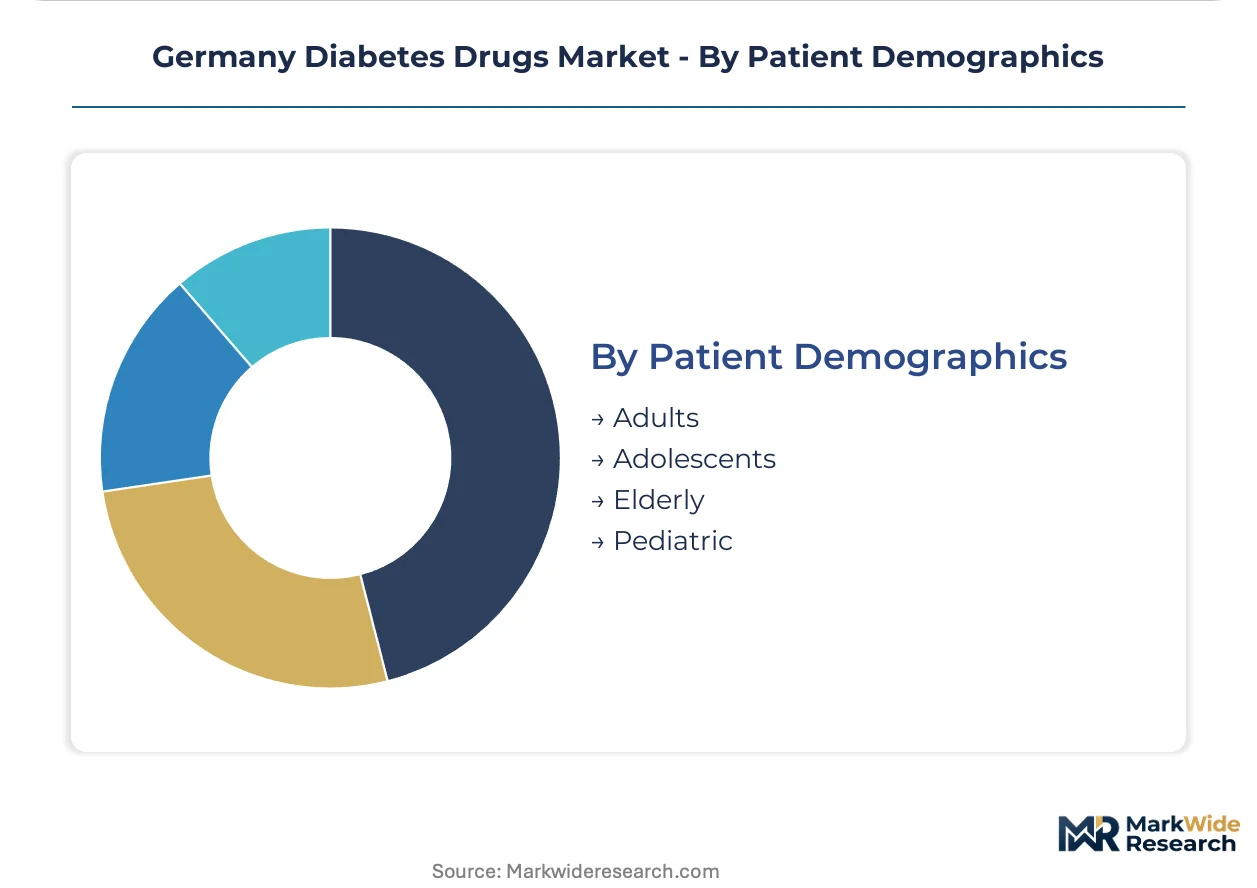
Adults constitute the dominant demographic segment, while Elderly patient volumes are climbing fastest amid Germany's aging population structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports flow into hospital procurement networks across Western and Central Europe, with integrated care contracts in North Rhine-Westphalia setting formulary templates that radiate into neighboring health systems.
North Rhine-Westphalia
AOK Rhineland/Hamburg's bundled diabetes management tenders combine drug provision with continuous glucose monitoring services. The Federal Joint Committee's AMNOG process governs price negotiations for novel agents entering these contracts. Düsseldorf and Cologne anchor integrated care procurement clusters where formulary decisions cascade into regional sickness fund networks.
Bavaria
Specialized diabetes centers in Munich and Erlangen drive insulin pump therapy adoption alongside continuous monitoring integration. Bavarian hospital procurement offices prioritize MDR-compliant device-therapy bundles under tightened Medical Device Regulation standards. Academic medical centers here shape prescribing protocols that diffuse into Austria and Switzerland.
Baden-Württemberg
Regional sickness funds pilot outcomes-based contracting for drug-device combinations, creating testbeds for value-based pricing models. Stuttgart and Mannheim host digital health corridors where oral peptide formulations gain traction three times faster than rural clinics. The state's sickness fund association, AOK Baden-Württemberg, leads procurement innovation for GLP-1 agonist protocols.
Lower Saxony
Hospital outpatient networks in Hanover and Braunschweig concentrate gestational diabetes management with tight obstetric monitoring requirements. The state's Statutory Health Insurance physicians' association negotiates regional formularies that emphasize insulin safety profiles in maternity care pathways. Wolfsburg's employer-sponsored health funds experiment with workplace-based diabetes screening linked to pharmacotherapy provision.
Hesse
Frankfurt's private insurance density supports premium-tier formulary access for novel oral agents. The state's position at Germany's logistics crossroads facilitates distribution of temperature-sensitive biologics to Central European markets. Darmstadt's pharmaceutical manufacturing presence creates local employment clusters that influence regional health policy priorities.
Germany Diabetes Drugs Market Competitive Landscape
Listed leaders compete with private specialists across formulary anchoring and manufacturing scale. The market structures around three concentration tiers: integrated portfolio holders with insulin-GLP-1 combinations, recombinant manufacturing specialists with supply chain depth, and oral delivery platform innovators. Strategic moves center on hospital formulary anchoring through bundled device contracts and accelerated AMNOG evidence generation for combination therapies.
Among integrated portfolio holders, Novo Nordisk and Sanofi occupy positions exemplifying the formulary-anchoring archetype, while Eli Lilly and Company represents the R&D-intensive oral delivery tier. These three entities illustrate the competitive spectrum from manufacturing-scale defense to peptide bioavailability innovation. Each anchors distinct geographic prescribing patterns across German hospital networks and integrated care contracts.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Merck |
| Boehringer Ingelheim |
| Takeda |
| Pfizer |
| Janssen Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Ninety-day cold-chain inventory buffers at German hospital pharmacies tether pricing power to biologics manufacturing concentration in Denmark and France. AMNOG price caps compress margins for novel agents during their first reimbursement year, while integrated care networks in North Rhine-Westphalia exploit bundled procurement to extract volume discounts from insulin and GLP-1 suppliers.
Pricing Analysis
Next-generation oral peptide formulations command 40-60% premiums over subcutaneous GLP-1 agonists, while prior-generation recombinant human insulin faces commoditization pressure from unbranded analog substitution in regional sickness fund contracts. Three-tier pricing structure across premium biologics, standard analogs, and economy human insulin segments stratifies the market, with cardiovascular outcome data driving premium positioning for SGLT-2 inhibitors and GLP-1 agonists. Cost compression in the insulin tier intensifies because North Rhine-Westphalia's integrated care networks are piloting biosimilar substitution protocols. Statutory health insurance funds exhibit highest price sensitivity, while private insurance patients in Hesse show lowest sensitivity to out-of-pocket differentials for novel oral agents.
Supply Chain Analysis
Recombinant protein fermentation capacity concentration in Denmark, France, and Germany's own Rhineland chemical corridor anchors biologics supply security for German diabetes therapeutics. Active pharmaceutical ingredient production draws from Irish peptide synthesis hubs, Swiss fine chemical specialists, and Indian fermentation capacity for older insulin generations. Single-source vulnerability concentrates in GLP-1 agonist fill-finish operations, where Novo Nordisk's Danish facilities supply the majority of German hospital demand. Distribution runs through temperature-controlled logistics networks anchored at Frankfurt's pharmaceutical distribution hub, with regional depots in Munich, Hamburg, and Düsseldorf serving hospital outpatient clinics within 24-hour delivery windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's diabetes drugs market reflects accelerating buyer power consolidation through AOK Rhineland/Hamburg's bundled tender structures, which now cover 8 million lives under unified procurement protocols. Regional sickness fund associations are fragmenting commercialization strategies as multistate formulary variability forces manufacturers to maintain parallel field force deployments.
For Market Incumbents: Secure hospital formulary anchoring in Bavaria's specialized diabetes centers through MDR-compliant device-therapy bundles that satisfy tightened Medical Device Regulation conformity requirements. Defend against oral peptide disruption by accelerating real-world evidence generation for subcutaneous GLP-1 agonists within AMNOG's twelve-month price negotiation window. Backward integration into continuous glucose monitoring sensor manufacturing reduces dependency on separate device suppliers in North Rhine-Westphalia's unbundled procurement environment.
For New Entrants and Emerging Players: Rural clinic service gaps in oral peptide formulation adoption present the most penetrable entry vector, with endocrinology practices outside Baden-Württemberg's digital health corridors showing threefold lower adoption rates than urban centers. Target pre-diabetes pharmacotherapy prophylaxis as the steepest expansion trajectory, where intensified screening protocols are creating first-mover opportunities for metformin combination therapies. Partner with regional sickness funds in Lower Saxony on workplace-based diabetes screening programs to establish downstream pharmacotherapy relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap European biotechs with late-stage oral peptide delivery platforms but insufficient capital for parallel EMA-G-BA evidentiary requirements. Position portfolios for 5-10 year value-based contracting evolution as outcomes-based drug-device combinations mature from Baden-Württemberg pilots to national reimbursement standards. Monitor Federal Joint Committee AMNOG assessment timelines as the critical inflection signal for novel agent market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| AMNOG Evidence Generation Acceleration | Parallel real-world data collection during price negotiation compresses time-to-reimbursement for GLP-1 agonists. |
| MDR-Compliant Device Bundling | Unified drug-sensor regulatory dossiers create first-mover advantages in Bavarian hospital procurement tenders. |
| Oral Peptide Bioavailability Investment | Peptide engineering achieving 70% absorption thresholds expands addressable populations beyond injection-tolerant patients. |
| Regional Sickness Fund Partnership | Direct contracting with AOK Baden-Württemberg pilots value-based pricing models ahead of national rollout. |
| Continuous Glucose Monitoring Integration | Interoperable data streams with hospital EHR architectures satisfy North Rhine-Westphalia's bundled care requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives at leading manufacturers, regulatory affairs specialists navigating EMA-G-BA parallel assessments, hospital formulary directors in Bavaria and North Rhine-Westphalia, and payer access specialists at regional sickness fund associations. Secondary validation drew from EMA centralized marketing authorization submissions, Federal Joint Committee benefit assessment dossiers, German hospital procurement databases, and InGef claims data on diabetes treatment patterns. Bottom-up patient volume modeling and top-down pharmaceutical sales triangulation were cross-referenced against statutory health insurance reimbursement statistics.
Across the analysis window, projections integrated drug class lifecycle dynamics, AMNOG price cap trajectories, and regional care network expansion patterns. Segmentation dimensions encompassed treatment stage, administration route, patient demographics, and state-level regulatory cluster variations. CAGRs were derived from multivariate regression against historical reimbursement volumes, with forecast inputs including G-BA treatment guideline revision schedules and integrated care contract penetration rates in North Rhine-Westphalia and Baden-Württemberg.
Forecasts assume regulatory continuity in Germany's AMNOG framework and EU Medical Device Regulation enforcement; material policy shifts in data exclusivity periods or MDR conformity timelines would require re-modeling. Specific risk factors include EMA-G-BA evidentiary divergence extending market access delays, biosimilar substitution acceleration in statutory health insurance tenders, and digital therapeutic reimbursement pathway revisions. Practitioners should keep alternative scenarios live as Federal Joint Committee assessment criteria and regional sickness fund procurement structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Germany Pharmaceuticals Market