
 Global Aspiration and Biopsy Needles Market | 2026-2036
Global Aspiration and Biopsy Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aspiration and Biopsy Needles Market Intelligence
Chinese stainless steel producers is pivoting toward medical-grade needle tubing capacity to serve downstream device manufacturers. Merit Medical Systems anchors its competitive position through vertical integration in Salt Lake City manufacturing. Hologic, Inc. specializes in breast health sampling systems and dominates the vacuum-assisted biopsy segment. Becton, Dickinson and Company extends its global reach through pathology lab direct sales channels.
Aspiration and biopsy needles are hollow, beveled-tip instruments manufactured from 304L or 316L stainless steel tubing with outer diameters ranging from 21 gauge to 14 gauge, designed to extract cellular material or tissue cores for histopathological examination and disease diagnosis. Fine needle aspiration products occupy the highest procedural volume tier due to their use in thyroid and lymph node assessment, while vacuum-assisted biopsy systems command premium positioning in breast tissue sampling workflows. Core needle biopsy competes across pulmonary and liver applications where larger specimen volumes improve diagnostic yield.
FDA 510(k) clearance and EMA MDR compliance create dual-track regulatory burdens for manufacturers seeking access to US and European healthcare systems, while Japan's PMDA shapes market entry timelines through localized clinical data requirements. China's NMPA has tightened sterile device registration standards, redirecting supplier investment toward in-country testing infrastructure. Stakeholders must monitor evolving reimbursement coding for image-guided procedures across Medicare, NHS England, and Japan's MHLW fee schedules.
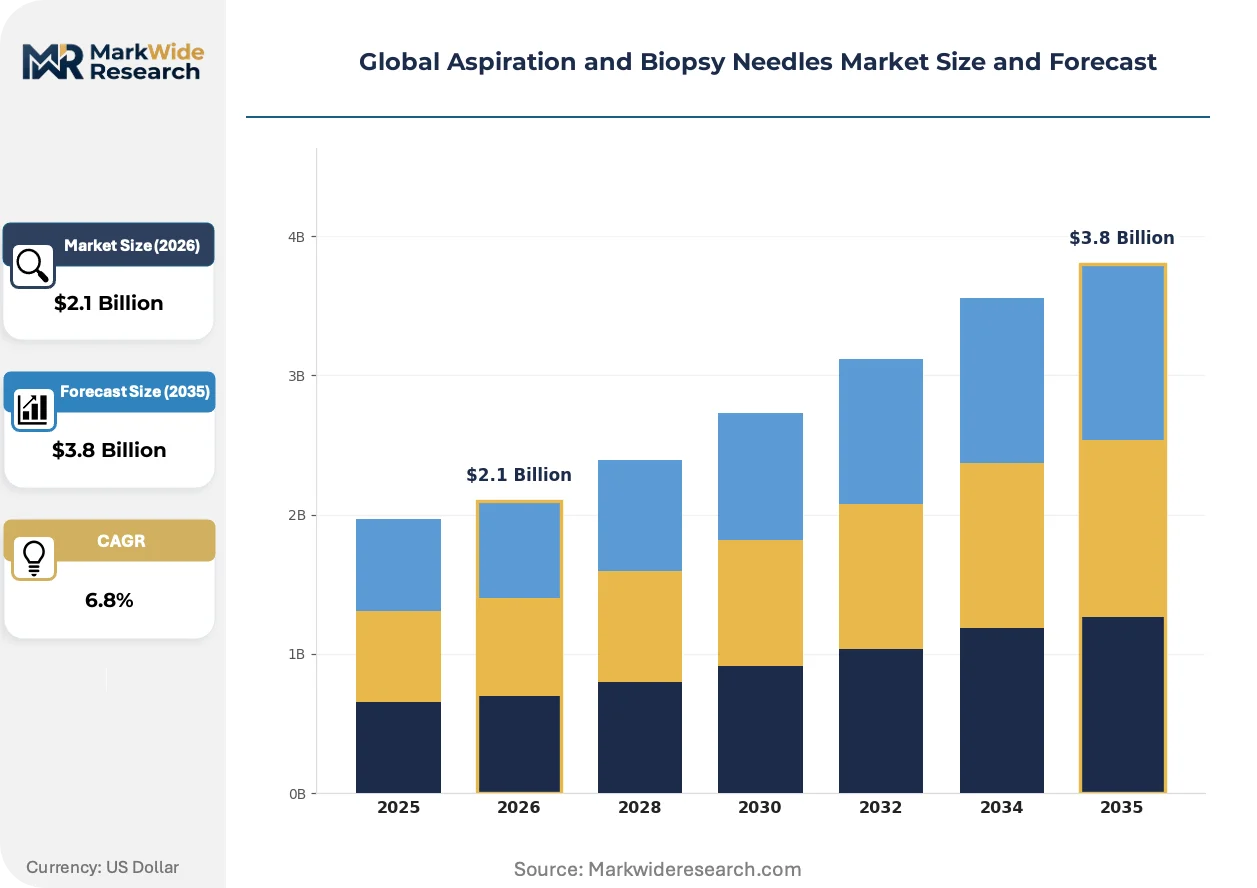
Market Dynamics
Oncology screening program expansion across hospital systems is concentrating procedural demand for precision sampling instruments, while regulatory divergence between FDA 510(k) and EMA MDR pathways fragments commercialization timelines for multi-market manufacturers.
Growth Catalysts
- Japan PMDA pathway streamlining:Localized clinical data requirements for Class II devices are compressing market entry timelines for vacuum-assisted biopsy systems in Tokyo and Osaka hospital networks.
- Thyroid nodule assessment protocols:Fine needle aspiration procedural volume is accelerating across endocrinology departments as first-line diagnostic standards tighten.
- 304L stainless steel tubing capacity:Chinese metallurgical producers are redirecting cold-drawing lines toward medical-grade specifications, expanding downstream supply security for device manufacturers.
Market Restraints
- Nickel price volatility:316L alloy feedstock costs fluctuate with Indonesian and Philippine ore export policies, compressing margin buffers for tubing suppliers.
- EMA MDR technical documentation:Expanded clinical evidence requirements for legacy biopsy needle portfolios are extending recertification cycles and freezing product line extensions.
- Reusable needle sterilization:Central sterile processing departments in budget-constrained facilities are delaying single-use conversion, constraining premium segment velocity.
Strategic Opportunities
- Brazil ANVISA harmonization:Mercosur alignment with ISO 13485 quality standards is reducing duplicative auditing burdens for manufacturers entering São Paulo and Rio de Janeiro procurement channels.
- Liquid biopsy convergence:Integration of needle-based tissue acquisition with circulating tumor DNA workflows is opening hybrid diagnostic service lines in academic medical centers.
- Direct pathology laboratory contracting:Bypassing distributor markups through Becton Dickinson-style channel strategies is capturing margin in high-volume US health systems.
Industry Challenges
- Electropolishing technician scarcity:Surface finish specifications for 21-gauge aspiration products require specialized training pipelines that regional manufacturing clusters struggle to populate.
- Legacy ERP integration:FDA 21 CFR Part 11 electronic record mandates are forcing mid-tier manufacturers to replace paper-based device history records with validated software systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aspiration and Biopsy Needles Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fine Needle Aspiration, Core Needle Biopsy, Vacuum-Assisted Biopsy, Endoscopic Ultrasound-Guided, Stereotactic Biopsy, Others Application: Oncology Diagnosis, Pulmonary Sampling, Liver Biopsy, Thyroid Analysis, Breast Tissue Sampling, Urology Testing End User: Pathology Labs, Diagnostic Clinics, Specialty Hospitals, Research Institutions, Ambulatory Surgical Centers, Radiology Centers Distribution Channel: Direct Sales, Medical Device Distributors, Online Medical Portals, Government Healthcare Programs, Private Clinics Supply, Group Purchasing Organizations |
| Companies Covered | Hologic, Inc., Merit Medical Systems, Becton, Dickinson and Company, Olympus Corporation, Argon Medical Devices, Inc., Medtronic, Cook Group Incorporated, CONMED Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aspiration and Biopsy Needles Market Strategic Shifts & Innovations
Active unification of imaging modalities with real-time needle guidance is compressing the gap between tissue acquisition and pathological confirmation, reshaping how interventional radiologists and surgeons coordinate diagnostic workflows.
Real-time ultrasound fusion with electromagnetic tracking is unifying previously separate imaging and navigation steps into single-procedure workflows. Interventional radiology departments at Cleveland Clinic and Johns Hopkins are standardizing these platforms for pulmonary and hepatic lesion access. The technology is unifying hardware procurement decisions, forcing device manufacturers to bundle needles with tracking sensors rather than sell standalone instruments.
EMA MDR Article 10 post-market surveillance requirements are mandating systematic implant card and patient register systems for all sterile invasive devices. German notified bodies are rejecting legacy technical files lacking clinical follow-up protocols. Breast biopsy needle portfolios face the steepest compliance burden, as manufacturers must reconstruct decade-old patient outcome data or withdraw SKUs from EU markets.
Hospital value analysis committees are consolidating vendor contracts for image-guided biopsy procedures into single-source agreements with mandatory volume commitments. US integrated delivery networks are replacing fragmented specialty purchasing with centralized interventional oncology contracts. This concentration is most visible in Texas and Florida health systems, where HCA and Tenet facilities are standardizing on two-needle vendor panels to leverage aggregate spend.
Global Aspiration and Biopsy Needles Market Segmentation
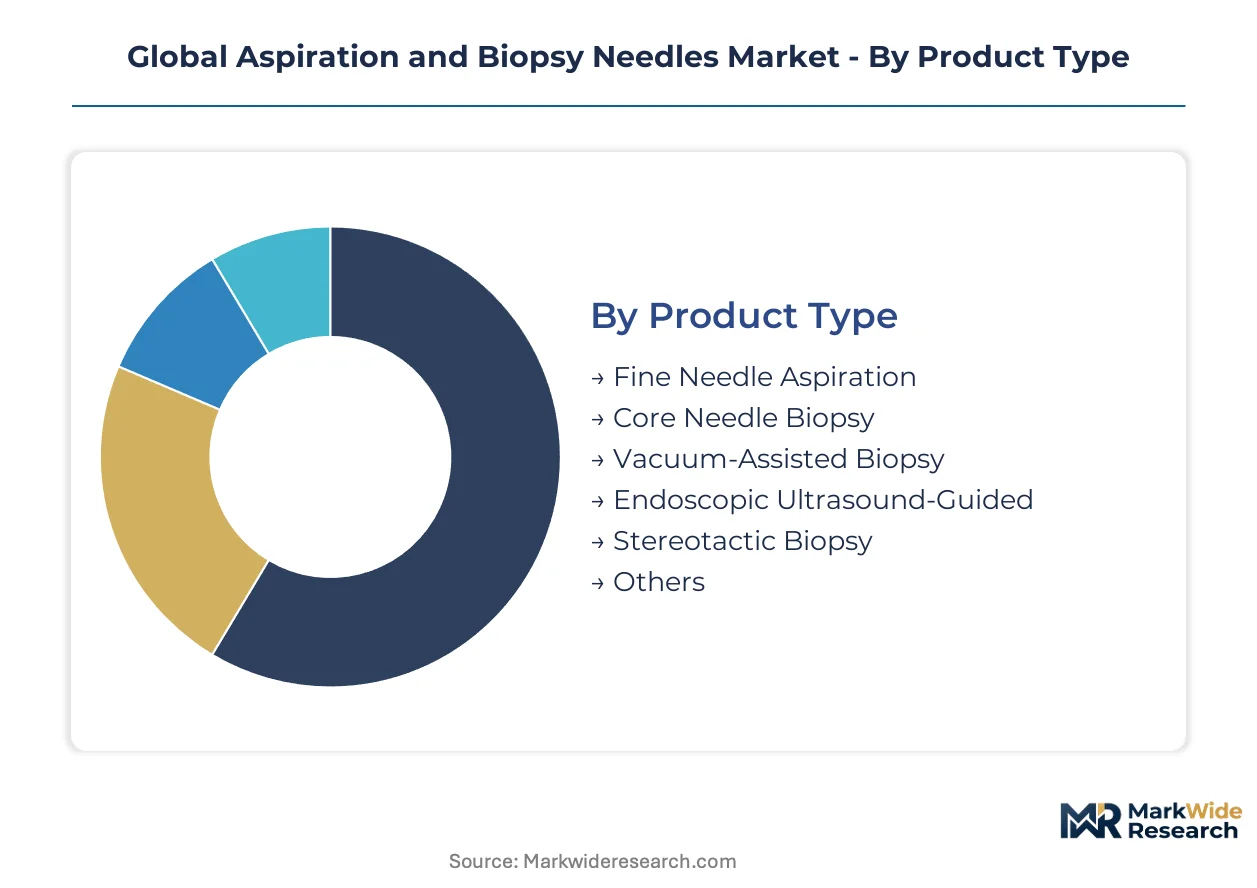
Segmentation in aspiration and biopsy needles reflects divergent technical requirements across tissue types and procurement economics. Product architecture, clinical setting, and channel economics each create distinct competitive arenas with separate margin profiles and regulatory pathways.
Product Type:
Fine needle aspiration and core needle biopsy systems operate as standalone instruments in outpatient settings, while vacuum-assisted and stereotactic platforms embed into integrated imaging workflows requiring capital equipment partnerships.
- Fine Needle Aspiration:21- to 25-gauge hollow needles manufactured from 304L stainless steel tubing extract cellular material for cytological examination. Thyroid and lymph node assessment in US endocrinology departments drives procedural volume as first-line diagnostic protocols tighten.
- Vacuum-Assisted Biopsy:Multi-lumen cannula systems with integrated vacuum chambers harvest contiguous tissue cores through single insertion points. Breast imaging centers in Germany and Japan specify these platforms for lesion characterization under stereotactic or ultrasound guidance.
- Core Needle Biopsy:Spring-loaded or automated cutting mechanisms capture 14- to 18-gauge specimens for histopathological analysis. Pulmonary and hepatic applications dominate procurement decisions at academic medical centers.
- Endoscopic Ultrasound-Guided:Curved linear array echoendoscopes with dedicated 19- or 22-gauge needles access mediastinal and pancreatic lesions. Gastroenterology departments at Cleveland Clinic and Johns Hopkins standardize these for submucosal sampling.
- Stereotactic Biopsy:Computer-guided coordinate systems align needles with mammographic targets for non-palpable breast lesions. US integrated delivery networks bundle these with Hologic or BD vacuum-assisted platforms.
- Others:Bone marrow aspiration needles and bone biopsy systems serve hematology and orthopedic oncology workflows with specialized tip geometries.
Fine needle aspiration leads volumes today; vacuum-assisted biopsy is gaining share fastest.
Application:
Cost tier stratification separates high-reimbursement oncology sampling from routine diagnostic procedures, with breast and thyroid applications commanding premium positioning over pulmonary and urology testing.
- Oncology Diagnosis:Multi-site tissue acquisition for staging and molecular profiling demands precision-engineered needles with consistent specimen quality. Medicare reimbursement rates for image-guided procedures in US hospital outpatient departments sustain premium pricing.
- Breast Tissue Sampling:Vacuum-assisted and core needle systems dominate screening-detected lesion workups. Japan's MHLW fee schedules and NHS England tariff systems concentrate procurement authority in national screening program administrators.
- Thyroid Analysis:Ultrasound-guided fine needle aspiration represents the standard of care for nodule risk stratification. Endocrinology clinics in Germany and Japan generate recurrent procedural demand through repeat surveillance protocols.
- Pulmonary Sampling:Electromagnetic navigation bronchoscopy with transbronchial needles accesses peripheral lung lesions. Interventional pulmonology departments at Mayo Clinic and Massachusetts General Hospital drive technology adoption.
- Liver Biopsy:Percutaneous and transjugular approaches utilize coaxial needle systems for parenchymal sampling. Hepatology centers managing non-alcoholic steatohepatitis trials generate volume for 16-gauge core instruments.
- Urology Testing:Prostate and renal mass sampling employs 18-gauge biopsy guns with automated firing mechanisms. Ambulatory surgical centers in Texas and Florida health systems consolidate these into urology service line contracts.
Oncology diagnosis anchors revenue concentration; thyroid analysis is expanding most quickly.
End User:
Customer type fragmentation creates divergent purchasing behaviors, with pathology laboratories prioritizing specimen quality consistency while ambulatory centers minimize per-procedure supply costs.
- Pathology Labs:Direct contracting relationships with manufacturers like Becton Dickinson emphasize specimen adequacy rates and standardized processing protocols. US health system laboratory consolidation is compressing vendor panels.
- Specialty Hospitals:Cancer centers and women's hospitals specify vacuum-assisted biopsy platforms with dedicated service contracts. MD Anderson and Memorial Sloan Kettering negotiate multi-year needle supply agreements.
- Diagnostic Clinics:Independent imaging centers prioritize disposable cost per procedure over capital equipment integration. Group purchasing organization participation determines supplier access.
- Ambulatory Surgical Centers:Medicare ASC payment rates constrain supply budgets, favoring standard core needle biopsy over vacuum-assisted systems. Texas and Florida certificate-of-need environments concentrate volume in multi-site operators.
- Radiology Centers:Free-standing imaging facilities require needles compatible with diverse ultrasound and mammography platforms. Equipment manufacturer partnerships influence needle procurement decisions.
- Research Institutions:Academic medical centers source specialized needles for clinical trial protocols with custom specifications. NIH-funded oncology trials drive demand for molecular preservation features.
Pathology labs lead procurement volume today; ambulatory surgical centers are climbing the fastest.
Distribution Channel:
Supply concentration in direct sales and group purchasing organizations is displacing fragmented distributor networks, with manufacturer channel strategy determining margin capture in high-volume health systems.
- Direct Sales:Becton Dickinson and Hologic field organizations contract directly with US integrated delivery networks, bypassing distributor markups. Pathology laboratory relationships require specialized clinical support capabilities.
- Group Purchasing Organizations:Vizient and Premier contracts aggregate demand across hundreds of hospital systems, standardizing on two-needle vendor panels. Compliance penalties enforce volume commitments.
- Medical Device Distributors:Regional distributors serve mid-tier hospitals and international markets lacking direct sales infrastructure. Brazilian and Mexican procurement channels rely on local distributor relationships.
- Government Healthcare Programs:NHS Supply Chain and Japan's MHLW centralized purchasing dictate specification standards and price ceilings. Tender compliance requires dedicated regulatory documentation.
- Online Medical Portals:E-commerce platforms serve small clinics and veterinary applications with standard gauge needles. Price transparency pressures distributor margins.
- Private Clinics Supply:Specialty distributors cater to dermatology and plastic surgery practices with aesthetic biopsy applications. Lower procedural volumes limit manufacturer direct engagement.
Direct sales leads channel revenue today; group purchasing organizations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan concentrate procedural demand through dense screening networks, while the United States anchors premium pricing through Medicare reimbursement structures. Brazil and China represent contrasting expansion trajectories shaped by regulatory harmonization and domestic manufacturing investment.
United States
Medicare outpatient prospective payment systems sustain premium pricing for vacuum-assisted biopsy procedures at academic medical centers. FDA 510(k) clearance pathways compress commercialization timelines for manufacturers targeting integrated delivery networks. Texas and Florida health systems concentrate procurement volume through HCA and Tenet multi-site standardization programs.
Germany
Breast cancer screening program density drives vacuum-assisted biopsy system demand across university hospital networks. EMA MDR technical documentation requirements extend recertification cycles for legacy needle portfolios. Notified bodies in Munich and Frankfurt enforce Article 10 post-market surveillance mandates for sterile invasive devices.
Japan
Thyroid nodule surveillance protocols generate recurrent fine needle aspiration volume through endocrinology departments. PMDA localized clinical data requirements shape market entry timelines for Class II devices in Tokyo and Osaka hospital networks. MHLW fee schedules concentrate procurement authority in national screening program administrators.
Brazil
Mercosur alignment with ISO 13485 quality standards reduces duplicative auditing burdens for manufacturers entering São Paulo and Rio de Janeiro procurement channels. ANVISA harmonization accelerates registration pathways for vacuum-assisted biopsy platforms. Regional distributors anchor supply relationships with mid-tier hospitals lacking direct sales infrastructure.
China
Domestic stainless steel producers redirect cold-drawing capacity toward medical-grade tubing specifications for downstream device manufacturers. NMPA tightened sterile device registration standards redirect supplier investment toward in-country testing infrastructure. Shanghai and Beijing manufacturing clusters expand electropolishing technician training pipelines for surface finish specifications.
Global Aspiration and Biopsy Needles Market Key Industry Players
United States producers anchor one tier; Japanese and German specialists hold differentiated positions through imaging integration partnerships. Market structure concentrates around three strategic archetypes: vertically integrated manufacturers with captive tubing supply, imaging equipment bundlers with needle-sensor integration, and pure-play disposable specialists with pathology laboratory direct sales. Dominant competitive moves include backward integration into stainless steel tubing production and strategic partnerships with ultrasound platform manufacturers for electromagnetic tracking compatibility.
Among US-based manufacturers, Hologic, Inc. and Becton, Dickinson and Company occupy positions exemplifying the imaging-bundler and direct-sales archetypes respectively. Merit Medical Systems represents vertical integration strategy through Salt Lake City manufacturing concentration. These three entities anchor competitive positioning across distinct channel strategies rather than converging on identical procurement pathways.
| Leading Market Players |
|---|
| Hologic, Inc. |
| Merit Medical Systems |
| Becton, Dickinson and Company |
| Olympus Corporation |
| Argon Medical Devices, Inc. |
| Medtronic |
| Cook Group Incorporated |
| CONMED Corporation |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Electropolishing technician scarcity in Chinese manufacturing clusters widens labor-cost differentials between premium 21-gauge aspiration products and economy-grade alternatives, compressing mid-tier margin buffers as hospitals consolidate procurement.
Pricing Analysis
Capacity additions in Chinese cold-drawing facilities are reshaping price floors for 304L and 316L stainless steel tubing feedstock. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared vacuum-assisted systems from CE-marked core needles and unbranded disposable alternatives. Cost compression in standard-tier products is intensifying because Indonesian nickel ore export policies feed 316L alloy volatility. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare ASC reimbursement constraints, while academic medical centers prioritize specimen quality over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Salt Lake City, Munich, and Shanghai anchor hub-and-spoke patterns for sterile needle inventory. Manufacturing concentrates in the United States, Germany, and China, with downstream device assembly drawing from Japanese precision-cutting tool suppliers and Italian electropolishing equipment providers. Raw material dependencies rest on Indonesian and Philippine nickel ore, Chinese stainless steel billets, and German specialty coatings. Single-source vulnerability around 21-gauge thin-wall tubing creates chokepoint exposure. Distribution runs through direct sales forces for integrated delivery networks, with group purchasing organizations aggregating mid-tier hospital demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Aspiration and Biopsy Needles Market compounds steadily as oncology screening program density tightens first-line diagnostic protocols across hospital systems.
For Market Incumbents: Cement backward integration into medical-grade tubing production to defend against Chinese metallurgical entrants capturing downstream margin. Lock in multi-year service contracts with MD Anderson and Memorial Sloan Kettering before EMA MDR recertification cycles freeze legacy SKU extensions. Priority rests on securing 304L stainless steel supply commitments from redirected Chinese cold-drawing capacity. For New Entrants and Emerging Players: ANVISA harmonization with ISO 13485 in Brazil opens a window for vacuum-assisted biopsy platforms entering São Paulo and Rio de Janeiro procurement channels. Target mid-tier hospitals in Mercosur markets lacking direct sales infrastructure from established players. Deploy regional distributor partnerships as the primary go-to-market angle, bypassing capital requirements for field sales organizations. For Investors and Strategic Acquirers: Imaging equipment manufacturers are the most active acquirer in this space, seeking needle-sensor integration capabilities for electromagnetic tracking platforms. Five-to-ten year viability hinges on hybrid diagnostic service lines converging tissue acquisition with liquid biopsy workflows. Watch for FDA 510(k) clearance acceleration for real-time ultrasound fusion systems as the inflection signal indicating platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates US commercialization timelines for vacuum-assisted biopsy systems targeting integrated delivery networks. |
| CE Marking Pathway | EMA MDR Article 10 compliance enables EU market retention for breast biopsy needle portfolios. |
| Hospital System Partnership | Direct pathology laboratory contracting with Becton Dickinson-style strategies captures margin in high-volume US health systems. |
| Backward Integration | Captive 304L stainless steel tubing supply insulates Merit Medical Systems from nickel price volatility. |
| Reimbursement Strategy | Medicare outpatient prospective payment system alignment sustains premium pricing for image-guided procedures. |
Research Approach
Coverage spans the United States, Germany, Japan, Brazil, and China, with primary inputs from each market. Interviews with interventional radiologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and PMDA Class II device registrations. Bottom-up procedural volume estimates and top-down manufacturer revenue analysis triangulate market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, application, end user, and distribution channel, with regional regulatory cluster as the cross-cutting analytical layer. CAGRs derive from fitted growth curves applied to procedural volume trajectories. Forecast inputs incorporate thyroid nodule surveillance protocol adoption rates and EMA MDR recertification timeline assumptions.
Revisions become necessary when nickel ore export policy shifts, EMA notified body capacity constraints, or liquid biopsy substitution thresholds materialize. Forecasts reflect documented assumptions about screening program expansion and reimbursement stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market