
 Phototherapy Device Market | 2026-2036
Phototherapy Device Market Size, Share, and Industry Trends Forecast 2026-2036
Phototherapy Device Market Intelligence
The distinction between broad-spectrum fluorescent and targeted narrow-band devices is collapsing as LED technology becomes the standard. This shift favors manufacturers with strong R&D in solid-state lighting and clinical validation. GE Healthcare leverages its extensive hospital network to drive adoption in neonatal care. Natus Medical specializes in solutions for neonatal jaundice management, while Herbert Waldmann dominates the European clinical dermatology segment with its high-intensity UV systems.
A phototherapy device administers controlled doses of non-ionizing light from specific wavelengths of the electromagnetic spectrum, such as UVA, UVB, or blue light. These systems are designed to treat various medical conditions by inducing biological reactions in target tissues. Within applications, psoriasis treatment and neonatal jaundice management constitute the largest segments due to high prevalence rates and established clinical protocols. Hospitals and specialized dermatology clinics remain the primary end-user channels, capturing the majority of device value.
Market access hinges on compliance with stringent medical device regulations. Manufacturers must secure approvals such as the FDA's 510(k) clearance in the United States, CE marking under the MDR in Europe, and NMPA registration in China. These frameworks mandate rigorous clinical data and safety testing. The key decision for manufacturers now is how to balance investment in clinical-grade devices versus the expanding, less-regulated home-use market.
Market Dynamics
The market's structure is fundamentally altered by the widespread adoption of LED-based systems. This technological shift, combined with stringent demands for clinical validation from regulators like the FDA and NMPA, sets new benchmarks for device efficacy and safety.
Growth Catalysts
- LED Efficiency Gains:Advances in solid-state lighting allow for more precise wavelength targeting and energy efficiency. This improves treatment outcomes for conditions like psoriasis and reduces operational costs for dermatology clinics.
- Rising Prevalence in China:Increased incidence of dermatological conditions and neonatal jaundice in China, coupled with expanding public healthcare infrastructure, drives significant volume demand for both clinical and neonatal phototherapy units.
- Clinical Protocol Standardization:The establishment of clear clinical guidelines for psoriasis and neonatal jaundice management by health authorities encourages hospitals to invest in compliant, state-of-the-art phototherapy systems to ensure standardized care.
Market Restraints
- High Initial Capital Outlay:The significant cost of clinical-grade, high-intensity UV and LED systems presents a substantial barrier for smaller clinics and healthcare facilities in emerging economies, limiting market penetration.
- Complex Regulatory Pathways:Navigating the divergent requirements of the FDA's 510(k) process, Europe's MDR, and China's NMPA registration creates long and costly development cycles, slowing new product introductions.
- Competition from Systemic Drugs:The availability of effective biologic drugs and other systemic treatments for severe psoriasis presents a clinical alternative that can reduce patient volume for phototherapy in some cases.
Strategic Opportunities
- Home-Use Market Expansion:Developing and marketing FDA-cleared or CE-marked phototherapy devices for at-home management of chronic conditions like psoriasis opens a new revenue stream directly targeting consumers.
- New Dermatological Applications:Research into the efficacy of specific light wavelengths for treating conditions beyond psoriasis, such as vitiligo and atopic dermatitis, creates opportunities for specialized device development.
- Integration with Digital Health:Connecting phototherapy devices to patient management platforms allows for remote monitoring, personalized dosimetry, and data collection, offering a value-added service for clinicians and patients.
Industry Challenges
- Clinical Data Generation:The requirement for extensive and costly clinical trials to support efficacy claims and secure regulatory approvals under frameworks like the EU's MDR is a major operational hurdle for manufacturers.
- Specialized R&D Talent:A scarcity of engineers with dual expertise in both medical device design and advanced solid-state lighting physics complicates product innovation and development timelines.
- Navigating Reimbursement:Securing favorable reimbursement codes and rates from public and private payers in different countries is a complex challenge that directly impacts hospital purchasing decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phototherapy Device Market |
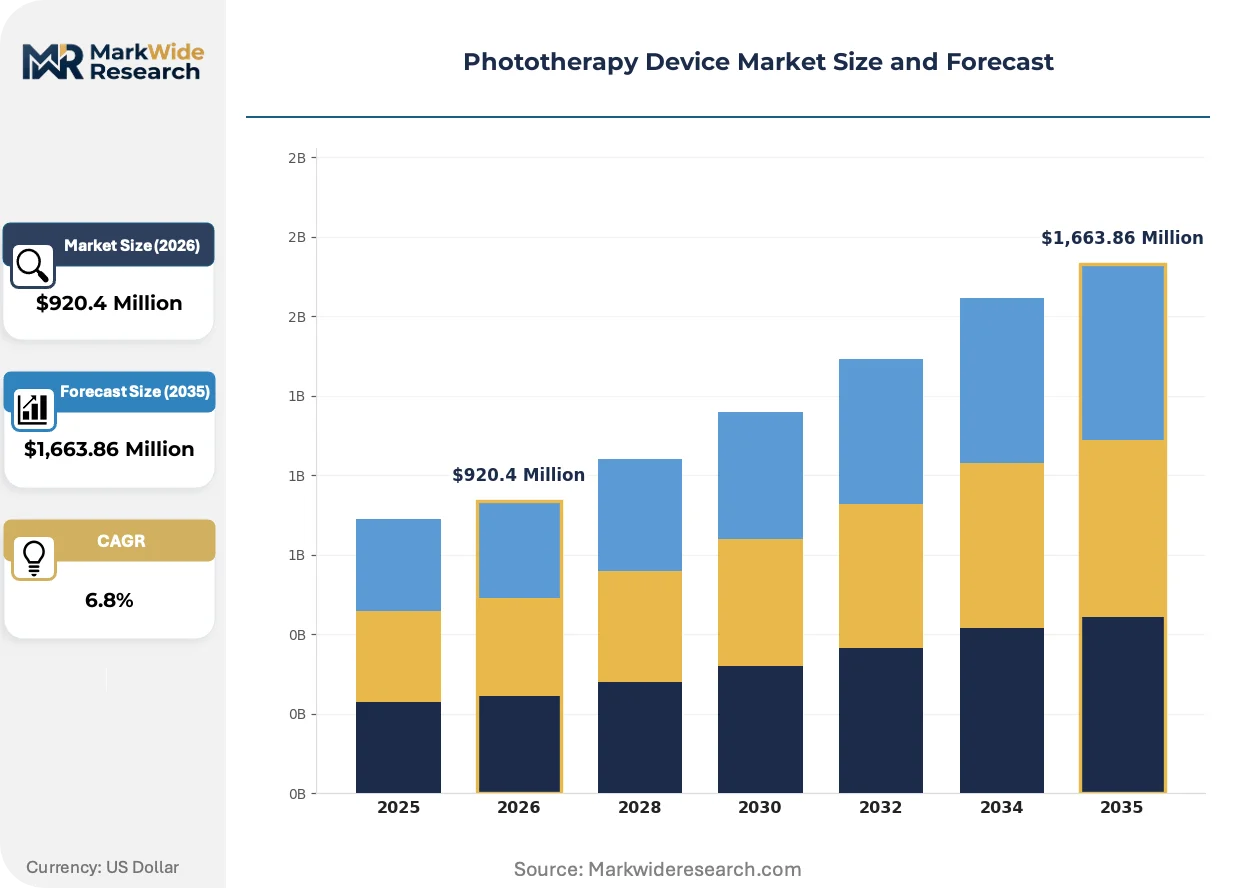
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $1,663.86 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Phototherapy, Fluorescent Lamp, Laser Therapy, Ultraviolet Therapy, Broadband Light Application: Neonatal Jaundice, Psoriasis Treatment, Seasonal Affective Disorder, Acne Management, Atopic Dermatitis End User: Hospitals, Dermatology Clinics, Pediatric Centers, Cosmetic Clinics, Therapy Centers Deployment: In-Clinic Devices, Home-Based Units, Portable Devices, Wearable Technology |
| Companies Covered | GE Healthcare, Atom Medical, Draeger, Herbert Waldmann, Natus Medical, Daavlin, Beurer, National Biological, Solarc Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phototherapy Device Market Strategic Shifts & Innovations
The evolution of phototherapy hardware is now inextricably linked to software and data analytics. This convergence is creating intelligent systems capable of delivering personalized, dose-controlled treatments, moving beyond one-size-fits-all clinical protocols.
Wearable phototherapy patches and handheld units leverage flexible OLEDs and micro-LED arrays to deliver targeted light therapy directly to affected skin areas. Dermatologists and patients are adopting these for localized psoriasis or vitiligo treatment, supplementing in-clinic sessions. This trend is miniaturizing the form factor of treatment delivery, shifting care from large clinical booths toward portable, patient-centric devices.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on all medical devices, including phototherapy systems. This is forcing manufacturers to invest more heavily in long-term clinical follow-up and robust quality management systems. Devices intended for high-risk applications or home use are most affected, requiring more extensive data to achieve and maintain CE marking.
A clear shift is occurring from standalone device purchases to procurement of integrated treatment room solutions. Hospitals and large dermatology clinics are increasingly sourcing complete packages that include the phototherapy unit, patient management software, and service contracts from a single vendor. This trend is most visible in the United States and Germany, where large hospital networks seek to standardize equipment and streamline purchasing.
Phototherapy Device Market Segmentation
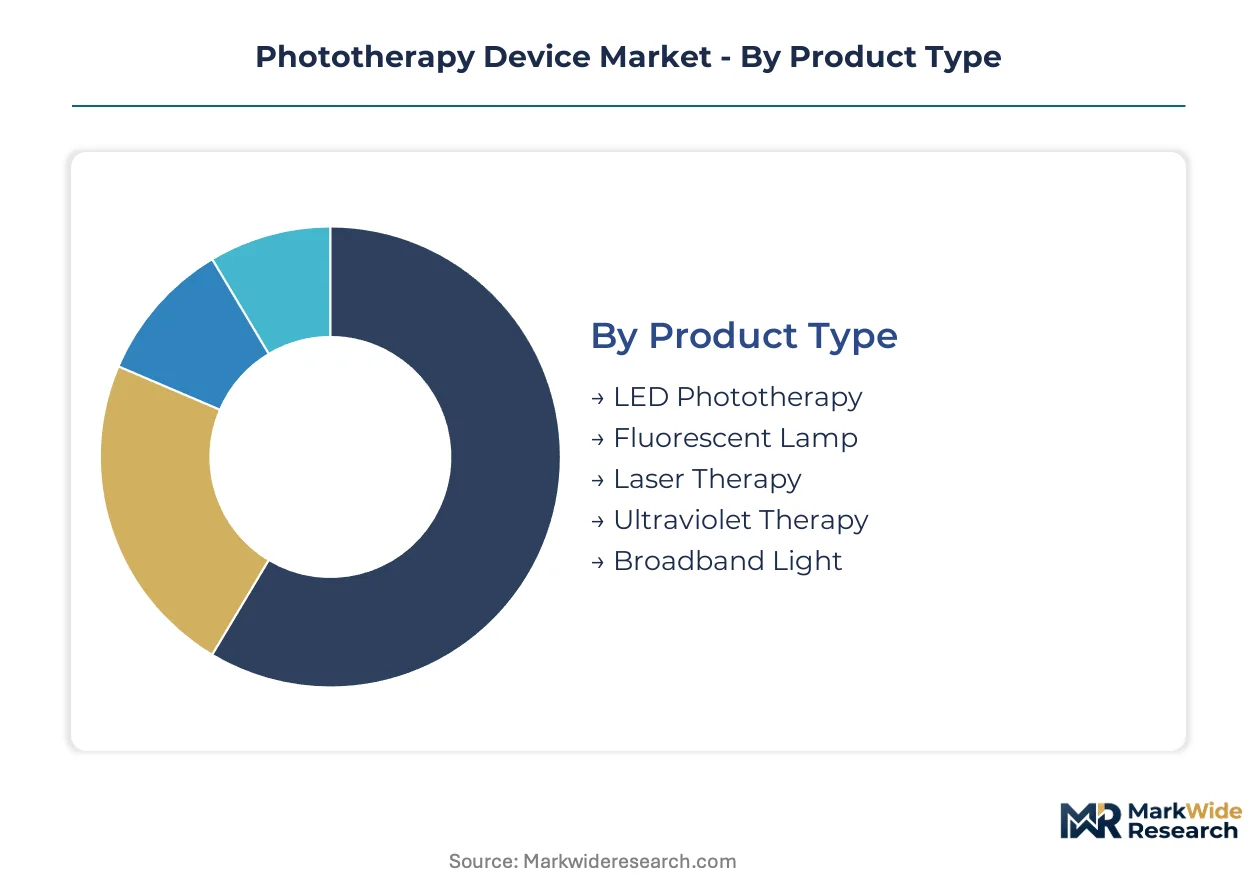
Segmentation within the phototherapy device market provides crucial insight into the technological shifts and diverse clinical demands influencing product development and adoption strategies. Understanding these categories helps manufacturers align innovations with specific medical requirements and end-user preferences.
Product Type:
Regulatory bodies such as the FDA and Europe's MDR increasingly scrutinize product type classifications, influencing device approval pathways and market access.
- LED Phototherapy:Emits highly precise, targeted wavelengths, such as blue light for neonatal jaundice or specific UV bands for dermatological conditions. Demand is concentrating in China due to its expanding healthcare infrastructure and focus on energy-efficient solutions.
- Ultraviolet Therapy:Utilizes specific UVA or UVB wavelengths to induce therapeutic effects in skin cells, widely employed for chronic dermatological diseases like psoriasis. Hospitals in Germany are investing in these systems for established clinical protocols.
- Fluorescent Lamp:These devices provide broad-spectrum light, historically used for general phototherapy applications, but are being displaced by more precise technologies.
- Laser Therapy:Employs monochromatic, coherent light for highly localized treatment of specific skin lesions or conditions, often in specialized clinics.
- Broadband Light:Delivers a wide range of light wavelengths, used for various dermatological and aesthetic treatments, offering versatility in clinical settings.
Established volume favors Fluorescent Lamp technology; emerging adoption favors LED Phototherapy.
Application:
The varied applications of phototherapy devices reflect diverse clinical needs and patient populations across different medical disciplines.
- Neonatal Jaundice:Involves exposing infants to blue light (typically 450-470 nm) to break down bilirubin, preventing severe neurological complications. Demand is concentrating in pediatric centers in India due to high birth rates and increasing access to specialized care.
- Psoriasis Treatment:Utilizes specific UV wavelengths (e.g., narrowband UVB) to slow down rapid skin cell growth and reduce inflammation in patients with chronic plaque psoriasis. Dermatology clinics in the United States prioritize these systems for their established efficacy.
- Seasonal Affective Disorder:Administers bright light therapy to regulate circadian rhythms and improve mood in individuals affected by reduced daylight exposure.
- Acne Management:Employs blue or red light to target acne-causing bacteria and reduce inflammation, often used as an adjunctive therapy.
- Atopic Dermatitis:Light therapy helps reduce inflammation and itching in patients with eczema, offering a non-pharmacological treatment option.
Clinical utility drives demand in Neonatal Jaundice, while patient comfort is central to Seasonal Affective Disorder.
End User:
Different end-user segments exhibit distinct purchasing behaviors and require tailored device features, influencing market distribution strategies.
- Hospitals:Large healthcare institutions requiring high-capacity, multi-functional phototherapy systems for diverse patient populations, including neonates and critical care patients. Procurement patterns in France favor integrated solutions for streamlined operations.
- Dermatology Clinics:Specialized facilities focusing on skin conditions, demanding precise, often high-intensity systems for conditions like psoriasis and vitiligo. These clinics in the United Kingdom prioritize devices with advanced wavelength targeting.
- Pediatric Centers:Dedicated facilities for infant and child care, primarily utilizing phototherapy for neonatal jaundice management with specialized safety features.
- Cosmetic Clinics:Focus on aesthetic light-based treatments, often employing broadband light or laser systems for skin rejuvenation and pigmentation issues.
- Therapy Centers:Provide various light therapy services, including those for pain management or mental health, often with smaller, more versatile units.
Infrastructure investment primarily supports Hospitals, while specialized care drives growth in Dermatology Clinics.
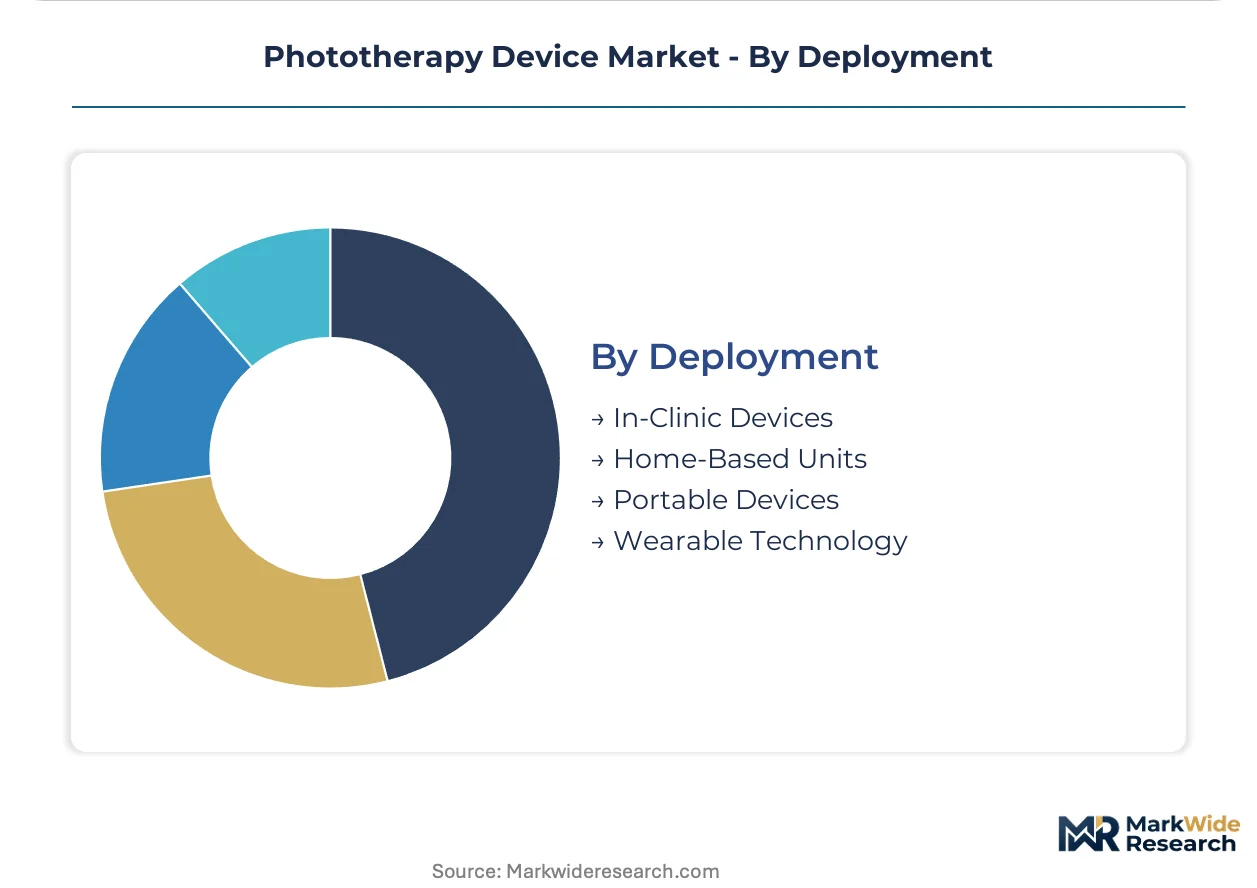
Deployment:
The maturity of deployment models ranges from established clinical setups to innovative, patient-centric solutions gaining traction.
- In-Clinic Devices:Large, stationary units designed for supervised administration of high-intensity light therapy within medical facilities, ensuring precise dosage and patient safety. Hospitals in Japan maintain these systems for consistent, high-volume treatments.
- Home-Based Units:Smaller, user-friendly devices enabling patients to self-administer phototherapy for chronic conditions like psoriasis under medical guidance. Demand for these devices is expanding most quickly in the United States due to patient convenience and cost-effectiveness.
- Portable Devices:Compact, often handheld units offering flexibility for targeted treatment or use in various clinical or home settings.
- Wearable Technology:Miniaturized, flexible light sources integrated into patches or garments, providing continuous or localized therapy directly on the skin.
Traditional care delivery relies on In-Clinic Devices, yet patient empowerment drives interest in Home-Based Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for phototherapy devices varies significantly across regions, with emerging economies often more sensitive to initial capital outlay, while developed markets prioritize advanced features and clinical efficacy. Countries with established healthcare systems and high prevalence rates drive consistent demand for state-of-the-art phototherapy solutions. Regulatory frameworks also heavily influence market access and product adoption in each region.
China
Rising incidence of dermatological conditions and neonatal jaundice drives substantial demand for phototherapy units in China. The NMPA registration process mandates rigorous safety and efficacy testing for all medical devices. Expanding public healthcare infrastructure in cities like Shanghai and Beijing supports the widespread adoption of energy-efficient LED phototherapy systems.
United States
Psoriasis treatment and the expanding home-use market fuel demand for phototherapy devices across the United States. Manufacturers must secure FDA's 510(k) clearance for market entry, ensuring device safety and effectiveness. Dermatology clinics in major metropolitan areas like New York and Los Angeles prioritize systems with advanced wavelength targeting capabilities.
Germany
Germany's robust clinical dermatology segment and established clinical protocols ensure consistent investment in ultraviolet therapy systems. CE marking under the MDR imposes strict requirements for clinical evidence and post-market surveillance. Hospitals in regions like Bavaria and North Rhine-Westphalia actively seek integrated phototherapy solutions for streamlined operations.
India
High birth rates and increasing access to specialized care significantly drive demand for neonatal jaundice phototherapy in India. The country's national medical device standards guide the procurement of essential medical equipment. Pediatric centers in urban hubs such as Mumbai and Delhi are increasingly investing in blue light phototherapy units.
France
Hospitals in France increasingly favor integrated phototherapy solutions for improved operational efficiency and patient management. Compliance with CE marking under the MDR is a prerequisite for all phototherapy devices sold in the market. Procurement patterns in regions like Île-de-France and Auvergne-Rhône-Alpes prioritize comprehensive packages from single vendors.
Phototherapy Device Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the phototherapy device market. The market structure exhibits a tiered consolidation, with established medical device giants coexisting with specialized phototherapy solution providers. Strategic archetypes include R&D-focused innovators, clinical device specialists, and emerging home-use market players. Dominant competitive moves involve strategic partnerships for market access and portfolio diversification to address various applications.
Specialists in specific phototherapy applications include Natus Medical, which focuses on solutions for neonatal jaundice management. GE Healthcare leverages its extensive hospital network to drive adoption in neonatal care, demonstrating a strong presence in broader healthcare systems. Herbert Waldmann dominates the European clinical dermatology segment with its high-intensity UV systems, exemplifying a regional specialization in advanced phototherapy.
| Leading Market Players |
|---|
| GE Healthcare |
| Atom Medical |
| Draeger |
| Herbert Waldmann |
| Natus Medical |
| Daavlin |
| Beurer |
| National Biological |
| Solarc Systems |
| Others |
Cost & Logistics Intelligence
LED technology's substitution for traditional fluorescent lamps simultaneously reshapes supply geography and pricing economics. This shift concentrates component manufacturing in specific regions, influencing cost structures and overall device pricing.
Pricing Analysis
After-sales service contracts and bundled software solutions drive significant lifetime value for phototherapy devices. The pricing model often combines per-unit transactional sales for hardware with recurring contract-based revenue for maintenance and upgrades. Price differentiation stems from FDA/CE certification levels, advanced wavelength targeting capabilities, and brand premium. Pricing softness exists in the home-use segment due to competition, while clinical-grade devices maintain premium positions. Smaller clinics and healthcare facilities in emerging economies exhibit the highest price sensitivity, unlike large hospital networks seeking integrated solutions.
Supply Chain Analysis
Rising inbound logistics costs, particularly from Asian manufacturing hubs, influence the final price of phototherapy units. Geographic supply concentration for LED emitters and optical components primarily centers in China, with specialized UV lamp manufacturing in Germany. Raw material dependencies include advanced semiconductors for LED drivers and specialized glass for optical filters. Single-source vulnerability for high-performance LED components represents a structural supply chain risk. Distribution runs through direct sales channels to hospitals and dermatology clinics, alongside specialized medical distributors and online platforms for home-based units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phototherapy device market faces a significant talent gap in advanced solid-state lighting physics and medical device integration. This specialized expertise is critical for next-generation product development and regulatory navigation.
For Market Incumbents: Secure long-term supply agreements for critical LED components, protecting against supply chain disruptions and new entrant competition. Invest in vertical integration for key optical components, mitigating single-source risks. Diversify product portfolios to include digital health integration, countering the threat from systemic drug alternatives in psoriasis treatment. Pursue partnerships with large hospital networks to standardize integrated treatment room solutions.
For New Entrants and Emerging Players: FDA's De Novo pathway for novel low-risk devices offers a faster route to market entry. Target the underserved home-use market for chronic conditions like mild psoriasis, leveraging consumer-friendly designs and direct-to-consumer channels. Focus on developing wearable phototherapy patches, offering a distinct value proposition over traditional in-clinic systems. Partner with telehealth platforms for integrated patient management and remote dosimetry capabilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized, specialized phototherapy device manufacturers with strong regional presence. The market offers long-term viability, driven by chronic dermatological conditions and neonatal care needs over the next decade. Seek out companies with proprietary LED technology and established regulatory approvals in major markets. Watch for increased M&A activity driven by large medical device conglomerates seeking to expand their dermatology or neonatal portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Technology R&D Investment | Accelerates development of energy-efficient, precise wavelength systems for diverse medical applications. |
| NMPA Regulatory Approval Focus | Unlocks substantial volume demand from China's expanding public healthcare infrastructure and patient base. |
| Home-Use Device Certification | Creates new revenue streams by directly addressing consumer needs for convenient, at-home chronic disease management. |
| Digital Health Platform Integration | Enhances patient monitoring, personalizes treatment dosimetry, and provides valuable clinical data for practitioners. |
| Clinical Evidence Generation (MDR) | Ensures compliance with stringent European regulations, maintaining market access and building physician trust. |
Research Approach
Operator-level perspectives from dermatologists, pediatricians, hospital procurement managers, and medical device engineers anchored the qualitative base. Primary interviews combined with robust secondary validation informed market understanding. Secondary sources included FDA filings, CE marking databases, NMPA registrations, and specialized medical journals. This approach facilitated bottom-up and top-down triangulation for data accuracy.
Sensitivity analysis explored various growth scenarios for phototherapy device adoption across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, and deployment. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included dermatological condition prevalence and healthcare infrastructure investment.
Underlying assumptions cover current regulatory stability and expected technological progression, with deviation risk concentrated in unforeseen clinical trial outcomes or major shifts in reimbursement policies. Forecasts reflect these documented assumptions over the projection horizon. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Sustained Acoustic Medicine Market