
 Mexico Hospital Supplies Market | 2026-2036
Mexico Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Hospital Supplies Market Foresight
Modular surgical kit bundling is hardening as the dominant procurement format across Mexican hospital systems. Cardinal Health leverages its distribution infrastructure to control kit assembly logistics in central Mexico. Medtronic anchors high-value implant modules through direct hospital partnerships in Mexico City. Baxter sustains fluid-management kit standardization across both public ISSSTE facilities and private hospital chains.
Hospital supplies encompass sterile and non-sterile products used in patient treatment, surgery, and diagnostic procedures, including latex and nitrile examination gloves meeting ASTM D6319 tensile-strength specifications, single-use syringes manufactured via injection molding of medical-grade polypropylene, and electrosurgical pencils rated for 300-500 kHz output frequency. Disposable supplies dominate volume throughput in Mexican procurement channels due to infection-control protocols and COFEPRIS single-use mandates, while surgical instruments capture concentrated margin pools through premium stainless-steel and ceramic-coated instrument sets. Diagnostic equipment represents the fastest-growing product category as public hospital networks modernize imaging and point-of-care testing capabilities under INSABI restructuring.
COFEPRIS enforces medical device registration under NOM-240-SSA1-2012, shaping import timelines and quality-documentation requirements for all foreign manufacturers. NOM-117-SSA1-1994 governs sterilization validation, forcing domestic distributors to maintain certified reprocessing partnerships or shift entirely to pre-sterilized disposables. Stakeholders must monitor whether Mexico's pending alignment with FDA-recognized consensus standards accelerates dual-approval pathways for US-origin suppliers.
Market Dynamics
Modular surgical kit bundling is compressing procurement cycles across Mexican hospital systems, forcing distributors to reconfigure logistics networks around pre-assembled sterile modules rather than discrete SKUs.
Growth Catalysts
- COFEPRIS Registration Acceleration:Updated medical device registration protocols under NOM-240-SSA1-2012 are compressing approval timelines for compliant importers.
- Specialty Hospital Expansion:Monterrey and Guadalajara surgical centers are scaling procurement of advanced procedure kits for orthopedic and cardiovascular interventions.
- Single-Use Mandate Enforcement:Infection-control protocols and COFEPRIS disposable mandates are displacing reprocessed instruments in tertiary care facilities.
Market Restraints
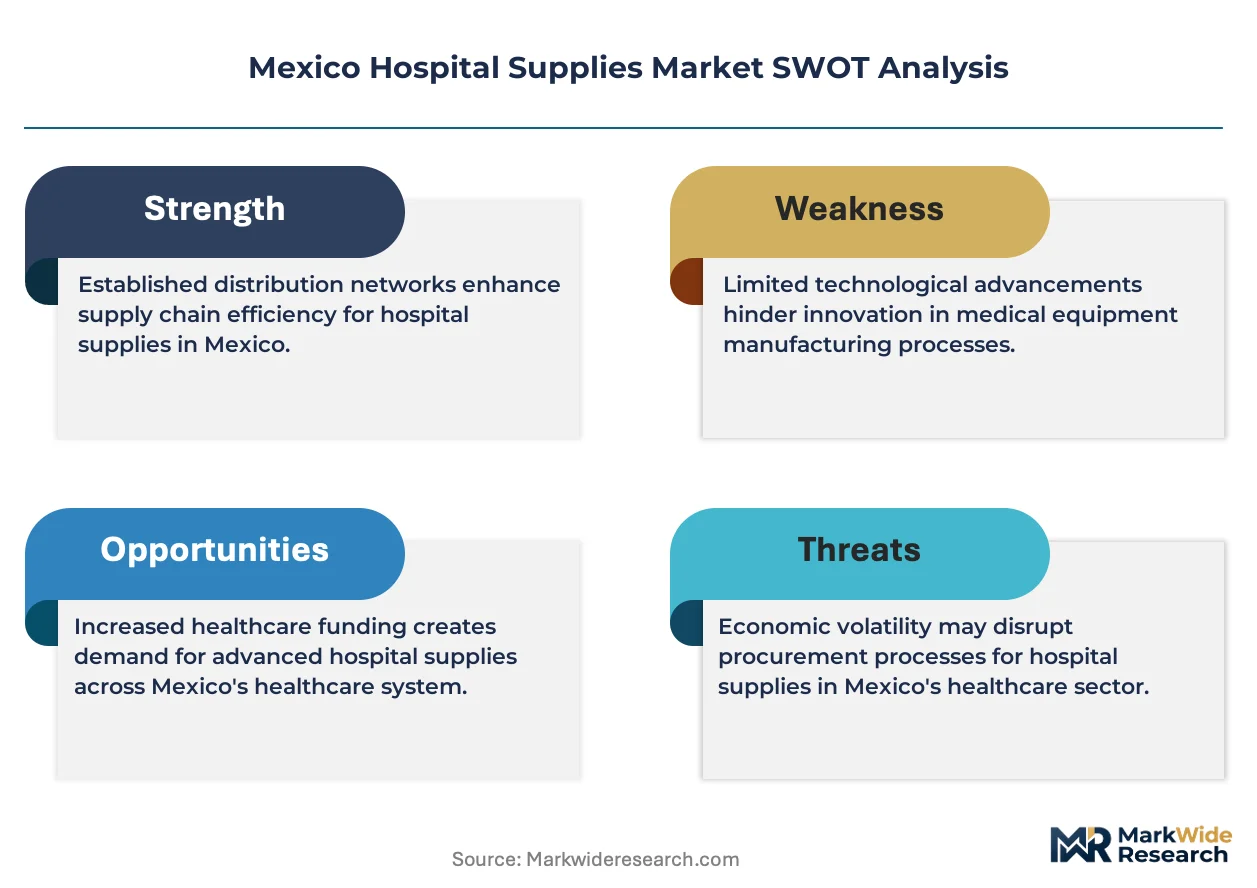
- Import Dependency Concentration:Domestic production gaps in medical-grade polypropylene and nitrile butadiene rubber force reliance on US and Asian resin suppliers.
- Sterilization Validation Costs:NOM-117-SSA1-1994 compliance requires certified reprocessing partnerships or full conversion to pre-sterilized disposables, elevating unit economics.
- Regulatory Documentation Burden:COFEPRIS quality-documentation requirements extend import timelines for foreign manufacturers lacking established Mexican legal representatives.
Strategic Opportunities
- Jalisco Diagnostic Modernization:Public hospital networks under INSABI restructuring are replacing legacy imaging equipment with point-of-care testing platforms.
- Dual-Approval Pathway Alignment:Pending harmonization with FDA-recognized consensus standards could accelerate market entry for US-origin suppliers with existing 510(k) clearances.
- Kit Assembly Localization:Regional distributors in Nuevo León are capturing margin pools by performing final sterile packaging of imported component modules.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Public ISSSTE facilities face recruitment gaps for technicians qualified in electrosurgical equipment calibration and preventive maintenance protocols.
- Legacy Inventory System Integration:Hospital chains migrating to modular kit procurement encounter data-translation friction with existing ERP platforms configured for discrete item tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Hospital Supplies Market |
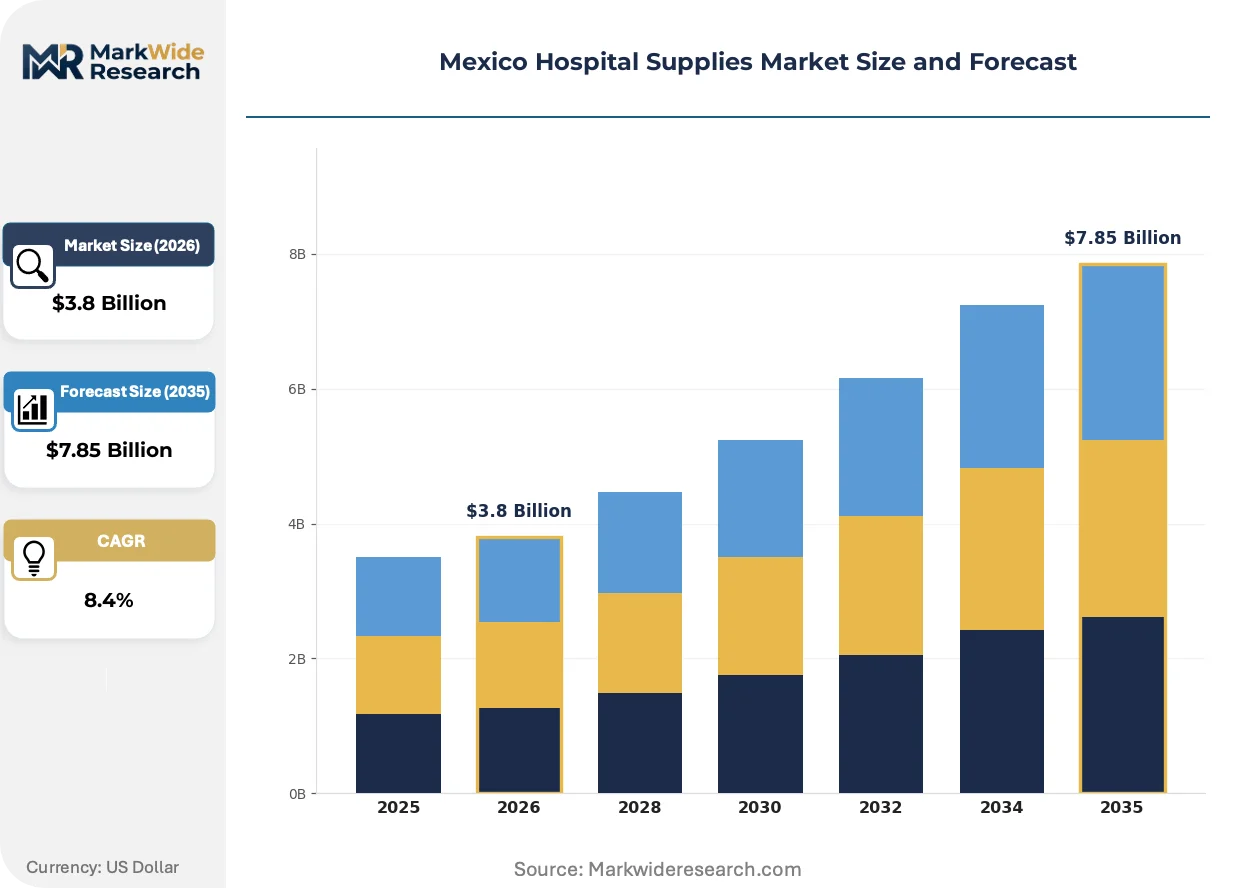
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposables, Surgical Instruments, Diagnostic Equipment, Medical Implants End User: Clinics, General Hospitals, Specialty Hospitals, Long-Term Care Facilities Technology: Telemedicine, Robotics, Wearable Devices, Electronic Health Records Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Medtronic, 3M, Baxter, Becton, Dickinson and Company, Boston Scientific Corporation, Cardinal Health, Abbott Laboratories, Koninklijke Philips NV, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Hospital Supplies Market Shifts & Advancements
Three forces are actively reshaping Mexico's hospital supplies landscape: sterile barrier materials are converging with smart tracking technologies, regulatory data requirements are tightening traceability standards, and procurement hierarchies are flattening as hospital systems consolidate vendor relationships.
Smart sterile barrier systems incorporating RFID-enabled temperature and humidity sensors are consolidating supply chain visibility for high-value implant modules. Tertiary cardiac centers in Mexico City are piloting these platforms to monitor cold-chain integrity of biologic mesh and synthetic graft shipments. The technology is consolidating accountability previously distributed across multiple handoff points between importer warehouses and hospital receiving docks.
COFEPRIS is mandating expanded Unique Device Identification compliance timelines for Class II and III devices, mirroring FDA UDI phased implementation. Foreign manufacturers must now embed GS1-standardized identifiers at the unit-of-use level, not merely case-level packaging. Implant suppliers with orthopedic and cardiovascular portfolios face the steepest documentation retrofit requirements.
Hospital systems are compressing vendor rosters from fragmented multi-source purchasing to single-source kit contracts with integrated logistics providers. Private hospital chains in Mexico State are replacing discrete item procurement with annual framework agreements covering entire procedure categories. This concentration is most visible in laparoscopic surgery, where standardized instrument and consumable bundles now dominate tender specifications.
Mexico Hospital Supplies Market Segmentation
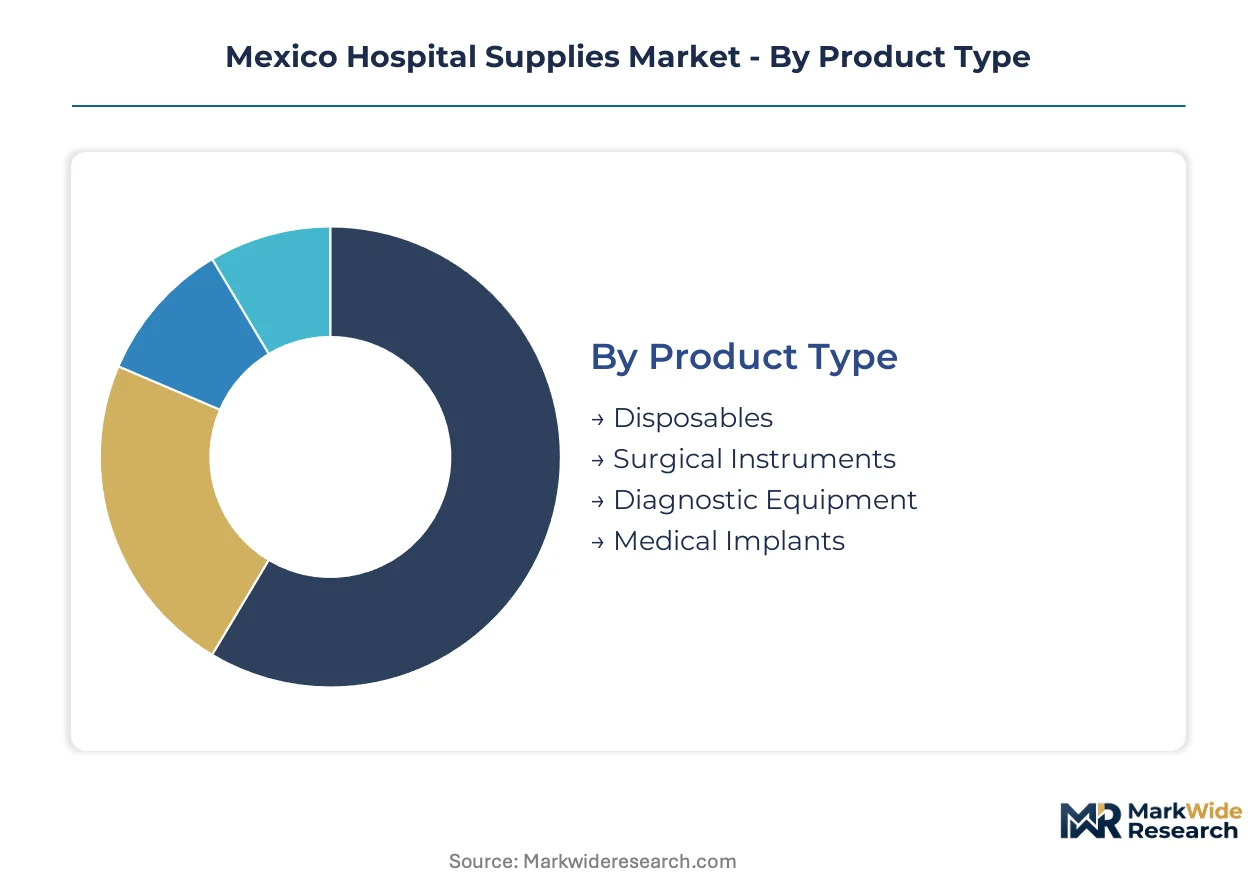
Segmentation in Mexico's hospital supplies market reveals how procurement power concentrates across specific product categories and institutional tiers. Understanding these divides exposes where margin pools accumulate and where regulatory compliance creates entry barriers for new suppliers.
Product Type:
Supply concentration in this category tracks directly to sterilization infrastructure and import dependency patterns across Mexican states.
- Disposables:Single-use gloves, syringes, and wound dressings manufactured from medical-grade polypropylene and nitrile butadiene rubber dominate procurement volumes. Jalisco, Nuevo León, and Mexico State drive demand concentration as COFEPRIS single-use mandates displace reprocessed instruments in tertiary facilities.
- Surgical Instruments:Premium stainless-steel and ceramic-coated instrument sets command concentrated margin pools through specialized orthopedic and cardiovascular applications. Monterrey and Guadalajara specialty hospitals are expanding procurement of advanced procedure kits, forcing distributors to reconfigure logistics around pre-assembled sterile modules.
- Diagnostic Equipment:Imaging and point-of-care testing platforms are gaining share fastest as INSABI restructuring modernizes public hospital networks.
- Medical Implants:Biologic mesh and synthetic grafts require cold-chain integrity monitoring via RFID-enabled sterile barrier systems.
Today's leader: Disposables. Tomorrow's challenger: Diagnostic Equipment.
End User:
Cost tier stratification across this category separates high-volume public procurement from premium private contracting.
- Specialty Hospitals:Cardiovascular and orthopedic centers in Mexico City and Monterrey anchor demand for high-value implant modules and advanced surgical kits. These facilities command direct manufacturer partnerships that bypass traditional distribution layers.
- General Hospitals:ISSSTE facilities and state health systems standardize fluid-management kits and basic disposables through framework agreements. NOM-117-SSA1-1994 sterilization compliance forces conversion to pre-sterilized supplies, elevating unit economics.
- Clinics:Outpatient surgical centers concentrate demand for laparoscopic instrument bundles.
- Long-Term Care Facilities:Extended-care institutions in Mexico State prioritize wound care disposables and patient monitoring consumables.
Specialty Hospitals capture premium pricing. General Hospitals drive volume scale.
Technology:
Application maturity in this category spans from established digital infrastructure to emerging intervention platforms.
- Electronic Health Records:Hospital chains migrating to modular kit procurement require ERP integration with legacy inventory systems, creating data-translation friction that slows technology adoption.
- Telemedicine:Remote consultation platforms expand point-of-care testing demand in Jalisco public networks under INSABI modernization programs.
- Robotics:Surgical automation systems concentrate in Mexico City tertiary centers.
- Wearable Devices:Patient monitoring wearables penetrate private hospital chains for post-operative tracking.
Electronic Health Records anchor current investment. Robotics represents the steepest expansion trajectory.
Distribution Channel:
Customer type concentration here separates integrated logistics providers from transactional resellers.
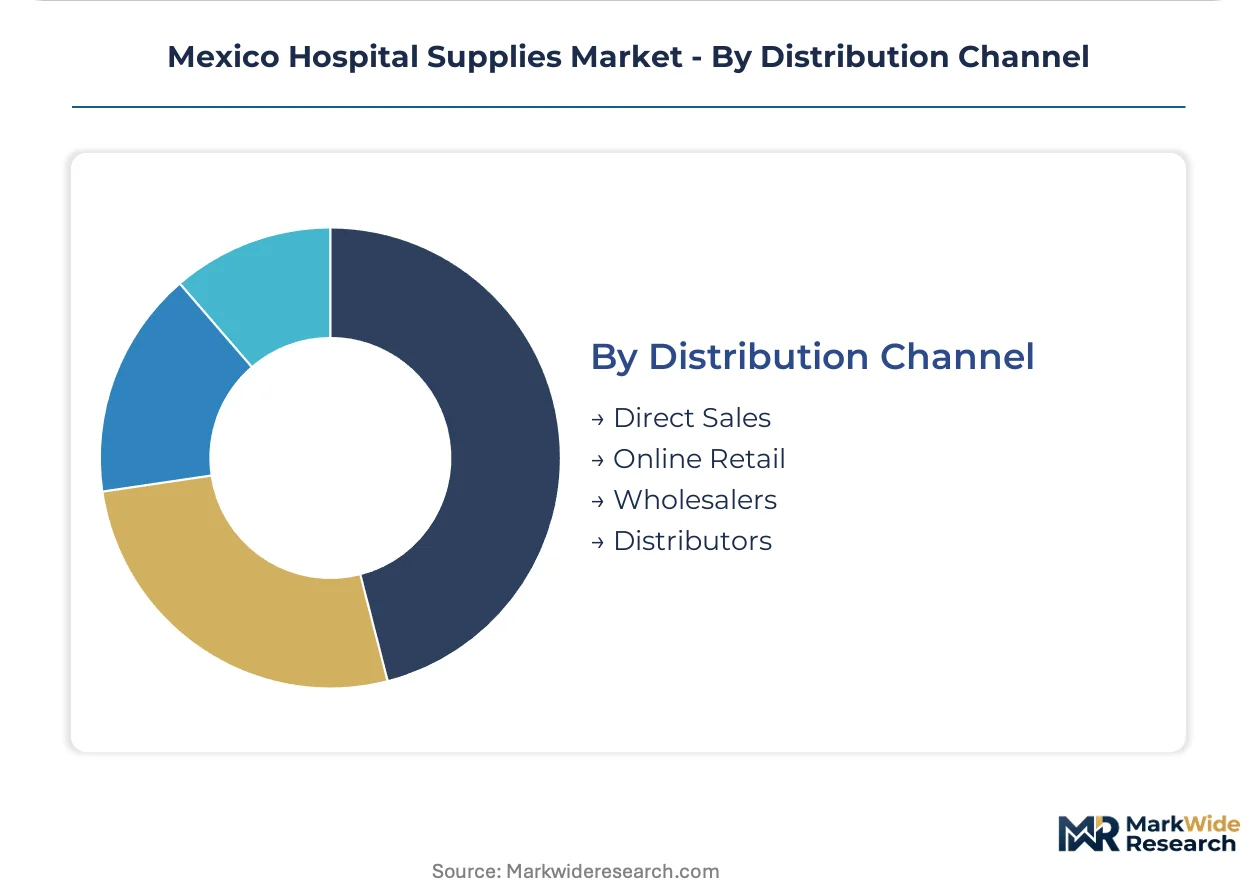
- Distributors:Regional distributors in Nuevo León capture margin pools by performing final sterile packaging of imported component modules, compressing procurement cycles through kit assembly localization.
- Direct Sales:Implant manufacturers with orthopedic and cardiovascular portfolios bypass intermediaries for Mexico City cardiac centers, consolidating vendor relationships under single-source contracts.
- Wholesalers:Bulk procurement channels serve ISSSTE facilities with standardized disposables.
- Online Retail:E-commerce platforms penetrate clinic and small-hospital segments for non-urgent supplies.
Distributors control kit logistics. Direct Sales capture implant margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's hospital supplies industry traces its modern procurement infrastructure to the 1980s expansion of social security health systems, when federal programs standardized bulk purchasing for public hospitals across major metropolitan zones.
Mexico City Metro
Cardiovascular and orthopedic specialty hospitals anchor demand for high-value implant modules and advanced surgical kits. COFEPRIS regulatory oversight under NOM-240-SSA1-2012 shapes import timelines for foreign manufacturers serving this cluster. Tertiary cardiac centers in the capital pilot RFID-enabled sterile barrier systems to monitor cold-chain integrity of biologic mesh shipments.
Nuevo León
Monterrey's surgical centers drive procurement of advanced procedure kits for orthopedic interventions, forcing distributors to reconfigure logistics around pre-assembled sterile modules. The state's regional distributors capture margin pools by performing final sterile packaging of imported component modules. NOM-117-SSA1-1994 sterilization compliance elevates conversion to pre-sterilized supplies across both public and private facilities.
Jalisco
Public hospital networks under INSABI restructuring modernize imaging and point-of-care testing capabilities, making diagnostic equipment the fastest-growing product category in this state. COFEPRIS single-use mandates displace reprocessed instruments in Guadalajara's tertiary facilities. Specialty hospitals in the metropolitan area expand procurement of advanced surgical kits alongside disposable supply volumes.
Bajío Region
General hospitals and state health systems standardize fluid-management kits and basic disposables through framework agreements. ISSSTE facilities face biomedical engineering talent scarcity for electrosurgical equipment calibration and preventive maintenance protocols. The region's hospital chains encounter data-translation friction when migrating to modular kit procurement with legacy ERP platforms.
Northern Border States
Import dependency concentrates in medical-grade polypropylene and nitrile butadiene rubber, forcing reliance on US and Asian resin suppliers. Private hospital chains consolidate vendor rosters from fragmented multi-source purchasing to single-source kit contracts with integrated logistics providers. Pending harmonization with FDA-recognized consensus standards could accelerate market entry for US-origin suppliers with existing 510(k) clearances.
Mexico Hospital Supplies Market Competitive Landscape
Premium-margin players sit above commodity-margin players across kit assembly and distribution capabilities, with implant manufacturers commanding direct hospital partnerships while regional distributors capture logistics efficiencies. The market structures around three tiers: multinational manufacturers with established COFEPRIS registrations, regional kit assemblers with sterile packaging certifications, and transactional resellers serving clinic segments. Dominant competitive moves include backward integration into sterile barrier fabrication and geographic expansion through state-level framework agreements.
Within the multinational tier, Medtronic, Cardinal Health, and Baxter exemplify divergent strategic positioning. Medtronic occupies a position anchoring high-value implant modules through direct hospital partnerships. Cardinal Health sits within the integrated logistics provider archetype, controlling kit assembly infrastructure. Baxter represents the standardization-focused player sustaining fluid-management kit contracts across both public ISSSTE facilities and private hospital chains.
| Leading Market Players |
|---|
| Medtronic |
| 3M |
| Baxter |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Cardinal Health |
| Abbott Laboratories |
| Koninklijke Philips NV |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
NOM-117-SSA1-1994 sterilization validation mandates gate qualified supply access and premium-tier pricing for hospital supplies in Mexico, forcing importers to either certify reprocessing partnerships or convert entirely to pre-sterilized disposables that command higher unit economics. COFEPRIS registration timelines under NOM-240-SSA1-2012 further stratify pricing power between established registrants and new market entrants facing extended compliance costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Mexico's hospital supplies procurement, separating COFEPRIS-registered implant modules from basic disposable commodities. Price differentiation hinges on sterilization certification grade and volume scale under framework agreements, with ISSSTE facilities driving cost compression through consolidated tender specifications. Pricing pressure stems from single-use mandate enforcement displacing reprocessed instruments, while specialty hospitals in Mexico City exhibit lowest price sensitivity for cardiovascular and orthopedic kits.
Supply Chain Analysis
Biomedical engineering talent scarcity in Mexican manufacturing geographies constrains domestic kit assembly capacity and elevates reliance on imported sterile modules. Supply concentration centers on US and Asian sources for medical-grade polypropylene and nitrile butadiene rubber, with Northern Border States facing acute import dependency. Single-source vulnerability runs through resin suppliers for disposable gloves and syringes. Distribution runs through Nuevo León-based regional assemblers performing final sterile packaging for hospital system delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's hospital supplies market functions as a stable compounder, with INSABI restructuring and specialty hospital expansion providing steady demand tailwinds across public and private procurement channels.
For Market Incumbents: Extend kit assembly localization into Nuevo León to capture margin pools from regional sterile packaging demand and defend against emerging distributor competition. Deepen backward integration into sterile barrier fabrication to offset NOM-117-SSA1-1994 compliance cost inflation. Anchor direct hospital partnerships in Guadalajara's expanding specialty surgical centers before new entrants secure COFEPRIS registrations.
For New Entrants and Emerging Players: Capture white-space opportunity in Jalisco diagnostic equipment modernization under INSABI restructuring programs, where point-of-care testing platforms face limited incumbent saturation. Target clinic segments in Mexico State with laparoscopic instrument bundles through e-commerce channels that bypass established distributor relationships. Lead with RFID-enabled cold-chain monitoring as a differentiated service layer for biologic mesh shipments.
For Investors and Strategic Acquirers: Roll-up economics work for regional kit assemblers with sterile packaging certifications because hospital systems are consolidating vendor rosters from fragmented multi-source purchasing to single-source framework agreements. Five-to-ten year viability rests on capturing state-level procurement contracts as procurement hierarchies flatten. Monitor pending FDA consensus standards harmonization as the signal indicating accelerated market entry pathways for US-origin suppliers with existing clearances.
| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Acceleration | Compresses approval timelines for compliant importers serving Monterrey specialty hospitals. |
| Kit Assembly Localization | Nuevo León distributors capture margin pools through final sterile packaging of imported modules. |
| Hospital System Partnership | Direct manufacturer relationships in Mexico City bypass traditional distribution layers for implant sales. |
| Software Companion Development | RFID-enabled tracking platforms consolidate supply chain visibility for cold-chain integrity monitoring. |
| Reimbursement Strategy | INSABI restructuring frameworks determine diagnostic equipment procurement prioritization in Jalisco public networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and COFEPRIS regulatory consultants with secondary validation against hospital procurement databases, GPO contract filings, and customs import records. Bottom-up demand modeling across product categories triangulated with top-down market sizing from federal health expenditure disclosures.
Comparable-period anchoring linked projection assumptions to historical procurement cycle patterns across the analysis window, with segmentation modeling across disposables, surgical instruments, diagnostic equipment, and medical implants by end-user tier and distribution channel. CAGRs derived from trend extrapolation of specialty hospital expansion rates, single-use mandate compliance trajectories, and INSABI modernization program disbursements.
Regulatory timeline delays, resin supply disruptions, and biomedical engineering recruitment gaps are the dominant revision risks that could compress forecast accuracy. Material deviation in COFEPRIS alignment with FDA consensus standards or INSABI restructuring pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Microcarrier Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Safety Box for Syringe Market