
 Dental Surgical and Diagnostic Devices Market | 2026-2036
Dental Surgical and Diagnostic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Surgical and Diagnostic Devices Market Analysis
ISO 13485 certification is bifurcating the competitive landscape between qualified manufacturers and aspirants lacking quality management credentials. Dentsply Sirona leverages its integrated CAD/CAM workflow to dominate restorative digital dentistry. Envista Holdings Corporation anchors its position through specialized orthodontic and implantology portfolios. Danaher Corporation sustains competitive intensity via precision instrumentation and diagnostic platform breadth.
Dental surgical and diagnostic devices encompass powered and hand-held instruments, radiographic systems, intraoral scanners, and single-use consumables designed for hard- and soft-tissue procedures, disease detection, and treatment planning. These products typically operate within 3-70 kV ranges for imaging equipment and withstand autoclave sterilization cycles at 121-134 degrees Celsius. Diagnostic imaging commands margin concentration due to software-locked recurring revenue and replacement part dependency. Surgical instruments maintain steadier replacement cycles while consumables generate volume-driven recurring streams across oral surgery and periodontics applications.
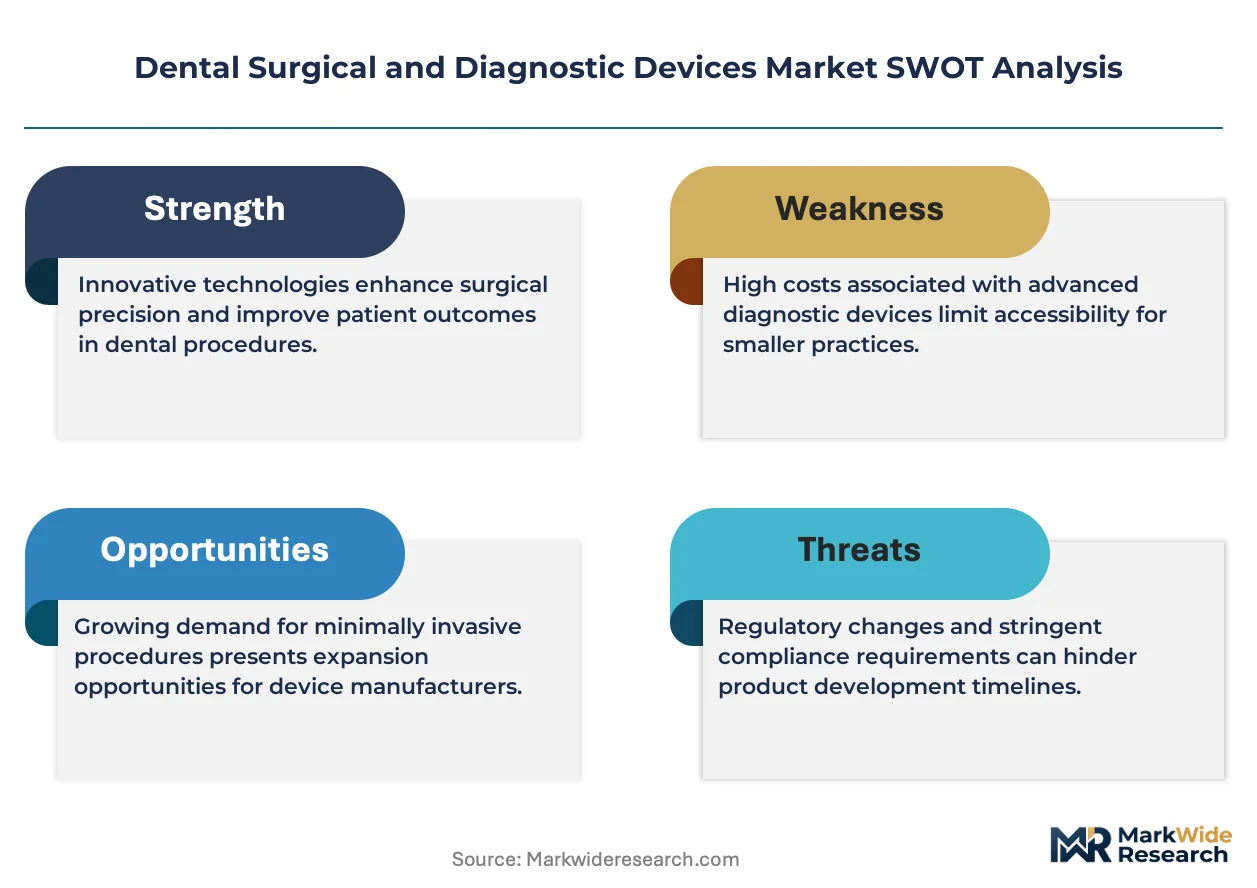
The FDA's 510(k) clearance framework governs market entry for Class II dental devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking access. Japan's PMDA maintains distinct pharmaceutical and medical device agency oversight that foreign manufacturers must navigate for commercialization. Stakeholders must monitor evolving harmonization between FDA and MDR quality system expectations to preempt compliance cost escalation.
Market Dynamics
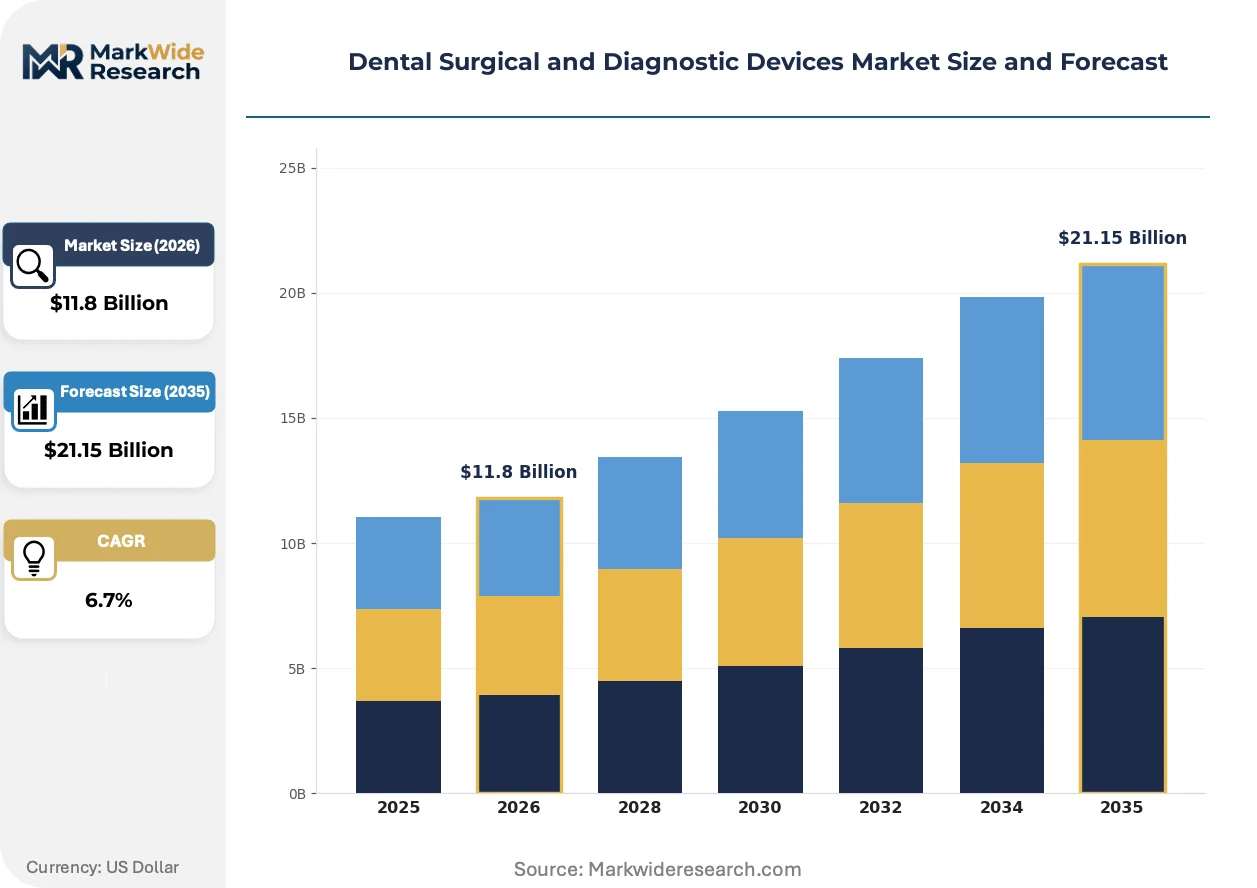
ISO 13485 certification requirements are concentrating manufacturing capacity among qualified suppliers, while dental clinics accelerate diagnostic imaging adoption as a core revenue stream. This dual pressure reshapes competitive positioning between established instrument makers and emerging digital workflow providers.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States exhibit elevated procedural volumes for implantology and periodontal surgery. Oral health expenditure correlates directly with population age structure in these markets.
- FDA 510(k) Streamlining:The premarket notification pathway for Class II dental devices accelerates product iteration cycles. Manufacturers leverage this framework to deploy iterative software updates for imaging platforms.
- Intraoral Scanner Penetration:CAD/CAM adoption in restorative practices displaces conventional impression materials. Chairside milling integration drives recurring consumable demand for ceramic blocks and resin composites.
Market Restraints
- Titanium Supply Concentration:Implant-grade titanium feedstock originates from a limited supplier base concentrated in aerospace-adjacent metallurgy. Price volatility in this input compresses margin stability for implant manufacturers.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation imposes expanded clinical investigation requirements for CE marking renewal. Small-to-mid manufacturers face disproportionate compliance cost escalation relative to revenue base.
- Autoclave Sterilization Limits:Polymer-based surgical instruments face thermal degradation thresholds at 134 degrees Celsius. Material science constraints restrict design freedom for single-use instrument alternatives.
Strategic Opportunities
- India Dental Infrastructure:Private clinic chains in Mumbai, Delhi, and Bangalore are expanding diagnostic imaging capabilities. The CDSCO regulatory pathway offers faster market entry relative to mature jurisdictions.
- AI-Assisted Radiography:Machine learning algorithms for caries detection and pathology identification are converging with cone-beam computed tomography systems. Software-locked diagnostic modules create recurring revenue attachment.
- PLI Scheme Alignment:India's Production Linked Incentive scheme for medical devices reduces effective manufacturing cost for domestic production. Foreign manufacturers establishing local assembly gain tariff and tax advantages.
Industry Challenges
- Biocompatibility Certification Timelines:ISO 10993 testing protocols for new implant surface coatings extend development cycles by 18-24 months. Delayed regulatory feedback loops compress commercialization windows.
- Legacy PMS Integration:New digital impression systems require interoperability with established practice management software. Fragmented data standards across vendors complicate seamless workflow deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Surgical and Diagnostic Devices Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Imaging, Consumables, Equipment Application: Oral Surgery, Periodontics, Orthodontics, Endodontics End User: Dentists, Dental Clinics, Hospitals, Research Laboratories Technology: Digital Imaging, Laser Systems, Ultrasonic Devices, Surgical Navigation |
| Companies Covered | Dentsply Sirona, Carestream Health, Envista Holdings Corporation, Danaher Corporation, Planmeca Oy, 3M Company, KaVo Kerr, Ivoclar Vivadent AG, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Surgical and Diagnostic Devices Market Emerging Trajectories
Digital dentistry workflows are compressing traditional laboratory intermediation, while regulatory harmonization efforts between FDA and EU authorities reshape quality system investment priorities. Three developments merit particular attention.
Photopolymer resin formulations for 3D-printed surgical guides are bifurcating manufacturing economics between centralized dental laboratories and chairside production. Large clinic chains in the United States and Germany are deploying in-house printing capacity for same-day surgical stent fabrication. This technology compression threatens conventional milling center revenue models while enabling procedure volume expansion in high-throughput practices.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing serialization infrastructure investment across implant and instrument portfolios. Manufacturers serving European markets must integrate traceability systems from production through point-of-use. Implantology segments face the steepest compliance cost given lot-level tracking requirements for permanent placement devices.
Dental service organizations are consolidating procurement authority previously dispersed across individual practitioner decisions. Large DSO platforms in the United States now negotiate enterprise pricing for imaging equipment and consumable bundles. This buyer concentration shifts vendor sales resource allocation toward relationship management and away from traditional territory-based representative models.
Dental Surgical and Diagnostic Devices Market Segmentation
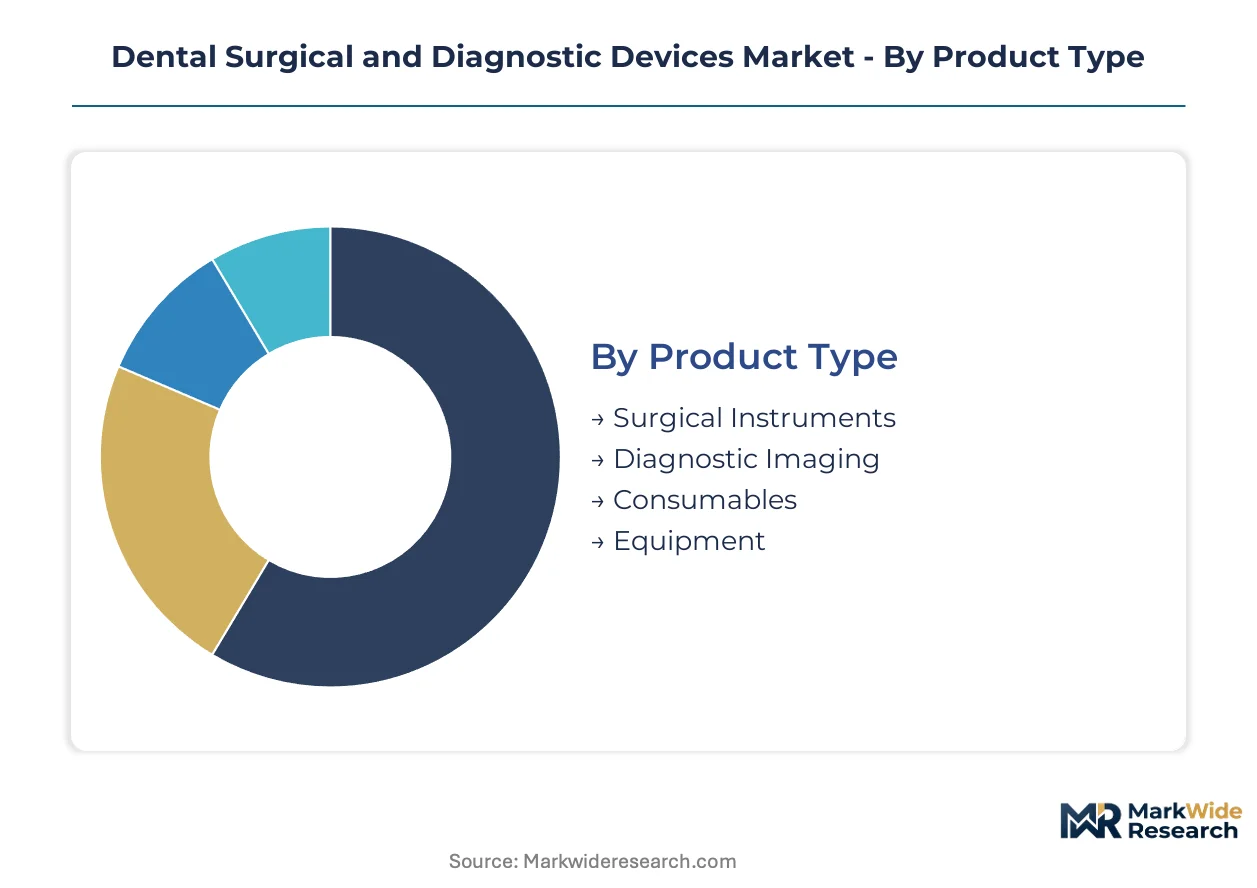
Segmentation in dental surgical and diagnostic devices reveals distinct procurement patterns across clinical settings. Product complexity, sterilization requirements, and software integration needs determine which channels dominate specific categories.
Product Type:
Surgical instruments flow through distributor networks with high service intensity, while diagnostic imaging ships direct from manufacturers requiring installation support. Consumables replenish through group purchasing organizations and dental supply cooperatives.
- Surgical Instruments:Powered handpieces and manual tools fabricated from surgical-grade stainless steel withstand repeated autoclave cycles at 134 degrees Celsius. Demand concentrates in high-volume oral surgery centers across the United States and Germany where procedure throughput drives replacement frequency. German instrument makers leverage regional metallurgy expertise to command premium positioning.
- Diagnostic Imaging:Cone-beam computed tomography systems and intraoral scanners operate within 3-70 kV ranges with software-locked recurring revenue modules. Dental clinics in Japan and the United States deploy these as core service differentiators, with chairside integration driving ceramic block and resin composite attachment sales.
- Consumables:Single-use burs, sutures, and barrier membranes eliminate sterilization logistics for busy practices.
- Equipment:Autoclaves, compressor systems, and operatory furniture complete clinical infrastructure.
By volume, Consumables leads. By growth pace, Diagnostic Imaging is ahead.
Application:
Procedure reimbursement rates and clinical specialization depth shape equipment investment intensity across application areas. Hospital-based oral surgeons deploy capital-intensive navigation systems, while private periodontists prioritize portable diagnostic tools.
- Oral Surgery:Implantology and bone grafting procedures require surgical navigation systems with real-time imaging feedback. Demand clusters in tertiary hospitals across Japan where aging demographics elevate complex case volume. FDA 510(k) clearances for navigation software accelerate product iteration in this segment.
- Periodontics:Ultrasonic scalers and laser systems target soft-tissue management with reduced post-operative recovery. Private practice concentration in Germany drives premium equipment adoption, with ISO 13485-certified manufacturers capturing qualified supplier status.
- Orthodontics:Intraoral scanners and digital treatment planning platforms displace conventional impression workflows.
- Endodontics:Apex locators and rotary instrumentation systems target root canal therapy precision.
Orthodontics shows the steepest expansion trajectory as clear aligner therapy digitizes traditional workflows. Oral Surgery maintains the largest revenue base.
End User:
Procurement authority consolidation distinguishes institutional buyers from independent practitioners. Dental service organizations negotiate enterprise pricing, while solo practitioners rely on distributor relationships and financing programs.
- Dentists:Independent general practitioners balance equipment utility against practice cash flow constraints. These buyers concentrate in suburban United States markets where patient demographics support technology amortization. Equipment financing programs from manufacturers influence purchase timing and brand selection.
- Dental Clinics:Multi-chair facilities achieve scale economies in consumable purchasing and imaging utilization. Chains in Mumbai, Delhi, and Bangalore expand diagnostic capabilities as competitive differentiation, with CDSCO regulatory pathways enabling faster technology deployment than mature jurisdictions.
- Hospitals:Academic medical centers integrate dental surgery within broader surgical service lines.
- Research Laboratories:Universities and material science institutes drive preclinical validation for novel implant surfaces.
Dental Clinics command the highest imaging equipment attachment rate. Dentists represent the largest absolute unit volume for hand instruments.
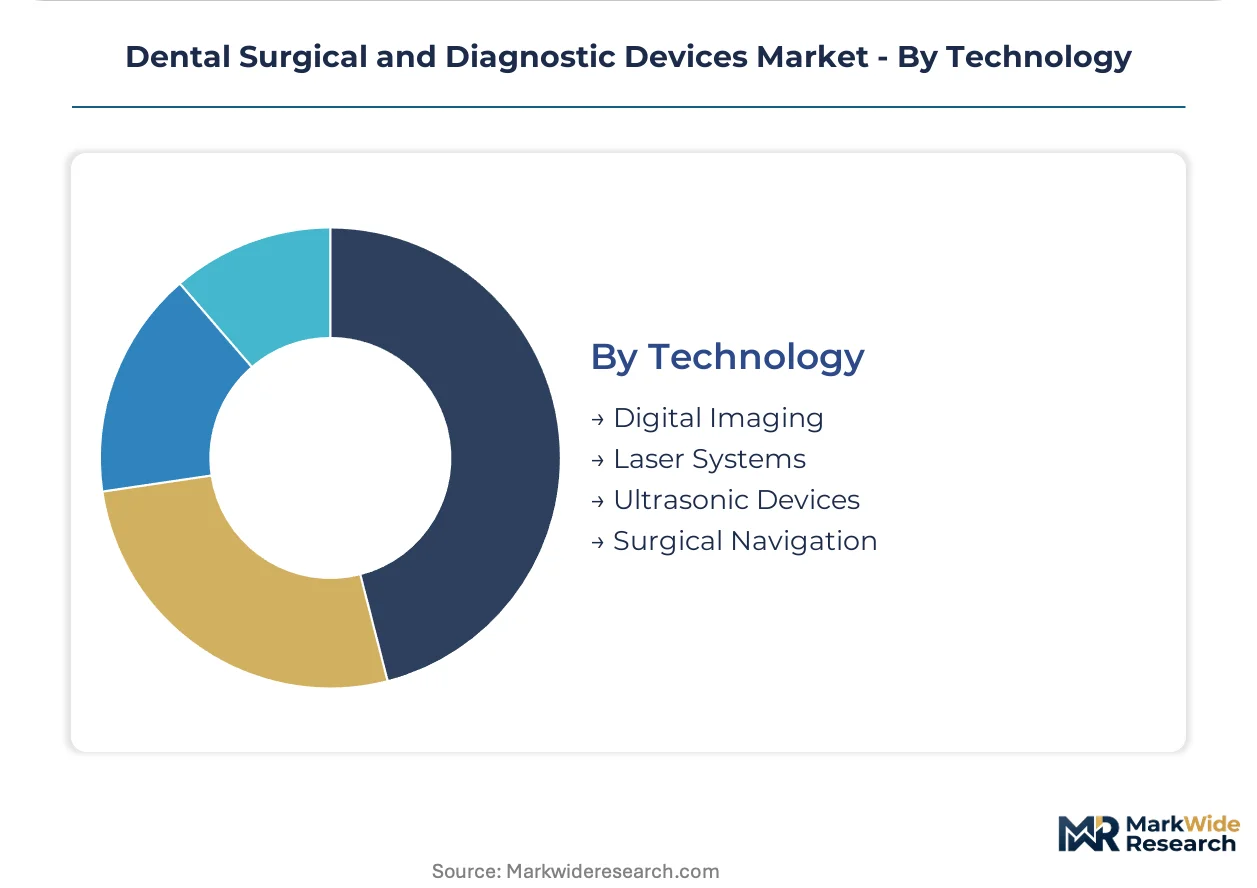
Technology:
Technology maturity curves separate established modalities from emerging platforms requiring clinical evidence accumulation. Digital imaging achieves mainstream penetration while surgical navigation builds specialist adoption.
- Digital Imaging:Intraoral sensors, phosphor plate systems, and cone-beam computed tomography dominate diagnostic workflows. Japanese dental clinics lead adoption density, with PMDA oversight ensuring software validation rigor. AI-assisted radiography modules create recurring revenue attachment through subscription pricing.
- Laser Systems:Erbium and diode wavelengths target soft-tissue procedures with reduced bleeding and faster healing. German manufacturers concentrate production capacity, with EU MDR clinical evidence requirements filtering market entry for new entrants.
- Ultrasonic Devices:Piezoelectric and magnetostrictive systems power scaling and surgical applications.
- Surgical Navigation:Optical and electromagnetic tracking enables implant placement precision in complex anatomies.
Digital Imaging holds the broadest installed base. Surgical Navigation is gaining share fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is redirecting foreign manufacturing investment toward domestic assembly facilities. Germany's MDR implementation timeline continues filtering market entry for smaller instrument makers. Japan's aging demographic structure sustains procedural volume growth across implantology and periodontal surgery.
United States
FDA 510(k) clearance pathways enable rapid product iteration for Class II dental imaging systems. Dental service organizations in Texas and Florida consolidate procurement authority across multi-clinic networks. Henry Schein and Patterson Dental maintain distribution dominance through financing programs targeting independent practitioners.
Germany
EU MDR clinical evidence requirements impose disproportionate compliance burdens on mid-sized instrument manufacturers. Bavarian and Baden-Württemberg industrial clusters concentrate precision metallurgy expertise for surgical-grade stainless steel production. KaVo Kerr and W&H Dentalwerk anchor regional supply chains through ISO 13485-certified fabrication facilities.
Japan
PMDA oversight ensures rigorous software validation for AI-assisted radiography modules entering diagnostic workflows. Tokyo and Osaka dental clinics achieve the highest per-capita cone-beam CT penetration among mature markets. Morita and J. Morita Manufacturing exemplify domestic instrumentation expertise serving aging patient demographics.
India
CDSCO regulatory pathways offer faster market entry timelines relative to FDA or PMDA jurisdictions. Mumbai, Delhi, and Bangalore private clinic chains expand diagnostic imaging capabilities as competitive differentiation. The PLI scheme reduces effective manufacturing costs for foreign companies establishing local assembly operations.
China
NMPA medical device registration requirements intensify clinical trial obligations for imported dental equipment. Yangtze River Delta manufacturing zones concentrate domestic production capacity for consumables and basic instruments. Local champions like Mindray and United Imaging are extending product portfolios into dental-specific diagnostic platforms.
Dental Surgical and Diagnostic Devices Market Vendor Landscape
Player mix skews toward diversified multinationals with integrated digital workflows and specialized regional champions with metallurgy or optics expertise. Market structure exhibits tiered concentration: three to four conglomerates control imaging and CAD/CAM platforms, while surgical instruments fragment across German, Japanese, and Swiss precision manufacturers. Strategic archetypes include workflow-integrated platform providers, component-specialist suppliers, and distributor-anchored service networks. Dominant competitive moves encompass M&A for software capabilities and strategic partnerships for AI-assisted diagnostic modules.
Among workflow-integrated platform providers, Dentsply Sirona and Planmeca Oy occupy positions spanning imaging hardware through chairside milling systems. Envista Holdings Corporation and Danaher Corporation represent the diversified conglomerate archetype, with dental portfolios nested within broader life science or instrumentation umbrellas. These four entities exemplify contrasting strategic postures: pure-play dental focus versus cross-sector resource allocation.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Carestream Health |
| Envista Holdings Corporation |
| Danaher Corporation |
| Planmeca Oy |
| 3M Company |
| KaVo Kerr |
| Ivoclar Vivadent AG |
| Henry Schein |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates supply qualification and price differentiation simultaneously, bifurcating manufacturers into qualified premium suppliers and uncertified cost competitors while dental service organizations exploit this split in enterprise procurement negotiations.
Pricing Analysis
Certification level creates the primary spread between premium ISO 13485-validated instruments and standard-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, metallurgical grade, and software-locked diagnostic modules. Cost compression in economy surgical instruments intensifies because Indian and Chinese manufacturers expand autoclave-compatible polymer production. Independent dentists in suburban United States markets exhibit highest price sensitivity, while Japanese hospital oral surgery departments prioritize performance over unit cost.
Supply Chain Analysis
Inventory lead times for implant-grade titanium extend 16-24 weeks due to aerospace-adjacent metallurgy allocation priorities. Manufacturing concentrates in Germany, Japan, and Switzerland for precision instruments, with China and India expanding consumables fabrication. Feedstock draws from Ukrainian titanium sponge and Chinese rare earth processing for laser system components. Single-source vulnerability concentrates in surgical-grade stainless steel from Baden-Württemberg mills. Distribution runs through Henry Schein and Patterson Dental in North America, regional specialty distributors in Europe, and clinic-direct models for imaging platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as dental service organization procurement consolidation creates tier-two supplier niches for specialized orthodontic and periodontal equipment.
For Market Incumbents: Fortify ISO 13485-certified production capacity in Germany and Japan against emerging Indian PLI-subsidized competitors. Deepen backward integration into titanium feedstock through aerospace metallurgy partnerships to defend margin position from commodity volatility. Lock hospital system partnerships in Tokyo and Osaka through PMDA-validated AI-assisted radiography modules.
For New Entrants and Emerging Players: Chairside 3D-printed surgical guide services represent the service-layer gap where incumbents under-serve high-throughput United States clinic chains. Target Mumbai, Delhi, and Bangalore private clinic expansion with CDSCO-fast-tracked intraoral scanners and localized consumable bundles. Deploy direct sales teams bypassing traditional distributor markups for dental service organization procurement committees.
For Investors and Strategic Acquirers: EU MDR Unique Device Identification mandate reshapes the acquisition landscape toward serialization-ready implant manufacturers. Five-to-ten year viability favors platform-integrated workflow providers over standalone instrument makers. Target mid-cap German and Swiss precision manufacturers with established CE marking infrastructure. Monitor FDA 510(k) clearance velocity for AI-assisted diagnostic modules as inflection indicator for software-locked revenue attachment potential.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks access to German and French hospital procurement frameworks. |
| Hospital System Partnership | Tokyo academic medical centers anchor implantology navigation system validation. |
| Software Companion Development | AI-assisted radiography modules attach recurring revenue to cone-beam CT hardware. |
| Backward Integration | Titanium feedstock control insulates implant margins from aerospace allocation competition. |
| Reimbursement Strategy | CMS coding alignment drives CAD/CAM adoption in United States restorative practices. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dental clinic operators, biomedical engineers, GPO contracts managers, and regulatory affairs leads; and secondary validation through FDA 510(k) filings, PMDA approval databases, CDSCO registration records, hospital procurement databases, and EU MDR notified body certificates. Bottom-up unit economics triangulated against top-down expenditure estimates across the analysis window.
Across the projection horizon, the analytical framework modeled product type, application specialty, end-user procurement authority, and technology maturity curves. CAGRs derived from procedure volume elasticity, equipment replacement cycles, and consumable attachment rates. Forecast inputs incorporated aging demographic indices from Japan, Germany, and the United States alongside dental service organization expansion trajectories in Texas and Florida.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and PMDA oversight regimes; material policy shifts would require re-modeling. Specific risks include titanium supply disruption, MDR clinical evidence timeline extensions, and autoclave sterilization standard revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market