
 Upper GI Series Market | 2026-2036
Upper GI Series Market Size, Share, and Industry Trends Forecast 2026-2036
Upper GI Series Market Analytics
Radiologic technologist specialization in fluoroscopy is bifurcating the competitive landscape, as hospitals with certified GI imaging teams command higher throughput and referral loyalty. GE Healthcare leverages its installed base of remote-controlled fluoroscopy suites to sustain service contract stickiness across academic medical centers. Siemens Healthineers anchors its position through proprietary dual-source X-ray technology that reduces patient dose during barium swallow protocols. Philips Healthcare competes on workflow integration, embedding its GI imaging platforms into enterprise-wide PACS architectures.
An upper GI series encompasses fluoroscopic and radiographic examination of the esophagus, stomach, and duodenum using barium sulfate suspension as a positive contrast medium, typically administered in concentrations of 40-250% w/v depending on anatomical target and suspected pathology. The procedure serves as a first-line structural assessment tool for dysphagia, reflux, and peptic ulcer disease before endoscopic or cross-sectional intervention. Barium swallow formulations dominate product type revenue due to their irreplaceable role in esophageal motility evaluation, while CT scan technology captures the fastest-growing technology segment as facilities hybridize traditional fluoroscopy with low-dose volumetric imaging for complex post-operative assessment. Hospitals absorb the majority of end-user spending, though imaging centers are gaining share through dedicated GI service lines that attract direct-pay and commercially insured volumes.
The FDA governs barium contrast as a prescription drug under 21 CFR, enforcing manufacturing purity and labeling standards that directly determine supplier qualification for institutional purchasing. The EPA regulates barium discharge from imaging facilities under Clean Water Act provisions, adding compliance cost layers that favor centralized hospital-based processing over smaller outpatient sites. Medicare's Physician Fee Schedule and hospital outpatient prospective payment system shape procedure economics, with reimbursement stability or volatility directly influencing capital allocation for fluoroscopy suite upgrades. Stakeholders must monitor whether CMS shifts toward bundled payment models that could compress standalone imaging center margins while rewarding vertically integrated hospital systems.
Market Dynamics
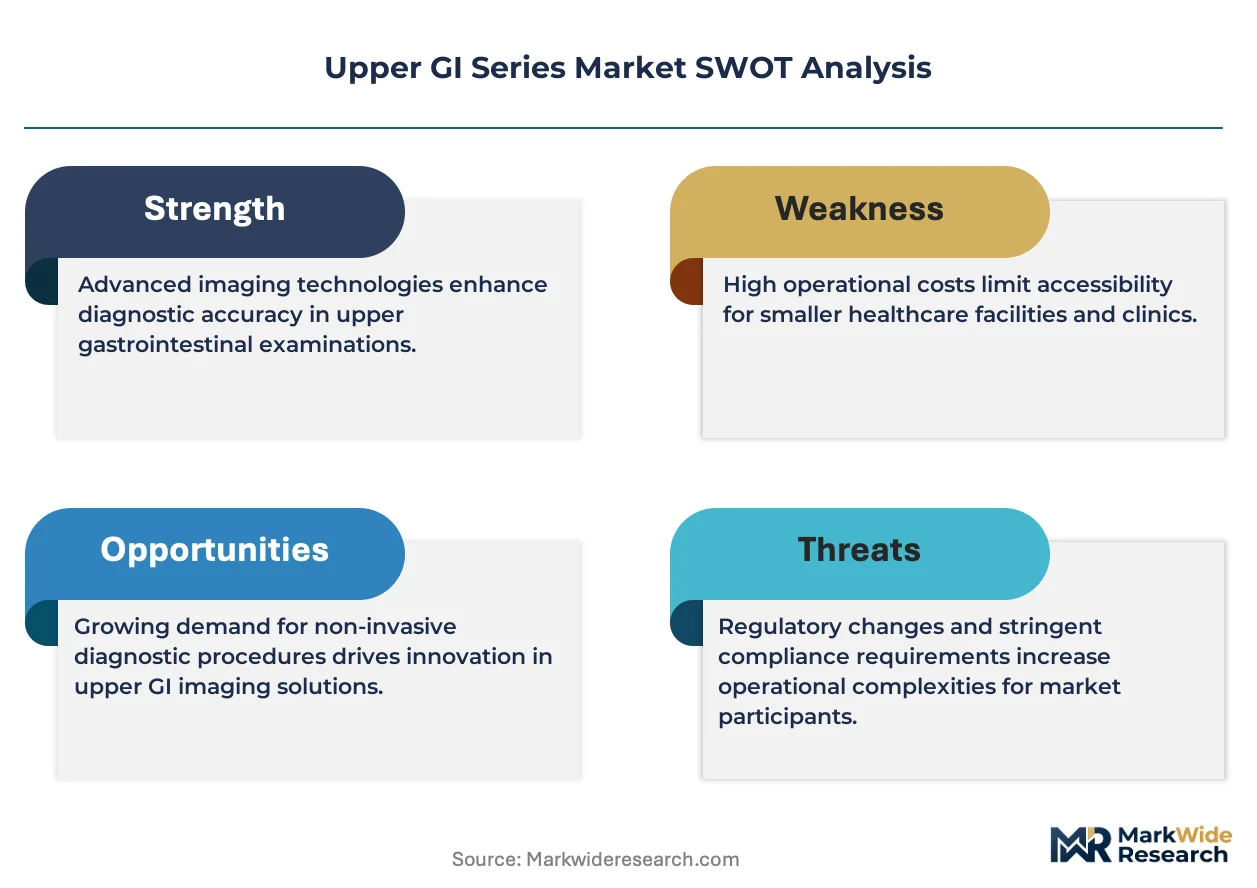
Fluoroscopy-to-CT hybridization is compressing the addressable market for standalone upper GI series procedures as hospitals consolidate imaging pathways around volumetric platforms.
Growth Catalysts
- CMS reimbursement stability:Medicare's hospital outpatient prospective payment system sustains capital allocation for fluoroscopy suite upgrades across United States health systems.
- Barium sulfate purity standards:The FDA's tightened 21 CFR enforcement on radiopharmaceutical contrast agents is consolidating supplier qualification lists toward institutional-scale manufacturers.
- Aging infrastructure replacement:End-of-life fluoroscopy systems in United States academic medical centers are generating replacement demand for remote-controlled suites.
Market Restraints
- Barium supply concentration:Mining and processing of barium sulfate concentrates in China, creating geopolitical exposure for contrast agent formulators.
- EPA discharge compliance:Clean Water Act provisions add centralized processing costs that disadvantage smaller outpatient imaging sites against hospital-based competitors.
- Endoscopic substitution:Therapeutic GI endoscopy is capturing structural assessment volumes previously routed to barium swallow protocols.
Strategic Opportunities
- Imaging center service lines:Dedicated GI-focused outpatient facilities in the United States are attracting commercially insured volumes through direct-pay models.
- Dual-source X-ray convergence:Integration of photon-counting detectors with conventional fluoroscopy platforms enables low-dose motility studies.
- PACS workflow embedding:Enterprise imaging architectures create vendor stickiness through seamless GI study integration with radiology operations.
Industry Challenges
- Radiologic technologist certification gaps:Shortage of fluoroscopy-specialized RTs limits throughput at community hospitals and imaging centers.
- Legacy system integration friction:Retrofitting remote-controlled fluoroscopy suites into existing procedure rooms demands structural modifications and extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Upper GI Series Market |
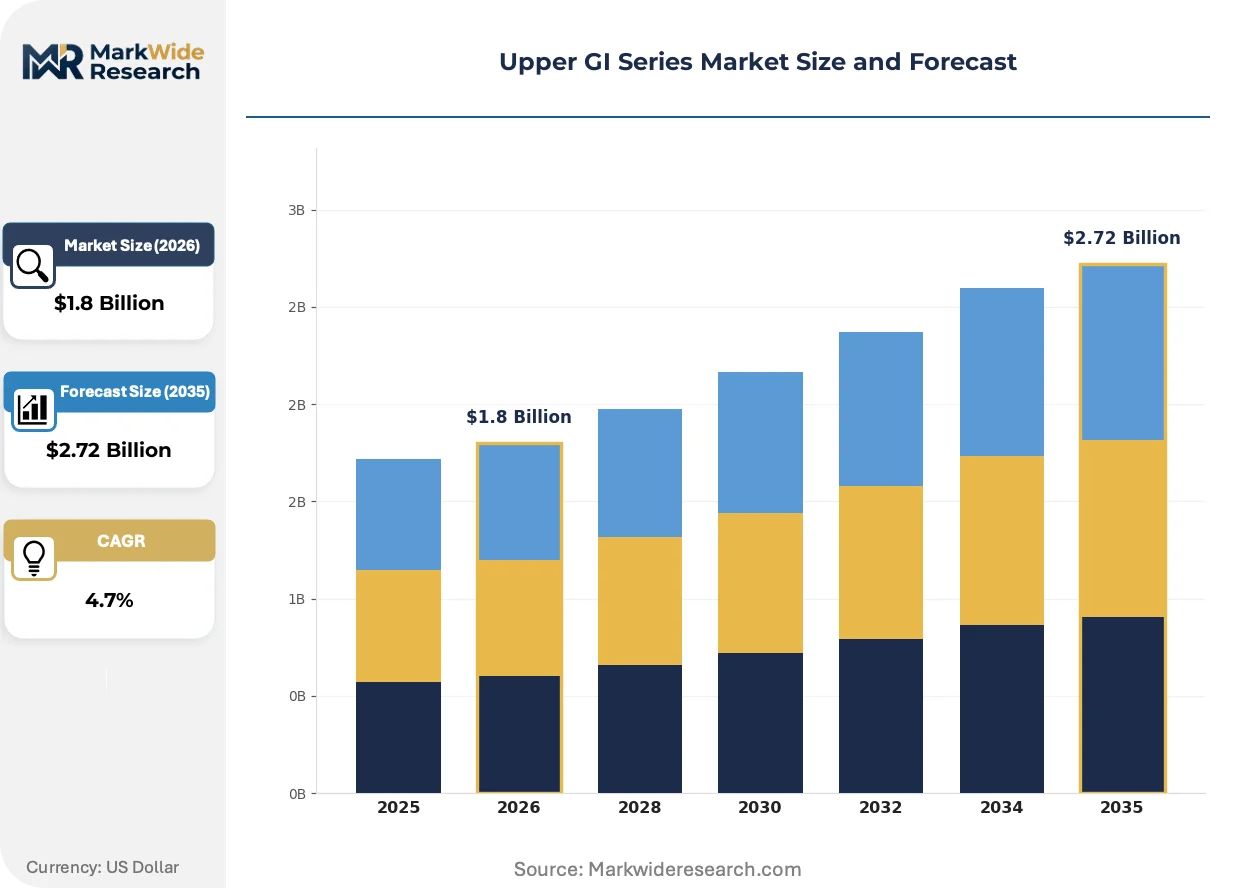
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barium Swallow, Barium Meal, Barium Enema, Radiographic Contrast End User: Hospitals, Imaging Centers, Outpatient Facilities, Clinics Technology: X-ray, CT Scan, MRI, Ultrasound Application: Diagnosis, Screening, Research, Post-operative Assessment |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Eisai Co., Ltd., AstraZeneca, Cadila Pharmaceuticals Limited, Purdue Pharma L.P., Alfa Wassermann, Novadaq Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Upper GI Series Market Evolving Landscape
Digital subtraction fluoroscopy with automated motion correction is compressing examination times while elevating diagnostic yield for esophageal motility disorders.
Photon-counting detector technology is displacing conventional flat-panel fluoroscopy in premium hospital installations. Academic medical centers in the United States are adopting these systems for barium swallow protocols to achieve sub-millisievert dose profiles. The structural consequence is compressing demand for refurbished legacy fluoroscopy suites in secondary markets.
The FDA's updated guidance on radiopharmaceutical contrast purity under 21 CFR is forcing barium sulfate manufacturers to upgrade filtration and quality control infrastructure. This regulatory tightening raises qualification barriers for institutional purchasing contracts. United States hospital systems are responding by consolidating supplier relationships toward vertically integrated chemical processors with captive barium mining operations.
Direct-to-employer contracting for diagnostic imaging is fragmenting traditional referral patterns in the United States. Large self-insured employers are steering dysphagia and reflux workups toward dedicated GI imaging centers with transparent bundled pricing. This channel shift is most visible in Texas, Florida, and North Carolina metropolitan corridors where employer concentration supports standalone service line economics.
Upper GI Series Market Segmentation
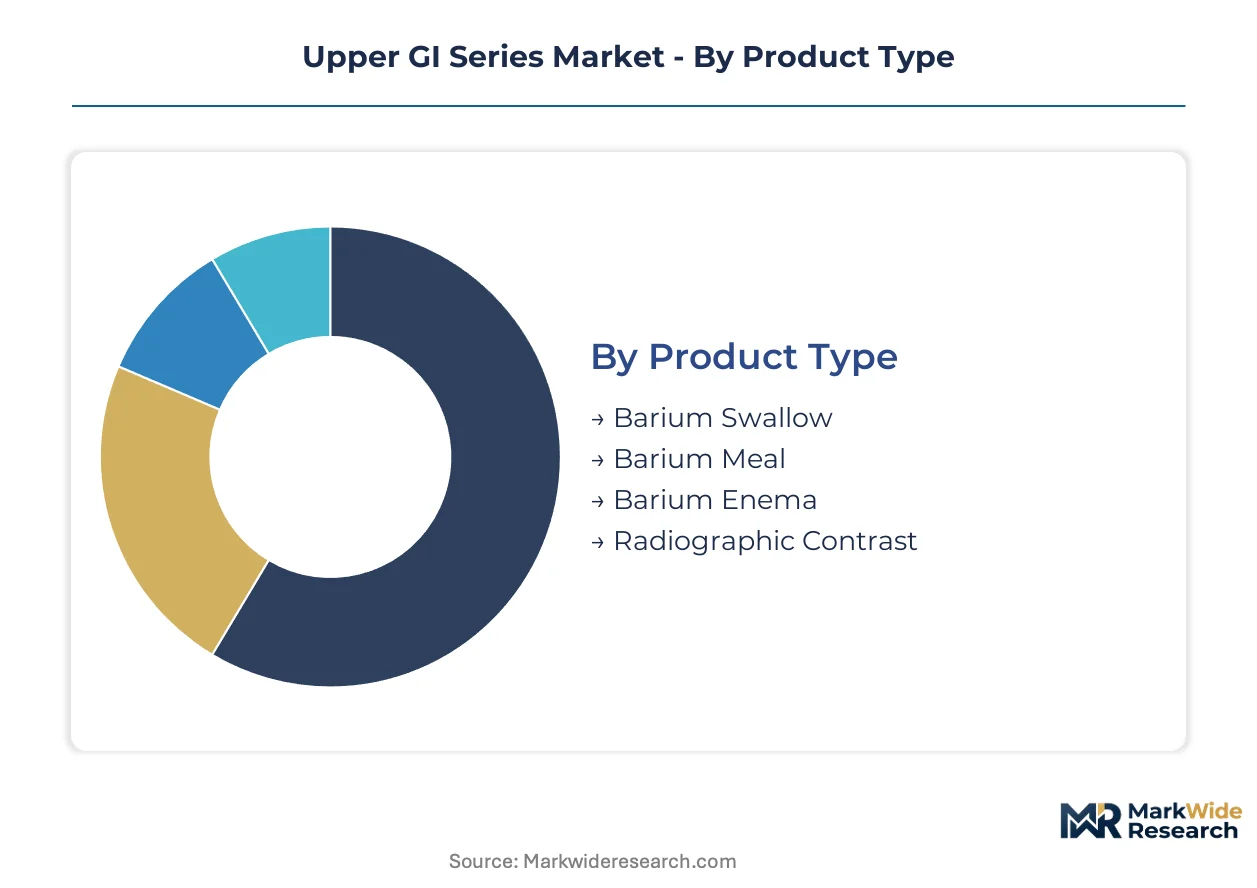
Upper GI series segmentation reveals distinct procurement and utilization patterns across product formulations, care settings, and imaging modalities. Channel dynamics vary sharply between hospital-based fluoroscopy suites and outpatient imaging centers, with reimbursement structures and regulatory compliance costs determining where specific segments concentrate.
Product Type:
Barium sulfate formulations flow through differentiated channels based on concentration specifications and institutional purchasing power, with high-volume hospital systems commanding tiered pricing advantages over smaller outpatient sites.
- Barium Swallow:Aqueous barium sulfate suspension at 40-250% w/v concentration enables real-time fluoroscopic visualization of esophageal motility and structural integrity. Academic medical centers in the United States absorb the majority of volume for dysphagia workups, driven by Medicare reimbursement stability for hospital outpatient procedures.
- Barium Meal:Higher-density formulations coat gastric mucosa for ulcer detection and post-surgical anatomy assessment. Imaging centers with dedicated GI service lines in Texas and Florida metropolitan corridors are capturing commercially insured volumes through direct-pay bundled pricing models.
- Barium Enema:Lower gastrointestinal applications using similar barium sulfate chemistry, though distinct procedural protocols apply.
- Radiographic Contrast:Water-soluble iodinated alternatives for patients with suspected perforation or aspiration risk.
Barium swallow dominates installed base. Barium meal is where expansion concentrates.
End User:
Procurement scale and EPA discharge compliance capabilities create sharp tiering in end-user economics, favoring centralized hospital processing over distributed outpatient networks.
- Hospitals:Integrated health systems leverage fluoroscopy suite density and captive barium processing infrastructure to achieve compliance economies under Clean Water Act provisions. Medicare's hospital outpatient prospective payment system sustains capital allocation for remote-controlled suite upgrades across United States academic medical centers.
- Imaging Centers:Dedicated GI-focused facilities attract direct-pay and commercially insured volumes through transparent pricing and specialized radiologic technologist teams. Employer contracting in North Carolina and Florida corridors is accelerating this channel's expansion.
- Outpatient Facilities:Smaller sites face structural disadvantages from EPA discharge compliance costs and barium supply concentration risks.
- Clinics:Limited fluoroscopy capabilities restrict upper GI series to referral relationships with hospital-based imaging departments.
Hospitals retain procedure volume leadership. Imaging centers are climbing the fastest in revenue share.
Technology:
Capital intensity and dose optimization capabilities segment technology adoption, with premium installations displacing legacy equipment in high-throughput settings.
- X-ray:Conventional fluoroscopy with flat-panel detectors remains the workhorse for barium swallow protocols, though photon-counting systems are gaining traction. Siemens Healthineers' dual-source installations at United States academic medical centers demonstrate sub-millisievert dose profiles that justify premium pricing.
- CT Scan:Low-dose volumetric imaging hybridizes with traditional fluoroscopy for complex post-operative assessment, capturing the steepest expansion trajectory as facilities consolidate imaging pathways around volumetric platforms.
- MRI:Limited upper GI application due to motility imaging constraints and cost barriers.
- Ultrasound:Adjunct role for biliary assessment rather than primary upper GI structural evaluation.
X-ray anchors installed base. CT scan is where technology investment concentrates.
Application:
Clinical utility and reimbursement coding precision determine application segment economics, with diagnostic workups commanding stable volumes against more variable research and screening categories.
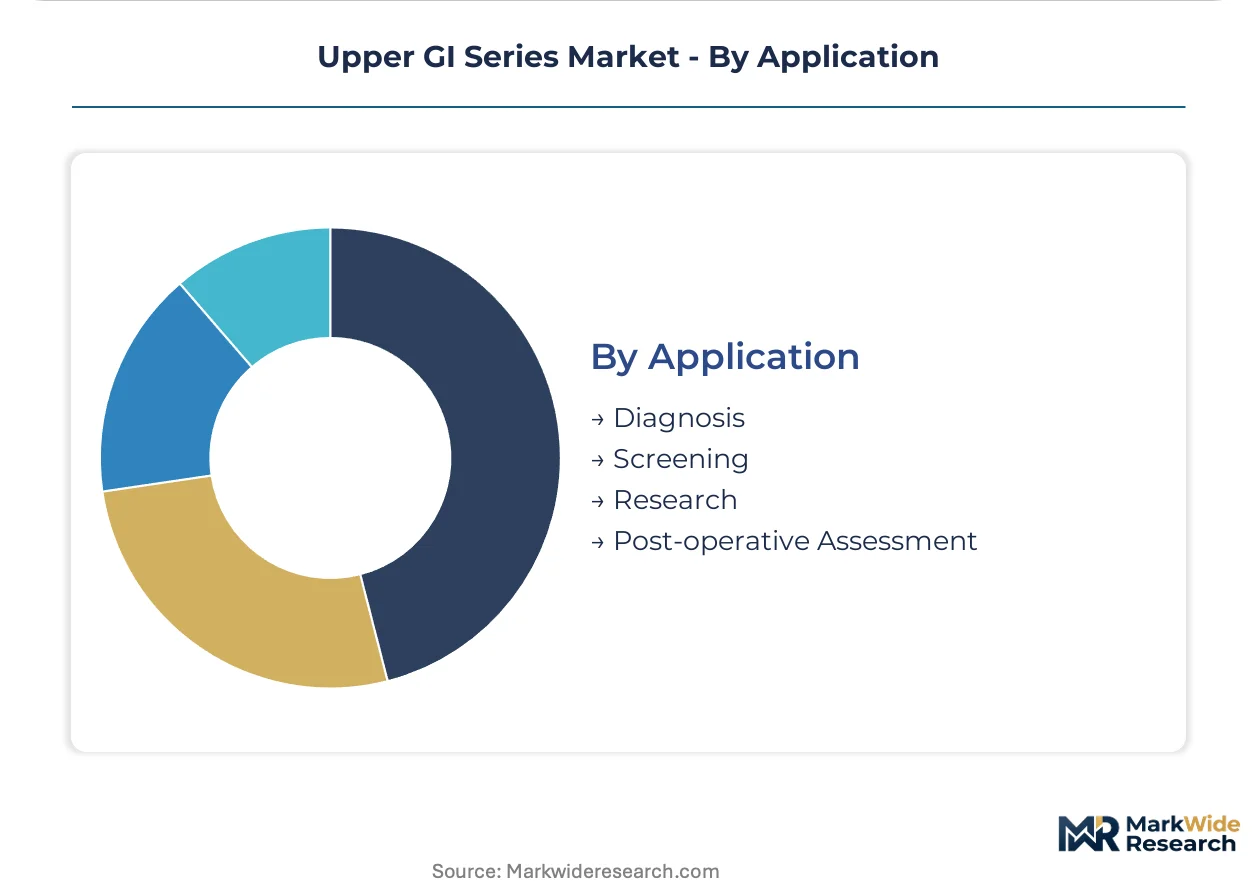
- Diagnosis:First-line structural assessment for dysphagia, reflux, and peptic ulcer disease generates predictable demand from gastroenterology referrals. Medicare fee schedule stability supports consistent procedure economics across United States hospital systems.
- Screening:Population-level programs face substitution pressure from therapeutic endoscopy for structural assessment, compressing growth potential.
- Research:Academic protocols for esophageal motility disorders drive specialized fluoroscopy utilization with dedicated funding streams.
- Post-operative Assessment:Anastomotic leak evaluation and gastric bypass anatomy confirmation utilize hybrid CT-fluoroscopy protocols in surgical centers.
Diagnosis dominates procedure volume. Post-operative assessment is where imaging complexity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States deploys upper GI series predominantly within hospital outpatient departments under stable Medicare reimbursement, while Germany and Japan concentrate procedures in specialized endoscopy centers with tighter regulatory scrutiny on contrast agent purity.
United States
Hospital outpatient departments absorb the majority of fluoroscopic upper GI volume, driven by Medicare's hospital outpatient prospective payment system. The FDA enforces barium sulfate purity standards under 21 CFR, consolidating supplier relationships toward institutional-scale manufacturers. Texas and Florida metropolitan corridors host expanding dedicated GI imaging centers that attract commercially insured volumes through direct-pay bundled pricing.
Germany
Academic medical centers anchor procedure volume, with dual-source X-ray technology penetrating premium installations for dose-optimized barium swallow protocols. The EMA's medical device regulation framework shapes procurement requirements for fluoroscopy suite upgrades. Bavaria and North Rhine-Westphalia concentrate replacement demand as aging infrastructure reaches end-of-life across university hospital networks.
Japan
Specialized endoscopy centers capture structural assessment volumes that substitute for traditional barium swallow protocols in dysphagia workups. PMDA oversight of radiopharmaceutical contrast agents maintains stringent manufacturing quality standards. The Kanto region around Tokyo sustains the highest fluoroscopy suite density, with Kansai academic centers piloting photon-counting detector integration.
China
Barium sulfate supply concentration creates upstream exposure, with mining and processing capacity centered domestically. NMPA regulation of medical contrast agents is tightening purity certification requirements for institutional purchasers. Yangtze River Delta hospital systems are consolidating imaging pathways around hybrid CT-fluoroscopy platforms for complex post-surgical assessment.
United Kingdom
NHS reimbursement frameworks compress standalone imaging center economics, favoring vertically integrated hospital system provision. The MHRA governs barium contrast as a prescription medicine under parallel regulatory tracks to EU standards. London and Southeast England academic centers maintain fluoroscopy specialization teams that command higher throughput and referral loyalty.
Upper GI Series Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational imaging equipment manufacturers commanding service contract stickiness through installed base density. The specialist tier comprises regional contrast agent formulators and dedicated fluoroscopy technology vendors. Three archetypes define competitive positioning: full-suite imaging platform providers, barium sulfate chemical processors with captive supply chains, and niche workflow software integrators. Consolidation through strategic partnerships and backward integration into contrast agent manufacturing represent the dominant competitive moves reshaping vendor relationships.
Among full-suite imaging platform providers, GE Healthcare, Siemens Healthineers, and Philips Healthcare occupy positions that exemplify divergent technology anchoring strategies. GE Healthcare leverages remote-controlled fluoroscopy suite density across United States academic medical centers to sustain long-term service agreements. Siemens Healthineers anchors its market presence through proprietary dual-source X-ray installations that reduce patient dose during barium swallow protocols. Philips Healthcare competes on enterprise workflow integration, embedding GI imaging platforms into hospital-wide PACS architectures that create switching costs for radiology operations.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Eisai Co., Ltd. |
| AstraZeneca |
| Cadila Pharmaceuticals Limited |
| Purdue Pharma L.P. |
| Alfa Wassermann |
| Novadaq Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Water-soluble iodinated alternatives displacing barium sulfate in perforation-risk cases are redrawing procurement geography toward pharmaceutical-grade chemical processors while compressing pricing power among legacy mining-dependent formulators. This substitution dynamic simultaneously elevates FDA 21 CFR compliance costs and fragments buyer concentration across hospital systems and dedicated GI imaging centers.
Pricing Analysis
Long-term offtake agreements dominate hospital system procurement, with tiered contracts separating academic medical centers securing volume discounts from imaging centers paying spot-equivalent premiums. Price differentiation hinges on barium sulfate purity certification under FDA 21 CFR and bundled service contract density from fluoroscopy suite manufacturers. Cost compression in standard-grade formulations is intensifying because EPA discharge compliance adds centralized processing overhead. Community hospitals exhibit highest price sensitivity due to capital constraint, while integrated health systems leverage scale for locked-in pricing.
Supply Chain Analysis
Inventory buffers for high-purity barium sulfate extend lead times for institutional purchasers qualifying under tightened FDA filtration standards. Mining and processing concentrates in China, with secondary chemical refinement capacity in Germany and the United States. Raw material dependencies include barite ore extraction, sulfuric acid processing, and pharmaceutical-grade filtration media. Single-source vulnerability concentrates in Chinese mining operations. Distribution runs through institutional-scale chemical processors with captive vertical integration into hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital systems and self-insured employers steering volume to dedicated GI imaging centers, fragmenting traditional referral channels and compressing standalone outpatient site economics.
For Market Incumbents: Consolidate service contract density across remote-controlled fluoroscopy installed bases to defend against photon-counting detector substitution from Siemens Healthineers and GE Healthcare. Deepen backward integration into barium sulfate chemical processing to secure FDA 21 CFR qualification advantages. Lock in radiologic technologist certification pipelines to sustain throughput differentiation against imaging center competitors. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for photon-counting detector retrofits open white-space in community hospital fluoroscopy suite upgrades. Target employer-direct contracting corridors in Texas and Florida metropolitan clusters where transparent bundled pricing attracts commercially insured dysphagia volumes. Pursue software workflow integration with enterprise PACS architectures as primary go-to-market wedge against hardware incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed imaging center platforms in the United States Southeast and Southwest corridors ripe for roll-up consolidation. Five-to-ten year viability hinges on reimbursement stability under CMS hospital outpatient prospective payment system evolution. Watch for CMS bundled payment model shifts as inflection signal compressing standalone imaging center margins while rewarding vertically integrated hospital systems.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Integration | Sub-millisievert dose profiles justify premium pricing at academic medical centers. |
| Backward Integration into Barium Processing | Captive supply chains secure FDA 21 CFR qualification barriers against competitors. |
| Enterprise PACS Workflow Embedding | Seamless GI study integration creates switching costs for radiology operations. |
| Direct-to-Employer Contracting | Transparent bundled pricing attracts commercially insured volumes in Texas and Florida. |
| Radiologic Technologist Certification Pipeline | Specialized fluoroscopy teams command higher throughput and referral loyalty. |
Research Methodology
Operator-level perspectives from radiologic technologists, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 21 CFR filings, CMS Medicare reimbursement databases, hospital procurement records, and EPA Clean Water Act compliance disclosures. Bottom-up procedure volume modeling triangulated against top-down capital expenditure tracking across fluoroscopy suite installations.
Sensitivity analysis tested forecast robustness across reimbursement scenario variants and barium sulfate supply disruption assumptions. Segmentation dimensions spanned product formulation concentration tiers, end-user facility scale categories, technology modality types, and regional regulatory clusters. CAGRs derived from installed base replacement cycles and procedure volume elasticity to Medicare fee schedule adjustments. Forecast inputs incorporated photon-counting detector adoption curves and employer-direct contracting penetration rates.
Underlying assumptions cover CMS reimbursement stability, EPA discharge compliance cost trajectories, and barium mining supply continuity, with deviation risk concentrated in geopolitical disruption to Chinese processing capacity and regulatory tightening under FDA updated guidance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market