
 Global Therapeutic Plasma Exchange Market | 2026-2036
Global Therapeutic Plasma Exchange Market Size, Share, and Industry Trends Forecast 2026-2036
Global Therapeutic Plasma Exchange Market Foresight
Multi-source procurement for membrane filtration components is pivoting toward vertically integrated supply chains among top device manufacturers. Fresenius Medical Care leverages captive polymer sourcing to secure filter membrane consistency across European and Asian production lines. Haemonetics Corporation anchors its competitive stance through dedicated apheresis platform R&D, while Asahi Kasei Medical differentiates via specialized hollow-fiber technology for selective plasma separation.
Therapeutic plasma exchange denotes an extracorporeal blood purification procedure that removes pathogenic antibodies, immune complexes, and inflammatory mediators through centrifugal or membrane-based separation, typically processing 1.0–1.5 plasma volumes per session to treat autoimmune and hematologic conditions. Plasma filters command the largest product-type revenue pool due to recurring replacement cycles and stringent sterility requirements, whereas outpatient deployment mode exhibits the fastest structural expansion as payors push procedure migration from inpatient settings. Neurological applications, particularly myasthenia gravis and chronic inflammatory demyelinating polyneuropathy, concentrate margin-rich procedural volumes in tertiary referral centers.
FDA device clearance pathways and EMA's Medical Device Regulation reshape product development timelines and clinical evidence requirements for membrane-based exchange systems. Japan's PMDA enforces distinct biocompatibility testing protocols that influence regional product configurations. Stakeholders must monitor evolving reimbursement thresholds for outpatient therapeutic plasma exchange as payor pressure intensifies across major health systems.
Market Dynamics
Outpatient migration is compressing inpatient procedural volumes as payors across Germany, Japan, and the United States enforce site-of-care differentials that redirect therapeutic plasma exchange toward ambulatory settings.
Growth Catalysts
- Autoimmune disease prevalence:Rising diagnostic capture rates for myasthenia gravis and chronic inflammatory demyelinating polyneuropathy expand addressable patient pools in tertiary referral networks.
- FDA plasma collection standards:Evolving donor eligibility and collection protocols strengthen supply security for source plasma used in exchange procedures.
- Membrane filtration advances:Hollow-fiber biocompatibility improvements reduce treatment-related adverse events and extend session tolerability.
Market Restraints
- Specialized polymer supply concentration:Filter membrane feedstock production clusters in select Asian chemical manufacturing zones, creating input vulnerability.
- EMA Medical Device Regulation compliance costs:Clinical evidence requirements for membrane-based exchange systems extend development timelines and elevate registration expenditures.
- Trained apheresis specialist scarcity:Limited certification programs for operating centrifugal and membrane separation equipment constrain procedural capacity expansion.
Strategic Opportunities
- Underpenetrated neurological indications:Acute disseminated encephalomyelitis and neuromyelitis optica spectrum disorder represent expansion targets with limited established treatment protocols.
- Japan PMDA biocompatibility pathway:Distinct testing protocols create first-mover advantage potential for manufacturers configuring region-specific device submissions.
- Home-based exchange service models:Portable separation technology convergence with remote monitoring infrastructure enables care delivery outside traditional clinical settings.
Industry Challenges
- Apheresis nurse and technician certification pipelines:Extended training durations and limited program slots throttle workforce scaling to match procedural demand.
- Legacy health information system integration:Exchange platforms require custom interfacing with hospital electronic medical records and laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Therapeutic Plasma Exchange Market |
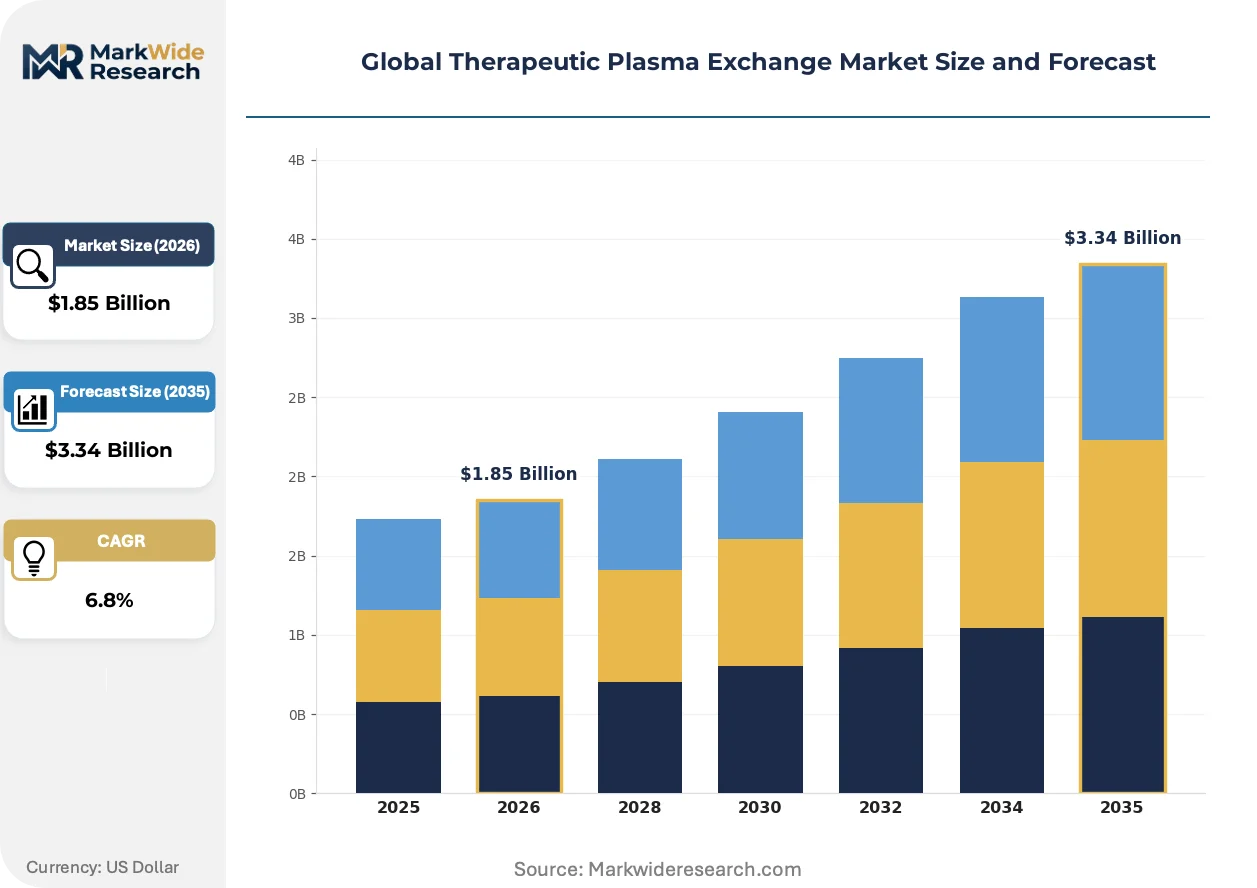
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasma Filters, Adsorbers, Separators, Tubing Sets, Replacement Fluids Application: Neurological Disorders, Autoimmune Diseases, Hematologic Conditions, Transplantation Support, Metabolic Disorders End User: Hospitals, Specialty Clinics, Blood Banks, Research Institutes Deployment Mode: Inpatient, Outpatient, Home Care, Ambulatory Care |
| Companies Covered | Baxter International, B. Braun Melsungen AG, Fresenius Medical Care, Kaneka Corporation, Grifols S.A., Terumo BCT, Asahi Kasei Medical, Cerus Corporation, Haemonetics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Therapeutic Plasma Exchange Market Shifts & Advancements
Device architecture is fragmenting into configurable subsystems that permit indication-specific customization without full platform replacement, while regulatory evidence requirements harden across major jurisdictions.
Membrane cartridge design is modularizing around standardized connector geometries that permit mixing of filtration, adsorption, and selective separation modules within single treatment sessions. Academic medical centers in the United States and Germany are piloting these configurable arrays for complex multi-pathology presentations. This architecture is modularizing capital deployment by allowing incremental capability expansion rather than full system replacement.
EMA's Medical Device Regulation mandates clinical performance studies for Class III active therapeutic devices that process blood or plasma, forcing manufacturers to generate procedure-specific safety and effectiveness data. Japanese PMDA biocompatibility testing protocols diverge from ISO 10993 standards in cytotoxicity and hemocompatibility endpoints. European manufacturers are responding with parallel-track development programs that isolate regional regulatory dossiers.
Hospital purchasing consortia are consolidating procurement authority for apheresis platforms and disposables, displacing individual facility negotiations with multi-year enterprise agreements. Group purchasing organizations in the United States now dominate membrane filter and tubing set acquisition for integrated delivery networks. This concentration is most visible in tertiary referral centers where procedural volumes justify dedicated supply chain investment.
Global Therapeutic Plasma Exchange Market Segmentation
Segmentation in therapeutic plasma exchange reveals distinct capital requirements, reimbursement pathways, and clinical workflows that shape vendor go-to-market strategies. Understanding these divides enables targeted platform configurations and supply chain positioning.
Product Type:
Capital intensity varies sharply across this category, with membrane manufacturing and sterilization infrastructure demanding the heaviest upfront investment.
- Plasma Filters:Hollow-fiber membrane cartridges with pore sizes calibrated for selective immunoglobulin removal. Demand concentrates in German and Japanese tertiary centers where high procedural volumes justify premium filter procurement. Recurring replacement cycles and stringent sterility requirements anchor revenue concentration here.
- Adsorbers:Selective ligand-immobilized columns that capture specific pathogenic antibodies without full plasma volume exchange. United States academic medical centers are piloting these for complex multi-pathology presentations where standard filtration proves insufficient.
- Separators:Centrifugal or membrane-based units that isolate plasma from cellular blood components.
- Tubing Sets:Single-use disposable circuits connecting patient vasculature to separation hardware.
- Replacement Fluids:Albumin solutions and fresh frozen plasma formulations that restore volume post-exchange.
Plasma Filters absorb the bulk of installed capacity; Adsorbers are expanding most quickly.
Application:
Reimbursement tiers and procedure complexity create divergent margin profiles across clinical indications.
- Neurological Disorders:Myasthenia gravis and chronic inflammatory demyelinating polyneuropathy dominate tertiary referral volumes. United States centers report the steepest expansion trajectory as diagnostic capture rates improve and outpatient protocols mature.
- Autoimmune Diseases:Systemic lupus erythematosus and antineutrophil cytoplasmic antibody-associated vasculitis drive protocol standardization efforts. German hospital networks are consolidating these procedures into dedicated apheresis units.
- Hematologic Conditions:Thrombotic thrombocytopenic purpura and cryoglobulinemia requiring urgent plasma exchange.
- Transplantation Support:Desensitization protocols and antibody-mediated rejection management.
- Metabolic Disorders:Familial hypercholesterolemia and acute liver failure bridging interventions.
Neurological Disorders command the highest reimbursement rates; Autoimmune Diseases show the steepest volume climb.
End User:
Procurement authority and capital deployment timelines segment distinctly across facility types.
- Hospitals:Integrated delivery networks in the United States and Germany dominate capital equipment purchasing through multi-year enterprise agreements. These institutions house the majority of high-volume apheresis platforms and captive specialist workforces.
- Specialty Clinics:Dedicated neurological and autoimmune centers in Japan are expanding outpatient capacity. PMDA biocompatibility certifications influence device selection at these facilities more than at hospital systems.
- Blood Banks:Collection and processing infrastructure for source plasma used in exchange procedures.
- Research Institutes:Academic medical centers piloting modular cartridge configurations and selective separation protocols.
Hospitals retain the largest installed base; Specialty Clinics are gaining share fastest.
Deployment Mode:
Site-of-care economics and payor pressure are restructuring where procedures occur.
- Outpatient:Ambulatory infusion centers with dedicated apheresis nursing staff. United States payor site-of-care differentials are compressing inpatient volumes and redirecting routine exchanges to lower-cost settings.
- Inpatient:Acute care units managing unstable patients or complex multi-organ involvement. German DRG frameworks still favor hospital-based delivery for high-acuity cases.
- Home Care:Portable separation technology with remote monitoring infrastructure enabling care outside traditional clinical settings.
- Ambulatory Care:Same-day surgical centers and standalone dialysis facilities adding apheresis capability.
Inpatient retains the highest acuity caseload; Outpatient is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for therapeutic plasma exchange concentrates in Germany, Japan, and the United States, where tertiary referral networks and payor restructuring redirect procedural volumes toward ambulatory settings. Regulatory divergence across FDA, EMA, and PMDA jurisdictions shapes device certification pathways and regional product configurations.
United States
Academic medical centers in Boston and Houston pilot modular cartridge arrays for complex neurological presentations. FDA device clearance pathways for membrane-based exchange systems mandate procedure-specific clinical evidence. Integrated delivery networks in the Southeast consolidate procurement authority through multi-year enterprise agreements with group purchasing organizations.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia consolidate autoimmune disease protocols into dedicated apheresis units. EMA Medical Device Regulation compliance costs extend development timelines for Class III active therapeutic devices. The Rhine-Ruhr metropolitan cluster houses concentrated membrane manufacturing infrastructure serving European production lines.
Japan
Specialty clinics in Tokyo and Osaka expand outpatient capacity for myasthenia gravis and chronic inflammatory demyelinating polyneuropathy. PMDA enforces distinct biocompatibility testing protocols diverging from ISO 10993 standards in cytotoxicity endpoints. Kansai-based manufacturers configure region-specific device submissions to capture first-mover certification advantages.
United Kingdom
Tertiary centers in London and Manchester concentrate margin-rich procedural volumes for hematologic conditions requiring urgent plasma exchange. The Medicines and Healthcare products Regulatory Agency aligns with EMA frameworks while maintaining national vigilance reporting requirements. The Oxford-Cambridge corridor anchors research institute pilot programs for selective separation protocols.
Switzerland
Swissmedic certification requirements influence premium-tier device selection at university hospitals in Zurich and Geneva. The Basel pharmaceutical cluster supports specialized polymer sourcing relationships for filter membrane feedstock. Alpine referral networks manage cross-border patient flows from neighboring jurisdictions seeking high-acuity exchange procedures.
Global Therapeutic Plasma Exchange Market Competitive Landscape
Strategic partnerships dominate the current landscape as device manufacturers secure captive polymer supply and apheresis platform interoperability. The vendor base concentrates around vertically integrated multinational corporations with dedicated membrane manufacturing infrastructure, mid-scale specialists in hollow-fiber technology, and regional platform assemblers serving national health systems. Three archetypes define positioning: integrated filtration-to-therapy providers, selective separation technology specialists, and modular subsystem configurators. M&A activity and capacity expansion in Asian chemical manufacturing zones represent the dominant competitive moves reshaping supply security.
Among integrated filtration-to-therapy providers, Fresenius Medical Care and Haemonetics Corporation exemplify divergent strategic postures. Fresenius anchors European and Asian production lines through captive polymer sourcing for filter membrane consistency. Haemonetics occupies a position emphasizing dedicated apheresis platform research and development. Asahi Kasei Medical sits within the selective separation specialist tier, representing Japanese hollow-fiber technology differentiation for plasma separation applications.
| Leading Market Players |
|---|
| Baxter International |
| B. Braun Melsungen AG |
| Fresenius Medical Care |
| Kaneka Corporation |
| Grifols S.A. |
| Terumo BCT |
| Asahi Kasei Medical |
| Cerus Corporation |
| Haemonetics Corporation |
| Others |
Supply & Pricing Matrix
Polypropylene resin price indices in Asian chemical manufacturing zones cascade through membrane filtration component costs, compressing margins for standard-grade plasma filters while premium hollow-fiber cartridges retain pricing power through captive polymer sourcing arrangements.
Pricing Analysis
High-volume plasma filter replacements generate thin margins for disposable manufacturers, whereas selective adsorber cartridges capture substantial premiums through indication-specific ligand engineering. Pricing stratifies across premium, standard, and economy tiers based on FDA clearance tier and hollow-fiber biocompatibility certification grade. Cost compression in standard filtration runs through group purchasing organization consolidation, while pricing softness reflects payor site-of-care differentials redirecting procedures toward outpatient settings. Academic medical centers demonstrate lowest price sensitivity due to protocol standardization requirements; standalone specialty clinics exhibit highest sensitivity to per-procedure disposable costs.
Supply Chain Analysis
Certified apheresis technician shortages in German and Japanese manufacturing zones constrain sterilization facility throughput and extend lead times for finished membrane cartridges. Filter membrane feedstock production clusters in South Korean and Chinese chemical zones, creating single-source vulnerability for specialized polymer formulations. Hollow-fiber spinning equipment and ethylene-vinyl alcohol copolymer resins feed from concentrated Asian suppliers, with tariff exposure on medical-grade polymers threatening margin stability. Distribution runs through hospital purchasing consortia and group purchasing organizations that displace direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained apheresis specialist scarcity props pricing for procedure-capable facilities, creating durable margin pools for operators that resolve workforce bottlenecks faster than competitors.
For Market Incumbents: Acquire hollow-fiber membrane manufacturing assets to secure polymer supply consistency against emerging Asian chemical conglomerates expanding into medical-grade filtration. Deepen backward integration into ethylene-vinyl alcohol copolymer resin sourcing to defend against feedstock concentration risk. Invest in PMDA biocompatibility certification pipelines to capture first-mover advantage in Japanese outpatient clinic expansion. For New Entrants and Emerging Players: Begin with home-based exchange service models leveraging portable separation technology convergence, as regulatory frameworks for remote monitoring infrastructure remain underdeveloped and penetrable. Target acute disseminated encephalomyelitis and neuromyelitis optica spectrum disorder indications where established treatment protocols are sparse. Pursue hospital system partnership structures that outsource apheresis capacity rather than compete for capital equipment procurement. For Investors and Strategic Acquirers: The window for entry favors selective separation technology specialists with PMDA-certified hollow-fiber platforms and established Japanese distribution. Long-term viability rests on capturing outpatient migration economics before payor site-of-care differentials fully mature. Monitor FDA device clearance pathway evolution for membrane-based exchange systems as the inflection signal indicating regulatory barrier height.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Sourcing | Fresenius Medical Care secures filter membrane consistency across European and Asian production lines. |
| PMDA Biocompatibility Certification | First-mover manufacturers capture Japanese outpatient clinic expansion before competitors complete testing protocols. |
| Modular Cartridge Development | Academic medical centers in Boston and Germany pilot configurable arrays for complex multi-pathology presentations. |
| Apheresis Workforce Expansion | Extended training programs address certified technician scarcity constraining procedural capacity growth. |
| Outpatient Service Model Buildout | United States payor site-of-care differentials compress inpatient volumes and redirect routine exchanges. |
Research Methodology
FDA 510(k) filings, EMA Medical Device Regulation submission databases, and Japanese PMDA approval records formed the secondary backbone for device certification pathway mapping. Primary interviews with apheresis unit directors, biomedical engineers, hospital purchasing committee members, and group purchasing organization contract managers validated procedural volume and procurement pattern assumptions. Bottom-up modeling of membrane filter replacement cycles and top-down triangulation against tertiary center capacity estimates produced convergent market sizing.
Historical procedural volume trendlines across neurological and autoimmune indications informed the analytical framework over the projection horizon. Segmentation dimensions included product type, application, end user, and deployment mode, with regional regulatory cluster variations modeled separately. CAGRs derived from installed base expansion rates and per-procedure disposable consumption patterns, incorporating FDA plasma collection standard evolution and payor reimbursement threshold shifts as structural inputs.
Underlying measurement precision varies by segment; outpatient deployment mode and plasma filter product type carry tighter precision than home care and adsorber categories due to data availability. Forecasts reflect documented assumptions regarding PMDA certification timelines, EMA MDR compliance cost trajectories, and specialist workforce training program scaling. Material deviation in FDA device clearance pathway stringency or apheresis nurse certification pipeline throughput warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Therapeutic Apheresis Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market