
 Disposable Negative Pressure Wound Therapy Devices Market | 2026-2036
Disposable Negative Pressure Wound Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Negative Pressure Wound Therapy Devices Market Analysis
Hospital procurement is reconfiguring around value-based contracts that bundle disposable NPWT canisters with service-level guarantees. Smith & Nephew leverages its direct sales force to control large integrated delivery network accounts in North America. 3M anchors its position through material science leadership in adhesive drape technologies that reduce skin trauma during dressing changes. Mölnlycke Health Care differentiates via vertical integration into foam substrate manufacturing, securing supply continuity for European hospital systems.
Disposable negative pressure wound therapy devices are closed-loop systems comprising a vacuum pump, exudate collection canister, and occlusive dressing that apply subatmospheric pressure to wound beds to accelerate granulation tissue formation and reduce edema. Single-use devices dominate hospital procurement due to infection control protocols, while portable battery-powered systems represent the fastest-growing technology segment as home healthcare reimbursement expands. Chronic wounds command the largest application share driven by diabetic foot ulcer and pressure injury incidence, though surgical wound applications carry higher per-procedure margins due to bundled pricing in ambulatory settings.
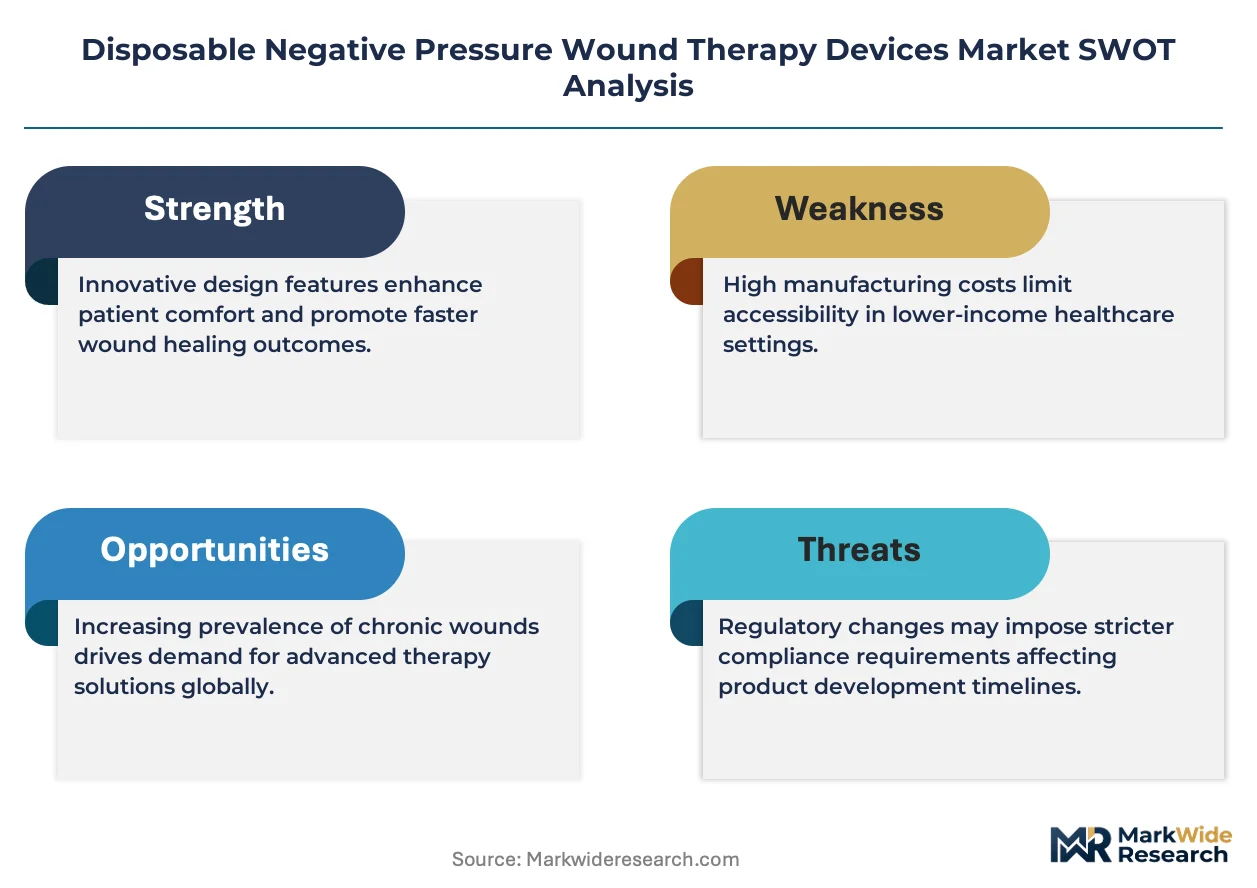
The FDA regulates these devices as Class II medical devices under 21 CFR 878.4780, requiring 510(k) clearance for new pump technologies and driving compliance costs that favor established manufacturers with regulatory infrastructure. The EU MDR transition imposes stricter clinical evidence requirements on wound care devices, creating market access barriers for smaller entrants lacking notified body relationships. Stakeholders must monitor reimbursement parity between disposable and traditional NPWT systems across Medicare Advantage plans and commercial payers as this determines home segment profitability.
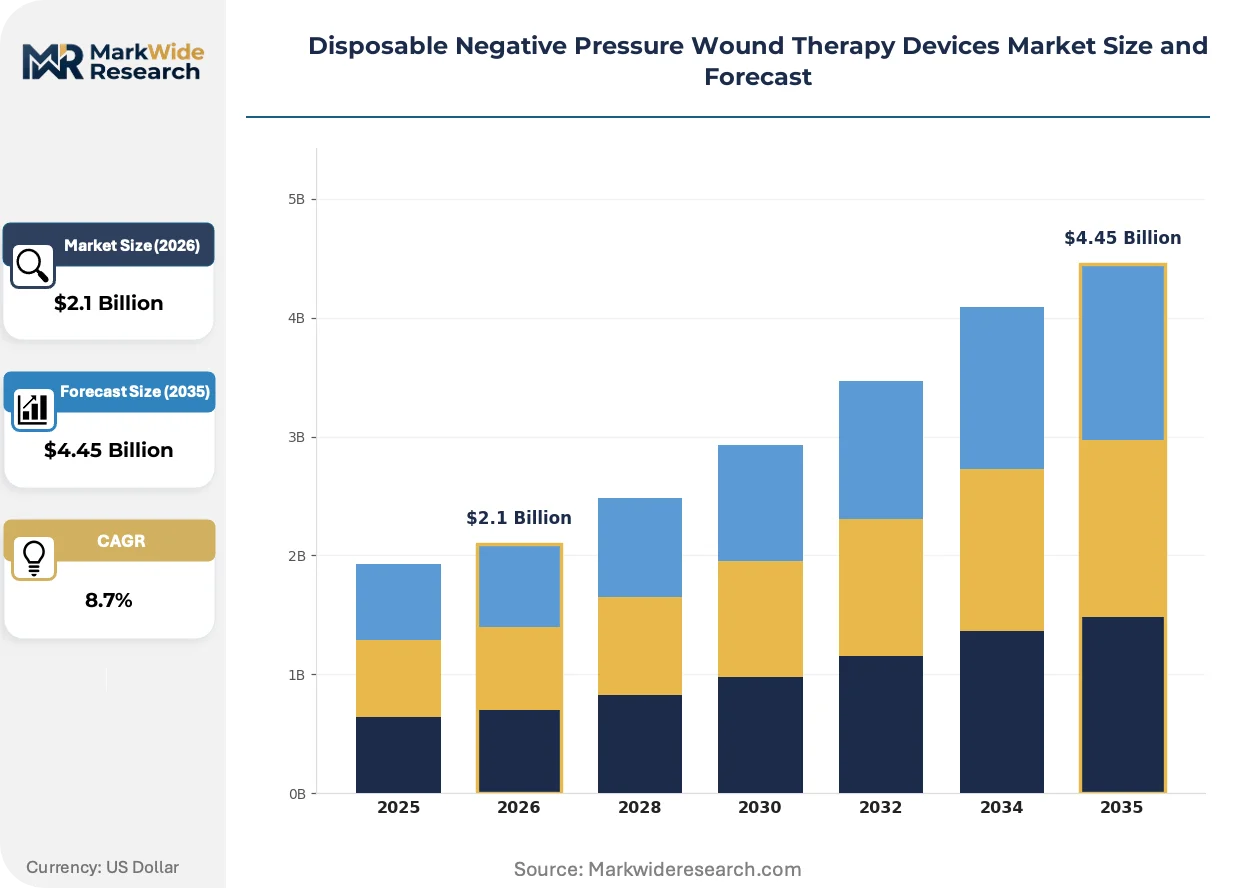
Market Dynamics
Post-acute care migration from hospitals to home settings is compressing device form factors and rewiring reimbursement logic across the disposable NPWT value chain. This structural force elevates portable battery-powered systems while eroding demand for institutional-grade stationary pumps.
Growth Catalysts
- Medicare Advantage expansion:United States payers now cover disposable NPWT for home use, eliminating prior authorization barriers that previously limited ambulatory adoption. This policy shift unlocks chronic wound patient populations previously confined to skilled nursing facilities.
- Diabetic foot ulcer protocols:Endocrinology departments in tertiary hospitals are embedding single-use NPWT into standard-of-care pathways for Wagner Grade 3 and 4 lesions, driving procedural volume through clinical guideline alignment.
- Antimicrobial foam substrates:Silver-ion and PHMB-impregnated wound contact layers are reducing per-patient dressing change frequency, improving total cost-of-ownership metrics that hospital procurement committees weight heavily.
Market Restraints
- EU MDR clinical evidence requirements:The transition from Medical Device Directive to Medical Device Regulation imposes costly post-market surveillance obligations on wound pump manufacturers, disproportionately burdening mid-tier competitors lacking established notified body relationships.
- Medical-grade silicone volatility:Occlusive drape adhesive formulations depend on silicone supply concentrated in German and Chinese chemical manufacturing clusters, exposing margin compression when feedstock prices fluctuate.
- Negative pressure range limitations:Current disposable pumps operate within narrower vacuum parameters than reusable systems, constraining applicability in heavily exudating wounds or deep cavity defects.
Strategic Opportunities
- Rural United States access gaps:Federally Qualified Health Centers in Appalachian and Mississippi Delta regions lack wound care specialists, creating white space for telemedicine-integrated disposable NPWT with remote pressure monitoring.
- Burn center applications:Partial-thickness thermal injury management represents an emerging indication where single-use systems reduce cross-contamination risk in mass casualty scenarios.
- Closed-incision negative pressure:Surgical prophylactic applications on high-risk incisions are expanding beyond orthopedic into cardiothoracic and abdominal procedures, enabled by smaller-profile canister designs.
Industry Challenges
- Bioelectronics manufacturing talent:Miniaturized pump engineering requires cross-functional expertise in microfluidics and low-power electronics that medical device firms compete for against consumer technology sectors.
- 510(k) predicate device strategy:FDA clearance pathways for novel pressure algorithms demand careful predicate selection to avoid de novo classification timelines that delay commercialization by 12-18 months.
- Legacy EHR integration:Home health agencies struggle to incorporate disposable NPWT usage data into existing wound documentation workflows, creating adoption friction despite clinical efficacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Negative Pressure Wound Therapy Devices Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Devices, Multi-use Devices, Portable Systems, Fixed Systems End User: Hospitals, Home Healthcare, Outpatient Clinics, Long-term Care Facilities Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burns Technology: Electric Pumps, Manual Pumps, Digital Monitoring, Battery-powered Systems |
| Companies Covered | Smith & Nephew, 3M, Mölnlycke Health Care, ConvaTec, Medela AG, Cardinal Health, Solventum, KCI Licensing, Talley Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Negative Pressure Wound Therapy Devices Market Emerging Trajectories
Digital connectivity architectures are penetrating disposable wound devices, transforming previously analog pumps into data-generating endpoints that feed remote patient monitoring platforms and predictive analytics engines.
Bluetooth Low Energy modules embedded in single-use canisters enable real-time pressure transmission to cloud-based dashboards accessible by wound care nurses and prescribing physicians. Home health agencies in the United States are piloting these connected systems to reduce unscheduled nursing visits while maintaining therapeutic adherence. This connectivity layer is virtualizing traditional in-person wound assessment, compressing the role of physical clinical encounters in routine monitoring workflows.
The FDA's 2023 medical device cybersecurity guidance now mandates secure data transmission protocols for networked wound therapy systems, forcing firmware architecture redesigns across the supplier base. Manufacturers must implement cryptographic authentication and encrypted payload structures that increase per-unit microcontroller costs but reduce hospital liability exposure. European notified bodies are incorporating these FDA precedents into their own technical documentation expectations, creating transatlantic regulatory convergence around digital health security standards.
Hospital supply chain directors are consolidating disposable NPWT purchasing through integrated delivery network-level contracts that bundle devices with outcomes-based service commitments. This procurement model displaces traditional spot-buying through distributor intermediaries, concentrating volume with manufacturers willing to assume inventory risk and guarantee product availability. The shift is most visible in United States metropolitan markets where health system consolidation has produced dominant regional players capable of dictating terms to device vendors.
Disposable Negative Pressure Wound Therapy Devices Market Segmentation
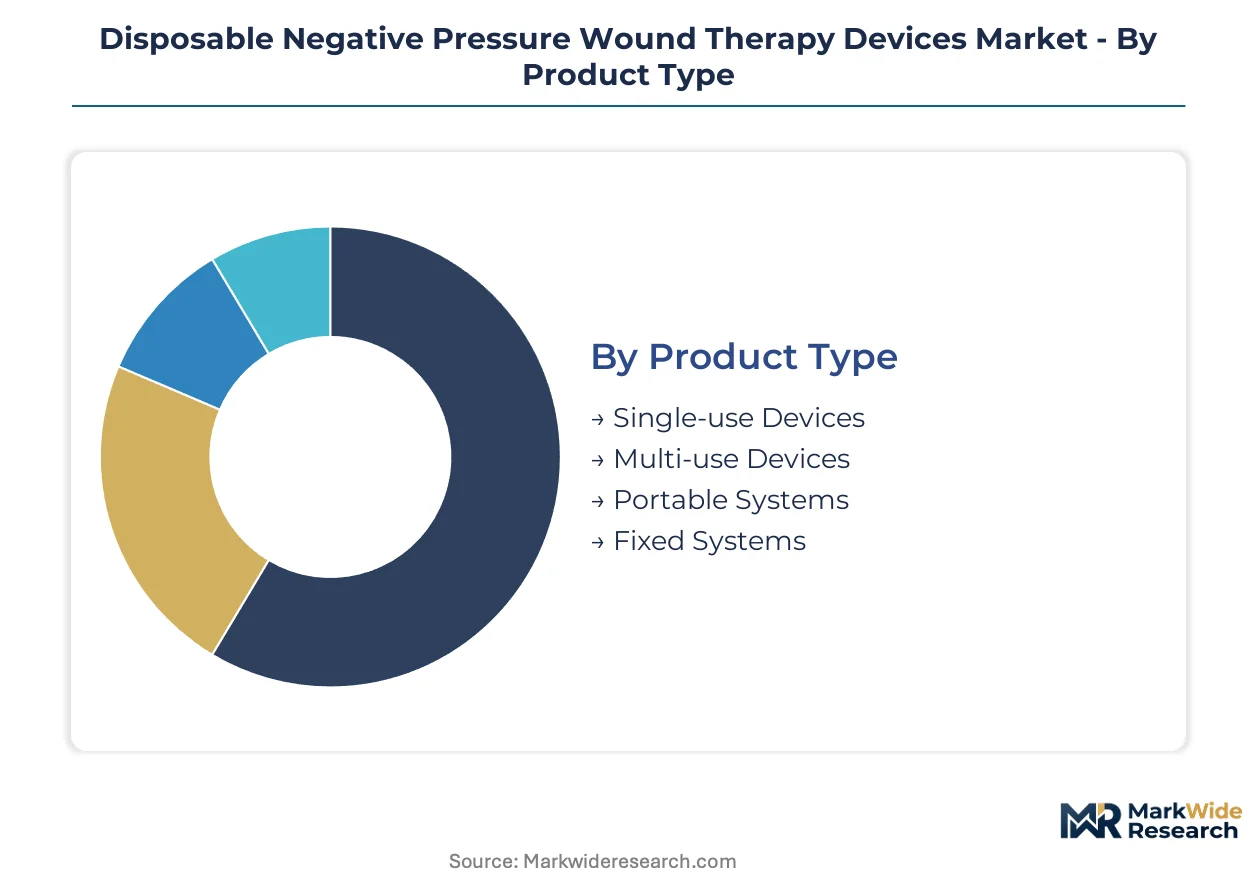
Disposable NPWT segmentation reveals distinct turnover rhythms across product categories. Cycle time variations from single-use disposables to capital-intensive fixed systems reshape inventory strategies and pricing architectures for manufacturers and procurement teams alike.
Product Type:
Single-use devices turn over in days, while fixed systems persist for years—this cycle-time spread fragments manufacturing footprints and margin profiles across the supplier base.
- Single-use Devices:Self-contained pump-canister-dressing units designed for one patient episode. Hospital infection control protocols in the United States and Germany drive procurement concentration here, though waste disposal regulations in France and Italy impose incremental cost burdens.
- Portable Systems:Battery-powered compact units enabling ambulatory therapy. Home healthcare agencies in Texas, Florida, and California represent the steepest demand concentration as Medicare Advantage reimbursement expands post-acute coverage outside institutional walls.
- Multi-use Devices:Semi-durable pumps with replaceable canister components for extended use across multiple dressing changes.
- Fixed Systems:Stationary institutional-grade pumps with wall-mounted or cart-based configurations for intensive care and burn unit deployment.
Single-use devices anchor the volume base while portable systems gain share at the steepest rate.
End User:
Cost tier stratification separates capital-rich hospitals from reimbursement-dependent home health agencies, rewiring distribution economics and service attachment models.
- Hospitals:Integrated delivery networks negotiate enterprise contracts bundling devices with clinical training and outcomes guarantees. Tertiary centers in Illinois, New York, and Pennsylvania concentrate procurement volume through value-based purchasing arrangements with 3M and Smith & Nephew direct sales forces.
- Home Healthcare:Agency-based wound care delivery shifting from skilled nursing facilities to residential settings. Reimbursement parity under Medicare Advantage plans in Arizona, Georgia, and North Carolina unlocks patient populations previously confined to institutional care.
- Outpatient Clinics:Ambulatory surgical centers and wound care clinics with procedural volume tied to bundled payment models.
- Long-term Care Facilities:Nursing homes and rehabilitation centers managing pressure injuries and diabetic foot complications in elderly populations.
Hospitals anchor the volume base while home healthcare gains share at the steepest rate.
Application:
Volume-maturity divergence separates established chronic wound protocols from emerging surgical prophylaxis indications with divergent evidence requirements and margin structures.
- Chronic Wounds:Diabetic foot ulcers, pressure injuries, and venous leg ulcers with extended therapy durations. Endocrinology departments at Cleveland Clinic, Mayo Clinic, and Johns Hopkins embed single-use NPWT into Wagner Grade 3 and 4 standard-of-care pathways, driving procedural volume through clinical guideline alignment.
- Surgical Wounds:Closed-incision negative pressure therapy for high-risk orthopedic, cardiothoracic, and abdominal procedures. Ambulatory surgical centers in California and Texas command premium per-procedure margins through bundled pricing arrangements.
- Traumatic Wounds:Acute injury management in emergency and trauma center settings.
- Burns:Partial-thickness thermal injury management with emerging adoption in mass casualty preparedness protocols.
Chronic wounds anchor the volume base while surgical wounds gain share at the steepest rate.
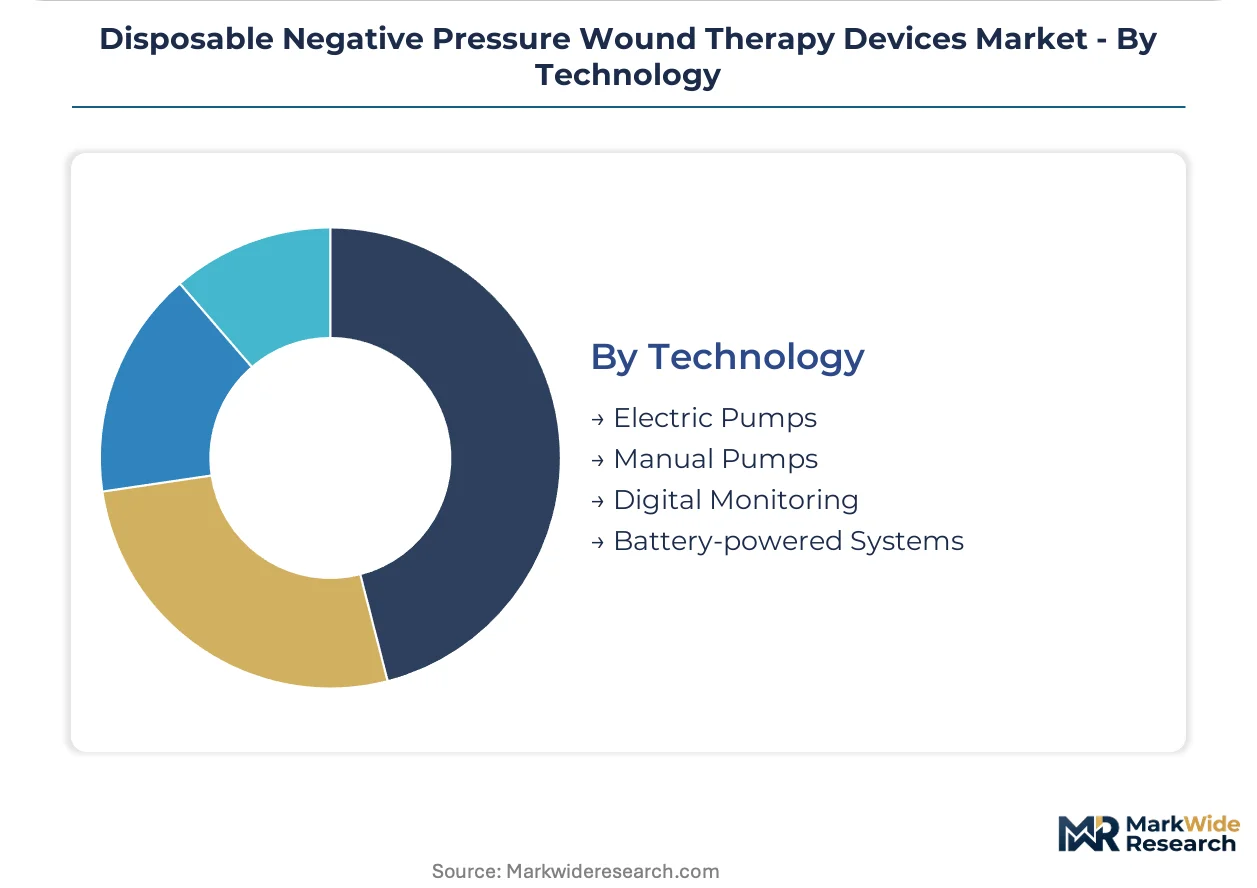
Technology:
Supply concentration in microelectronics manufacturing clusters concentrates battery-powered and digital monitoring capabilities among firms with captive semiconductor sourcing relationships.
- Battery-powered Systems:Low-energy pump architectures enabling ambulatory therapy without tethered power. Miniaturized motor and control module production concentrates in Shenzhen, Dongguan, and Singapore manufacturing clusters, with FDA 510(k) clearance pathways favoring established players with predicate device libraries.
- Digital Monitoring:Bluetooth Low Energy-enabled pressure transmission to cloud-based dashboards for remote patient monitoring. FDA cybersecurity guidance mandates cryptographic authentication and encrypted payload structures, increasing per-unit microcontroller costs while reducing hospital liability exposure.
- Electric Pumps:AC-powered institutional-grade vacuum systems with continuous pressure regulation.
- Manual Pumps:Hand-operated negative pressure generation for resource-constrained settings and emergency backup applications.
Electric pumps anchor the volume base while digital monitoring gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical logistics corridor underwrites Europe's distribution dominance, while Dallas-Fort Worth International Airport's cargo throughput anchors United States supply chain velocity for wound care devices.
United States
Medicare Advantage expansion and chronic wound prevalence in Florida and Arizona drive procurement concentration. FDA 510(k) clearance pathways favor established manufacturers with predicate device libraries. The Dallas-Fort Worth metroplex hosts centralized distribution hubs serving integrated delivery networks across Texas, Oklahoma, and Louisiana.
Germany
Hospital infection control protocols and silicone adhesive supply concentration shape procurement patterns. EU MDR transition imposes stricter clinical evidence requirements through notified bodies in Berlin and Munich. The Rhine-Ruhr industrial corridor maintains medical-grade silicone manufacturing clusters supplying occlusive drape formulations.
China
Domestic wound care demand and government hospital procurement reform accelerate local production scale. NMPA medical device registration requirements create compliance barriers for imported systems. Shenzhen and Dongguan manufacturing clusters concentrate miniaturized pump motor and control module production.
Japan
Aging demographics and diabetic foot ulcer incidence expand home healthcare device adoption. PMDA regulatory review timelines favor incremental innovation over novel pressure algorithms. The Kansai region's Osaka-Kobe medical device corridor hosts wound care specialists and distribution infrastructure.
United Kingdom
NHS procurement consolidation and value-based purchasing frameworks reshape vendor relationships. MHRA post-Brexit regulatory autonomy maintains alignment with FDA cybersecurity guidance precedents. The Cambridge-Oxford-London triangle concentrates digital health integration expertise for connected wound monitoring systems.
Disposable Negative Pressure Wound Therapy Devices Market Vendor Landscape
On the supply side, the industry is consolidating around integrated delivery network contracts that bundle devices with service-level guarantees. Tiered competitive positioning separates multinational wound care conglomerates from regional specialists and contract manufacturers. Strategic archetypes include direct sales force operators, material science leaders, and vertically integrated foam substrate producers. Dominant competitive moves encompass M&A for regulatory infrastructure acquisition and backward integration into critical raw material supply.
Among established wound care conglomerates, Smith & Nephew and 3M exemplify divergent competitive positioning. Smith & Nephew occupies a position anchored in direct sales force deployment for large integrated delivery network account control. 3M represents material science leadership through adhesive drape technologies. Mölnlycke Health Care sits within the vertical integration archetype through captive foam substrate manufacturing.
| Leading Market Players |
|---|
| Smith & Nephew |
| 3M |
| Mölnlycke Health Care |
| ConvaTec |
| Medela AG |
| Cardinal Health |
| Solventum |
| KCI Licensing |
| Talley Group |
| Others |
Supply Flow & Price Mechanics
Shenzhen's miniaturized pump motor manufacturing clusters concentrate capacity for battery-powered systems, translating component scarcity into pricing leverage for tier-one device vendors serving United States integrated delivery networks. This geographic concentration feeds downstream into three-tier pricing structures that separate FDA-cleared premium systems from standard hospital procurement tiers and economy-grade manual alternatives.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with integrated delivery networks extracting 15-25% price concessions against list rates through multi-year bundled contracts. Price differentiation rests on FDA 510(k) clearance tier and silicone adhesive formulation grade, with antimicrobial foam substrates commanding material premiums. Cost compression in economy tiers is intensifying because Medicare Advantage reimbursement parity compresses per-procedure margins. Home health agencies exhibit acute price sensitivity due to thin agency margins, while tertiary hospital systems prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessments for microelectronics-dependent portable systems. Manufacturing concentrates in China, Germany, and Singapore, with medical-grade silicone feedstock anchored in Rhine-Ruhr chemical clusters and miniaturized motors sourced from Shenzhen-Dongguan electronics corridors. Raw material dependencies span lithium-ion cells, medical-grade silicone, and antimicrobial silver-ion substrates. Single-source vulnerability persists for Bluetooth Low Energy modules qualifying under FDA cybersecurity guidance. Distribution runs through Dallas-Fort Worth centralized hubs serving regional integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by Medicare Advantage expansion unlocking previously institutional-bound patient populations for home-based therapy.
For Market Incumbents: Harden regulatory infrastructure moats by deepening 510(k) predicate device libraries against emerging digital-native entrants lacking FDA clearance pathways. Prioritize backward integration into medical-grade silicone supply to insulate margin structures from German-Chinese feedstock volatility. Secure exclusive GPO contracts with top-10 United States health systems to foreclose competitor access. For New Entrants and Emerging Players: Establish a beachhead in rural United States Federally Qualified Health Centers where wound care specialist scarcity creates service-model white space. Target burn center applications for mass casualty preparedness protocols where cross-contamination risk drives single-use preference. Deploy telemedicine-integrated pressure monitoring as the primary go-to-market angle to differentiate from analog incumbent offerings. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-elasticity play because aging diabetic populations in Florida and Arizona guarantee chronic wound volume expansion regardless of macroeconomic cycles. Acquisition target archetype: mid-tier European manufacturers with EU MDR technical documentation assets but lacking United States distribution infrastructure. Watch Medicare Advantage plan reimbursement parity decisions as the inflection signal determining home segment profitability trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks volume through integrated delivery network bundling with Smith & Nephew and 3M direct sales forces. |
| FDA Submission | Accelerates 510(k) clearance timelines for novel pressure algorithms against predicate device strategies. |
| CE Marking Pathway | Opens EU MDR-compliant market access through notified bodies in Berlin and Munich. |
| Software Companion Development | Enables Bluetooth Low Energy pressure transmission to cloud dashboards for remote patient monitoring. |
| Reimbursement Strategy | Aligns device pricing with Medicare Advantage coverage expansion in Texas, Florida, and California. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across wound care nurses, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and home health agency directors. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement contract repositories, and EU MDR technical documentation. Bottom-up and top-down triangulation reconciled device shipment estimates against reimbursement claim volumes.
Calibration against historical Medicare Advantage enrollment trends and diabetic foot ulcer incidence rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, application indication, and technology architecture. CAGRs were derived from logistic diffusion curves fitted to portable system adoption patterns. Industry-specific inputs incorporated silicone feedstock price volatility indices and FDA cybersecurity guidance compliance cost trajectories.
Sensitivities concentrate around EU MDR notified body capacity constraints, Medicare Advantage plan reimbursement parity timing, and medical-grade silicone supply disruptions. Forecasts reflect assumptions documented in the segmentation and regional outlook sections without claiming predictive certainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market