
 Sustained Acoustic Medicine Market | 2026-2036
Sustained Acoustic Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Sustained Acoustic Medicine Market Analytics
Aftermarket service revenue is reconfiguring margin distribution across the sustained acoustic medicine value chain. ZetrOZ Systems leverages direct-to-patient subscription models for device maintenance and consumable replenishment. Medtronic anchors hospital procurement through integrated service contracts that bundle equipment with clinical training. NANOVIBRONIX Corporation specializes in portable form factors that reduce reliance on clinic-based technician visits.
Sustained acoustic medicine delivers low-intensity pulsed ultrasound or focused acoustic energy at 1-3 MHz frequencies to stimulate tissue repair and modulate inflammatory response in musculoskeletal conditions. The primary commercial purpose centers on non-invasive, drug-free alternatives for chronic pain management and accelerated soft-tissue healing. Wearable devices command expanding margin pools as patients shift rehabilitation from clinical settings to home care environments, while therapeutic equipment remains the volume foundation in hospital and physiotherapy clinic installations. Low-intensity pulsed ultrasound technology leads application development for bone fracture healing, whereas focused ultrasound platforms attract premium pricing in sports medicine segments.
FDA 510(k) premarket notification requirements govern therapeutic ultrasound device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for CE marking in European markets. ISO 13485 quality management certification shapes supplier qualification criteria for original equipment manufacturers seeking contract manufacturing partnerships. Stakeholders must monitor evolving reimbursement codes for acoustic therapy procedures as payer coverage decisions will determine addressable patient populations.
Market Dynamics
Home-based rehabilitation protocols are compressing clinic visit volumes and reallocating margin pools toward wearable device manufacturers. This demand migration pressures traditional physiotherapy networks to reconfigure service delivery models around remote patient monitoring capabilities.
Growth Catalysts
- FDA 510(k) streamlining:Expedited premarket notification pathways for therapeutic ultrasound equipment reduce time-to-market for device innovators. This regulatory efficiency accelerates commercialization cycles.
- Collegiate athletic procurement:University sports medicine programs are standardizing wearable ultrasound protocols for injury prevention. This institutional adoption builds clinical evidence bases.
- Low-intensity pulsed ultrasound:Bone fracture healing applications demonstrate measurable recovery acceleration. Orthopedic specialists are integrating this modality into post-operative care pathways.
Market Restraints
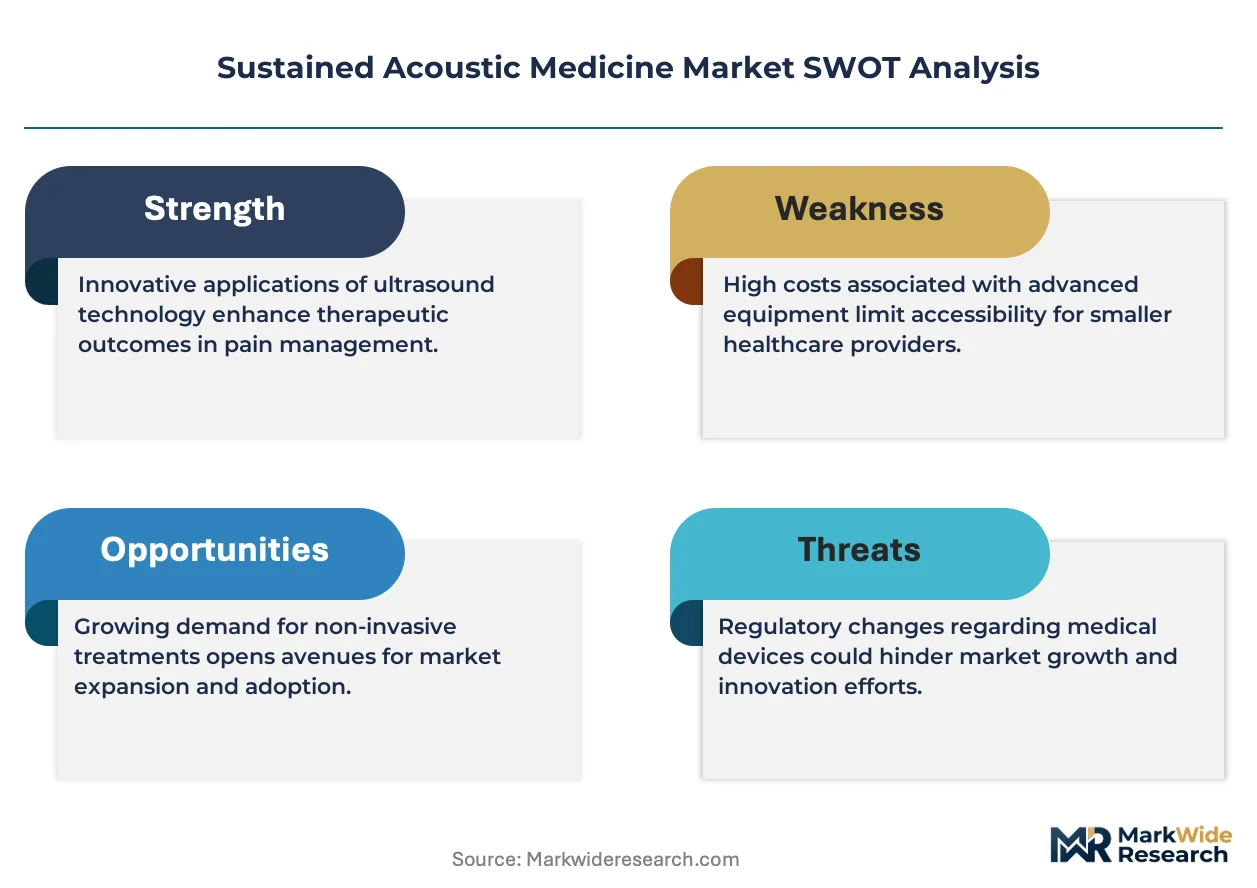
- Reimbursement code fragmentation:Payer coverage decisions for acoustic therapy procedures remain inconsistent across Medicare Advantage plans. This variability limits addressable patient populations.
- Supply concentration in transducer components:Precision piezoelectric material sourcing clusters in East Asian manufacturing corridors. Geopolitical friction threatens component availability.
- Technical depth limitations:Focused ultrasound platforms require precise tissue targeting that challenges non-specialist operators. Training intensity constrains deployment scalability.
Strategic Opportunities
- Underpenetrated home care channels:Post-acute care settings in Germany represent untapped deployment environments for wearable sustained acoustic devices. Aging demographics amplify chronic pain management needs.
- EU Medical Device Regulation harmonization:Stricter CE marking clinical evidence standards create competitive moats for established manufacturers. Early compliance investments yield market access advantages.
- Telehealth convergence:Integration of acoustic therapy devices with remote physiotherapy platforms enables asynchronous clinical oversight. This hybrid model expands rural patient reach.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for contract manufacturing partnerships extend supplier qualification cycles. Resource-intensive documentation requirements strain mid-tier device firms.
- Biomedical engineering talent scarcity:Specialized ultrasound transducer design expertise concentrates in established medical device hubs. Recruitment competition intensifies compensation pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustained Acoustic Medicine Market |
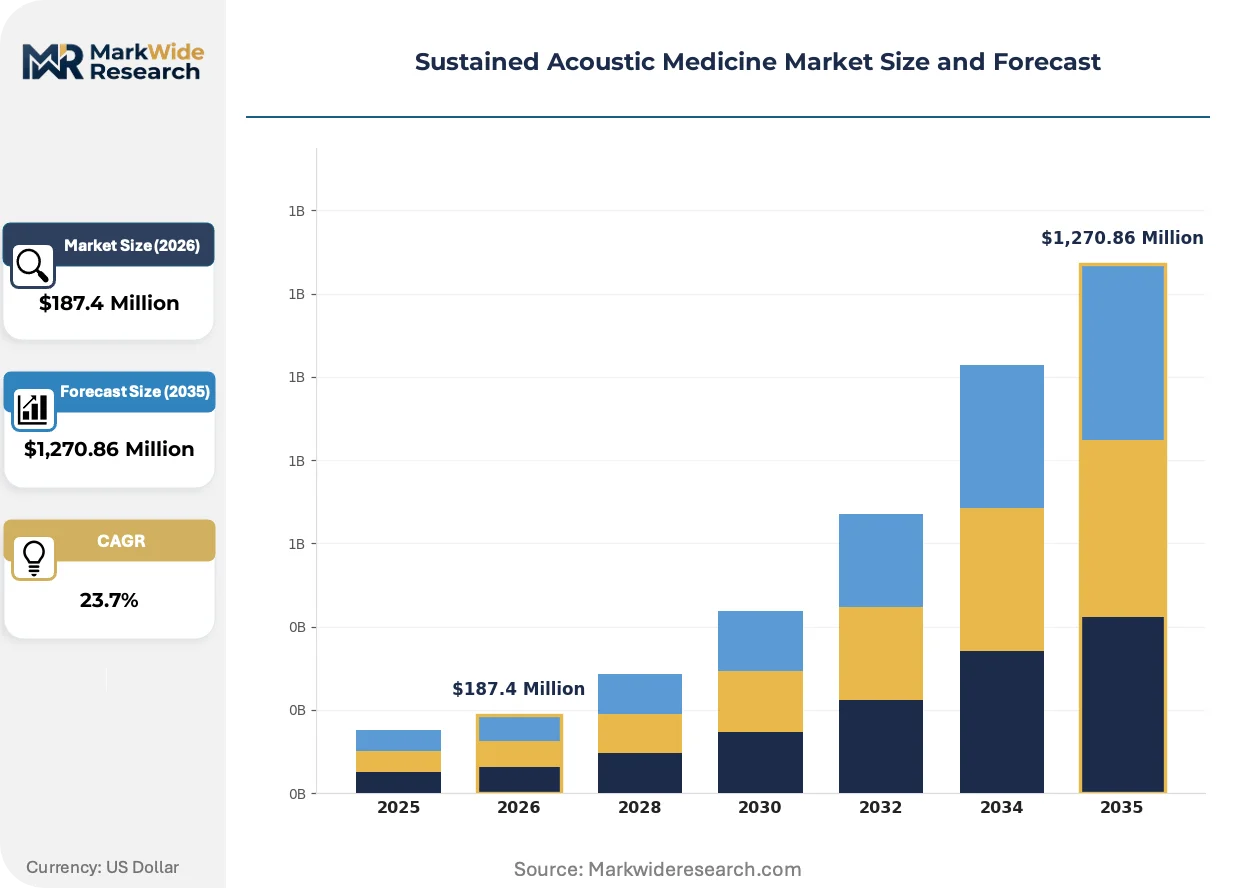
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Devices, Therapeutic Equipment, Monitoring Systems, Wearable Devices Application: Chronic Pain Management, Rehabilitation, Sports Medicine, Injury Prevention End User: Physiotherapy Clinics, Hospitals, Rehabilitation Centers, Home Care Settings Technology: Focused Ultrasound, Low-Intensity Pulsed Ultrasound, Shockwave Therapy, Thermal Therapy |
| Companies Covered | ZetrOZ Systems, BTL, Compass Health Brands, Mettler Electronics Corp, Dynatronics Corporation, Danaher Corporation, NANOVIBRONIX Corporation, Beckman Coulter, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustained Acoustic Medicine Market Evolving Landscape
Wearable form factors are compressing the boundary between clinical-grade therapeutic delivery and consumer-accessible pain management tools. This hardware miniaturization is simultaneously expanding addressable user bases and complicating regulatory classification frameworks.
Focused ultrasound platforms are migrating from hospital-based installation models toward portable prescription devices that patients operate independently. Professional sports franchises are piloting these systems for sideline injury management. This capability shift is enabling real-time therapeutic intervention outside traditional care settings.
The EU Medical Device Regulation imposes stricter clinical evidence standards for CE marking that extend validation timelines for novel acoustic therapy indications. Manufacturers must generate prospective trial data rather than relying on predicate device equivalence. European orthopedic networks are responding by consolidating procurement around established suppliers with robust quality dossiers.
Direct-to-patient subscription models are displacing traditional capital equipment sales in ambulatory care segments. Device-as-a-service arrangements bundle hardware with consumable replenishment and remote clinical support. This preference shift is most visible in United States physical therapy networks seeking to reduce upfront capital commitments.
Sustained Acoustic Medicine Market Segmentation
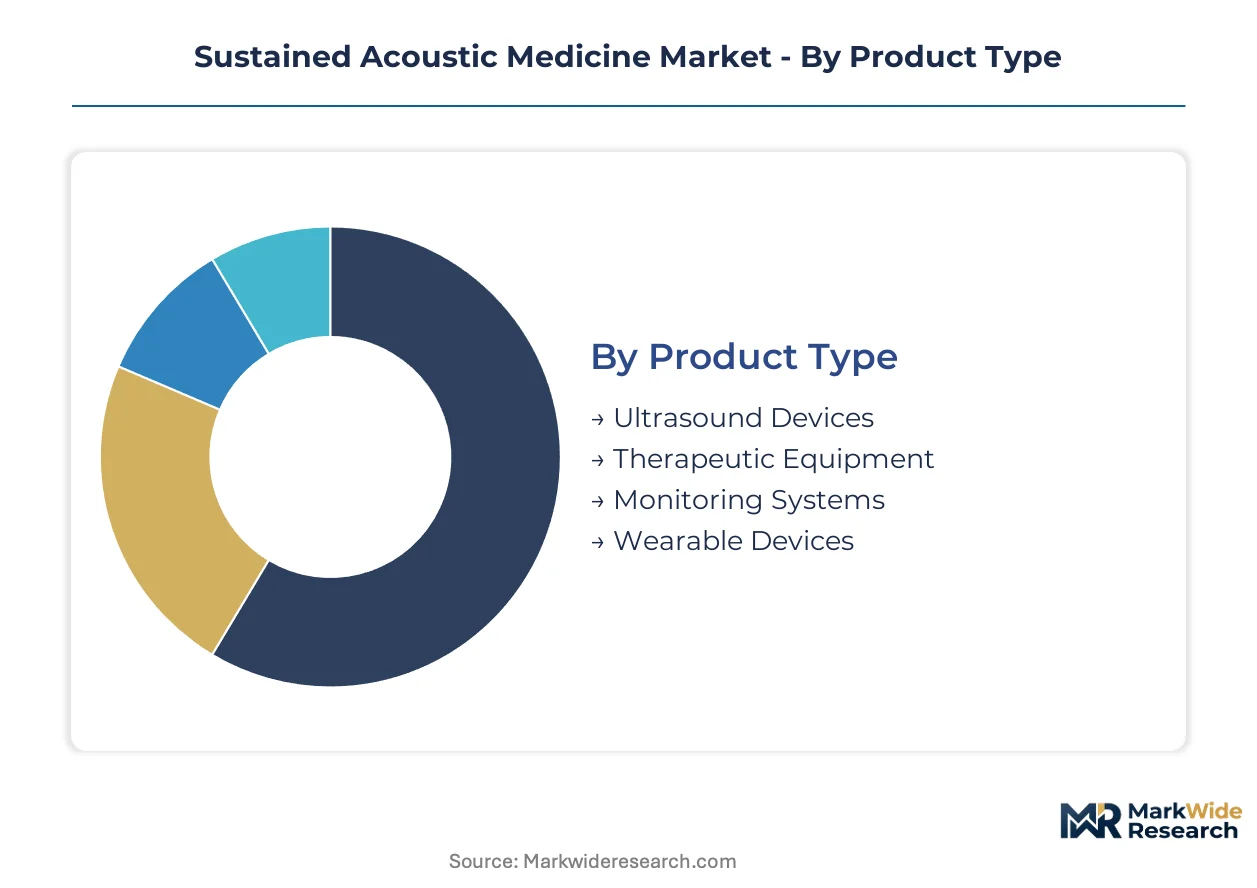
Segmentation in sustained acoustic medicine reveals distinct margin architectures across hardware form factors and care delivery settings. Product type and end user dimensions expose the tension between capital-intensive hospital installations and recurring-revenue home care models reshaping commercial strategy.
Product Type:
Cost tier differentiation separates capital equipment from consumable-dependent delivery systems across the product portfolio.
- Wearable Devices:Miniaturized transducer arrays with adhesive coupling interfaces enable patient-operated therapy sessions outside clinical supervision. Demand concentrates in United States collegiate athletic programs seeking portable injury prevention protocols, though FDA 510(k) classification ambiguity for prescription versus over-the-counter status constrains channel expansion.
- Therapeutic Equipment:Cart-mounted or fixed-installation systems deliver higher acoustic intensities with integrated imaging guidance for precise tissue targeting. Hospital procurement in Germany and France anchors volume, with integrated service contracts bundling hardware, training, and maintenance into multi-year agreements.
- Ultrasound Devices:General-purpose diagnostic-to-therapeutic platforms serve dual clinical functions in resource-constrained settings.
- Monitoring Systems:Compliance-tracking peripherals capture treatment adherence data for remote physiotherapy oversight.
Wearable Devices holds installed capacity. Therapeutic Equipment is rotating up the share rankings.
Application:
Volume concentration in musculoskeletal conditions reflects reimbursement alignment and clinical evidence maturity.
- Sports Medicine:Acute soft-tissue injury protocols leverage focused ultrasound for rapid inflammation modulation and return-to-play acceleration. Professional franchises in the United States and football clubs in Spain deploy sideline systems for real-time intervention, with competitive pressure driving procurement standardization.
- Chronic Pain Management:Drug-free alternatives to opioid prescriptions target Medicare Advantage populations with demonstrated cost-offset potential. United States orthopedic networks integrate sustained acoustic protocols into value-based care bundles for lumbar and osteoarthritis presentations.
- Rehabilitation:Post-operative care pathways incorporate low-intensity pulsed ultrasound for tendon and ligament remodeling.
- Injury Prevention:Pre-season conditioning programs use wearable devices for tissue preconditioning in high-impact athletics.
Sports Medicine holds installed capacity. Chronic Pain Management is rotating up the share rankings.
End User:
Customer type stratification tracks the decentralization of rehabilitation delivery from institutional to domestic environments.
- Home Care Settings:Direct-to-patient subscription models bundle wearable hardware with consumable replenishment and asynchronous clinical support. Post-acute demand in Japan and South Korea accelerates as aging demographics expand chronic pain prevalence and family-caregiver capacity constraints favor independent therapy management.
- Hospitals:Integrated delivery networks consolidate procurement around established suppliers with robust quality dossiers satisfying EU Medical Device Regulation clinical evidence requirements. German and French orthopedic departments anchor European volume through centralized capital budgeting.
- Physiotherapy Clinics:Independent practices adopt device-as-a-service arrangements to reduce upfront capital commitments.
- Rehabilitation Centers:Specialized post-acute facilities maintain higher-intensity therapeutic equipment for complex cases.
Home Care Settings holds installed capacity. Hospitals is rotating up the share rankings.
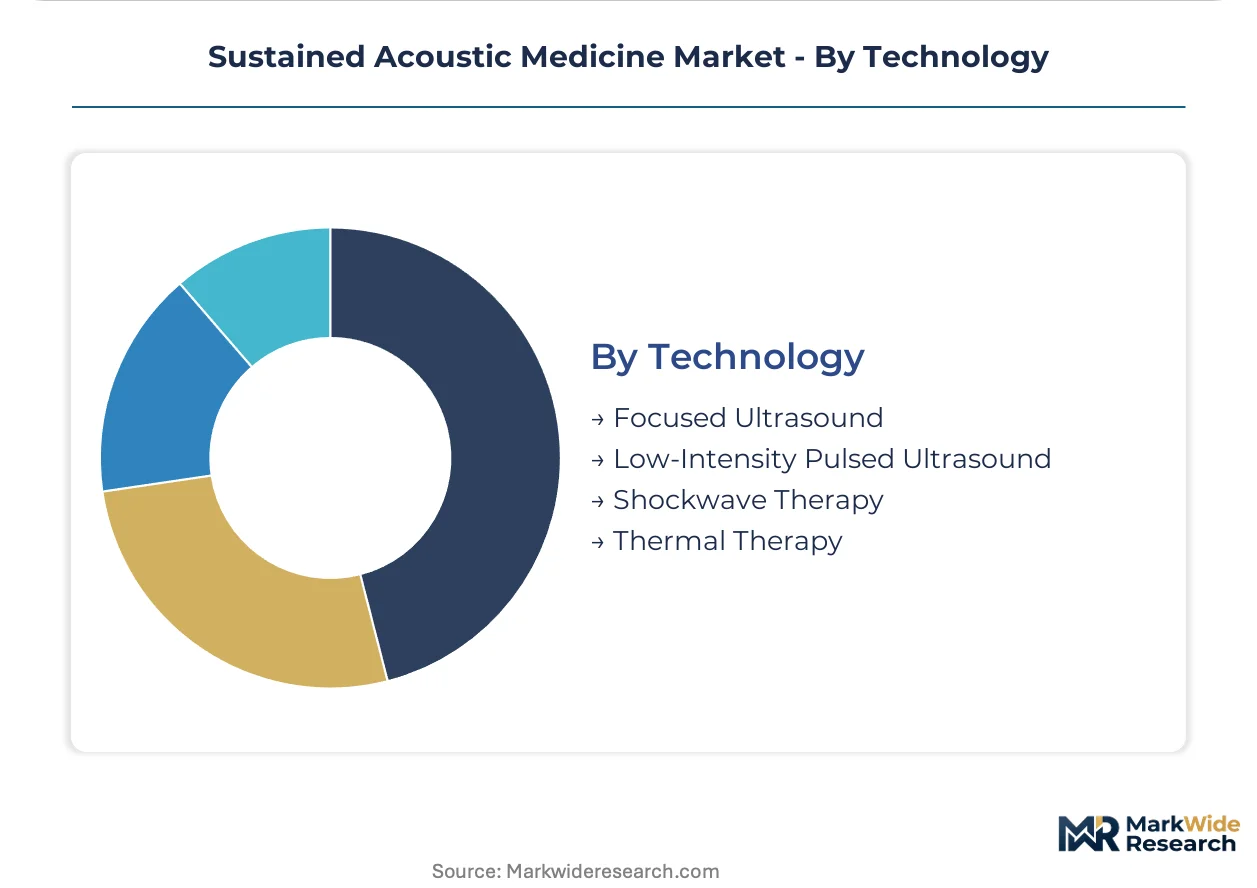
Technology:
Application specificity distinguishes acoustic modalities by tissue penetration depth and biological mechanism.
- Low-Intensity Pulsed Ultrasound:Mechanical stimulation at 1.5 MHz frequency accelerates osteoblast activity and angiogenesis in bone fracture healing. Orthopedic specialists in the United States integrate this modality into post-operative care pathways for stress fractures and non-union presentations, with measurable recovery acceleration driving protocol standardization.
- Focused Ultrasound:Concentrated acoustic energy enables precise thermal or mechanical tissue ablation without incision. Sports medicine applications in the United States and Australia command premium pricing for acute injury intervention, though operator training intensity constrains deployment scalability outside specialist centers.
- Shockwave Therapy:Extracorporeal pressure waves target calcific tendinopathy and plantar fasciitis with distinct biological effects.
- Thermal Therapy:Sustained mild heating modulates inflammatory response in subacute soft-tissue presentations.
Low-Intensity Pulsed Ultrasound holds installed capacity. Focused Ultrasound is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies. United States buyers absorb premium pricing for wearable prescription devices, while German procurement offices negotiate aggressive capital equipment discounts. Japanese home care channels prioritize reliability over cost, accepting higher per-session fees for remote clinical support integration.
United States
Collegiate athletic programs and professional sports franchises drive wearable device procurement for sideline injury management. FDA 510(k) clearance pathways streamline market entry for therapeutic ultrasound innovators. The Boston-Cambridge medical device corridor hosts concentrated R&D activity for miniaturized transducer technologies.
Germany
Hospital orthopedic networks anchor European demand for cart-mounted therapeutic equipment with integrated imaging guidance. EU Medical Device Regulation clinical evidence requirements favor established suppliers with robust quality dossiers. The Baden-Württemberg precision manufacturing cluster supplies piezoelectric transducer components to original equipment manufacturers.
Japan
Aging demographics expand chronic pain prevalence and family-caregiver capacity constraints favor independent therapy management. PMDA regulatory frameworks emphasize post-market surveillance for home-use medical devices. Tokyo-based rehabilitation networks pilot device-as-a-service models bundling hardware with asynchronous clinical oversight.
South Korea
Post-acute care settings accelerate adoption of wearable sustained acoustic devices for elderly populations. MFDS quality management certification shapes supplier qualification criteria for domestic manufacturers. The Seoul Capital Area concentrates distribution infrastructure for consumer-accessible pain management tools.
Australia
Sports medicine applications command premium pricing for acute soft-tissue injury intervention in professional football and rugby franchises. TGA regulatory alignment with international standards facilitates parallel market entry strategies. Sydney and Melbourne physiotherapy networks consolidate procurement around remote patient monitoring capabilities.
Sustained Acoustic Medicine Market Competitive Landscape
Capability concentration sits with specialized ultrasound transducer designers; scale advantage sits with diversified medical technology conglomerates. The vendor base organizes around three strategic archetypes: wearable form factor specialists, hospital-grade equipment incumbents, and diagnostic-to-therapeutic platform generalists. Consolidation pressure intensifies as subscription-based revenue models displace traditional capital sales. Dominant competitive moves include strategic partnerships with physiotherapy networks and technology licensing agreements for miniaturized acoustic delivery systems.
Within the wearable device tier, ZetrOZ Systems and NANOVIBRONIX Corporation exemplify direct-to-patient subscription architectures. Medtronic anchors the hospital procurement segment through integrated service contracts bundling equipment with clinical training. Among diversified technology holdings, Danaher Corporation occupies a position spanning diagnostic and therapeutic ultrasound platforms.
| Leading Market Players |
|---|
| ZetrOZ Systems |
| BTL |
| Compass Health Brands |
| Mettler Electronics Corp |
| Dynatronics Corporation |
| Danaher Corporation |
| NANOVIBRONIX Corporation |
| Beckman Coulter |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Single-source dependency on East Asian piezoelectric transducer manufacturing determines both pricing tier spreads and supply chain shape, with precision ceramic sourcing concentration in specific manufacturing corridors creating asymmetric cost structures across device categories.
Pricing Analysis
After-sales service revenue tiers drive lifetime value capture across the sustained acoustic medicine landscape. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared prescription devices from consumer-accessible over-the-counter alternatives, with certification grade and after-sales bundling as primary differentiation drivers. Cost compression in economy-tier wearable segments is intensifying because of subscription model proliferation. Hospital procurement committees demonstrate lowest price sensitivity, while individual consumers in direct-to-patient channels exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from original equipment manufacturers to component suppliers characterize working capital dynamics in this sector. Manufacturing concentration clusters in China, Japan, and Germany for precision piezoelectric ceramics, with assembly operations drawing from Malaysian and Mexican facilities. Raw material dependencies center on lead zirconate titanate ceramics, acoustic coupling gels, and medical-grade adhesives. Single-source vulnerability in specialized transducer designs threatens component availability. Distribution runs through hospital procurement networks, GPO contracts, and direct-to-patient e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized ultrasound transducer engineering talent scarcity constrains expansion velocity, with biomedical engineering programs failing to replenish domain expertise at commercialization-scale rates.
For Market Incumbents: Build regulatory dossier moats through early EU MDR compliance investments that extend validation timelines for competitors. Deepen backward integration into precision piezoelectric ceramic production to secure component availability against geopolitical friction. Anchor hospital procurement through multi-year integrated service contracts bundling equipment, training, and maintenance. Counter emerging wearable specialists by accelerating miniaturized form factor development timelines. For New Entrants and Emerging Players: Build out direct-to-patient subscription architectures in underpenetrated German and Japanese home care channels where aging demographics expand chronic pain prevalence. Target post-acute rehabilitation settings with device-as-a-service models that reduce upfront capital barriers for independent physiotherapy practices. Penetrate collegiate athletic programs in the United States through sideline injury prevention protocols. Lead with telehealth integration capabilities that enable asynchronous clinical oversight. For Investors and Strategic Acquirers: Specialized ultrasound transducer design boutiques with ISO 13485 certification and established OEM relationships represent priority acquisition targets. Long-term viability hinges on recurring revenue model transition completion and reimbursement code consolidation. Monitor FDA 510(k) clearance velocity and Medicare Advantage coverage expansion as inflection indicators for addressable patient population scaling. Macroscopic, regulatory, or technological deviation would prompt revision.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited premarket notification accelerates commercialization cycles for therapeutic ultrasound innovators. |
| CE Marking Pathway | EU MDR clinical evidence requirements create competitive moats for established manufacturers with robust dossiers. |
| Hospital System Partnership | Integrated delivery network contracts bundle equipment, training, and maintenance into multi-year agreements. |
| Software Companion Development | Remote patient monitoring platforms enable asynchronous clinical oversight and expand rural patient reach. |
| Reimbursement Strategy | Medicare Advantage coverage decisions determine addressable populations for acoustic therapy procedures. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and physiotherapy clinic owners anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR submission dossiers. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation cross-verified volume estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application, end user, and technology modality. CAGRs derived from fitted growth curves applied to installed base expansion and replacement cycle dynamics. Forecast inputs incorporated collegiate athletic procurement trends, home care channel migration velocity, and regulatory clearance pipeline status.
Sensitivities concentrate around reimbursement code consolidation timelines, piezoelectric material supply disruption, and FDA classification ambiguity for prescription versus over-the-counter wearable devices. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and payer coverage expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market