
 Therapeutic Apheresis Market | 2026-2036
Therapeutic Apheresis Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Apheresis Market Outlook
Neurological disorder treatment is realigning the end-use mix for therapeutic apheresis, drawing capital toward plasma exchange protocols for conditions such as Guillain-Barré syndrome and myasthenia gravis. Baxter International leverages its integrated hospital supply chain to sustain recurring kit sales across major treatment centers. Fresenius Medical Care anchors European demand through its dialysis-adjacent apheresis service footprint. Terumo BCT differentiates via continuous flow processing systems that occupy the high-throughput segment of hospital blood banks.
Therapeutic apheresis denotes an extracorporeal procedure that separates blood components using centrifugation or membrane filtration at flow rates typically between 50 and 150 mL per minute, returning desired elements to the patient while removing pathogenic substrates or cells. Its primary purpose is to treat autoimmune, neurological, and hematological conditions where pharmacological intervention proves insufficient. Plasmapheresis leads product type revenue due to its established reimbursement codes and broad indication profile across neurological disorders. Membrane filtration technology is displacing legacy centrifugation in new hospital installations where space constraints and disposable cost reduction matter. Autoimmune disorders represent the most mature application segment, while oncological applications tied to CAR-T leukapheresis collection are expanding fastest among academic research institutions.
FDA 510(k) pathways and EU MDR conformity assessments shape device commercialization timelines, with the FDA demanding clinical validation for novel membrane pore specifications and the EU requiring post-market surveillance under the Medical Device Regulation. ISO 13485 quality management standards govern manufacturing consistency for disposable apheresis kits across both jurisdictions. Stakeholders must monitor evolving CMS reimbursement decisions for outpatient plasmapheresis and the trajectory of EU notified body capacity constraints that could delay market entry for next-generation continuous flow systems.
Market Dynamics
Membrane filtration technology is converging with centrifugation systems in hybrid apheresis platforms, forcing incumbent equipment suppliers to redesign disposable architectures and recalibrate hospital service contracts around throughput-per-square-meter metrics rather than standalone device placement.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's predicate device framework for membrane pore specifications accelerates clearance timelines for next-generation filtration modules, reducing commercialization lag for US-based manufacturers.
- Academic medical center expansion:CAR-T leukapheresis collection protocols at major US and German university hospitals are creating dedicated cell processing infrastructure that doubles as therapeutic apheresis capacity.
- Neurological indication broadening:Plasma exchange protocols for Guillain-Barré syndrome and myasthenia gravis now command dedicated reimbursement codes in Germany and Japan, pulling procedure volume into outpatient settings.
Market Restraints
- Single-use kit cost concentration:Proprietary disposable sets represent 60-70% of per-procedure economics, locking treatment centers into vendor-specific supply agreements with limited substitution flexibility.
- EU MDR notified body bottleneck:Conformity assessment capacity constraints under the Medical Device Regulation extend certification timelines for novel continuous flow systems by 12-18 months versus pre-2021 baselines.
- Trained operator scarcity:Specialized nursing certification for extracorporeal procedures creates workforce bottlenecks in secondary care facilities attempting to expand autoimmune treatment programs.
Strategic Opportunities
- India outpatient infrastructure:Dialysis center networks in Mumbai and Delhi present retrofit opportunities for plasmapheresis capability with minimal incremental capital expenditure.
- Japan's aging neurological burden:METI incentives for chronic disease management infrastructure support dedicated apheresis suites in prefectural hospitals for CIDP and TTP cases.
- Continuous-membrane hybrid systems:Integration of hollow-fiber filtration with centrifugal cell separation enables single-platform flexibility across autoimmune, oncological, and hematological applications.
Industry Challenges
- ISO 13485 audit complexity:Multi-site manufacturing quality management for disposable kits requires synchronized compliance across polymer extrusion, membrane casting, and sterile packaging operations.
- Legacy device interoperability:Hospital blood banks operate mixed-vendor environments where new continuous flow systems must interface with existing patient data management and anticoagulant monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Apheresis Market |
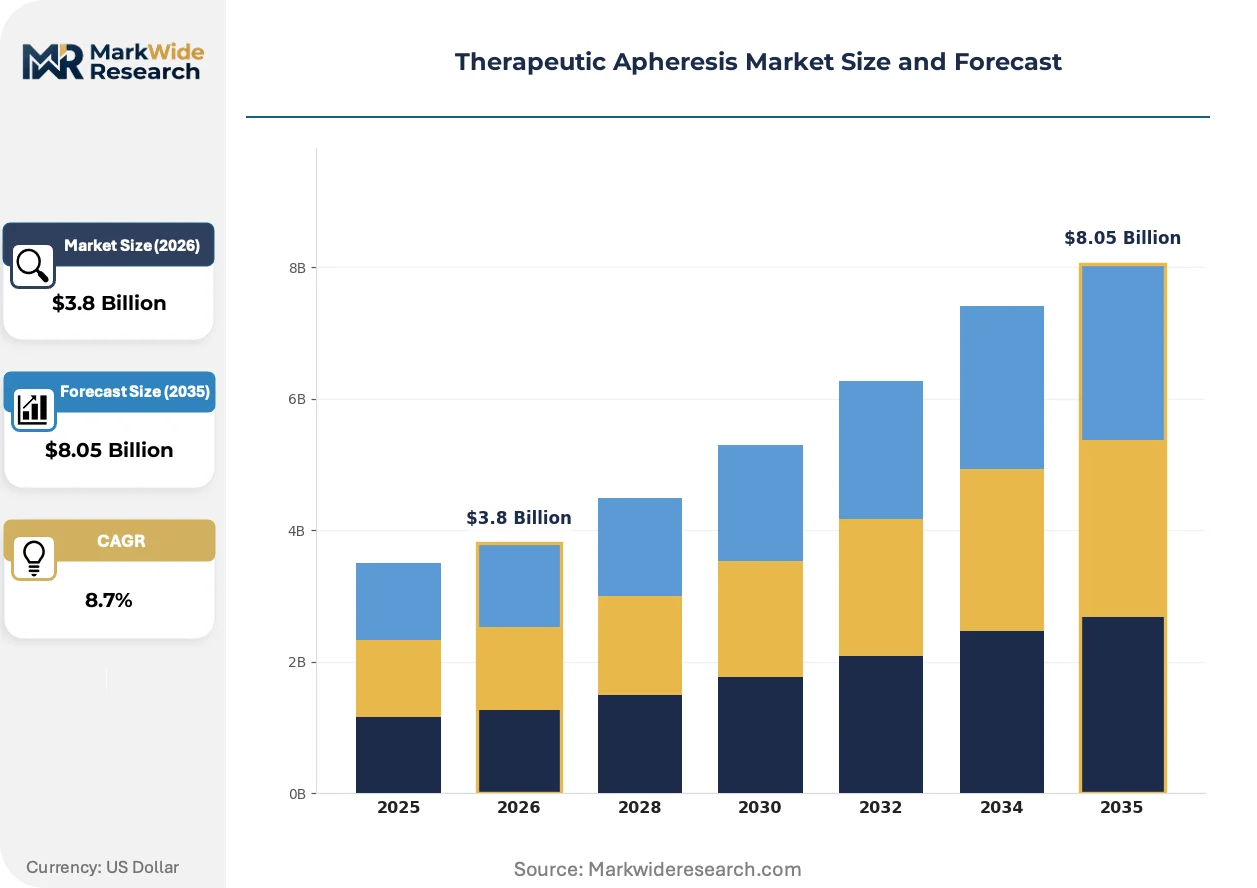
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmapheresis, Leukapheresis, Erythrocytapheresis, Thrombocytapheresis Application: Autoimmune Disorders, Neurological Disorders, Renal Disorders, Oncological Disorders Technology: Membrane Filtration, Centrifugation, Continuous Flow Processing, Electrophoresis End User: Hospitals, Blood Banks, Academic Research Institutions, Clinics |
| Companies Covered | Asahi Kasei Medical, Baxter International, Fresenius Medical Care, Cerus Corporation, Kaneka Corporation, Terumo BCT, B. Braun Melsungen AG, MEDICA S.P.A., Haemonetics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Apheresis Market Strategic Shifts
Technology trajectories in therapeutic apheresis center on modular platform architectures that compress footprint requirements while expanding treatable indication sets, with regulatory frameworks and procurement models adapting to accommodate capital-constrained buyers.
Membrane filtration is converging with centrifugation in hybrid apheresis systems that separate plasma via hollow-fiber technology while retaining cellular components through density gradient processing. Academic medical centers in the United States and Germany are piloting these platforms for simultaneous therapeutic plasma exchange and stem cell collection. The structural consequence is converging with equipment purchasing decisions, as hospital blood banks consolidate vendor relationships around single-platform flexibility rather than maintaining discrete devices for discrete procedures.
EU MDR post-market surveillance requirements are mandating real-world performance data collection for membrane filtration devices, extending clinical validation obligations beyond pre-market conformity assessments. Manufacturers must now maintain post-launch safety registries that track thrombotic events, membrane fouling rates, and anticoagulant complications across installed base populations. High-throughput hospital blood banks in France and Germany face the most significant documentation burden, with some facilities delaying procurement of next-generation systems until surveillance infrastructure matures.
Hospital procurement departments are unbundling apheresis service contracts from capital equipment leases, separating disposable kit supply from device maintenance and clinical training obligations. This purchasing pattern shift concentrates negotiating leverage with group purchasing organizations representing multi-hospital systems in the United States and hospital federations in Germany. The unbundling is most advanced in outpatient plasmapheresis settings where procedure volume predictability enables standalone supply agreements independent of equipment vendor relationships.
Therapeutic Apheresis Market Segmentation
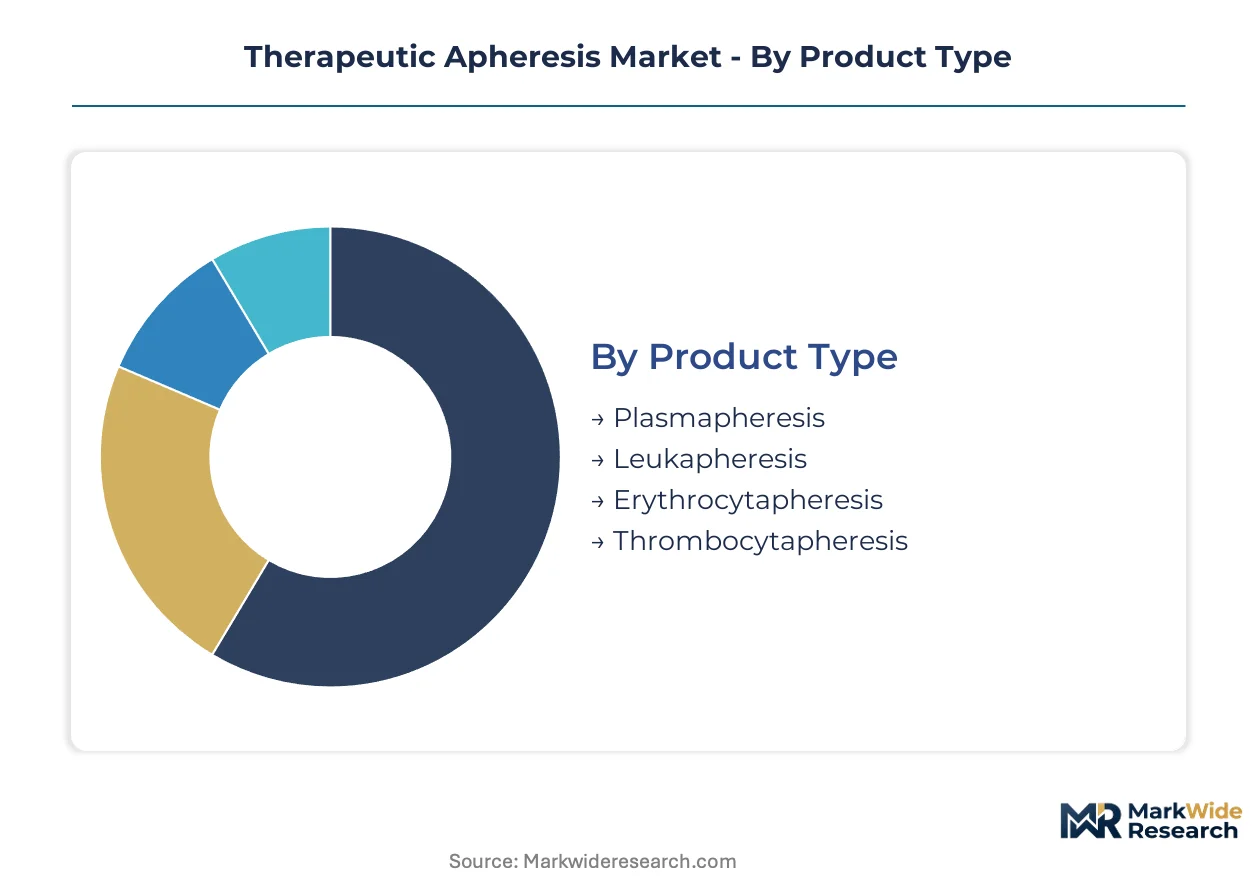
Therapeutic apheresis equipment and consumables segment across four critical axes that determine procurement patterns and clinical utility. Product type dictates reimbursement pathways and kit economics, while technology choice shapes hospital infrastructure requirements and operator training protocols.
Product Type:
Membrane pore specifications and separation physics define the clinical applicability of each product category.
- Plasmapheresis:Separates plasma from whole blood using centrifugation or membrane filtration at flow rates between 50-150 mL per minute, returning cellular components while removing pathogenic antibodies and immune complexes. Demand concentrates in United States outpatient centers where CMS reimbursement codes for Guillain-Barré syndrome and myasthenia gravis treatment sustain procedure volume.
- Leukapheresis:Selectively removes white blood cells or harvests peripheral blood stem cells for CAR-T manufacturing protocols. Academic medical centers in Germany and the United States are expanding dedicated cell processing infrastructure that doubles as therapeutic capacity.
- Erythrocytapheresis:Targets red blood cell exchange for sickle cell disease and severe malaria cases.
- Thrombocytapheresis:Reduces platelet counts in essential thrombocythemia and collects donor platelets for transfusion.
Plasmapheresis leads on scale; Leukapheresis leads on momentum.
Application:
Clinical indication breadth determines addressable patient populations and regulatory validation requirements.
- Autoimmune Disorders:Maturest application segment encompassing myasthenia gravis, Goodpasture syndrome, and antineutrophil cytoplasmic antibody-associated vasculitis. Hospital blood banks in Japan and Germany maintain dedicated autoimmune treatment protocols with established nursing certification pathways.
- Neurological Disorders:Plasma exchange for Guillain-Barré syndrome, chronic inflammatory demyelinating polyneuropathy, and acute disseminated encephalomyelitis. METI incentives in Japan support dedicated apheresis suites in prefectural hospitals for CIDP cases.
- Renal Disorders:Addresses anti-glomerular basement membrane disease and recurrent focal segmental glomerulosclerosis post-transplant.
- Oncological Disorders:CAR-T leukapheresis collection and tumor debulking applications.
Autoimmune Disorders anchor current revenue; Neurological Disorders are climbing the fastest.
Technology:
Platform architecture determines footprint requirements, disposable economics, and treatable indication flexibility.
- Membrane Filtration:Hollow-fiber systems separate plasma through pore size exclusion without density gradient processing. New hospital installations in France and Germany favor membrane platforms where space constraints and reduced disposable costs matter.
- Centrifugation:Legacy density gradient systems dominate installed base in United States blood banks.
- Continuous Flow Processing:High-throughput systems occupy the premium segment of hospital blood banks requiring rapid procedure completion.
- Electrophoresis:Niche application for protein fractionation in specialized research settings.
Centrifugation retains installed base dominance; Membrane Filtration gains share fastest.
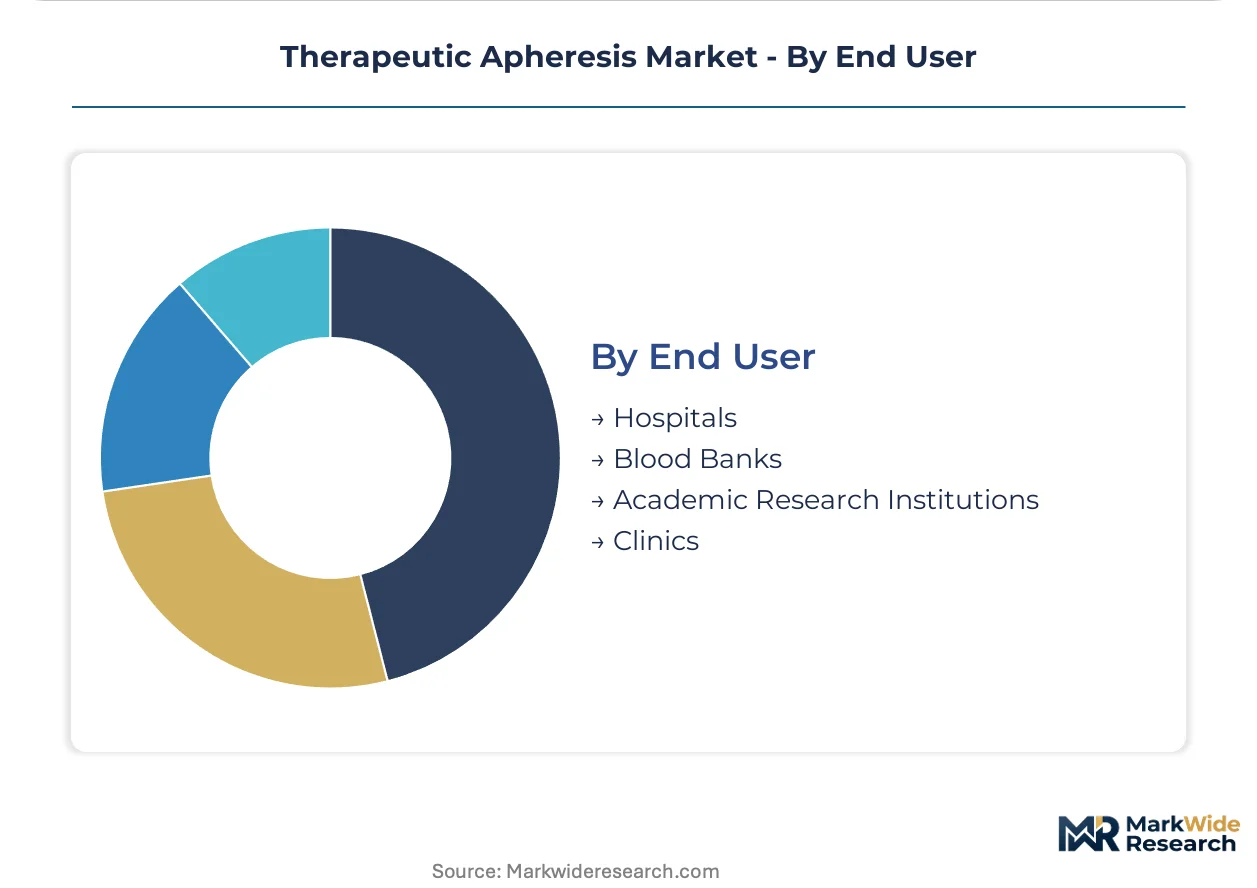
End User:
Procurement sophistication and procedure volume predictability vary sharply across facility types.
- Hospitals:Integrated health systems in the United States and Germany consolidate apheresis service contracts through group purchasing organizations, unbundling disposable supply from equipment leases.
- Blood Banks:Mixed-vendor environments require new continuous flow systems to interface with existing patient data management infrastructure.
- Academic Research Institutions:CAR-T collection protocols create dual-use infrastructure for therapeutic and research applications.
- Clinics:Outpatient plasmapheresis settings in Japan and Germany enable standalone supply agreements independent of equipment vendor relationships.
Hospitals concentrate procedure volume; Academic Research Institutions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting therapeutic apheresis equipment manufacturing toward jurisdictions with streamlined quality management certification. The FDA's 510(k) pathway and EU MDR conformity assessments create divergent cost-of-compliance profiles that shape regional competitive positioning.
United States
CMS reimbursement codes for outpatient plasmapheresis in Guillain-Barré syndrome and myasthenia gravis sustain procedure volume at specialized treatment centers. FDA 510(k) predicate device frameworks accelerate clearance timelines for membrane filtration modules, benefiting domestic manufacturers. Academic medical centers in Boston and Houston maintain dedicated CAR-T leukapheresis infrastructure that doubles as therapeutic capacity.
Germany
Hospital federations consolidate apheresis service contracts through group purchasing organizations, unbundling disposable supply from equipment leases. EU MDR notified body capacity constraints extend certification timelines for continuous flow systems by 12-18 months versus pre-2021 baselines. University hospitals in Munich and Heidelberg pilot hybrid membrane-centrifugation platforms for simultaneous plasma exchange and stem cell collection.
Japan
METI incentives for chronic disease management infrastructure support dedicated apheresis suites in prefectural hospitals for CIDP and TTP cases. PMDA regulatory pathways align with ISO 13485 quality management standards for disposable kit manufacturing. Treatment centers in Tokyo and Osaka handle complex autoimmune and neurological cases with established nursing certification pathways.
India
Dialysis center networks in Mumbai and Delhi present retrofit opportunities for plasmapheresis capability with minimal incremental capital expenditure. CDSCO medical device regulations govern import and domestic manufacturing of membrane filtration systems. Private hospital chains in Bangalore and Hyderabad are expanding extracorporeal blood purification protocols for autoimmune disorder treatment.
United Kingdom
NHS procurement frameworks favor single-platform flexibility across autoimmune, oncological, and hematological applications to compress capital expenditure. MHRA post-Brexit regulatory pathways maintain alignment with EU MDR surveillance requirements for membrane devices. Teaching hospitals in London and Manchester operate mixed-vendor blood bank environments requiring interoperability with existing patient data infrastructure.
Therapeutic Apheresis Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated device suppliers commanding premium positioning in high-throughput hospital installations while regional fabricators capture retrofit opportunities in emerging markets. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with hospital supply chain integration, pure-play apheresis equipment specialists with continuous flow processing expertise, and disposable kit manufacturers with polymer extrusion capabilities. Competitive moves concentrate on unbundling service contracts from capital leases and securing group purchasing organization relationships with multi-hospital systems.
Within the diversified conglomerate tier, Baxter International and Fresenius Medical Care occupy positions anchored by integrated hospital supply chains and dialysis-adjacent service footprints respectively. Terumo BCT exemplifies the pure-play specialist archetype with positioning in high-throughput continuous flow systems. These three entities represent distinct competitive vectors: supply chain breadth, adjacent service infrastructure, and processing technology specialization.
| Leading Market Players |
|---|
| Asahi Kasei Medical |
| Baxter International |
| Fresenius Medical Care |
| Cerus Corporation |
| Kaneka Corporation |
| Terumo BCT |
| B. Braun Melsungen AG |
| MEDICA S.P.A. |
| Haemonetics Corporation |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration's displacement of centrifugation in new hospital installations simultaneously compresses per-procedure disposable economics and concentrates polymer extrusion supply among Japanese and German specialty chemical producers. This technology transition rewards vendors with backward integration into hollow-fiber membrane casting while penalizing standalone equipment suppliers locked into proprietary kit architectures.
Pricing Analysis
Group purchasing organization rebates dominate channel economics, with three-tier pricing structure across premium continuous-flow systems, standard membrane platforms, and economy centrifugation modules differentiating by FDA 510(k) clearance tier and after-sales training bundling. Price differentiation hinges on ISO 13485 certification status and procedure volume commitments, with outpatient clinics in Japan exhibiting highest sensitivity due to METI reimbursement caps while academic medical centers in the United States show lowest sensitivity given CAR-T protocol margins. Pricing pressure stems from EU MDR conformity assessment delays extending vendor cost recovery timelines.
Supply Chain Analysis
Refurbishment flows for legacy centrifugation devices create secondary parts markets that compete with original disposable kit sales, particularly in Indian dialysis center retrofits. Polymer extrusion concentrates in Japan, Germany, and the United States, with hollow-fiber membrane casting drawing from medical-grade polysulfone and polyethersulfone resin grades. Single-source vulnerability pervades proprietary connector molding for Baxter and Fresenius kit architectures. Distribution runs through hospital federations in Germany and integrated delivery networks in the United States, bypassing traditional device distributors for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
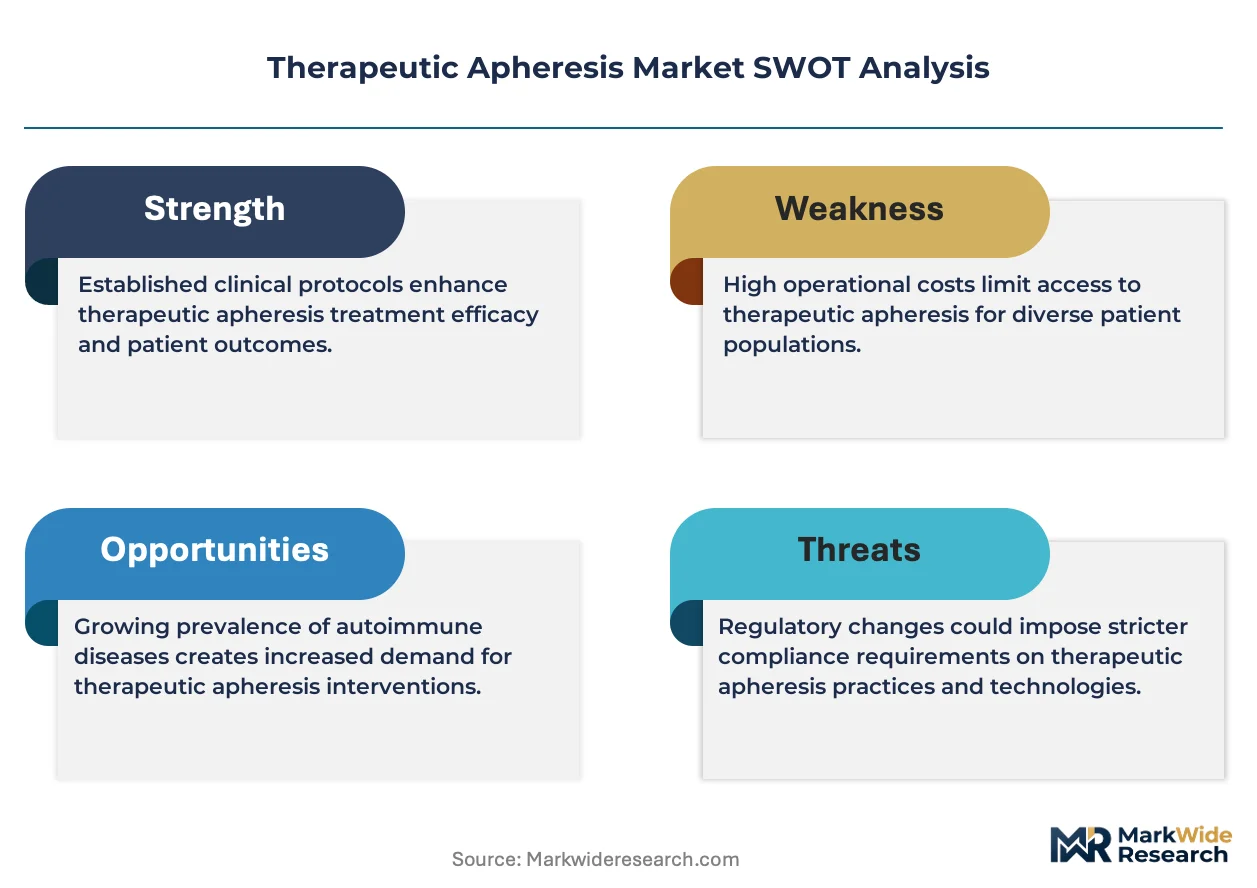
Therapeutic apheresis functions as a regulatory compounder where FDA 510(k) pathway streamlining for membrane pore specifications accelerates demand formation faster than manufacturing capacity can respond.
For Market Incumbents: Anticipate hybrid platform consolidation by securing exclusive hollow-fiber membrane supply agreements before notified body bottlenecks ease, while embedding continuous-membrane systems into long-term GPO contracts that lock out retrofit competitors. Defensive priority rests on backward integration into polymer extrusion to offset proprietary kit margin compression from unbundled procurement patterns. For New Entrants and Emerging Players: Capture India's outpatient plasmapheresis retrofit opportunity by designing membrane filtration modules compatible with existing dialysis infrastructure, bypassing capital equipment sales cycles entirely. White-space concentration sits with prefectural hospital suites in Japan's secondary cities where METI incentives exceed vendor penetration. Go-to-market leverage comes through disposable-only supply agreements decoupled from device placement. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play continuous flow specialists lacking GPO relationships but holding ISO 13485-certified manufacturing. Long-term viability favors vendors with dual-use CAR-T leukapheresis capacity bridging therapeutic and cell therapy demand cycles. Monitor EU notified body capacity expansion as the inflection signal for next-generation system certification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device frameworks for membrane modules accelerate US commercialization timelines versus de novo pathways. |
| CE Marking Pathway | EU MDR post-market surveillance registries extend clinical validation obligations beyond pre-market conformity assessments. |
| Hospital System Partnership | GPO contract consolidation in Germany and the United States unbundles disposable supply from equipment lease structures. |
| Software Companion Development | Patient data management interfaces enable interoperability with mixed-vendor blood bank environments. |
| Reimbursement Strategy | CMS code maintenance for Guillain-Barré syndrome and myasthenia gravis sustains outpatient procedure volume. |
Study Parameters
Direct dialogue with hospital blood bank directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at membrane filtration manufacturers combined secondary validation through FDA 510(k) filings, EU MDR notified body documentation, CMS reimbursement databases, and hospital procurement records. Bottom-up and top-down triangulation cross-checked installed base estimates against procedure volume claims.
Bottom-up modeling segmented demand across plasmapheresis, leukapheresis, erythrocytapheresis, and thrombocytapheresis product types; membrane filtration, centrifugation, and continuous flow processing technologies; and autoimmune, neurological, renal, and oncological applications across the projection horizon. CAGRs derived from procedure volume elasticity to reimbursement code expansion and technology substitution curves for membrane versus centrifugation platform adoption.
Regulatory pathway delays, EU notified body capacity constraints, and CAR-T manufacturing demand volatility are the dominant revision risks to forecast assumptions. Practitioners should monitor FDA predicate device clearance velocity and METI chronic disease infrastructure incentive renewal for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Therapeutic Robots Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Sustained Acoustic Medicine Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market