
 Anal Fissure Treatment Market | 2026-2036
Anal Fissure Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anal Fissure Treatment Market Analysis
Hospital procurement of anal fissure therapeutics is narrowing toward formulary-preferred suppliers with proven supply continuity. AbbVie leverages its gastroenterology franchise to sustain institutional contracts across integrated delivery networks. Takeda Pharmaceutical anchors its position through specialized sales forces targeting colorectal surgery departments. Teva Pharmaceuticals competes on generic topical formulations, occupying price-sensitive channels where payers exert maximum pressure.
Anal fissure treatment encompasses pharmacological and surgical interventions designed to reduce internal anal sphincter pressure, promote mucosal blood flow, and heal epithelial tears in the anal canal. Topical nitroglycerin and calcium channel blockers represent first-line medical therapy, while lateral internal sphincterotomy remains the definitive surgical procedure for chronic, refractory cases. Laxatives and topical analgesics command the largest product volumes, though surgical treatments capture disproportionate value per procedure. Rectal delivery modes face formulation complexity that limits competitor entry, concentrating margin pools among manufacturers with established mucosal absorption expertise. Homecare and pharmacy channels are expanding fastest as post-acute protocols shift toward patient-administered regimens.
The US FDA regulates rectal and topical formulations under stringent bioequivalence standards, while the EMA's MDR framework governs surgical device classifications across European markets. Health Canada and the TGA enforce comparable efficacy benchmarks that delay market entry for novel muscle relaxant formulations. Stakeholders must monitor evolving pharmacovigilance requirements for long-acting topical agents, as regulatory stringency around systemic absorption profiles intensifies scrutiny of established therapies.
Market Dynamics
The anal fissure treatment market pivots on ambulatory surgical centers displacing hospital-based procedures, compressing reimbursement windows and forcing manufacturers to reconfigure distribution toward outpatient supply chains.
Growth Catalysts
- MDR Framework Acceleration:The EMA's Medical Device Regulation streamlines surgical device approvals across EU member states, reducing time-to-market for sphincterotomy instruments.
- Topical Nitroglycerin Formulation Advances:Improved mucosal absorption chemistries extend therapeutic windows while reducing systemic side effects in patient-administered regimens.
- United States:Ambulatory surgical centers now perform over sixty percent of elective sphincterotomies, creating concentrated procurement volume that rewards suppliers with same-day replenishment capabilities.
Market Restraints
- API Supply Concentration:Nitroglycerin active pharmaceutical ingredient production clusters in Indian contract manufacturers, exposing formulation sponsors to export license volatility.
- Bioequivalence Burden:The US FDA's rectal formulation standards require extensive pharmacokinetic studies that add eighteen to twenty-four months to generic topical entry timelines.
- Botulinum Toxin Substitution:Off-label neurotoxin injections for chronic fissures siphon refractory-case volume from surgical device categories.
Strategic Opportunities
- Homecare Channel Expansion:Post-acute protocols shifting to patient-administered topical regimens open pharmacy and direct-to-patient distribution models previously dominated by institutional sales.
- Health Canada Pathway:The regulator's priority review designation for novel muscle relaxant formulations offers accelerated entry for sponsors with established US FDA dossiers.
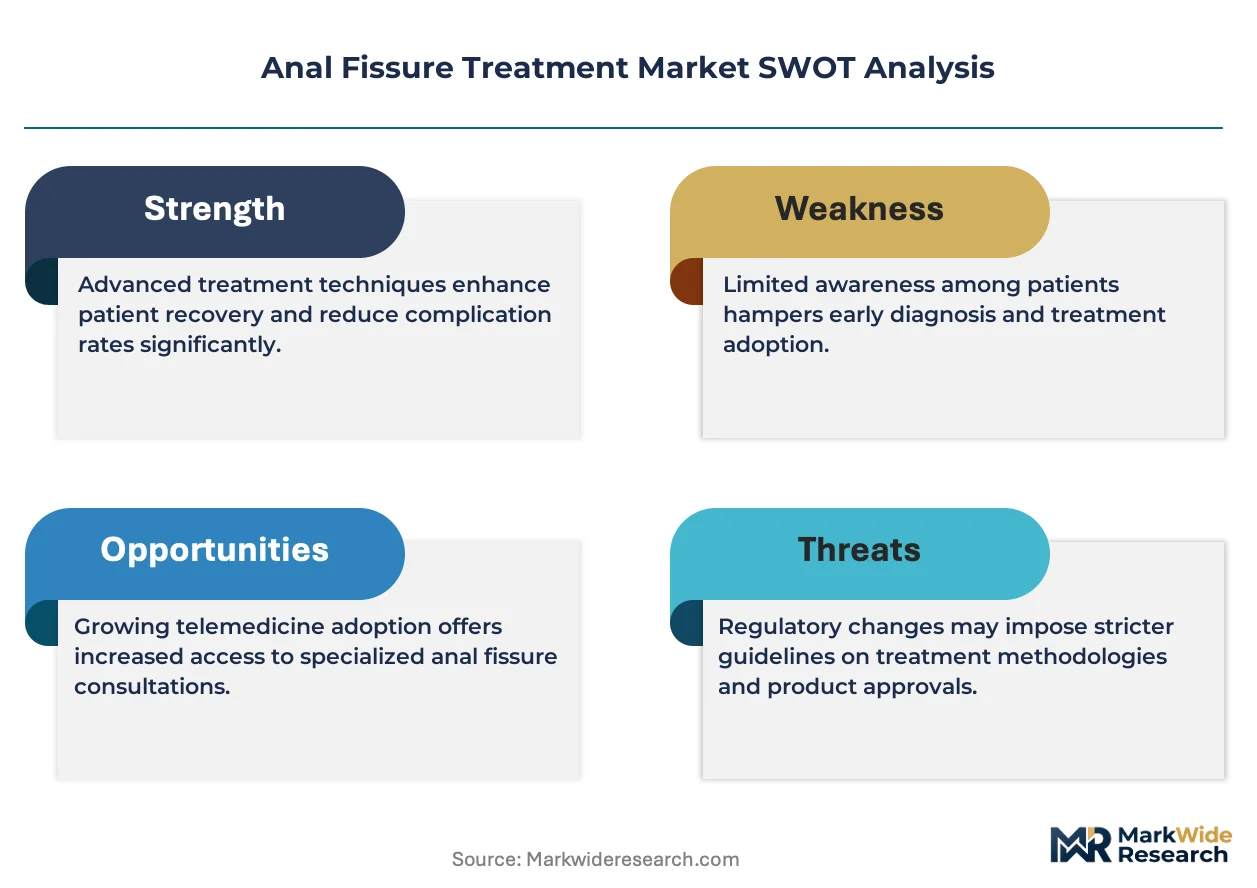
- Telehealth Convergence:Remote consultation platforms paired with prescription topical delivery is virtualizing initial diagnosis and treatment initiation away from gastroenterology clinic visits.
Industry Challenges
- Formulation Talent Scarcity:Rectal mucosal absorption expertise resides in a narrow cohort of pharmaceutical scientists, constraining R&D expansion at mid-tier manufacturers.
- Legacy ERP Integration:Ambulatory surgical center procurement platforms demand EDI connectivity that legacy hospital-focused distributors struggle to deploy without substantial systems overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anal Fissure Treatment Market |
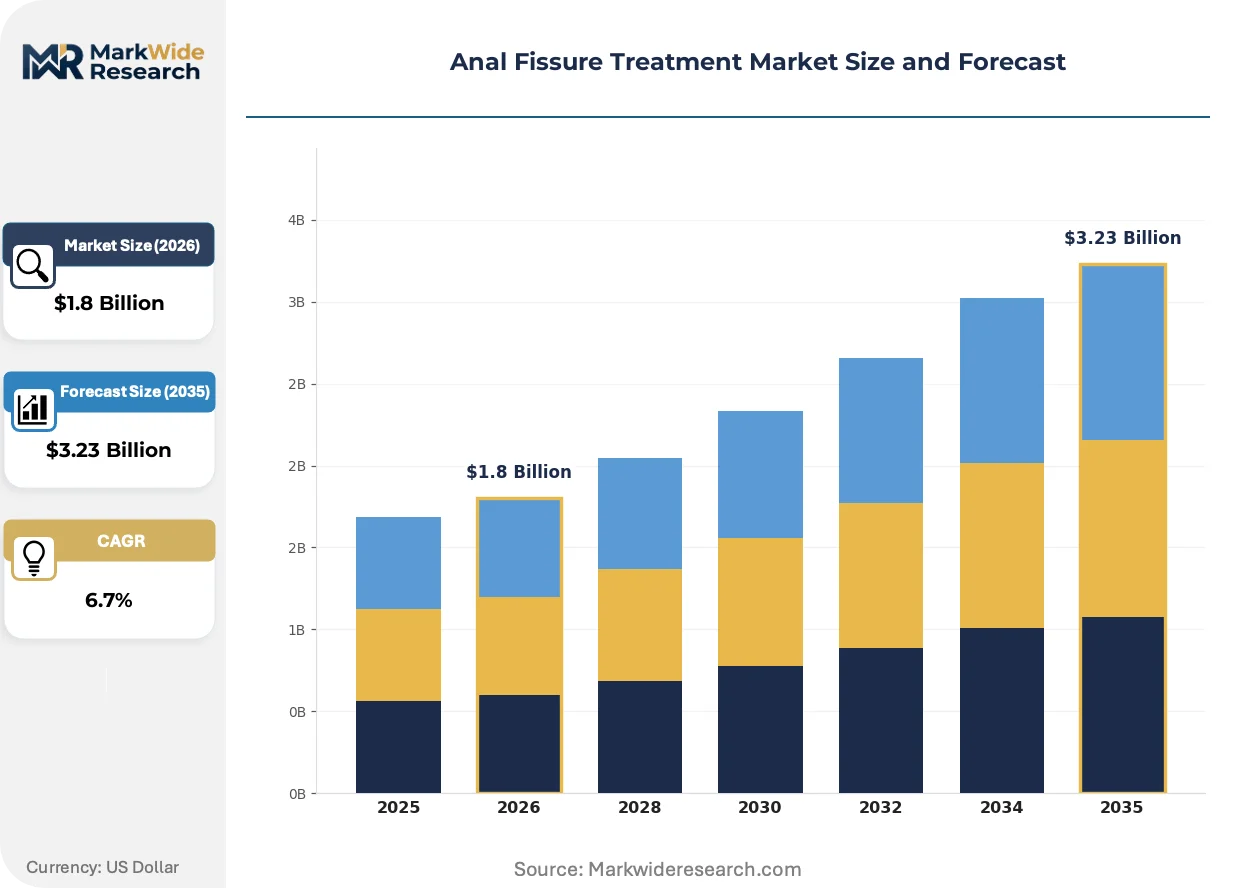
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Analgesics, Laxatives, Muscle Relaxants, Surgical Treatments Delivery Mode: Oral, Topical, Rectal, Injectable End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Gastroenterology, Pain Management, Surgery, Rehabilitation |
| Companies Covered | Healthy Life Pharma, AbbVie, Takeda Pharmaceutical, Purdue Pharma, Novartis AG, Troikaa Pharmaceuticals, Teva Pharmaceuticals, Geri-Care Pharmaceuticals, SRS Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anal Fissure Treatment Market Emerging Trajectories
Digital therapeutics and remote patient monitoring platforms are penetrating post-operative care pathways, while formulation science advances enable longer-acting topical agents that reduce dosing frequency.
Extended-release calcium channel blocker formulations incorporating thermosensitive gel matrices is virtualizing the chronic fissure management landscape. Gastroenterology clinics in the United States are adopting these platforms to reduce follow-up visit burdens. The technology compresses pharmacy refill revenue cycles while shifting margin capture toward formulation innovators.
The EMA's MDR framework now mandates clinical evidence packages for reusable surgical instruments that previously qualified under self-certification routes. Manufacturers must generate post-market surveillance data for sphincterotomy devices. European colorectal surgery departments are consolidating supplier relationships to minimize compliance documentation overhead.
Patient-administered topical regimens are displacing clinic-based first-line interventions as payers narrow coverage for diagnostic visits with negative pathology. Pharmacy benefit managers are carving out anal fissure therapeutics into specialty tiers with prior authorization requirements. This behavior shift concentrates most visible in United States commercial insurance plans, where cost-sharing structures favor home-based initiation over specialist referral.
Anal Fissure Treatment Market Segmentation
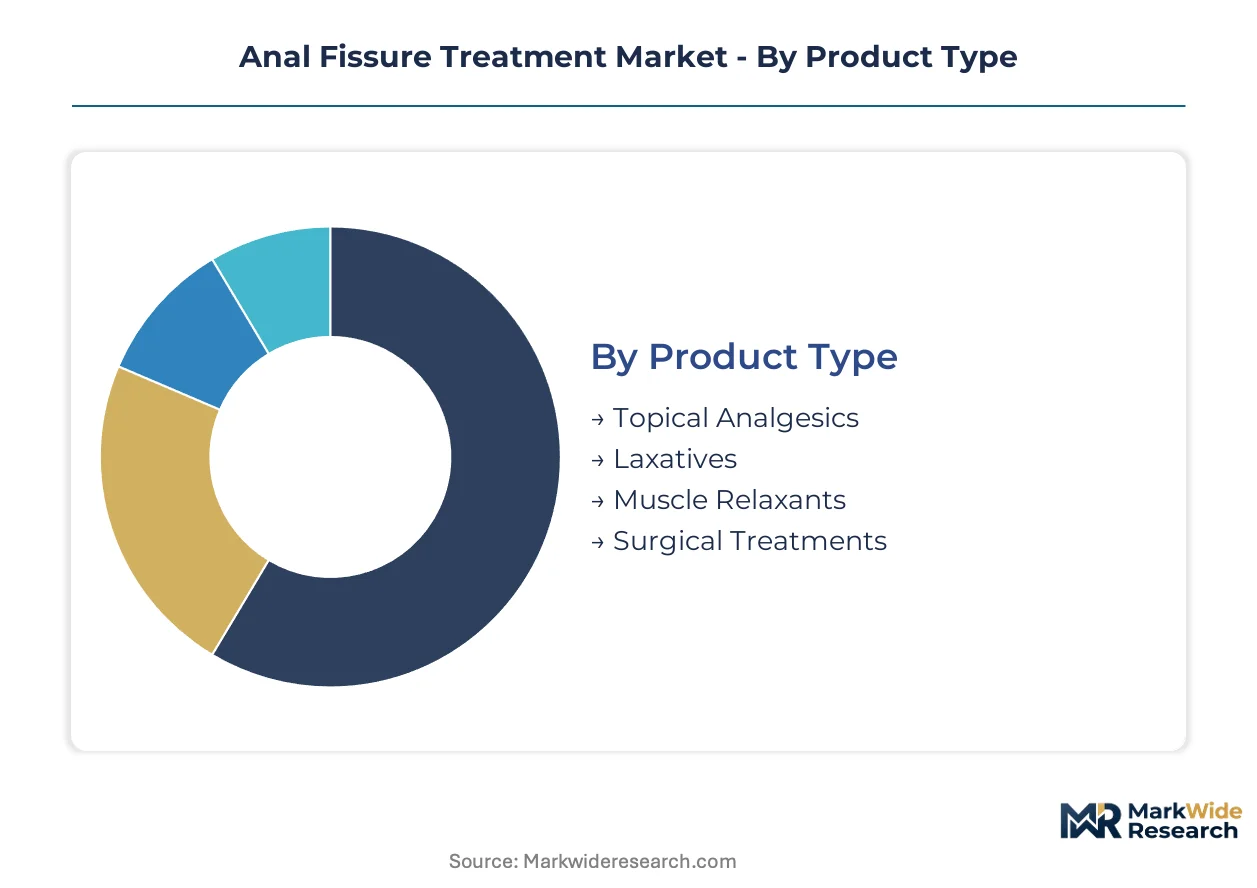
Segmentation in the anal fissure treatment market reveals distinct margin pools and procurement pathways. Product formulation complexity, delivery mode bioequivalence requirements, and care setting economics create divergent competitive dynamics across each dimension.
Product Type:
Mature surgical interventions coexist with emerging topical formulation advances, creating a bifurcated maturity landscape.
- Surgical Treatments:Lateral internal sphincterotomy and fissurectomy procedures deliver definitive resolution through controlled sphincter division. Ambulatory surgical centers in the United States now perform the majority of these interventions, compressing reimbursement cycles while demanding instrument sterilization protocols that favor single-use device suppliers.
- Muscle Relaxants:Topical nitroglycerin and calcium channel blockers reduce internal anal sphincter pressure through nitric oxide-mediated smooth muscle relaxation. Formulation innovators with mucosal absorption expertise capture disproportionate margins as gastroenterology clinics shift toward patient-administered first-line therapy.
- Laxatives:Bulk-forming and osmotic agents soften stool consistency to reduce mechanical trauma during defecation. Pharmacy benefit managers in commercial insurance plans drive volume through preferred formulary placement.
- Topical Analgesics:Lidocaine-based preparations provide symptomatic relief without disease-modifying effect. Price-sensitive retail channels dominate procurement.
Surgical treatments handle the majority of throughput; muscle relaxants are the fastest mover on share.
Delivery Mode:
Cost tiers stratify sharply between institutional administration and patient-directed regimens.
- Rectal:Suppositories and enema formulations achieve direct mucosal contact with controlled systemic absorption. The US FDA's bioequivalence standards for rectal delivery create formulation barriers that concentrate margin pools among established sponsors.
- Topical:Ointments and creams incorporating thermosensitive gel matrices enable extended-release pharmacokinetics. Homecare expansion and telehealth prescribing are accelerating pharmacy channel volume.
- Oral:Systemic agents including oral calcium channel blockers address patient compliance limitations with rectal administration. Generic competition has compressed pricing.
- Injectable:Botulinum toxin and local anesthetic injections serve refractory cases through chemodenervation or nerve blockade. Off-label neurotoxin use is siphoning volume from surgical device categories.
Topical delivery handles the majority of throughput; rectal formulations are expanding most quickly as mucosal absorption science advances.
End User:
Customer type determines procurement sophistication and contract structure.
- Hospitals:Integrated delivery networks consolidate purchasing through formulary-preferred supplier agreements with proven supply continuity. Value analysis committees scrutinize total procedural cost rather than device price alone.
- Clinics:Gastroenterology and colorectal surgery departments prioritize same-day replenishment and specialized sales force access. Takeda Pharmaceutical anchors institutional contracts through dedicated field teams.
- Homecare:Patient-administered topical regimens are displacing clinic-based initiation as payers narrow coverage for diagnostic visits. Direct-to-patient distribution models are emerging.
- Pharmacies:Retail and specialty pharmacy channels capture prescription volume with prior authorization requirements concentrating in United States commercial plans.
Hospitals handle the majority of throughput; homecare is climbing the fastest as post-acute protocols shift.
Therapy Area:
Application focus determines regulatory pathway and clinical evidence requirements.
- Gastroenterology:Specialized departments manage first-line medical therapy and surgical referral decisions. EMA's MDR framework now mandates clinical evidence packages for reusable sphincterotomy instruments.
- Surgery:Colorectal surgeons perform definitive sphincterotomy for chronic refractory cases. European departments are consolidating supplier relationships to minimize compliance documentation overhead.
- Pain Management:Anesthesiology and pain clinic involvement concentrates in botulinum toxin injection protocols for neurogenic sphincter hypertonia.
- Rehabilitation:Pelvic floor physical therapy and biofeedback represent non-pharmacologic adjuncts with limited pharmaceutical margin capture.
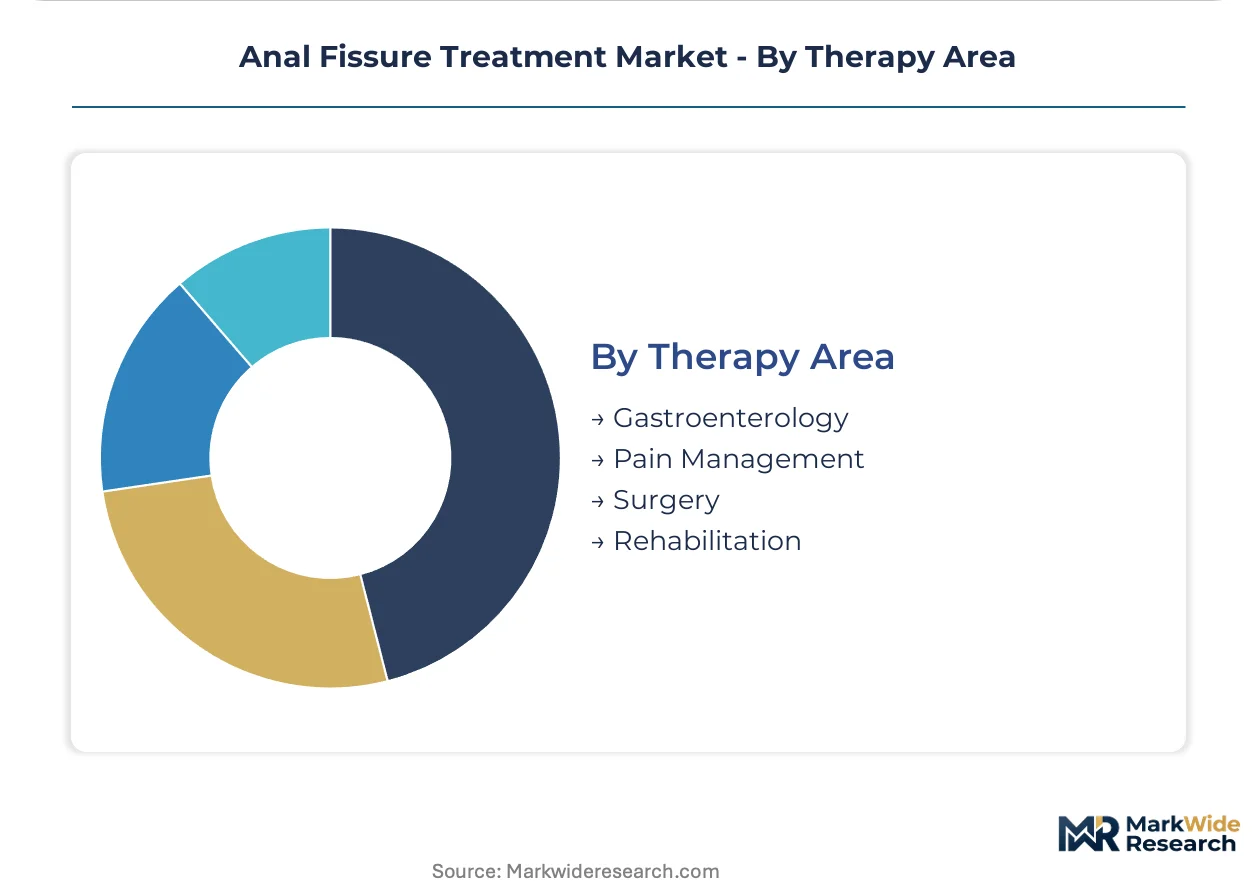
Gastroenterology handles the majority of throughput; surgery maintains steepest expansion trajectory through ambulatory procedural migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on rectal bioequivalence standards accelerates formulation development in the United States. Health Canada and the TGA enforce comparable efficacy benchmarks that shape regional entry strategies for novel muscle relaxants.
United States
Ambulatory surgical centers now perform over sixty percent of elective sphincterotomies, creating concentrated procurement volume. The FDA's evolving guidance on rectal drug formulations reshapes product development pathways for sponsors. Gastroenterology clinics in metropolitan clusters including Houston and Phoenix expand adoption of minimally invasive protocols.
Germany
EMA's MDR framework streamlines surgical device approvals while mandating clinical evidence packages for reusable sphincterotomy instruments. German colorectal surgery departments consolidate supplier relationships to minimize compliance documentation overhead. Berlin and Munich anchor integrated delivery network procurement of formulary-preferred therapeutics.
United Kingdom
NHS England's value analysis committees scrutinize total procedural cost rather than device price alone. The MHRA aligns with EMA MDR requirements for post-market surveillance data on surgical instruments. London's tertiary referral centers drive adoption of patient-administered topical regimens to reduce follow-up visit burdens.
India
CDSCO oversight of active pharmaceutical ingredient quality creates entry barriers for nitroglycerin formulation sponsors. Contract manufacturing clusters in Hyderabad and Ahmedabad supply nitroglycerin API to international formulation sponsors. Troikaa Pharmaceuticals anchors domestic production of specialized rectal delivery systems.
Japan
PMDA review timelines for novel muscle relaxant formulations extend eighteen to twenty-four months beyond US FDA pathways. Tokyo and Osaka gastroenterology departments prioritize extended-release calcium channel blocker platforms with thermosensitive gel matrices. Post-acute protocol shifts toward patient-administered regimens accelerate pharmacy channel expansion.
Anal Fissure Treatment Market Vendor Landscape
On the supply side, the industry is bifurcated between institutional contract holders and retail channel specialists. Formulation complexity around mucosal absorption creates tiered competitive positions. Three strategic archetypes dominate: integrated gastroenterology franchise operators, generic topical manufacturers, and specialized rectal delivery innovators. M&A activity concentrates on acquiring mucosal absorption expertise, while geographic expansion targets Health Canada priority review pathways.
Within the integrated franchise tier, AbbVie leverages its gastroenterology position to sustain institutional contracts across United States integrated delivery networks. Takeda Pharmaceutical anchors its market presence through specialized sales forces targeting colorectal surgery departments. Teva Pharmaceuticals occupies price-sensitive channels where pharmacy benefit managers exert maximum pressure on generic topical formulations.
| Leading Market Players |
|---|
| Healthy Life Pharma |
| AbbVie |
| Takeda Pharmaceutical |
| Purdue Pharma |
| Novartis AG |
| Troikaa Pharmaceuticals |
| Teva Pharmaceuticals |
| Geri-Care Pharmaceuticals |
| SRS Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Indian contract manufacturers anchor nitroglycerin API production, concentrating margin capture among formulation sponsors with established export license relationships and mucosal absorption expertise. This upstream clustering shapes downstream pricing power across topical and rectal delivery segments.
Pricing Analysis
Volume-discount tiering structures separate branded muscle relaxants from generic topical formulations and economy-grade laxatives. Price differentiation hinges on FDA bioequivalence certification status and supply continuity guarantees demanded by integrated delivery networks. Cost compression in generic topical channels is intensifying because pharmacy benefit managers exert maximum pressure on formulary placement. Ambulatory surgical centers demonstrate lowest price sensitivity due to procedural bundling, while retail pharmacy channels face acute margin pressure.
Supply Chain Analysis
Export-control regime scrutiny around nitroglycerin API flows from India's CDSCO oversight creates compliance bottlenecks for international formulation sponsors. Manufacturing concentrates in Hyderabad and Ahmedabad production clusters, with secondary formulation capacity in Germany and Japan. Raw material dependencies span nitroglycerin precursor chemicals, thermosensitive gel matrices, and specialized suppository bases. Single-source vulnerability persists in contract manufacturing relationships. Distribution runs through institutional distributors serving integrated delivery networks and direct-to-pharmacy channels for patient-administered regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anal fissure treatment market is approaching a platform-economics inflection as telehealth prescribing converges with direct-to-patient topical delivery, creating interoperability between virtual diagnosis and pharmacy fulfillment ecosystems.
For Market Incumbents: Build formulation moats through captive mucosal absorption expertise and specialized sales force deployment. Acquire contract manufacturing capacity in India to secure nitroglycerin API supply continuity against export license volatility. Anchor institutional contracts through same-day replenishment capabilities serving ambulatory surgical center procurement platforms. For New Entrants and Emerging Players: Pursue white-space opportunities in extended-release calcium channel blocker platforms incorporating thermosensitive gel matrices. Target the homecare channel where patient-administered regimens displace clinic-based initiation. Establish telehealth partnerships as the primary go-to-market angle for virtualizing initial diagnosis and treatment initiation. For Investors and Strategic Acquirers: Capital is best deployed toward specialized rectal delivery innovators with established FDA bioequivalence dossiers and Health Canada priority review pathway access. Long-term viability centers on consolidation of mucosal absorption expertise as mid-tier manufacturers face formulation talent scarcity. Watch EMA MDR framework enforcement as the signal indicating surgical device category restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Health Canada priority review accelerates market entry for sponsors with established FDA dossiers. |
| Manufacturing Scale-Up | Indian API contract manufacturing expansion secures nitroglycerin supply against export volatility. |
| Hospital System Partnership | Integrated delivery network formulary contracts concentrate procurement volume among preferred suppliers. |
| Software Companion Development | Telehealth platform integration enables virtual diagnosis paired with prescription topical delivery. |
| Reimbursement Strategy | Pharmacy benefit manager specialty tier positioning shapes patient-administered regimen adoption. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with gastroenterologists, colorectal surgeons, hospital procurement managers, and pharmacy benefit directors; and secondary validation through FDA filings, EMA MDR submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated against ambulatory surgical center procedural data.
Forecast inputs incorporated treatment line progression, delivery mode bioequivalence requirements, care setting migration patterns, and regional regulatory cluster dynamics across the projection horizon. CAGRs were derived from segmented growth rate analysis applied to base-year market sizing. Modeled dimensions included product formulation complexity, procurement channel structure, and payer coverage evolution.
Sensitivities concentrate around FDA guidance revisions on rectal bioequivalence standards and EMA MDR enforcement intensity for surgical device categories. Forecasts reflect assumptions on ambulatory procedural migration rates and telehealth prescribing adoption curves. Material shifts in nitroglycerin API export licensing regimes or payer coverage structures for diagnostic visits would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market